
 Italy Wound Care Market | 2026-2036
Italy Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Wound Care Market Insights
Capital-intensity divergence between advanced dressing manufacturers and commodity bandage producers is reorganizing competitive tiers in Italy. Smith+Nephew leverages its hydrofiber technology portfolio to dominate high-acuity hospital segments. Mölnlycke Health Care anchors its position through direct distribution to regional health authorities across northern Italy. Coloplast specializes in silicone-based gentle adhesion products for fragile skin applications in long-term care.
Wound care encompasses medical products designed to protect injured tissue, manage exudate, prevent infection, and promote healing through controlled moisture balance and antimicrobial action. Hydrocolloid and foam dressings absorb wound fluid while maintaining a humid microenvironment conducive to granulation tissue formation. The dressings segment leads value generation due to premium pricing of silver-infused and antimicrobial variants, while home care represents the fastest-growing end-user channel as regional health systems push outpatient chronic wound management. Alginate technology occupies a specialized niche in heavily exuding wounds, where its gelling action upon contact with serum creates distinct clinical utility.
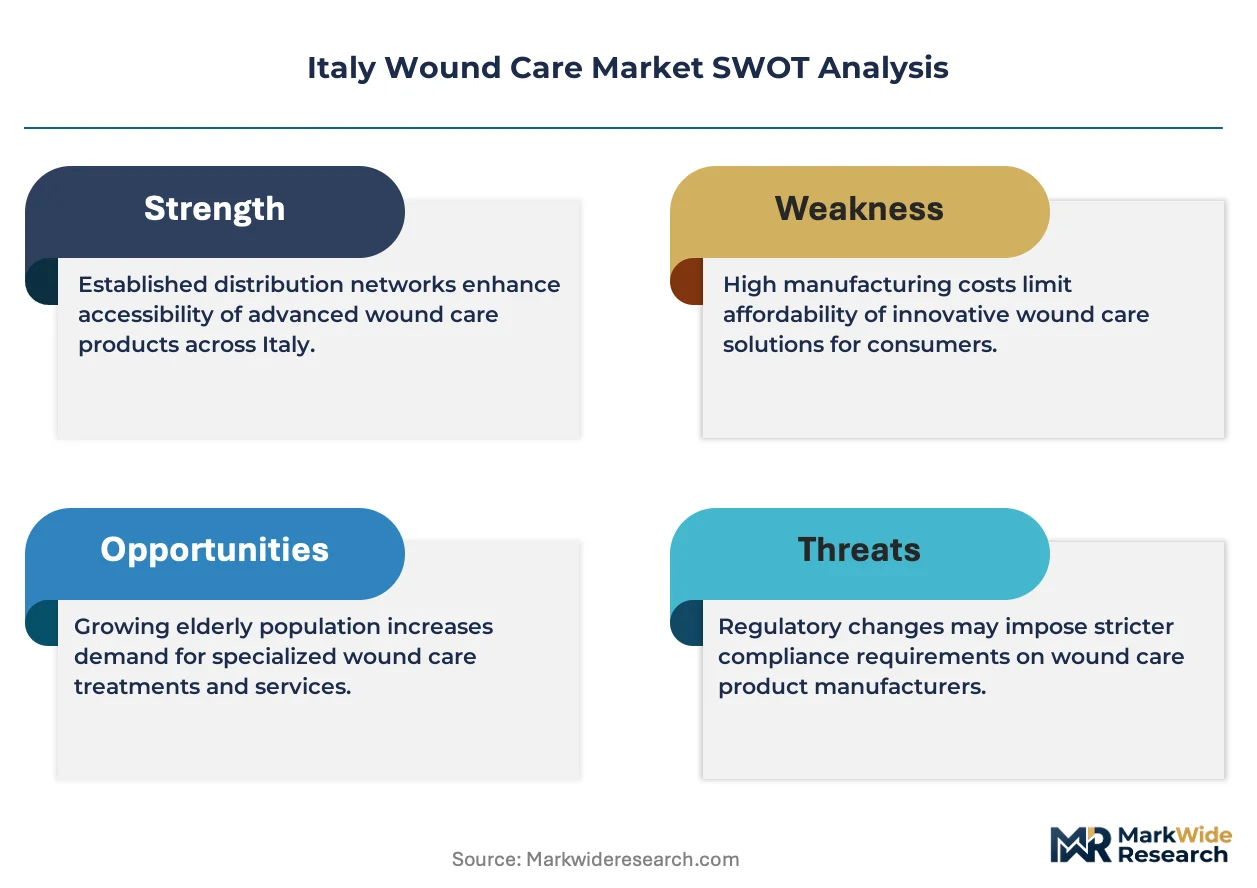
Italy's Ministry of Health sets reimbursement classifications that determine market access for novel wound care technologies, while BIS-aligned standards govern product safety and performance claims for domestic manufacturers. The EU Medical Device Regulation (MDR) imposes strengthened clinical evidence requirements, reshaping registration timelines and compliance costs for suppliers serving Italian providers. Stakeholders must monitor how regional health authority procurement consolidation affects pricing power and channel access for differentiated technologies.
Market Dynamics
Italy's Ministry of Health reimbursement frameworks for advanced dressings are compressing hospital procurement timelines and forcing rapid technology transitions from traditional gauze to antimicrobial and hydrofiber solutions. Regional health authority consolidation in Lombardy and Veneto is concentrating purchasing power among fewer decision-makers.
Growth Catalysts
- Aging Demographics:Italy's 65-plus population share drives chronic wound prevalence in diabetic foot and pressure ulcer categories. Home care protocols now absorb cases previously managed in acute settings.
- EU MDR Compliance:Strengthened clinical evidence requirements for Class IIa and IIb wound care devices are filtering out low-margin commodity suppliers. Surviving manufacturers capture expanded shelf space in hospital formularies.
- Hydrofiber Technology:Gel-forming dressings that manage exudate while maintaining moist wound environments are displacing alginate and foam alternatives in high-acuity segments across northern Italian hospital networks.
Market Restraints
- Silver Price Volatility:Antimicrobial dressing production depends on silver nitrate and silver sulfadiazine inputs subject to commodity swings. Manufacturers absorb margin compression or pass costs to constrained regional budgets.
- Supply Concentration:Advanced dressing polymer supply chains cluster in Germany and the Netherlands. Italian converters face extended lead times and freight cost exposure from single-source raw material dependencies.
- Substitution Pressure:Negative-pressure wound therapy systems capture complex chronic cases that dressings previously managed. Device manufacturers erode addressable market for advanced dressing portfolios in hospital settings.
Strategic Opportunities
- Sicily and Southern Expansion:Underdeveloped home care infrastructure in Calabria, Sicily, and Apulia creates whitespace for telemedicine-integrated wound management services. Regional health authorities seek outsourced chronic care partnerships.
- Silicone Adhesion Convergence:Gentle-removal silicone technology migrating from ostomy care into fragile-skin wound applications opens pediatric and geriatric segments previously excluded from advanced dressing protocols.
- SSN Procurement Reform:Italy's Servizio Sanitario Nazionale centralization of regional purchasing through Consip frameworks rewards suppliers with multi-region logistics capabilities and transparent cost structures.
Industry Challenges
- Specialized Nursing Shortage:Certified wound care nurses concentrate in Milan, Verona, and Bologna facilities. Southern and rural regions face recruitment gaps that delay protocol adoption and home care rollout.
- MDR Technical Documentation:Clinical evaluation reports and post-market surveillance systems demand 18-24 month preparation cycles. Smaller Italian manufacturers lack regulatory affairs capacity to maintain device registrations.
- Legacy System Integration:Hospital electronic health record platforms in Veneto and Emilia-Romagna use proprietary wound assessment modules. New digital dressing technologies face interoperability barriers and pilot-to-scale friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Wound Care Market |
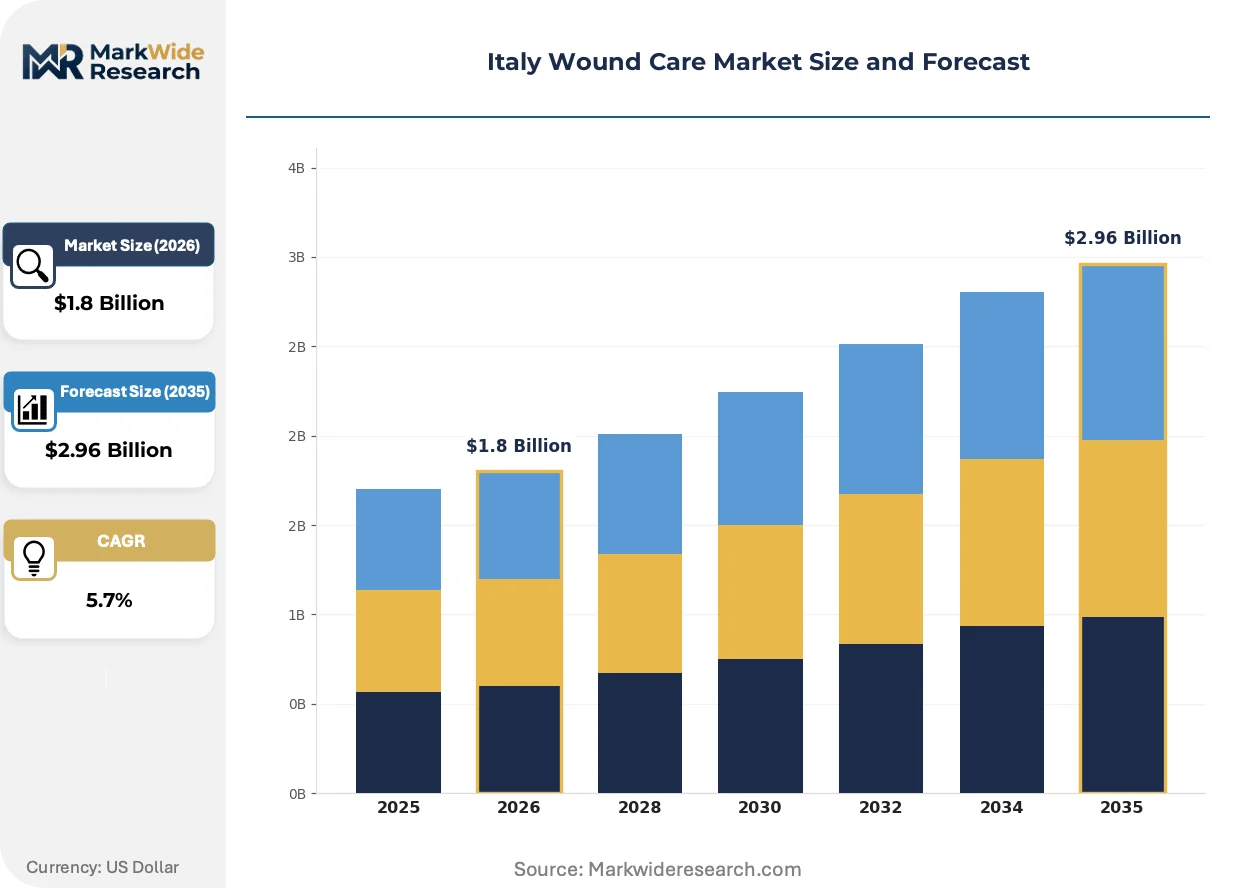
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Bandages, Antiseptics, Gels End User: Hospitals, Home Care, Clinics, Long-term Care Application: Chronic Wounds, Surgical Wounds, Burns, Ulcers Technology: Hydrocolloid, Foam, Alginate, Silver-infused |
| Companies Covered | Smith+Nephew, ConvaTec, Mölnlycke Health Care, Coloplast, 3M, Solventum, Medtronic, B. Braun, Paul Hartmann, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Wound Care Market Trends and Innovations
Smart materials and connected monitoring systems are penetrating Italian wound care protocols, shifting clinical decision-making from scheduled dressing changes to data-triggered interventions. Regulatory pressure and reimbursement incentives align to accelerate validated technology adoption.
Antimicrobial peptide-infused dressings are decomposing the silver-dominant infection control paradigm in Italian burn centers and diabetic foot clinics. Hospital pharmacies in Lombardy pilot these alternatives to address bacterial resistance concerns and heavy metal environmental discharge regulations. The technology is decomposing legacy silver sulfadiazine procurement volumes and compressing pricing power among established antimicrobial suppliers.
EU MDR clinical evidence requirements are extending registration timelines for hydrocolloid and foam dressing variants by 12-18 months. Italian notified bodies face audit backlogs that delay certificate issuance for modified product lines. Small and mid-tier manufacturers without dedicated regulatory affairs functions are withdrawing marginal SKUs rather than absorbing compliance costs, concentrating shelf presence among diversified multinationals.
Regional health authorities in Veneto and Tuscany are unbundling wound care supplies from procedure-based reimbursement. Separate product coding enables transparent price benchmarking and volume discount negotiations. This purchasing behavior shift pressures distributors to consolidate logistics networks and offer real-time inventory visibility rather than traditional rebate structures.
Italy Wound Care Market Segmentation
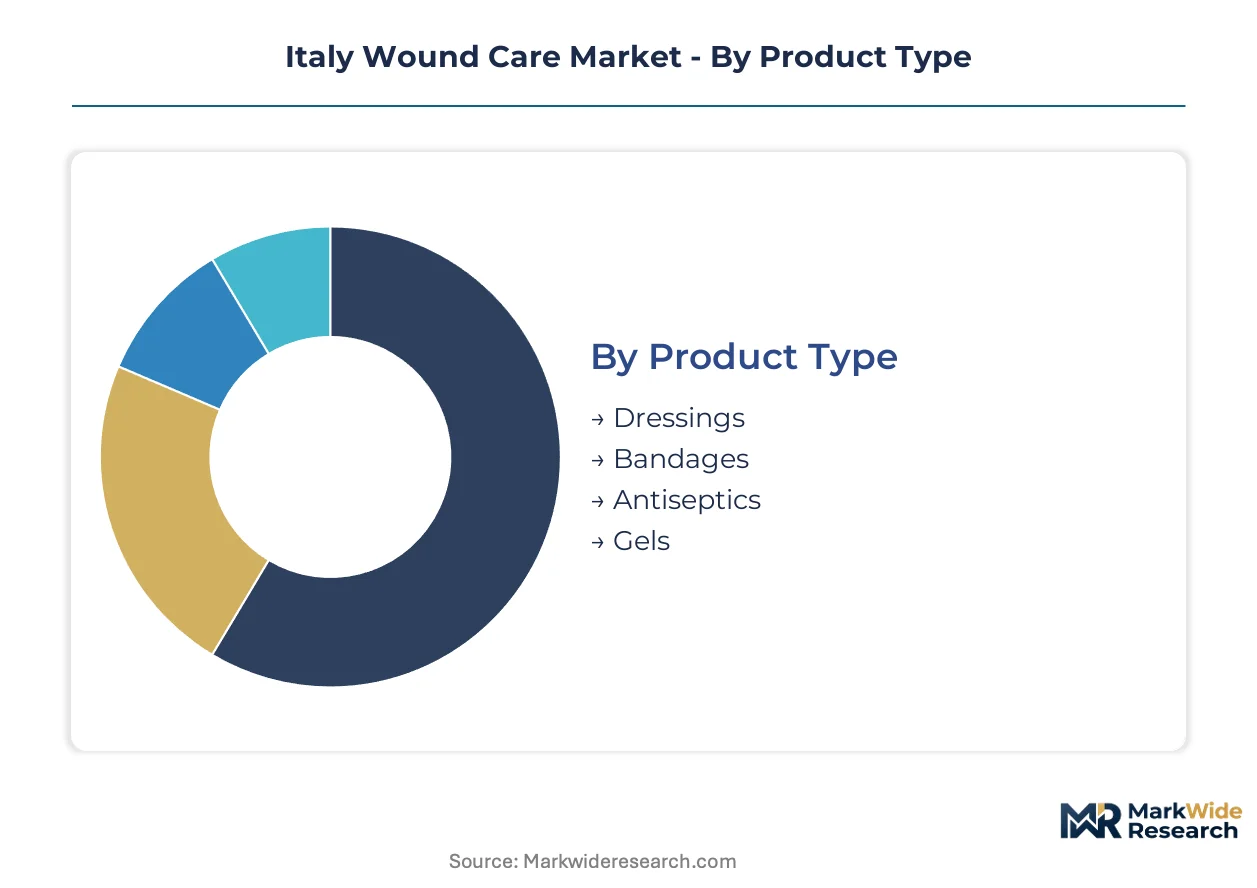
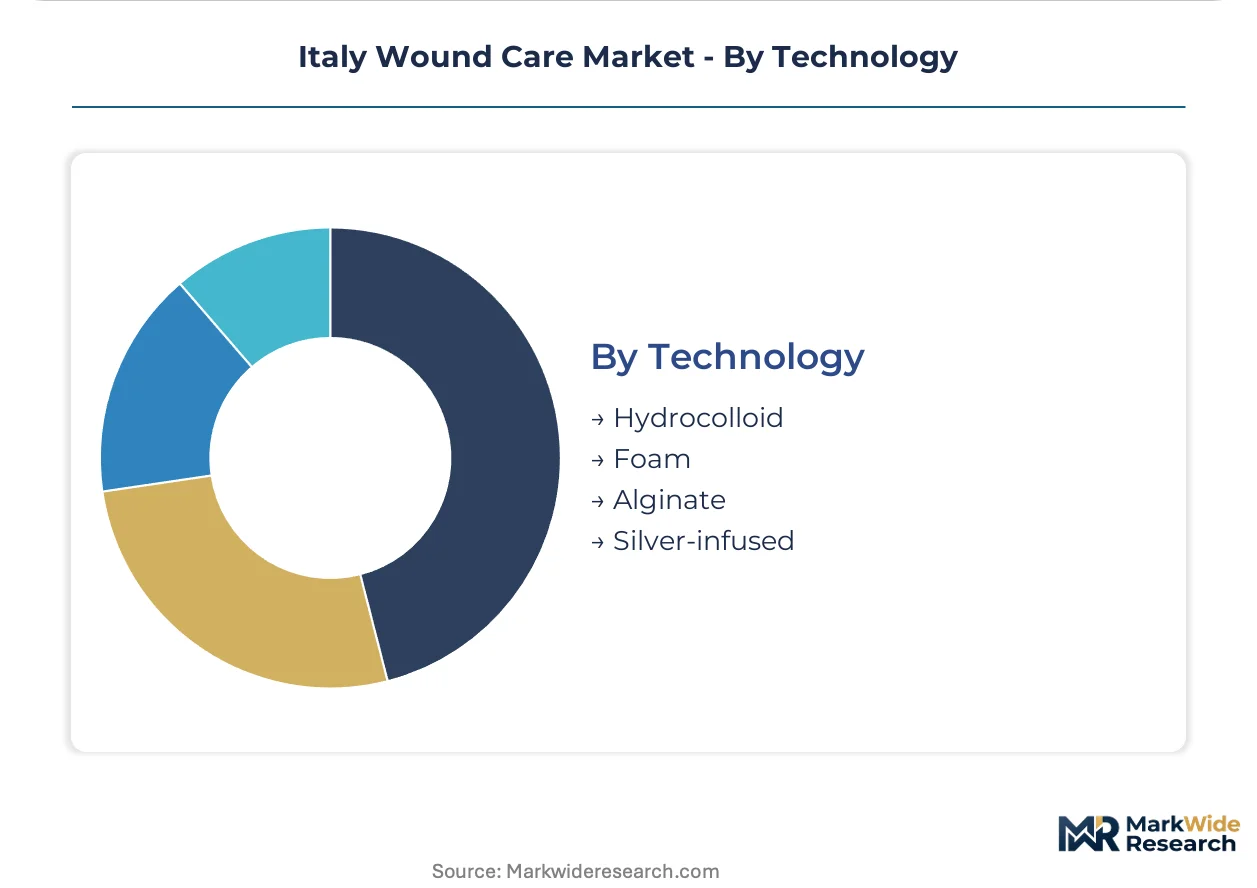
Wound care segmentation in Italy reflects divergent reimbursement pathways and clinical protocols across acute and post-acute settings. Product type and technology choices determine margin structures, while end-user channel selection shapes logistics requirements and regulatory compliance burdens.
Product Type:
Substitution pressure from negative-pressure wound therapy and bioengineered skin substitutes is compressing addressable volume for traditional consumables, forcing portfolio repositioning among dressing suppliers.
- Dressings:Hydrofiber, hydrocolloid, and foam variants dominate hospital formularies through Servizio Sanitario Nazionale reimbursement codes. Silver-infused and antimicrobial versions command premium positioning in Lombardy and Veneto wound clinics managing diabetic foot infections.
- Bandages:Compression and retention bandages serve venous ulcer protocols in Emilia-Romagna long-term care networks. Elastic and cohesive variants face commodity pricing pressure as regional health authorities consolidate procurement through Consip frameworks.
- Antiseptics:Povidone-iodine and chlorhexidine solutions maintain protocol presence in surgical preparation and wound cleansing across Italian acute care facilities.
- Gels:Hydrogel and alginate gel formats support autolytic debridement in home care settings where nurse visit frequency is constrained.
Dressings anchor the volume base while antiseptics gain share at the steepest rate as infection control protocols tighten in surgical wards.
End User:
Cost tier stratification separates capital-intensive hospital technology adoption from price-sensitive home care logistics, with distinct margin profiles across each channel.
- Hospitals:Acute care facilities in Milan, Verona, and Bologna drive demand for advanced moisture-retentive dressings and negative-pressure systems. Procurement concentrates through regional health authority tenders with strict EU MDR documentation requirements.
- Home Care:Outpatient chronic wound management expands fastest as Italy's aging population shifts pressure ulcer and diabetic foot treatment from institutional settings. Telemedicine-integrated protocols in Tuscany and Piedmont reduce dressing change frequency through remote monitoring.
- Clinics:Specialized wound centers in northern Italy concentrate certified nursing expertise and advanced debridement capabilities.
- Long-term Care:Nursing homes across Lombardy adopt silicone-adhesion gentle removal products for fragile geriatric skin applications.
Hospitals retain the highest absolute spending while home care demonstrates the most rapid expansion trajectory among end-user channels.
Application:
Volume concentration in chronic wound categories reflects Italy's demographic burden, while surgical wound protocols face pricing compression from procedure-based reimbursement unbundling.
- Chronic Wounds:Diabetic foot ulcers, pressure injuries, and venous leg ulcers consume the majority of advanced dressing volumes. Treatment protocols in southern regions lag northern standards due to nursing shortages and infrastructure gaps.
- Surgical Wounds:Post-operative incision management drives antimicrobial dressing adoption in orthopedic and cardiac surgery departments. Negative-pressure systems capture complex cases with high exudate or dehiscence risk.
- Burns:Specialized burn centers in Milan and Rome utilize silver sulfadiazine and emerging antimicrobial peptide alternatives for infection control.
- Ulcers:Arterial and neuropathic ulcer categories require differentiated moisture management protocols based on perfusion status and exudate levels.
Chronic wounds generate the dominant procedure volume while burns applications show the most pronounced technology transition intensity.
Technology:
Supply concentration in polymer feedstocks and antimicrobial active ingredients shapes competitive access and cost structures across technology platforms.
- Hydrocolloid:Gel-forming carboxymethylcellulose matrices maintain moist wound environments for partial-thickness injuries and pressure ulcer prevention. EU MDR clinical evidence requirements extend registration timelines for modified formulations.
- Foam:Polyurethane absorbent structures manage moderate-to-heavy exudate in venous leg ulcer protocols. Semi-permeable film backings permit moisture vapor transmission while blocking bacterial ingress.
- Alginate:Calcium-sodium fiber dressings derived from seaweed gelling upon serum contact serve heavily exuding wounds in hospital and home settings.
- Silver-infused:Ionic silver antimicrobial action addresses bioburden in infected wounds and diabetic foot ulcers, though environmental discharge regulations and resistance concerns drive peptide alternative pilots.
Foam technology holds the installed base leadership position while silver-infused variants face the most significant substitution dynamics from emerging antimicrobial platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates sharply in Lombardy and Veneto, where dense hospital networks and specialized wound clinics command premium procurement terms, while southern regions operate under constrained budgets and fragmented purchasing authority.
Lombardy
Milan's concentration of orthopedic and diabetic foot centers drives demand for hydrofiber and antimicrobial dressings. The region's health authority applies EU MDR documentation requirements strictly in hospital tenders. The Milan-Monza-Brianza corridor anchors Italy's most sophisticated wound care logistics networks.
Veneto
Verona and Padua host specialized burn centers and vascular surgery units requiring advanced moisture-retentive technologies. Regional procurement consolidation through the Azienda Zero framework compresses supplier margins while accelerating technology transitions. The Veneto cluster leads national adoption of telemedicine-integrated home care protocols.
Emilia-Romagna
Bologna's geriatric research hospitals pioneer silicone-adhesion protocols for fragile skin applications. The region's Servizio Sanitario Nazionale office unbundles wound care supplies from procedure-based reimbursement. Long-term care networks across Modena and Parma adopt gentle-removal products at scale.
Tuscany
Florence and Pisa health authorities pilot negative-pressure wound therapy integration with outpatient chronic care. Tuscany's regional government funds telemedicine infrastructure to reduce hospital readmissions. The Florence wound clinic cluster trains certified nurses for southern region deployment.
Sicily
Palermo and Catania face nursing shortages that delay protocol adoption despite rising diabetic foot ulcer prevalence. Sicily's regional health authority seeks outsourced chronic care partnerships to close infrastructure gaps. Underdeveloped home care networks create whitespace for integrated wound management services.
Italy Wound Care Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium innovators and scale-efficient manufacturers occupy distinct profit pools. The market consolidates around three strategic archetypes: multinational technology specialists with hydrofiber and silicone portfolios, diversified medical device conglomerates leveraging cross-selling infrastructure, and regional converters serving commodity bandage demand. Competitive moves center on M&A to acquire antimicrobial peptide capabilities and strategic partnerships with regional health authorities for multi-year supply contracts.
Among the technology specialists, Smith+Nephew, Mölnlycke Health Care, and Coloplast occupy positions defined by distinct material science competencies. Smith+Nephew exemplifies the hydrofiber-dominant archetype serving high-acuity hospital segments. Mölnlycke Health Care anchors the direct-distribution model to regional health authorities across northern Italy. Coloplast represents the silicone-adhesion convergence from adjacent ostomy care into wound applications.
| Leading Market Players |
|---|
| Smith+Nephew |
| ConvaTec |
| Mölnlycke Health Care |
| Coloplast |
| 3M |
| Solventum |
| Medtronic |
| B. Braun |
| Paul Hartmann |
| Others |
Pricing and Supply Chain Analysis
Antimicrobial peptide alternatives displacing silver sulfadiazine in Lombardy burn centers are rerouting procurement toward German and Dutch polymer converters while compressing legacy dressing margins. This substitution dynamic concentrates supply authority among EU MDR-certified manufacturers and amplifies price sensitivity in standard gauze segments.
Pricing Analysis
The customization-premium spread between configured-to-order hydrofiber dressings and standard foam variants determines margin capture across Italian hospital tiers. Three-tier pricing structure across premium, standard, and economy levels reflects EU MDR certification grade and volume scale commitments to regional health authorities. Price erosion runs through commodity bandage segments as Consip framework consolidation forces transparent benchmarking. Home care providers exhibit highest price sensitivity due to constrained per-patient budgets, while acute burn centers maintain lowest sensitivity given clinical outcome priorities.
Supply Chain Analysis
Inventory lead times for alginate and hydrocolloid raw materials have extended as German and Netherlands polymer suppliers prioritize MDR-compliant converters. Italian wound care manufacturing draws from seaweed-derived calcium alginate feedstocks, silver nitrate antimicrobial inputs, and silicone adhesive polymers. Single-source vulnerability concentrates in advanced dressing polymer supply chains clustered in northern Europe. Distribution runs through regional health authority tender systems with direct logistics contracts replacing traditional distributor rebate structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy wound care market sits at a technology disruption inflection where EU MDR compliance filters out commodity suppliers and concentrates shelf space among certified innovators. Hydrofiber and antimicrobial peptide transitions are reshaping competitive positioning faster than legacy players can reposition portfolios.
For Market Incumbents: Compound regulatory compliance investments into multi-region Consip framework contracts before smaller competitors recover MDR registration capacity. Secure backward integration into German polymer supply chains to defend margin position against freight cost volatility. Prioritize silicone-adhesion R&D convergence from ostomy applications into geriatric wound protocols. For New Entrants and Emerging Players: Telemedicine-integrated home care services in Sicily and Calabria represent the most penetrable whitespace where nursing shortages delay incumbent protocol rollout. Target outsourced chronic care partnerships with regional health authorities seeking infrastructure coverage. Deploy direct-to-clinic sampling programs bypassing consolidated hospital procurement gates. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified multinationals with MDR regulatory affairs capacity and multi-region logistics footprints. Acquisition target archetypes include mid-tier Italian converters with established hospital relationships but incomplete MDR technical documentation. Watch antimicrobial peptide pilot adoption rates in Lombardy burn centers as inflection signal for silver substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market access timelines for Class IIb dressing variants through notified body partnerships. |
| Regional Health Authority Direct Contracting | Secures multi-year supply commitments through Consip framework participation in Lombardy and Veneto. |
| Silicone Adhesion Technology Migration | Captures geriatric and pediatric fragile-skin segments previously excluded from advanced protocols. |
| Telemedicine-Integrated Home Care Partnership | Addresses nursing shortage constraints in Sicily through remote monitoring and reduced visit frequency. |
| Antimicrobial Peptide Portfolio Acquisition | Positions ahead of silver sulfadiazine displacement in Milan and Rome burn center procurement. |
Research Methodology
Cross-validation between hospital procurement database analysis and wound care clinician interviews anchors the qualitative findings in documented purchasing behavior. Primary fieldwork encompassed biomedical engineers, GPO contracts managers, hospital purchasing committee members, and regional health authority tender officers. Secondary sources included EU MDR notified body registration databases, Servizio Sanitario Nazionale reimbursement code filings, and Consip framework award disclosures. Bottom-up demand modeling triangulated against top-down macroeconomic projections.
Sensitivity analysis tested forecast outputs against variable adoption rates for hydrofiber and antimicrobial peptide technologies across the projection horizon. Segmentation dimensions modeled encompassed product type, end-user channel, wound application category, and technology platform. CAGRs derived from historical volume trajectories adjusted for EU MDR registration timeline disruptions and regional procurement consolidation intensity. Forecast inputs incorporated nursing workforce distribution data and telemedicine infrastructure deployment schedules by region.
Underlying assumptions cover stable EU MDR enforcement continuity and sustained Servizio Sanitario Nazionale reimbursement code stability, with deviation risk concentrated in silver price volatility and notified body audit backlogs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Surgery Medical Bandage Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Global Wound Irrigation System Market
Wound Care
Maggot Debridement Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Burn Care Centers Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
US Wound Irrigation System Market
Wound Care
Wound Evacuators Market
Wound Care
Antimicrobial Wound Dressings Market
Wound Care
US Burn Care Centers Market
Wound Care
Wound Care Biologics Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
Wound Closure Strips Market