
 Philippines Wound Care Market | 2026-2036
Philippines Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Wound Care Market Insights
Market Context
Advanced wound dressing technology is fragmenting into antimicrobial, moisture-retentive, and bioactive sub-categories, forcing manufacturers to recalibrate production lines for narrower indications. 3M Company leverages its adhesive science portfolio to dominate hydrocolloid and foam dressing supply to Philippine distributors. Smith & Nephew Plc sustains competitive positioning through specialized negative pressure wound therapy systems tailored to tropical climate conditions. Coloplast A/S anchors its presence in chronic wound management via ostomy and fistula care extensions that serve long-term care facilities.
Technical Definition and Segment Structure
Wound care encompasses medical products designed to protect injured tissue, manage exudate, prevent infection, and promote healing through controlled moisture balance, antimicrobial action, or mechanical closure. Primary compositions include alginate fibers derived from brown seaweed, hydrocolloid gels containing carboxymethylcellulose, and synthetic polymer films applied over partial-thickness wounds. Dressings lead product type revenue given their recurring consumption model and broad applicability across chronic and acute cases. Homecare represents the fastest-growing end user segment as the Philippine Department of Health pushes post-operative discharge protocols and family-based wound monitoring programs.
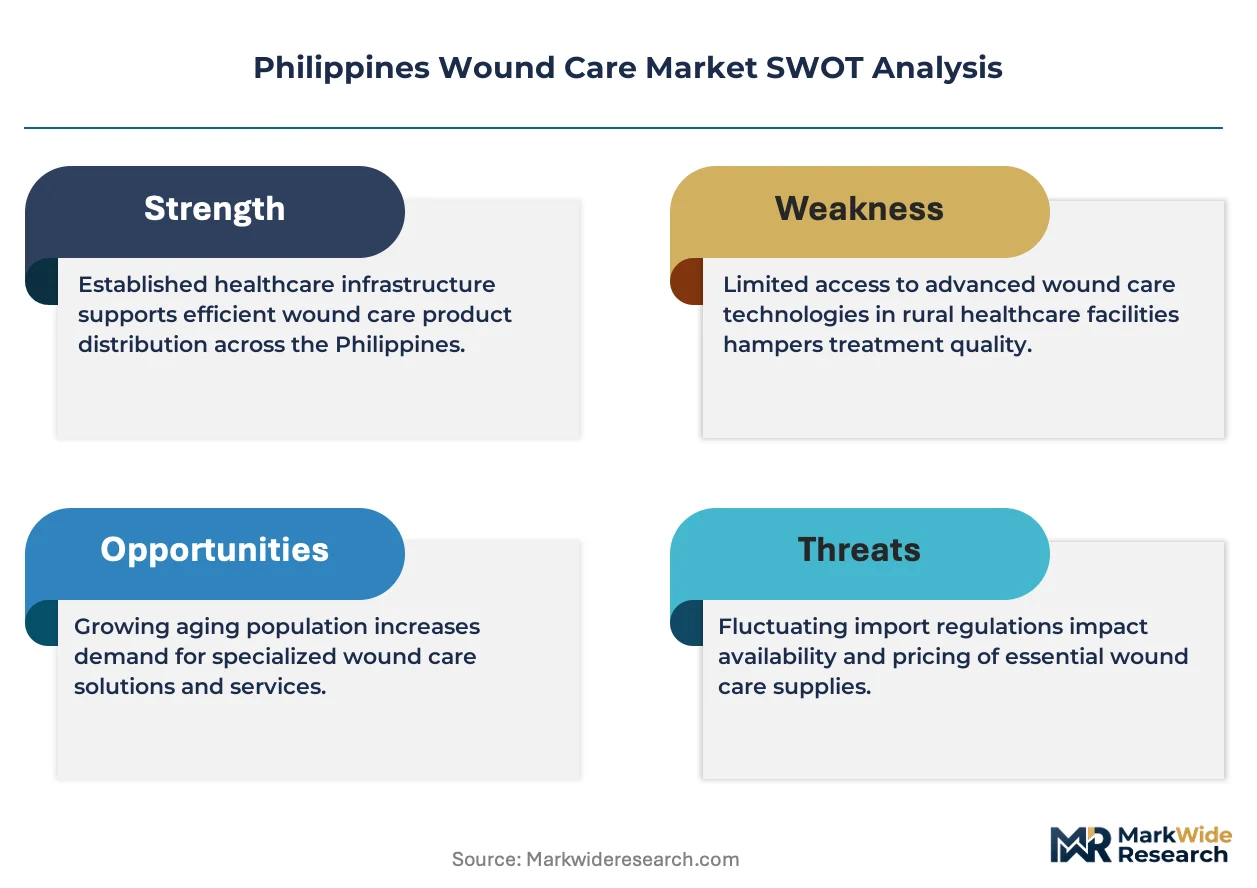
Regulatory Framework and Outlook
The Philippine Food and Drug Administration governs medical device registration through ASEAN Harmonized Regulatory Scheme alignment, while Bureau of Product Standards technical regulations enforce labeling and sterility benchmarks for imported dressings and sutures. Department of Health administrative orders mandate hospital infection control committees to document wound care protocol compliance, directly shaping procurement specifications for antimicrobial and barrier products. Stakeholders must monitor pending bioequivalence requirements for topical agents and the trajectory of PhilHealth reimbursement expansion for advanced outpatient wound management.
Market Dynamics
The Philippine Food and Drug Administration's tightened ASEAN Harmonized Regulatory Scheme alignment is compressing import timelines for advanced wound dressings while simultaneously elevating documentation burdens for foreign manufacturers seeking market entry.
Growth Catalysts
- PhilHealth Reimbursement Expansion:The Philippine Health Insurance Corporation's outpatient benefit package extension for chronic wound management is pulling advanced dressings into community health centers previously limited to basic gauze supplies.
- Diabetic Foot Clinic Networks:Department of Health administrative orders mandating specialized diabetic foot units in tertiary hospitals across Luzon and Visayas are creating dedicated procurement channels for antimicrobial and moisture-retentive technologies.
- Alginate Fiber Manufacturing:Local brown seaweed processing capabilities in Cebu and Iloilo are reducing import dependency for absorbent dressing cores used in exudate-heavy burn and pressure ulcer cases.
Market Restraints
- Carboxymethylcellulose Import Concentration:Hydrocolloid gel precursors remain concentrated among Korean and Japanese chemical suppliers, exposing Philippine converters to yen-won exchange volatility and maritime shipping disruptions through the Luzon Strait.
- Sterility Validation Bottlenecks:The Bureau of Product Standards' limited domestic gamma irradiation capacity forces manufacturers to route finished dressings through Singapore or Thailand for terminal sterilization, adding thirty to forty-five days to production cycles.
- Basic Gauze Substitution:Public hospital budget constraints sustain demand for woven cotton gauze in uncomplicated surgical wounds, limiting penetration of advanced polymer dressings in price-sensitive procurement tiers.
Strategic Opportunities
- Mindanao Health Infrastructure:The Department of Health's Barangay Health Station upgrade program in Davao and Cagayan de Oro creates first-mover advantage for distributors establishing cold-chain logistics for bioactive dressing storage.
- Negative Pressure Homecare Extension:Convergence of portable suction device miniaturization and PhilHealth's discharge protocol mandates is opening reimbursement pathways for post-acute wound therapy outside hospital walls.
- E-Commerce Direct Channels:Lazada and Shopee pharmaceutical marketplaces are bypassing traditional distributor markups for chronic wound patients in Metro Manila's upper-middle demographic seeking silicone foam and hydrofiber products.
Industry Challenges
- Wound Care Specialist Shortage:Philippine Medical Association data indicates fewer than two hundred certified wound, ostomy, and continence nurses serving a population exceeding one hundred million, constraining protocol adherence in provincial hospitals.
- Legacy Inventory Systems:Many Department of Health-retained hospitals operate on paper-based procurement tracking that cannot accommodate lot-level traceability requirements for FDA-registered medical devices, forcing parallel documentation workflows.
Report Scope
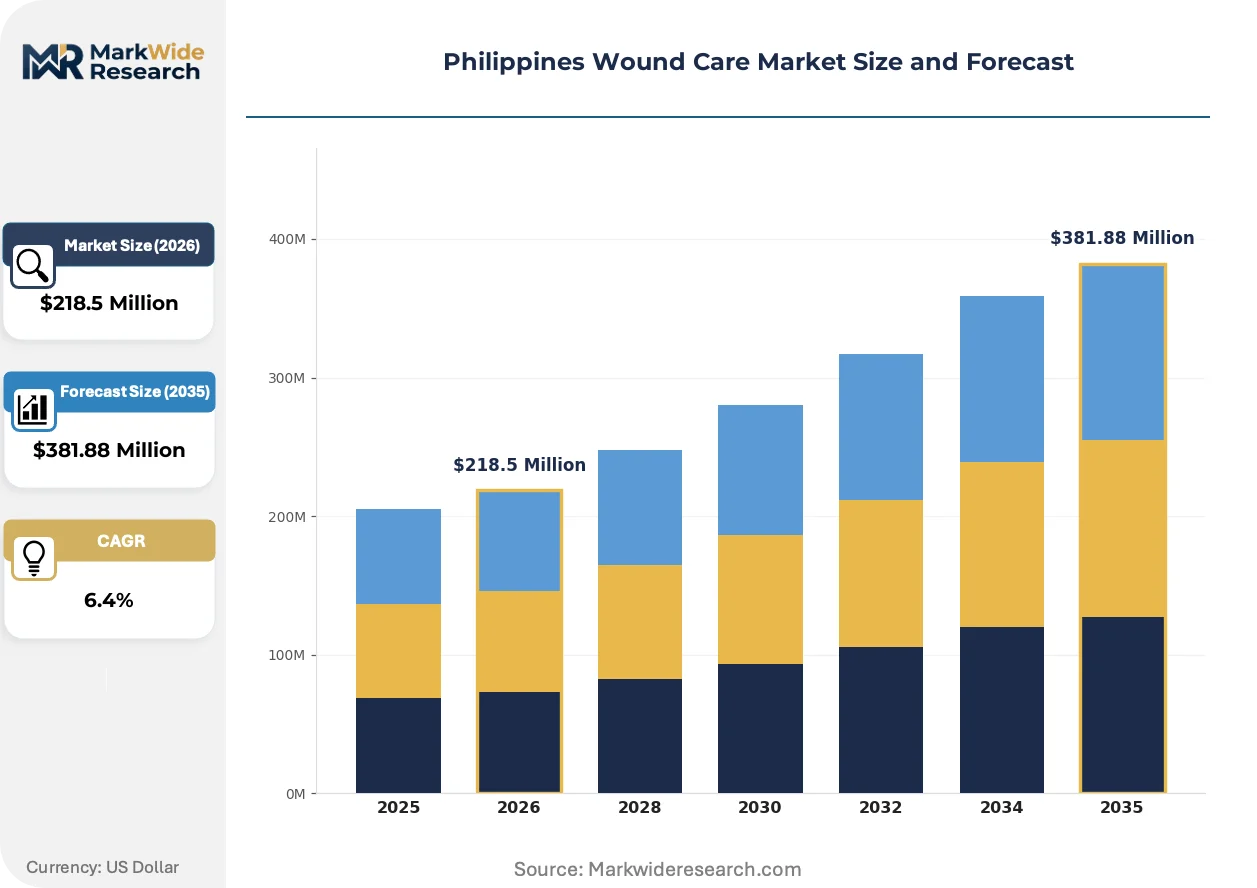
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Wound Care Market |
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $381.88 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Topical Agents, Sutures, Devices End User: Hospitals, Homecare, Clinics, Long-term Care Facilities Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burn Care Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Medtronic plc, Cardinal Health, Inc., 3M Company, B. Braun Melsungen AG, BSN Medical GmbH, Smith & Nephew Plc, ConvaTec Group Plc, Mundipharma International Ltd., Coloplast A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Wound Care Market Trends and Innovations
Digital wound assessment tools and bioactive material science are converging to reshape how Philippine clinicians document, monitor, and intervene in chronic wound cases across fragmented care settings.
Antimicrobial silver-ion and polyhexamethylene biguanide dressings are virtualizing traditional iodine-based infection control protocols in Metro Manila's burn centers. Tertiary hospital procurement committees now specify sustained-release antimicrobial action in tender documents for partial-thickness thermal injuries. This shift is compressing market space for conventional antiseptic-soaked gauze while elevating contract value thresholds for suppliers demonstrating biofilm disruption efficacy.
The Philippine Food and Drug Administration's pending bioequivalence requirements for topical wound healing agents are forcing reformulation submissions from ASEAN-registered pharmaceutical manufacturers. This regulatory friction is extending product registration timelines from eighteen to thirty-six months for hydrogel and collagen-based therapies. Importers are responding by front-loading clinical documentation from Singapore's Health Sciences Authority and Thailand's FDA to preempt local data requirements.
Family-based wound monitoring programs endorsed by the Department of Health are displacing routine clinic visits for post-operative surgical wounds in Calabarzon and Central Luzon provinces. Community health workers now distribute smartphone-compatible measurement guides and exudate logging templates to household caregivers. This behavioral pivot concentrates demand for patient-friendly dressing systems with extended wear times in peri-urban municipalities where transportation costs previously drove non-adherence.
Philippines Wound Care Market Segmentation
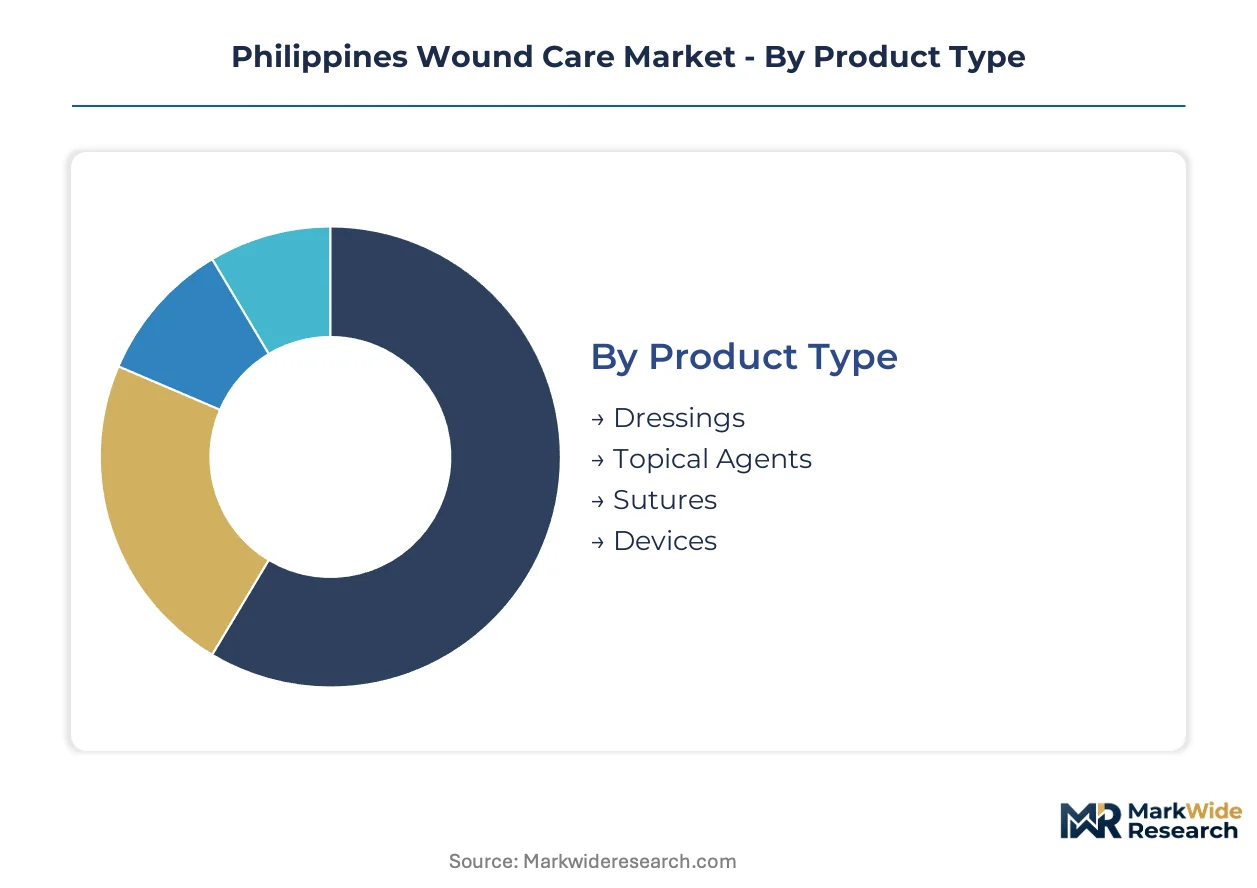
Segmentation in the Philippine wound care market reveals how procurement authority, reimbursement pathways, and clinical setting infrastructure fragment demand across radically different price sensitivities and technical specifications. Understanding these fault lines determines whether manufacturers target Department of Health hospital tenders, PhilHealth-accredited homecare networks, or direct-to-patient e-commerce channels.
Product Type:
Cost tier determines manufacturing scale and margin structure across the four product categories, with consumable dressings commanding recurring revenue streams against capital-intensive device placements.
- Dressings:Alginate fibers, hydrocolloid gels, and silicone foam composites absorb exudate while maintaining moist wound environments. Metro Manila's tertiary burn centers and diabetic foot clinics in Cebu drive procurement of antimicrobial silver-ion variants. PhilHealth's outpatient benefit expansion is pulling advanced moisture-retentive technologies into community health centers previously limited to basic gauze.
- Topical Agents:Hydrogels, collagen-based therapies, and sustained-release antimicrobial formulations accelerate granulation tissue formation. The Philippine Food and Drug Administration's pending bioequivalence requirements are extending registration timelines for ASEAN-registered pharmaceutical manufacturers seeking market entry.
- Sutures:Absorbable polyglycolic acid and non-absorbable polypropylene threads close surgical incisions across Luzon's hospital network.
- Devices:Negative pressure wound therapy systems and portable suction units serve post-acute care settings in Davao and Cagayan de Oro.
Dressings hold installed capacity. Devices is rotating up the share rankings.
End User:
Customer type segmentation maps directly to reimbursement authority and procurement sophistication, from centralized Department of Health tenders to fragmented household purchasing decisions.
- Hospitals:Tertiary facilities in Metro Manila and regional centers in Visayas maintain infection control committees that specify antimicrobial and barrier product requirements. These institutions dominate advanced dressing procurement through centralized tender processes.
- Homecare:Family-based wound monitoring programs in Calabarzon and Central Luzon displace routine clinic visits for post-operative cases. Smartphone-compatible measurement guides distributed by community health workers concentrate demand for extended-wear dressing systems.
- Clinics:Provincial primary care facilities in Mindanao operate on paper-based procurement tracking that struggles with lot-level traceability requirements.
- Long-term Care Facilities:Chronic wound management in elderly care settings anchors demand for ostomy and fistula care extensions.
Hospitals anchor procurement volume. Homecare is climbing the fastest as discharge protocols accelerate.
Application:
Application type determines clinical outcome metrics and regulatory scrutiny intensity, with burn care and diabetic foot cases commanding specialized procurement channels.
- Chronic Wounds:Pressure ulcers, venous leg ulcers, and diabetic foot ulcers require sustained antimicrobial action and moisture balance. The Department of Health's mandated diabetic foot clinic networks across Luzon and Visayas create dedicated procurement channels for advanced technologies.
- Surgical Wounds:Post-operative incision management in Department of Health-retained hospitals sustains demand for basic gauze in price-sensitive tiers while driving uptake of barrier dressings in private facilities.
- Traumatic Wounds:Acute injury cases in emergency departments require rapid exudate management and hemostasis.
- Burn Care:Partial-thickness thermal injuries in Metro Manila burn centers specify sustained-release antimicrobial action in tender documents, compressing market space for conventional antiseptic-soaked gauze.
Chronic wounds dominate addressable volume. Burn care is gaining share fastest through specialized center expansion.
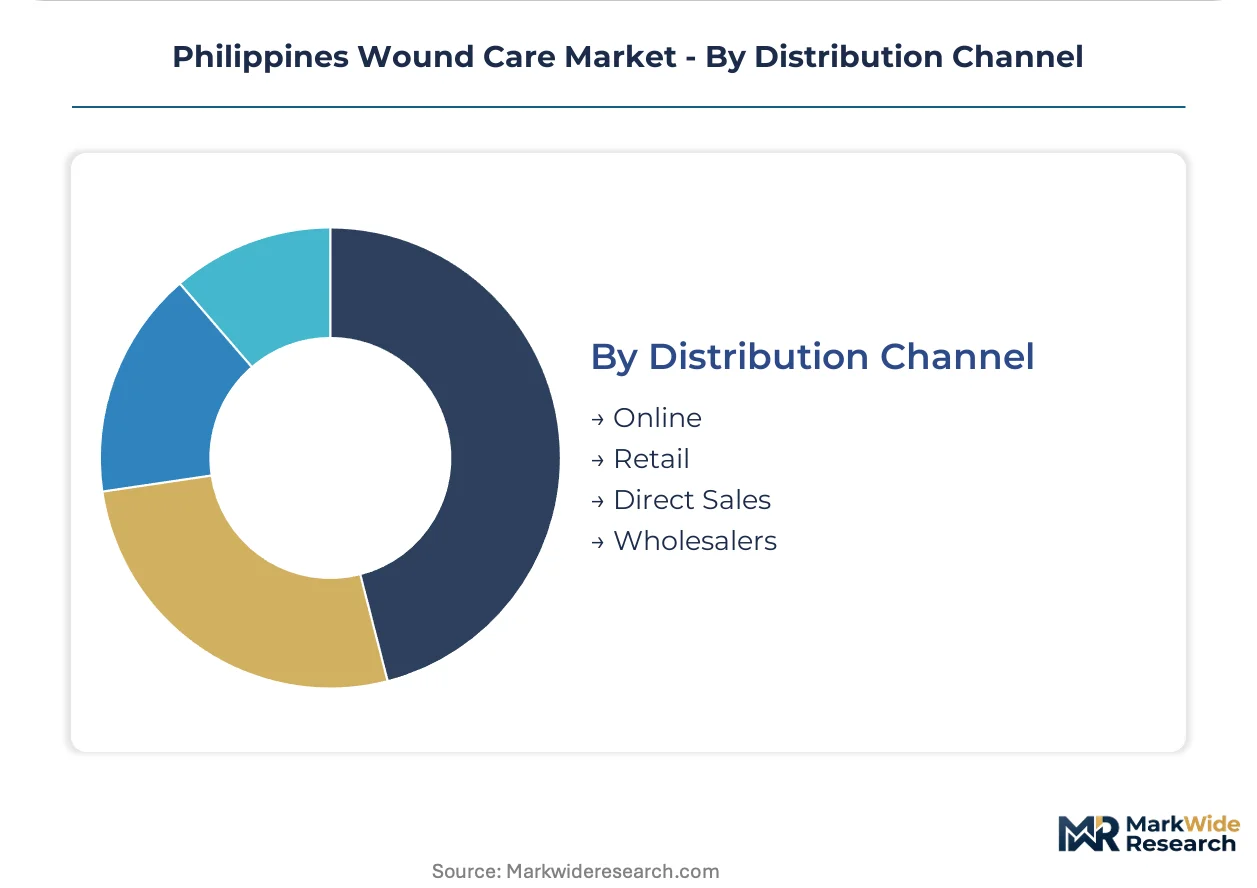
Distribution Channel:
Channel structure reflects supply chain concentration and margin capture, from manufacturer-direct hospital contracts to platform-mediated patient purchases.
- Online:Lazada and Shopee pharmaceutical marketplaces bypass traditional distributor markups for chronic wound patients in Metro Manila's upper-middle demographic. Silicone foam and hydrofiber products move through these channels to households seeking patient-friendly systems.
- Retail:Pharmacy chains serve post-operative patients with basic dressing supplies in peri-urban municipalities.
- Direct Sales:Manufacturers negotiate tenders directly with hospital procurement committees and Department of Health central medical stores.
- Wholesalers:Traditional distributors maintain cold-chain logistics for bioactive dressing storage in Mindanao's emerging health infrastructure.
Direct sales holds institutional contract value. Online is rotating up the share rankings through platform penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean and Japanese chemical suppliers dominate hydrocolloid gel precursor exports to Philippine wound care converters, routing through the Luzon Strait to manufacturing facilities in Metro Manila and Cebu.
Metro Manila
Tertiary hospital networks in Quezon City and Pasig anchor procurement volume for antimicrobial silver-ion dressings. The Department of Health's infection control committee mandates drive tender specifications toward sustained-release antimicrobial technologies. Burn centers in Manila's medical district specify advanced moisture-retentive systems, compressing conventional gauze market share.
Central Luzon
Family-based wound monitoring programs in Bulacan and Pampanga displace routine clinic visits for post-operative cases. Community health workers distribute smartphone-compatible measurement guides to household caregivers. This behavioral pivot concentrates demand for extended-wear dressing systems in peri-urban municipalities.
Calabarzon
PhilHealth's outpatient benefit expansion pulls advanced dressings into community health centers across Cavite and Laguna. The Philippine Food and Drug Administration's ASEAN Harmonized Regulatory Scheme alignment compresses import timelines for foreign manufacturers. Laguna-based distributors establish cold-chain logistics for bioactive product storage.
Visayas
Diabetic foot clinic networks mandated by Department of Health administrative orders create dedicated procurement channels in Cebu and Iloilo. Local brown seaweed processing capabilities reduce import dependency for alginate fiber cores used in exudate-heavy cases. Iloilo's converter facilities supply absorbent dressing materials to regional hospital networks.
Mindanao
The Department of Health's Barangay Health Station upgrade program in Davao and Cagayan de Oro creates first-mover advantage for distributors establishing specialized logistics. Portable negative pressure wound therapy devices gain traction through PhilHealth discharge protocol mandates. Davao's emerging health infrastructure anchors demand for chronic wound management technologies.
Philippines Wound Care Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Hospital procurement committees in Metro Manila and regional medical centers operate through centralized tender processes that favor established distributor relationships. Three archetypes dominate: diversified medical technology conglomerates with adhesive science portfolios, specialized wound care pure-plays with negative pressure systems, and ostomy-focused chronic care extensions. Competitive moves concentrate on portfolio diversification into antimicrobial sub-categories and geographic expansion through distributor network deepening in Visayas and Mindanao.
Among diversified technology conglomerates, 3M Company and Medtronic plc occupy positions anchored by broad medical device portfolios. Smith & Nephew Plc exemplifies the wound care pure-play archetype with specialized system offerings. Coloplast A/S represents the chronic care extension model through ostomy and long-term care anchoring. These three companies illustrate the competitive tension between scale-driven channel control and indication-specific technology depth.
| Leading Market Players |
|---|
| Medtronic plc |
| Cardinal Health, Inc. |
| 3M Company |
| B. Braun Melsungen AG |
| BSN Medical GmbH |
| Smith & Nephew Plc |
| ConvaTec Group Plc |
| Mundipharma International Ltd. |
| Coloplast A/S |
| Others |
Pricing and Supply Chain Analysis
Carboxymethylcellulose import concentration from Korean and Japanese chemical suppliers determines both the premium-to-economy pricing spread for hydrocolloid dressings and the three-tier supply chain structure routing through the Luzon Strait. Philippine converters absorb exchange volatility and maritime disruption risk, passing cost premiums to hospital procurement committees while basic gauze alternatives capture price-sensitive public tenders.
Pricing Analysis
Current-generation antimicrobial silver-ion and silicone foam technologies command three-tier pricing structure across premium, standard, and economy levels, with prior-generation hydrocolloid gels and woven cotton gauze occupying lower tiers. Certification grade under FDA's ASEAN Harmonized Regulatory Scheme and volume scale in Department of Health central tenders drive price differentiation. Cost compression in standard-tier hydrocolloid production is intensifying because carboxymethylcellulose precursor costs fluctuate with yen-won volatility. Public hospital procurement committees exhibit highest price sensitivity, while Metro Manila's private burn centers demonstrate lowest sensitivity due to outcome-based procurement mandates.
Supply Chain Analysis
Tariff exposure between South Korea and Japan dominates supply chain risk for hydrocolloid gel precursors, with Philippine converters dependent on maritime routes through the Luzon Strait. Raw material sourcing draws from Korean carboxymethylcellulose manufacturers, Japanese chemical suppliers for synthetic polymer films, and domestic brown seaweed processors in Cebu and Iloilo for alginate fibers. Single-source vulnerability in gamma irradiation terminal sterilization forces routing through Singapore or Thailand, extending production cycles. Distribution runs through traditional wholesalers maintaining cold-chain logistics for bioactive dressings, with Lazada and Shopee pharmaceutical marketplaces emerging as direct-to-patient channels bypassing distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Philippine wound care is a service-attach opportunity where family-based wound monitoring programs and extended-wear dressing system support services expand faster than commodity dressing hardware sales.
For Market Incumbents: Entrench position by deepening backward integration into Cebu and Iloilo brown seaweed processing for alginate fiber captive supply, insulating against Korean-Japanese precursor volatility. Add sterilization capacity partnerships in Singapore or Thailand to compress the thirty-to-forty-five-day terminal validation bottleneck threatening contract fulfillment. Certification investment in FDA bioequivalence documentation front-loading will preempt registration timeline extensions for topical agent portfolios. For New Entrants and Emerging Players: Mindanao's Barangay Health Station upgrade program in Davao and Cagayan de Oro represents the most penetrable geographic white space, with cold-chain logistics infrastructure still nascent. Portable negative pressure wound therapy devices for post-acute homecare offer the fastest-rotating application segment as PhilHealth discharge protocols accelerate. A distributor partnership model anchoring in regional medical centers before central tender qualification provides the most viable go-to-market angle. For Investors and Strategic Acquirers: Specialized wound care pure-plays with negative pressure system technology and established PhilHealth reimbursement pathways represent the priority acquisition target archetype. Long-term viability over the next decade hinges on convergence between digital wound assessment tools and bioactive material science platforms. The signal to watch is PhilHealth outpatient benefit expansion velocity for advanced dressing categories, which will indicate reimbursement-driven demand inflection before volume materializes in procurement data.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct tender access with Metro Manila tertiary networks secures antimicrobial dressing procurement volume. |
| Reimbursement Strategy | PhilHealth outpatient benefit alignment pulls advanced dressings into community health center formularies. |
| Backward Integration | Cebu and Iloilo brown seaweed processing captive supply reduces alginate fiber import dependency exposure. |
| Software Companion Development | Smartphone-compatible measurement guides for family-based wound monitoring displace routine clinic visits. |
| CE Marking Pathway | Singapore Health Sciences Authority clinical documentation front-loading preempts FDA bioequivalence delays. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, wound care clinicians, and GPO contracts managers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA registration databases, PhilHealth reimbursement bulletins, Department of Health administrative orders, and Bureau of Product Standards technical regulations. Bottom-up demand modeling from hospital tender documents and top-down macroeconomic triangulation anchored volume estimates.
Scenario-bracketing framed analytical approaches across the projection horizon, with sensitivity testing around regulatory timeline variations and reimbursement expansion trajectories. Segmentation dimensions modeled include product type, end user, application, and distribution channel, with geographic procurement sophistication as an industry-specific overlay. CAGRs were derived from fitted growth curves against historical tender award patterns and import volume trends. Forecast inputs incorporated alginate fiber domestic production capacity buildout and gamma irradiation terminal sterilization bottleneck resolution timelines.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates, maritime shipping costs through the Luzon Strait, or Korean-Japanese chemical export pricing would shift the trajectory. Forecasts reflect assumptions around FDA regulatory alignment maintenance and PhilHealth benefit package continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Drainage Devices Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Vascular Dressings Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Advanced Wound Care Market
Wound Care
Moist Wound Dressings Market
Wound Care
Wound Closure Market
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
Global Wound Dressings Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
North America Wound Care Management Market
Wound Care
Global Wound Irrigation System Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Dental Wound Dressings Market