
 Arthroscopy Fluid Management Disposables Market | 2026-2036
Arthroscopy Fluid Management Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Arthroscopy Fluid Management Disposables Market Intelligence
A clear divide between high-performance, integrated systems and basic, single-component disposables is consolidating the market. Stryker leverages its established surgical system platforms to promote bundled disposable sales with its pumps. Meanwhile, Arthrex differentiates through its extensive portfolio of specialized tubing sets and cannulas for specific joint procedures. Smith & Nephew competes on the strength of its fluid management pumps and compatible single-use cassettes, securing repeat business through system lock-in.
Arthroscopy fluid management disposables comprise sterile, single-use components designed to maintain a clear visual field and joint distention during surgery. These products, including tubing sets made from medical-grade PVC or silicone, manage the inflow of saline and outflow of waste fluids. Tubing sets and fluid bags represent the largest product segments by volume due to their one-per-procedure replacement cycle. Knee arthroscopy remains the dominant application, but shoulder arthroscopy procedures represent a fast-growing source of demand.
The US FDA's 510(k) clearance pathway is a primary hurdle for new device market entry in the United States. In Europe, compliance with the Medical Device Regulation (MDR) and its CE marking requirements governs product standards and post-market surveillance. Future competitive advantage will depend on developing disposables that minimize fluid extravasation and integrate seamlessly with next-generation smart pump systems.
Market Dynamics
The imperative for infection control, driven by stringent regulatory mandates for single-use devices, is the central force shaping the market. This pressure combines with the demand for procedural efficiency from ambulatory surgical centers, accelerating the transition to pre-packaged, sterile disposables.
Growth Catalysts
- Expanding Applications:The rising incidence of sports-related injuries and degenerative joint diseases is increasing procedural volumes for shoulder arthroscopy, which represents the fastest-growing source of demand for specialized tubing sets and cannulas.
- Regulatory Mandates:The EU's Medical Device Regulation (MDR) enforces rigorous standards for device traceability and sterility, compelling healthcare facilities to adopt certified, single-use disposables over reprocessed alternatives to ensure compliance and mitigate liability.
- Demographic Shifts:Aging populations in developed nations like Germany and Japan are leading to a higher prevalence of osteoarthritis, directly increasing the number of knee arthroscopy procedures performed and fueling consistent demand for fluid management products.
Market Restraints
- Proprietary System Lock-In:The high cost of disposables designed exclusively for a specific manufacturer's fluid management pump creates significant budget constraints for healthcare providers, limiting their purchasing flexibility and slowing adoption in cost-sensitive markets.
- Input Material Volatility:Production costs are directly exposed to price fluctuations and supply chain disruptions for key raw materials like medical-grade PVC and silicone, which can compress manufacturer margins or lead to price increases for end-users.
- Third-Party Competition:The availability of lower-cost, generic tubing sets from independent manufacturers presents a persistent substitution threat, particularly for basic procedures where the benefits of integrated, premium-priced systems are less critical for surgical outcomes.
Strategic Opportunities
- Smart Disposable Development:There is a clear opportunity to engineer disposables with integrated sensors that monitor intra-articular pressure and fluid balance in real-time, helping to minimize the risk of fluid extravasation during complex procedures.
- Emerging Market Penetration:Expanding distribution networks into Asia-Pacific countries, where healthcare infrastructure investment is rising and the adoption of minimally invasive surgery is accelerating, offers significant new growth potential for disposable manufacturers.
- Small-Joint Portfolio Expansion:Developing and marketing specialized, scaled-down disposable kits for arthroscopy of smaller joints, such as the wrist, elbow, and ankle, addresses a growing but currently underserved segment of the orthopedic market.
Industry Challenges
- Regulatory Compliance Timelines:Navigating the extensive documentation and clinical data requirements for obtaining FDA 510(k) clearance in the United States and CE marking under the EU MDR creates lengthy and costly barriers to entry for new products.
- Legacy System Integration:Ensuring backward compatibility and seamless interoperability of new, advanced disposables with the wide and fragmented installed base of older-generation fluid management pumps remains a significant technical and logistical hurdle for vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arthroscopy Fluid Management Disposables Market |
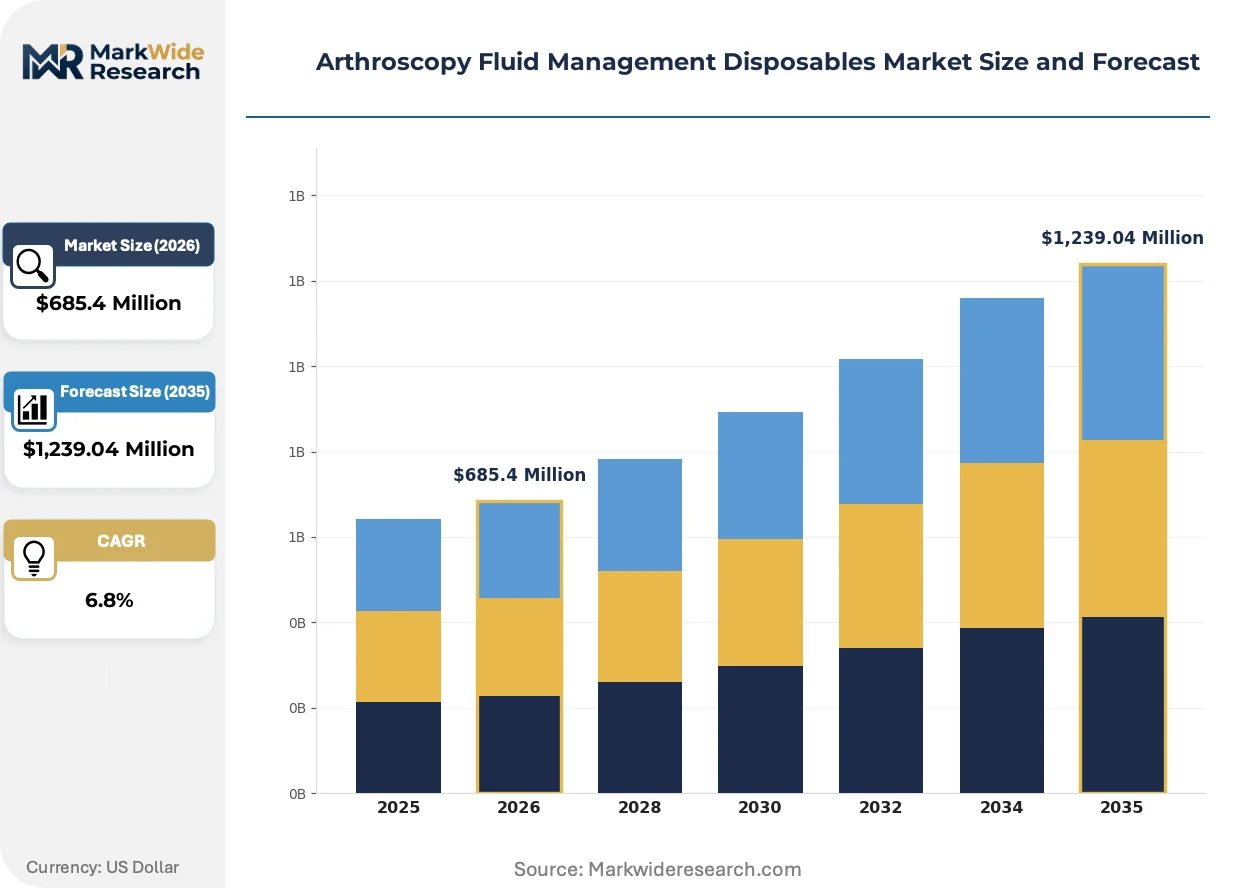
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluid Bags, Tubing Sets, Connectors, Cannulas Application: Knee Arthroscopy, Shoulder Arthroscopy, Elbow Arthroscopy, Wrist Arthroscopy, Hip Arthroscopy End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Specialty Surgery Centers Distribution Channel: Direct Sales, Medical Distributors, Online Retailers, Group Purchasing Organizations |
| Companies Covered | DePuy Synthes, Zimmer Biomet, Arthrex, Olympus, Karl Storz, Smith & Nephew, ConMed, Richard Wolf, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arthroscopy Fluid Management Disposables Market Strategic Shifts & Innovations
System-level integration and data-driven functionality are defining the next generation of arthroscopy disposables. The market is evolving from passive components to active tools that enhance surgical precision, improve patient safety, and streamline workflows within the operating room.
Smart cannulas and tubing sets embedded with micro-sensors provide real-time intra-articular pressure monitoring. High-volume orthopedic centers and ambulatory surgical centers are adopting these advanced disposables to improve patient safety. This integrated functionality is absorbing the role of separate monitoring equipment, simplifying the surgical workflow and reducing clutter.
The European Union's Medical Device Regulation (MDR) imposes stricter post-market surveillance and clinical evidence requirements on all medical devices. This regulation increases the compliance burden for manufacturers, demanding more robust quality management systems and lifecycle documentation. Tubing sets and cassettes are most affected, as vendors must now provide more detailed data on material biocompatibility to maintain their CE marking.
A definitive shift towards bundled procurement is evident, with hospitals purchasing disposables as part of a larger contract for arthroscopy towers and pumps. This model displaces transactional, item-by-item purchasing and favors vendors offering a complete, integrated system. The trend is most visible in the United States, where large hospital networks use their purchasing power to negotiate comprehensive contracts.
Arthroscopy Fluid Management Disposables Market Segmentation
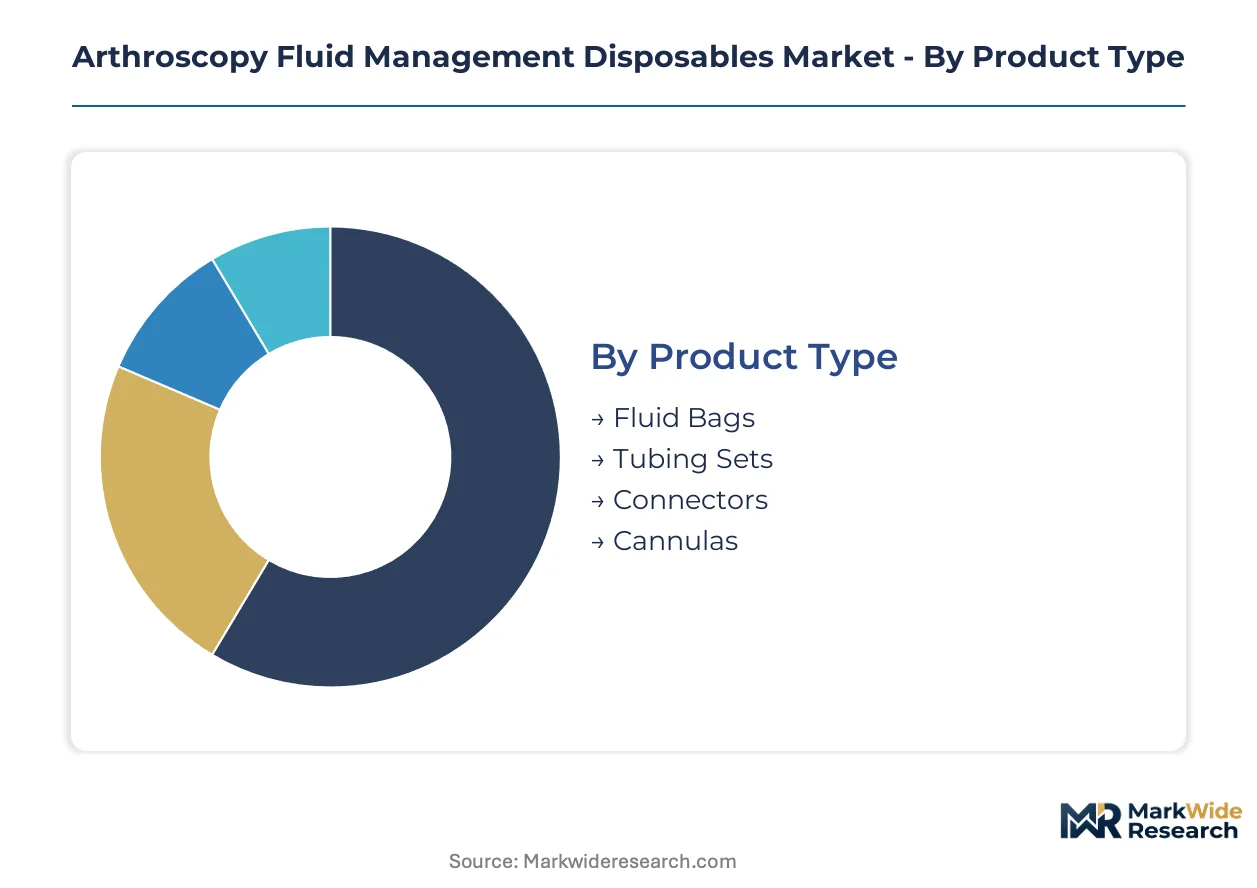
The arthroscopy fluid management disposables market is highly segmented, reflecting the diverse product requirements, clinical applications, and end-user operational models. Understanding these distinct segments is crucial for manufacturers to tailor product development, pricing strategies, and distribution networks effectively.
Product Type:
The capital intensity of manufacturing varies significantly across arthroscopy fluid management disposables.
- Tubing Sets:Tubing sets, often constructed from medical-grade PVC or silicone, facilitate the precise inflow and outflow of fluids during arthroscopic procedures. Demand for these single-use components is concentrated in high-volume orthopedic centers, driven by the imperative for infection control and procedural efficiency.
- Fluid Bags:Fluid bags store and deliver sterile saline solutions, typically featuring secure ports for connection to pump systems. Their consistent replacement cycle in ambulatory surgical centers underpins their significant market presence, ensuring continuous sterile fluid supply.
- Connectors:Connectors ensure leak-proof integration between tubing sets, fluid bags, and arthroscopic instruments, maintaining system integrity.
- Cannulas:Cannulas provide access channels into the joint space, allowing for instrument insertion and fluid exchange during surgery.
Tubing Sets absorb the bulk of installed capacity; Cannulas are expanding most quickly.
Application:
Arthroscopy fluid management disposables are specialized to address the unique anatomical and procedural demands of various joint surgeries.
- Knee Arthroscopy:Knee arthroscopy involves minimally invasive procedures to diagnose and treat conditions within the knee joint, frequently requiring high fluid volumes. This application represents the largest segment for disposables, driven by the high incidence of osteoarthritis in aging populations across countries like Germany and Japan.
- Shoulder Arthroscopy:Shoulder arthroscopy addresses rotator cuff tears, instability, and impingement, necessitating precise fluid management for visualization. It is a fast-growing application, with demand accelerating due to the rising incidence of sports-related injuries, particularly in the United States.
- Elbow Arthroscopy:Elbow arthroscopy procedures utilize smaller, specialized disposables for treating conditions like tennis elbow and loose bodies.
- Wrist Arthroscopy:Wrist arthroscopy, a niche application, requires micro-scale fluid management components for delicate joint access.
- Hip Arthroscopy:Hip arthroscopy, often for femoroacetabular impingement, demands longer cannulas and tubing sets due to deeper joint access.
Knee Arthroscopy procedures drive the majority of disposable consumption; Shoulder Arthroscopy is gaining share fastest.
End User:
The operational models and purchasing priorities of end-user segments significantly influence the adoption patterns of arthroscopy fluid management disposables.
- Hospitals:Hospitals represent the traditional and largest end-user segment, performing a broad spectrum of complex and routine arthroscopic surgeries. Their procurement is increasingly shifting towards bundled contracts for integrated systems, particularly in large networks across the United States.
- Ambulatory Surgical Centers:Ambulatory Surgical Centers (ASCs) specialize in outpatient procedures, prioritizing efficiency and cost-effectiveness in their fluid management systems. ASCs are rapidly expanding their adoption of pre-packaged, sterile disposables to streamline workflows and manage infection risks.
- Orthopedic Clinics:Orthopedic Clinics primarily focus on diagnosis and non-surgical treatment, with limited direct use of these disposables for minor in-office procedures.
- Specialty Surgery Centers:Specialty Surgery Centers focus on specific orthopedic sub-specialties, demanding tailored disposable solutions for niche procedures.
Hospitals maintain the largest share of disposable consumption; Ambulatory Surgical Centers exhibit the steepest expansion trajectory.
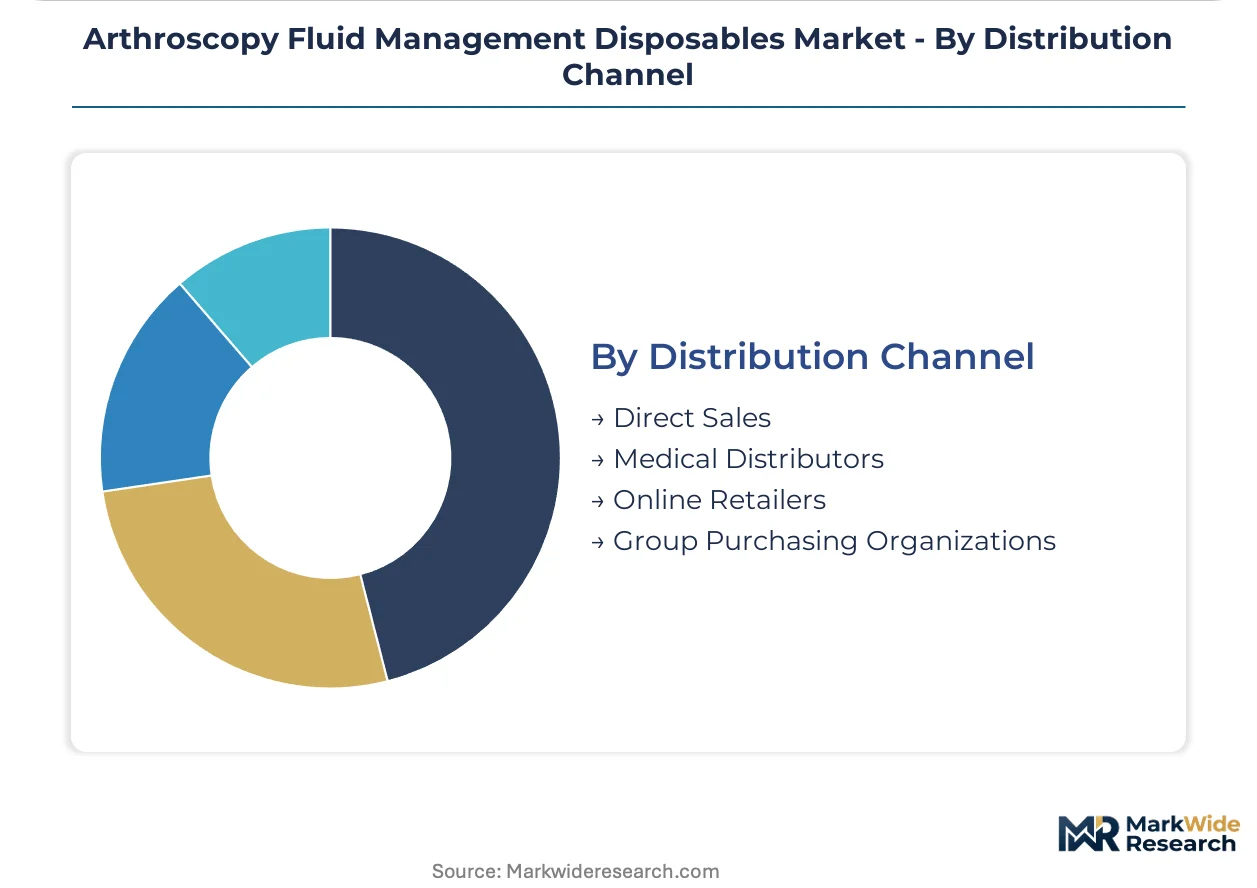
Distribution Channel:
The choice of distribution channel impacts market access, pricing strategies, and customer relationships for arthroscopy fluid management disposable manufacturers.
- Medical Distributors:Medical distributors provide extensive reach to a fragmented customer base, managing logistics and inventory for a wide range of products. This channel is crucial for smaller clinics and regional hospitals, offering efficient access to diverse product portfolios.
- Direct Sales:Direct sales channels involve manufacturers engaging directly with end-users, often for high-value integrated systems and bundled disposables. This approach allows for deeper customer relationships and tailored solutions, particularly with large hospital networks and key opinion leaders.
- Online Retailers:Online retailers offer convenience for smaller volume purchases of standard disposables, though regulatory hurdles limit their scope for complex medical devices.
- Group Purchasing Organizations:Group Purchasing Organizations (GPOs) leverage collective buying power to negotiate favorable terms for their member healthcare facilities, influencing large-volume procurement.
Medical Distributors remain the dominant channel for broad market penetration; Group Purchasing Organizations increasingly influence procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech cluster in the United States drives significant innovation in medical device development. This concentration of research institutions and companies fosters advancements in arthroscopy fluid management disposables. Demand for advanced surgical solutions is high within this region.
United States
High volumes of minimally invasive orthopedic procedures, particularly shoulder arthroscopy, fuel demand for advanced fluid management disposables. The US FDA's 510(k) clearance pathway governs new device market entry, ensuring product safety and efficacy. Major medical device manufacturers in the Minneapolis-St. Paul area focus on developing integrated surgical systems.
Germany
An aging population experiencing a higher prevalence of osteoarthritis consistently increases the number of knee arthroscopy procedures. Compliance with the European Medical Device Regulation (MDR) is critical for manufacturers to access this market. The Munich region, with its strong engineering and medical technology sector, is a hub for orthopedic device innovation.
Japan
Demographic shifts toward an older population contribute to a steady demand for knee arthroscopy procedures. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates medical device approvals, emphasizing product quality and clinical data. Companies in the Tokyo metropolitan area focus on precision manufacturing for specialized surgical instruments.
China
Rising healthcare infrastructure investment and accelerating adoption of minimally invasive surgery present substantial growth potential for disposables. The National Medical Products Administration (NMPA) oversees medical device registration and post-market surveillance. Manufacturing centers in the Yangtze River Delta region are expanding production capabilities for medical consumables.
France
The increasing incidence of sports-related injuries across Europe contributes to demand for shoulder arthroscopy procedures. Compliance with the EU MDR and CE marking requirements dictates product standards for market access. Medical technology clusters around Lyon develop specialized orthopedic solutions for complex joint procedures.
Arthroscopy Fluid Management Disposables Market Key Industry Players
Premium-margin players sit above commodity-margin players across the integrated system versus basic disposable spectrum. The market exhibits a tiered structure, with established medical device giants offering comprehensive solutions that integrate hardware and consumables. Two strategic archetypes include integrated system providers focused on system lock-in and specialized component manufacturers catering to niche procedural demands. Dominant competitive moves involve securing repeat business through proprietary system compatibility and strategically expanding portfolios for specific joint procedures.
Within the integrated system providers tier, Stryker exemplifies the strategy of leveraging established surgical platforms to promote bundled disposable sales with its pumps. Arthrex, conversely, occupies a position as a specialist, differentiating through an extensive portfolio of specialized tubing sets and cannulas for specific joint procedures. Smith & Nephew also anchors the market by competing on the strength of its fluid management pumps and compatible single-use cassettes, fostering customer loyalty through proprietary system compatibility.
| Leading Market Players |
|---|
| DePuy Synthes |
| Zimmer Biomet |
| Arthrex |
| Olympus |
| Karl Storz |
| Smith & Nephew |
| ConMed |
| Richard Wolf |
| Stryker |
| Others |
Cost & Logistics Intelligence
Proprietary system integration by dominant medical device companies anchors their supply position and significantly influences pricing power within the arthroscopy fluid management disposables market.
Pricing Analysis
Outcome-based pricing structures increasingly influence procurement decisions, especially for integrated systems that promise enhanced surgical efficiency and patient safety. Price differentiation stems from the quality grade of materials like medical-grade silicone, the stringency of certifications such as FDA 510(k) and EU MDR, and the brand premium associated with established manufacturers. Pricing pressure stems from the availability of lower-cost, generic alternatives, particularly impacting basic disposable segments. Ambulatory surgical centers exhibit higher price sensitivity compared to large hospital networks, which often prioritize bundled contracts for comprehensive solutions.
Supply Chain Analysis
Workforce availability in specialized manufacturing geographies like Germany and the United States supports the production of high-precision components for arthroscopy fluid management. The supply chain draws from key raw materials such as medical-grade PVC and silicone, which are susceptible to price fluctuations and logistics disruptions. Commodity price volatility for these inputs represents a structural risk for manufacturers. Distribution runs through a dual model, with medical distributors serving fragmented customer bases and direct sales channels catering to large hospital systems and group purchasing organizations for integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a consolidation play, as stringent regulatory mandates like the EU MDR are forcing weaker players out due to increased compliance burdens.
For Market Incumbents: Deepen proprietary system lock-in by integrating advanced disposables with next-generation smart pump systems. Expand specialized disposable portfolios for niche arthroscopic procedures, particularly for fast-growing applications like shoulder arthroscopy. This strategy mitigates threats from third-party competition by offering superior, integrated solutions. Investment in R&D for sensor technology and continuous certification updates under evolving regulations like FDA 510(k) provides a strong lever.
For New Entrants and Emerging Players: Online distribution channels offer a viable route for introducing cost-effective, standard disposables to price-sensitive ambulatory surgical centers. Target underserved segments such as small-joint arthroscopy (wrist, elbow, ankle) with specialized, scaled-down kits. A focused go-to-market angle involves collaborating with smaller orthopedic clinics or regional ASC networks that prioritize efficiency and specific procedural needs over full system integration.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized component manufacturers with strong intellectual property in real-time fluid monitoring or advanced material science. The long-term viability remains robust, driven by aging populations and the rising incidence of sports-related injuries globally. Investors should identify acquisition targets that offer complementary technologies or expand geographic reach into high-growth emerging markets. The adoption rate of smart disposables in high-volume orthopedic centers serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Smart Disposable with Real-time Pressure Monitoring | Enhances patient safety during complex procedures by preventing fluid extravasation. |
| Geographic Expansion: Penetration of Asia-Pacific Markets | Taps into rising healthcare infrastructure investment in China. |
| Regulatory Approval Pathway: Expedited FDA 510(k) Clearance | Accelerates market entry for innovative fluid management systems in the United States. |
| Strategic Partnership: Collaboration with Smart Pump Manufacturers | Ensures seamless integration and bundled sales opportunities with Stryker and Smith & Nephew. |
| Portfolio Diversification: Development of Small-Joint Arthroscopy Kits | Addresses underserved segments like wrist and ankle procedures, expanding market reach. |
Research Approach
Multi-period observation of market growth rates, technology adoption curves, and regulatory compliance trends anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing managers, ASC administrators, and medical device engineers. Secondary validation drew from FDA 510(k) clearances, EMA MDR compliance reports, medical device industry reports, and hospital procurement databases. This approach enabled robust bottom-up and top-down triangulation.
The segment-weighting approach informed the quantitative model, which integrated data across the analysis window to project market trajectories. Segmentation dimensions modeled included product type, application, end-user, distribution channel, and regional regulatory landscape. Compound Annual Growth Rates (CAGRs) were derived from historical data and projected market drivers, incorporating inputs such as the rising incidence of sports injuries and aging population demographics in Germany and Japan.
The model holds under current macroeconomic and regulatory conditions; deviation in raw material supply shocks or unforeseen regulatory changes would shift the forecast. Forecasts reflect assumptions regarding technological advancements and healthcare infrastructure investment. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
Specimen Containers Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Physiological Saline Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Surgical Gowns Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Anti Venom Market
Medical Supplies
Drosophila Bottles Market