
 Surgery Medical Bandage Market | 2026-2036
Surgery Medical Bandage Market Size, Share, and Industry Trends Forecast 2026-2036
Surgery Medical Bandage Market Analysis
Outpatient clinics is shifting toward higher-acuity procedures previously confined to hospital operating rooms, expanding demand for surgical-grade bandages in ambulatory settings. 3M leverages its materials science portfolio to dominate advanced adhesive platforms for post-operative wound closure. Johnson & Johnson sustains brand loyalty among surgeons through its Ethicon division's specialized sterile dressing lines. Medline Industries competes aggressively on contract pricing, securing group purchasing organization agreements that anchor volume across integrated delivery networks.
Surgery medical bandages encompass sterile, adhesive, or compression materials engineered to maintain moist wound environments, absorb exudate, and prevent microbial contamination, typically manufactured through non-woven fiber bonding, hydrocolloid gel casting, or foam polymerization processes with specified vapor transmission rates. Their primary purpose spans intraoperative site management through post-discharge healing support across acute and chronic wound pathways. Sterile dressings command margin concentration due to operating room compliance requirements and single-use protocols, while hydrocolloid materials capture growth from burn care applications where moisture retention accelerates re-epithelialization. Cotton-based products occupy mature demand in cost-sensitive hospital segments where commodity procurement prevails.
FDA 510(k) premarket notification requirements shape product development timelines and clinical evidence thresholds for antimicrobial claims, while ISO 13485 quality management standards govern manufacturing consistency across export-oriented suppliers. The EU Medical Device Regulation imposes stricter post-market surveillance obligations on bandage manufacturers seeking CE marking access. Stakeholders must monitor evolving sterilization validation requirements and biodegradability mandates as sustainability criteria penetrate healthcare procurement specifications.
Market Dynamics
Hospital consolidation across the United States is compressing vendor count and elevating technical compliance requirements for sterile dressing suppliers seeking integrated delivery network contracts.
Growth Catalysts
- FDA 510(k) pathway acceleration:Antimicrobial dressing developers gain faster market access through streamlined premarket notification reviews, reducing commercialization timelines for novel hydrocolloid and foam polymerization formulations.
- Ambulatory surgery center expansion:Outpatient clinics in the United States now perform higher-acuity procedures, generating surgical-grade bandage demand outside traditional hospital procurement channels.
- Moist wound healing protocols:Clinical adoption of evidence-based moisture-retention standards drives specification upgrades from cotton gauze to advanced vapor-transmission dressings in burn and post-operative care.
Market Restraints
- Raw material concentration:Medical-grade adhesive polymers and non-woven fiber supply chains cluster among specialty chemical producers in Germany and Japan, exposing converters to input volatility and allocation risk.
- Sterilization validation costs:Gamma and ethylene oxide sterilization facility qualification demands capital intensity that disadvantages mid-scale manufacturers seeking ISO 13485 certification for export markets.
- Commodity substitution pressure:Cost-sensitive hospital segments in developing markets retain cotton-based dressing procurement, limiting premium product penetration where procurement prioritizes unit economics over clinical outcomes.
Strategic Opportunities
- Sustainability mandate alignment:EU Medical Device Regulation biodegradability criteria and CSRD reporting requirements create first-mover advantage for suppliers developing compostable fiber bonding processes and reduced-packaging sterile delivery systems.
- Home care channel development:Post-discharge wound management shifts toward patient-directed application, opening direct-to-clinic and retail pharmacy distribution for simplified adhesive platforms with intuitive application design.
- Antimicrobial silver integration:Convergence of ionic silver release technology with flexible foam substrates addresses surgical site infection prevention protocols in orthopedic and cardiovascular procedure suites.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization study capacity constraints at contract research organizations extend product development timelines for novel hydrocolloid gel formulations.
- Legacy ERP integration:Hospital group purchasing organization e-procurement platforms require EDI compliance and real-time inventory visibility that strain smaller manufacturers' information technology infrastructure.
- Cross-border registration complexity:Divergent sterilization documentation requirements between FDA 510(k) submissions and CE marking technical files demand redundant quality management system maintenance for dual-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgery Medical Bandage Market |
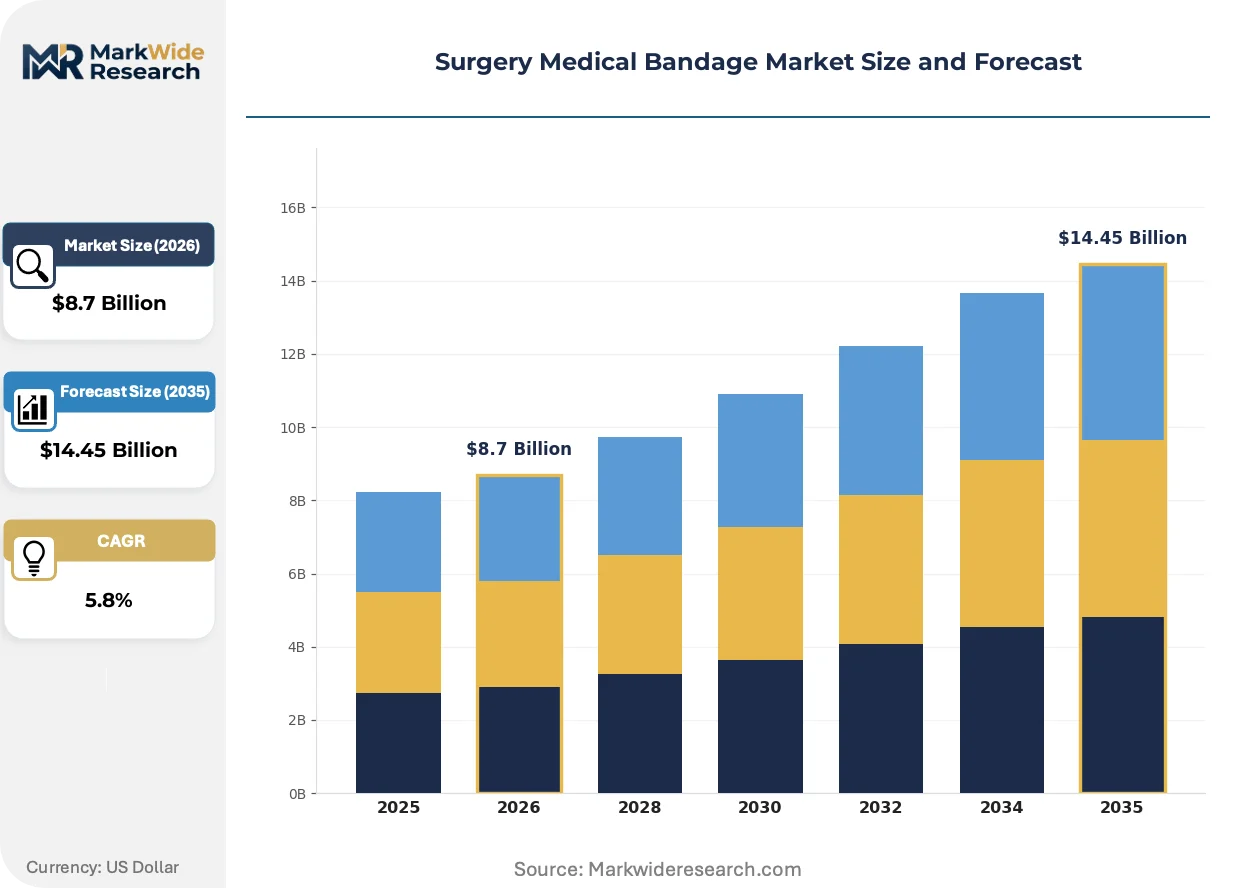
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Bandages, Sterile Dressings, Compression Bandages, Non-Adherent Pads End User: Hospitals, Outpatient Clinics, Home Healthcare, Emergency Services Material: Cotton, Polyester, Foam, Hydrocolloid Application: Surgical Wounds, Burn Care, Chronic Wounds, Traumatic Injuries |
| Companies Covered | 3M, Johnson & Johnson, Cardinal Health, Smith & Nephew, Mölnlycke Health Care, Medline Industries, B. Braun Melsungen, McKesson Corporation, ConvaTec Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgery Medical Bandage Market Emerging Trajectories
Materials science convergence with digital health monitoring is redefining surgical dressing functionality beyond passive wound coverage toward active healing management and remote patient surveillance.
Silicone adhesive technology is consolidating market position in post-operative applications where gentle removal preserves periwound skin integrity across repeated dressing changes. Outpatient surgery centers in the United States specify soft silicone border dressings for ambulatory procedures with short recovery windows. This material transition is consolidating procurement specifications around vapor-permeable platforms that reduce maceration risk compared to traditional acrylic adhesives.
EU Medical Device Regulation post-market surveillance obligations now require systematic clinical follow-up data collection for antimicrobial claims, elevating evidence generation costs for CE marking maintenance. Manufacturers must establish vigilance systems tracking adverse events across distributed hospital networks. High-risk wound dressing categories face expanded notified body audit frequency, compressing competitive timelines for smaller suppliers lacking dedicated regulatory affairs functions.
Centralized purchasing through group purchasing organizations now dominates United States hospital supply acquisition, consolidating vendor relationships around multi-year sole-source agreements. Independent ambulatory surgery centers increasingly affiliate with integrated delivery networks to access contract pricing, displacing fragmented spot-buying patterns. This concentration is most visible in metropolitan health systems where three to five IDNs control regional surgical volume and standardize dressing formularies across owned and affiliated facilities.
Surgery Medical Bandage Market Segmentation
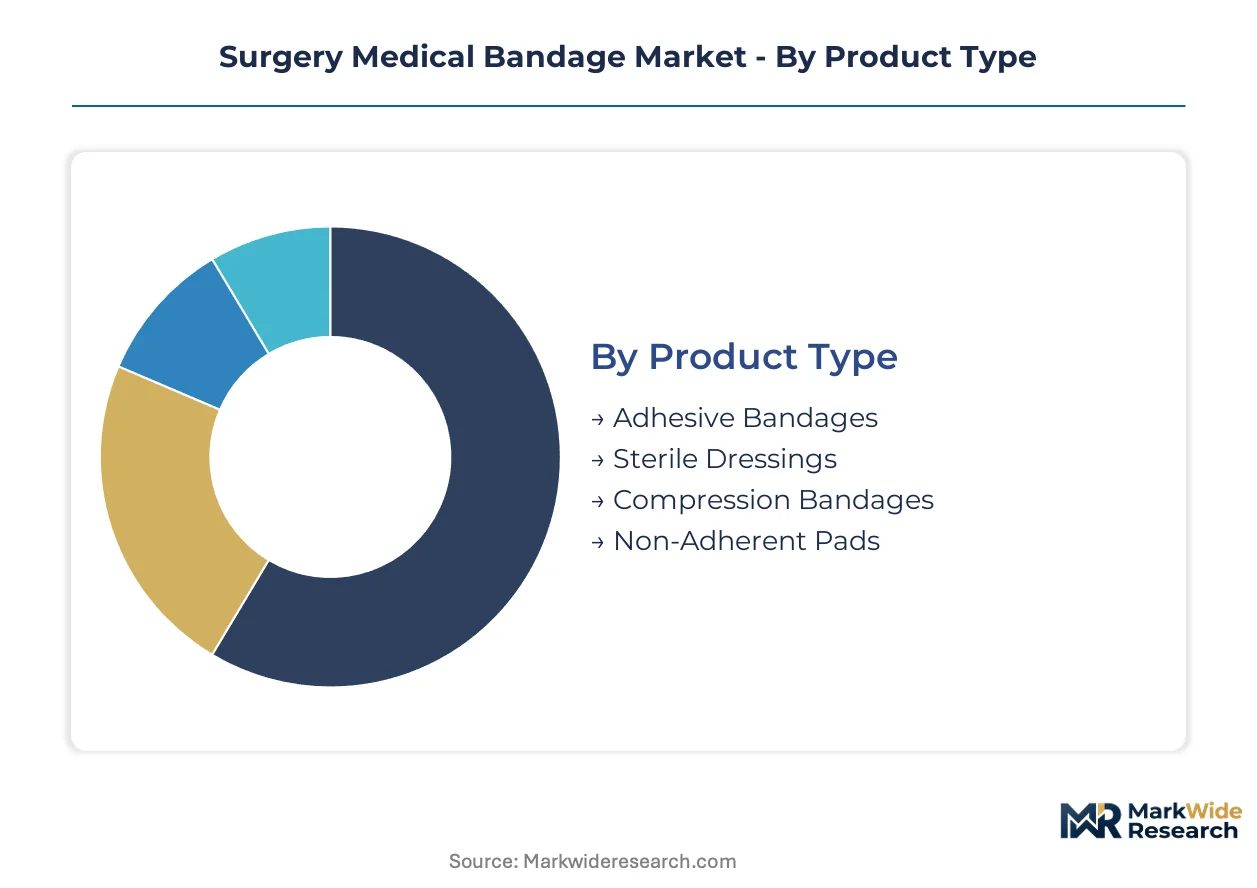
Surgical bandage procurement splits across multiple technical and commercial dimensions. Each segmentation axis reveals distinct margin profiles, regulatory pathways, and competitive dynamics that shape supplier strategy.
Product Type:
Capital intensity concentrates in sterile dressing manufacturing, where gamma sterilization infrastructure and cleanroom assembly demand seven-figure facility investments.
- Sterile Dressings:Non-woven fiber bonding and ethylene oxide terminal sterilization create barrier-to-entry economics. United States hospital operating rooms specify these for all invasive procedures, with procurement consolidating through integrated delivery network sole-source contracts.
- Adhesive Bandages:Medical-grade acrylic and silicone adhesive coating lines require precision slot-die equipment. Ambulatory surgery centers in the United States specify soft silicone variants for post-operative discharge kits where gentle removal preserves skin integrity.
- Compression Bandages:Elastic yarn knitting and graduated compression calibration dominate production costs. Germany and Japan specialty textile houses supply medical-grade elastane feedstock.
- Non-Adherent Pads:Petroleum-impregnated or silicone-coated mesh fabrication requires lower capital thresholds than adhesive platforms. Cost-sensitive hospital segments retain these for donor site coverage.
Most installed capacity flows through Sterile Dressings. Expansion is steepest in Adhesive Bandages.
End User:
Procurement authority concentrates in hospital supply chains, where group purchasing organization contracts lock multi-year volume commitments.
- Hospitals:Centralized sterile processing departments enforce vapor transmission rate specifications and bioburden limits. FDA 510(k) clearance documentation anchors vendor qualification.
- Outpatient Clinics:Ambulatory surgery centers perform higher-acuity procedures previously confined to inpatient settings. These facilities prioritize compact packaging and intuitive application for nursing staff with lower wound care specialization.
- Home Healthcare:Patient-directed application demands simplified adhesive platforms with extended wear time. Retail pharmacy and direct-to-clinic distribution channels bypass traditional hospital supply intermediaries.
- Emergency Services:Pre-hospital trauma care requires rapid-application compression and hemostatic functionality. Military and tactical medicine procurement drives specifications for extreme environment stability.
Volume concentration remains in Hospitals. Home Healthcare is gaining share fastest as post-discharge wound management shifts outside institutional settings.
Material:
Raw material sourcing geography shapes supply security, with medical-grade polymer supply chains clustering in German and Japanese specialty chemical producers.
- Hydrocolloid:Gelatin, pectin, and carboxymethyl cellulose casting into polyurethane backings demands precise moisture vapor transmission calibration. Burn care units specify these for re-epithelialization acceleration where moisture retention outperforms dry gauze protocols.
- Foam:Polyurethane polymerization with controlled porosity enables high exudate absorption. Post-operative orthopedic suites favor foam substrates for seroma management.
- Cotton:Commodity gauze weaving occupies mature demand in cost-sensitive procurement segments. Developing market hospitals retain cotton where unit economics dominate clinical outcome metrics.
- Polyester:Synthetic non-woven thermal bonding offers tear resistance and dimensional stability. Compression applications specify polyester for sustained pressure maintenance.
Most installed capacity flows through Cotton. Expansion is steepest in Hydrocolloid.
Application:
Clinical evidence requirements intensify with wound severity, elevating regulatory scrutiny and reimbursement complexity.
- Surgical Wounds:Sterile barrier maintenance and antimicrobial integration address surgical site infection prevention protocols. Orthopedic and cardiovascular procedure suites specify ionic silver-releasing dressings.
- Burn Care:Moist wound healing standards drive hydrocolloid and hydrogel specification. United States burn centers prioritize vapor-permeable platforms that reduce maceration risk.
- Chronic Wounds:Diabetic foot ulcer and pressure injury management extends dressing wear time requirements. Home healthcare channels capture volume as debridement and dressing changes shift outside hospitals.
- Traumatic Injuries:Emergency department and field medicine applications demand rapid hemostasis and contamination control. Military procurement specifications drive extreme environment performance standards.
Most installed capacity flows through Surgical Wounds. Burn Care is climbing the fastest as moisture-retention protocols displace traditional dry dressing approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing manufacturing capacity toward jurisdictions with streamlined sterilization validation pathways and lower cost-of-compliance structures. Producers migrate operations to exploit gaps between FDA 510(k) documentation burdens and EU MDR surveillance obligations.
United States
Hospital consolidation into integrated delivery networks concentrates procurement authority among three to five regional systems per metropolitan area. FDA 510(k) clearance documentation anchors vendor qualification for sterile dressing suppliers. Minneapolis-St. Paul hosts dense clusters of medical device engineering talent serving adhesive platform development.
Germany
Specialty chemical producers in the Rhine-Ruhr and Bavaria supply medical-grade adhesive polymers and non-woven fiber feedstock to global converters. EU Medical Device Regulation post-market surveillance obligations elevate evidence generation costs for CE marking maintenance. Freiburg and Tübingen medical technology corridors drive hydrocolloid gel casting innovation.
China
Domestic wound care demand expands as hospital infrastructure upgrades accelerate in second-tier cities. NMPA regulatory harmonization with ISO 13485 standards streamlines export qualification for qualified manufacturers. Suzhou and Shenzhen industrial parks concentrate cleanroom assembly capacity for sterile dressing production.
Japan
Aging demographics expand chronic wound management volume through home healthcare channels. PMDA quality management requirements align with MHLW reimbursement standards for advanced moisture-retention dressings. Osaka-Kobe manufacturing belt specializes in precision polymerization equipment for foam substrate production.
India
Cost-sensitive hospital segments sustain cotton-based dressing demand alongside gradual premium product adoption in tertiary care centers. CDSCO medical device rules impose sterilization facility registration requirements on domestic manufacturers. Ahmedabad and Mumbai pharmaceutical clusters diversify into wound care contract manufacturing.
Surgery Medical Bandage Market Vendor Landscape
Strategic partnerships dominate the current landscape as suppliers seek to bridge capability gaps in materials science and regulatory affairs. Market structure concentrates around diversified healthcare conglomerates with captive sterilization infrastructure and specialized wound care pure-plays with clinical evidence depth. Three archetypes prevail: adhesive technology specialists leveraging materials science portfolios, contract manufacturing organizations securing group purchasing organization volume, and antimicrobial platform developers pursuing 510(k) pathway acceleration. Geographic expansion and portfolio diversification constitute the dominant competitive vectors as vendors pursue integrated delivery network sole-source agreements.
Among diversified healthcare conglomerates, 3M and Johnson & Johnson exemplify the materials-science-to-clinical-application archetype, anchoring premium-tier positioning through sterile processing compliance depth. Medline Industries occupies the contract-scale vector, representing aggressive group purchasing organization pricing strategy. Smith & Nephew and Mölnlycke Health Care sit within the specialized wound care tier, exemplifying clinical evidence generation focus for moisture-retention platform adoption.
| Leading Market Players |
|---|
| 3M |
| Johnson & Johnson |
| Cardinal Health |
| Smith & Nephew |
| Mölnlycke Health Care |
| Medline Industries |
| B. Braun Melsungen |
| McKesson Corporation |
| ConvaTec Group |
| Others |
Supply Flow & Price Mechanics
Medical-grade cotton futures and specialty polymer feedstock indices cascade through converter economics into stratified pricing tiers, with hydrocolloid gel casting commanding premium positioning against commodity gauze procurement in cost-sensitive hospital segments.
Pricing Analysis
Distributor margins on sterile dressing systems absorb gamma sterilization facility qualification costs before hospital group purchasing organization contract pricing. Three-tier pricing structure across premium, standard, and economy levels separates vapor-transmission calibrated platforms from cotton-based alternatives, with FDA 510(k) clearance tier anchoring the premium band. Cost compression in the economy tier intensifies because integrated delivery network volume concentration squeezes mid-scale manufacturers. Ambulatory surgery centers exhibit highest price sensitivity, while orthopedic procedure suites demonstrate lowest sensitivity due to surgical site infection prevention protocol mandates.
Supply Chain Analysis
ISO 13485 certification and FDA facility registration requirements gate sterile dressing manufacturing capacity, concentrating qualified production in Germany, Japan, and the United States. Medical-grade adhesive polymers, non-woven fiber feedstock, and ethylene oxide sterilization services draw from specialty chemical producers in the Rhine-Ruhr and Osaka-Kobe belts. Single-source vulnerability clusters around gamma sterilization facility capacity, where limited qualified sites create allocation risk during demand surges. Distribution runs through group purchasing organization e-procurement platforms requiring EDI compliance and real-time inventory visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU Medical Device Regulation post-market surveillance obligations and FDA 510(k) pathway acceleration collectively elevating evidence-generation costs and accelerating commercialization timelines for compliant suppliers.
For Market Incumbents: Lock in integrated delivery network sole-source agreements through multi-year sterile processing compliance guarantees and captive gamma sterilization infrastructure. Capacity addition in the Minneapolis-St. Paul medical device engineering corridor secures adhesive platform development talent pools against emerging materials science specialists.
For New Entrants and Emerging Players: Independent ambulatory surgery centers outside metropolitan IDN affiliation represent underserved buyer archetypes with fragmented spot-buying patterns and lower wound care specialization requirements. Home healthcare channels with patient-directed application needs offer penetrable white-space, with simplified silicone adhesive platforms and intuitive application design as the go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized wound care pure-plays possessing clinical evidence depth for moisture-retention platform adoption and dedicated regulatory affairs functions for dual-market FDA and CE marking maintenance. Acquisition target archetypes include antimicrobial silver integration developers with 510(k) pathway momentum. The signal to watch is hospital consolidation velocity in United States metropolitan markets, as three-to-five IDN control thresholds accelerate vendor count compression.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification reviews compress commercialization timelines for novel hydrocolloid formulations. |
| CE Marking Pathway Investment | EU MDR post-market surveillance compliance secures access to German specialty chemical feedstock markets. |
| Hospital System Partnership | Integrated delivery network sole-source agreements anchor volume across owned and affiliated surgical facilities. |
| Sustainability Certification Program | Biodegradability criteria alignment with CSRD reporting requirements creates first-mover procurement advantage. |
| Antimicrobial Silver Platform Development | Ionic silver release technology integration addresses orthopedic surgical site infection prevention protocols. |
Methodological Framework
Multiple input streams — hospital procurement database analysis, GPO contract documentation review, and regulatory filing examination — were reconciled against primary interviews with sterile processing directors, biomedical engineers, GPO contracts managers, and adhesive platform R&D leads. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body technical file summaries, hospital supply chain expenditure reports, and ISO certification registry data. Bottom-up segment sizing and top-down market reconciliation triangulated volume estimates.
Historical shipment data cross-referenced against expert panel input on ambulatory surgery center expansion rates and moisture wound healing protocol adoption curves shaped the analytical framework across the modeling period. Product type, material composition, end-user channel, and application severity segmentation dimensions were modeled independently. CAGRs were derived from slope consensus across input streams, with raw material price index trajectories and sterilization facility capacity expansion schedules as industry-specific forecast inputs.
Inputs from hospital procurement databases and regulatory filing repositories were available through the study window; gaps in real-time ambulatory surgery center spot-buying transaction data introduce uncertainty bands in the outpatient clinic segment sizing. Forecasts reflect documented assumptions on IDN consolidation velocity and EU MDR audit frequency escalation. A model refresh is warranted upon material change in FDA 510(k) review timeline guidance or gamma sterilization facility capacity allocation protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Closure Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Surgical Wound Care Market
Wound Care
Belgium and Netherlands Advanced Wound Care Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Wound Skin Care Market
Wound Care
Global Compression Bandages Market
Wound Care
Bioactive Wound Management Market
Wound Care
LAMEA Surgical Dressing Market