
 United States Minimally Invasive Surgery Market | 2026-2036
United States Minimally Invasive Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Minimally Invasive Surgery Market Intelligence
Hospital supply chain consolidation is reshaping procurement dynamics for minimally invasive surgery platforms. Intuitive Surgical leverages direct-to-institution sales teams to sustain premium placement of robotic systems in academic medical centers. Medtronic competes through broad laparoscopic portfolios that anchor contracts with integrated delivery networks. Stryker Corporation differentiates via specialized visualization and powered instrumentation that occupies distinct procedural niches.
Minimally invasive surgery encompasses operative techniques performed through small incisions using specialized instruments, camera systems, and energy devices that reduce tissue trauma and recovery time compared with open approaches; robotic teleoperated systems integrate haptic feedback and 3D visualization to enable sub-millimeter precision in confined anatomical spaces. Robotic systems command the highest capital investment and service revenue pools among product categories, while ambulatory surgical centers represent the fastest-growing end user segment as same-day discharge protocols expand across gastroenterology and urology applications. Imaging technologies underpin procedure safety and outcomes documentation, creating durable demand for integrated hardware-software platforms.
FDA 510(k) clearance requirements and CMS national coverage determinations shape device development priorities and reimbursement access for manufacturers targeting the United States market. OSHA workplace safety standards and state-level certificate-of-need regulations further influence capital equipment deployment timelines in hospital and outpatient settings. Stakeholders must monitor evolving FDA guidance on autonomous surgical functions and parallel CMS technology add-on payment rulings that will determine next-generation platform economics.
Market Dynamics
CMS technology add-on payments and FDA breakthrough device designations are accelerating capital deployment toward autonomous surgical platforms, while hospital system consolidation compresses vendor negotiation cycles across integrated delivery networks.
Growth Catalysts
- CMS Reimbursement Expansion:Ambulatory surgical centers in Texas and Florida now qualify for enhanced facility fees under revised Medicare payment schedules, accelerating same-day robotic procedure volumes.
- Surgeon Training Pipeline:Residency programs at academic medical centers in California have standardized robotic certification curricula, expanding qualified operator pools faster than equipment deployment.
- Energy Device Innovation:Advanced bipolar and ultrasonic sealing technologies reduce operative time in confined anatomical spaces, directly lowering per-procedure costs for hospital systems.
Market Restraints
- Capital Equipment Concentration:Single-source dependency for robotic system maintenance contracts limits pricing leverage for mid-sized hospitals in the Midwest.
- Certificate-of-Need Friction:State-level CON regulations in New York and Illinois delay surgical suite expansion timelines by 18-24 months despite demonstrated demand.
- Disposable Instrument Costs:Per-procedure consumables for robotic platforms command premium pricing that compresses margins for outpatient facilities operating under bundled payment models.
Strategic Opportunities
- Rural Hospital Access:Telepresence surgical systems enable metropolitan specialists to perform complex procedures at community hospitals across Montana and Wyoming without patient transfer.
- Veterans Health Administration Modernization:VA hospital reconstruction mandates create dedicated procurement channels for next-generation visualization and instrumentation platforms.
- AI-Assisted Preoperative Planning:Integration of machine learning algorithms with imaging archives is reducing operative time variability and enabling procedure standardization across multi-site health systems.
Industry Challenges
- Robotic Credentialing Complexity:Hospital privileging committees lack standardized frameworks for assessing surgeon competence on evolving platform generations, creating liability exposure.
- Interoperability Fragmentation:Proprietary data formats between imaging systems, robotic consoles, and electronic health records force costly middleware investments.
- Supply Chain Reconfiguration:Sterile processing departments struggle to accommodate specialized instrument trays that differ materially from conventional laparoscopic sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Minimally Invasive Surgery Market |
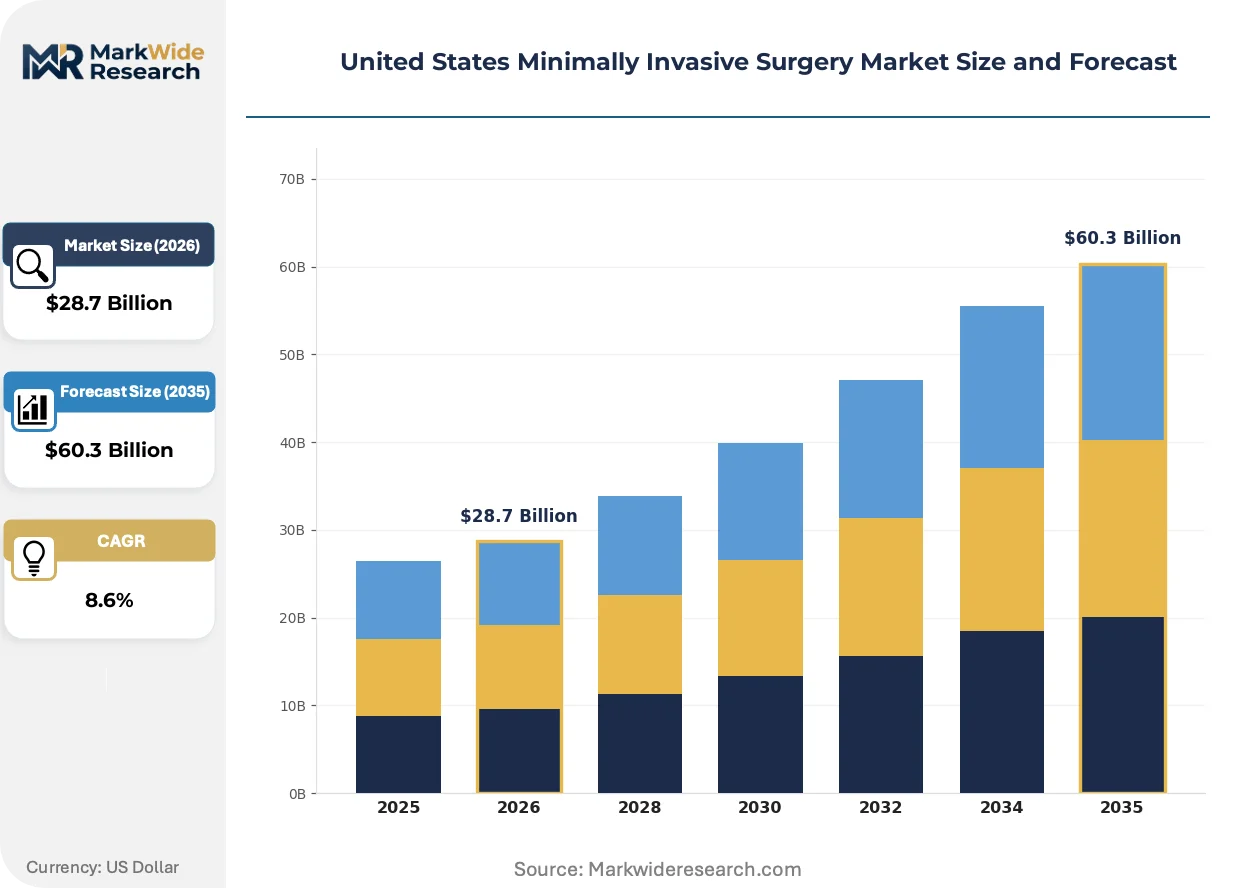
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $60.3 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopic Instruments, Robotic Systems, Endoscopic Devices, Visualization Systems Application: Gastroenterology, Urology, Gynecology, Cardiology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Outpatient Facilities Technology: Teleoperated Systems, Imaging Technologies, Energy-based Devices, Software Solutions |
| Companies Covered | Intuitive Surgical, Zimmer Biomet, Medtronic, Siemens Healthineers AG, Abbott Laboratories, Johnson & Johnson, Boston Scientific Corporation, GE HealthCare, Stryker Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Minimally Invasive Surgery Market Strategic Shifts & Innovations
Surgical simulation and remote proctoring platforms are dissolving geographic barriers to expertise distribution, while regulatory frameworks race to accommodate autonomous function claims without compromising safety verification standards.
Digital surgical planning software is virtualizing preoperative workflow across academic medical centers in California and Texas. Hospital systems deploy cloud-based anatomical modeling to rehearse complex cases before entering the operating room. This capability is compressing operative time variance and reducing conversion rates to open procedures.
FDA draft guidance on autonomous surgical devices is reshaping 510(k) submission requirements for manufacturers seeking marketing authorization. The agency's emphasis on real-world performance monitoring extends post-market surveillance obligations. Robotic system developers are responding by embedding continuous data transmission capabilities into next-generation consoles.
Health system procurement departments are consolidating vendor relationships through multi-year enterprise agreements that bundle capital equipment, disposables, and service contracts. Integrated delivery networks in Florida and Ohio negotiate these arrangements to standardize instrumentation across affiliated facilities. This concentration transfers pricing power from manufacturers to large buyers with volume leverage.
United States Minimally Invasive Surgery Market Segmentation
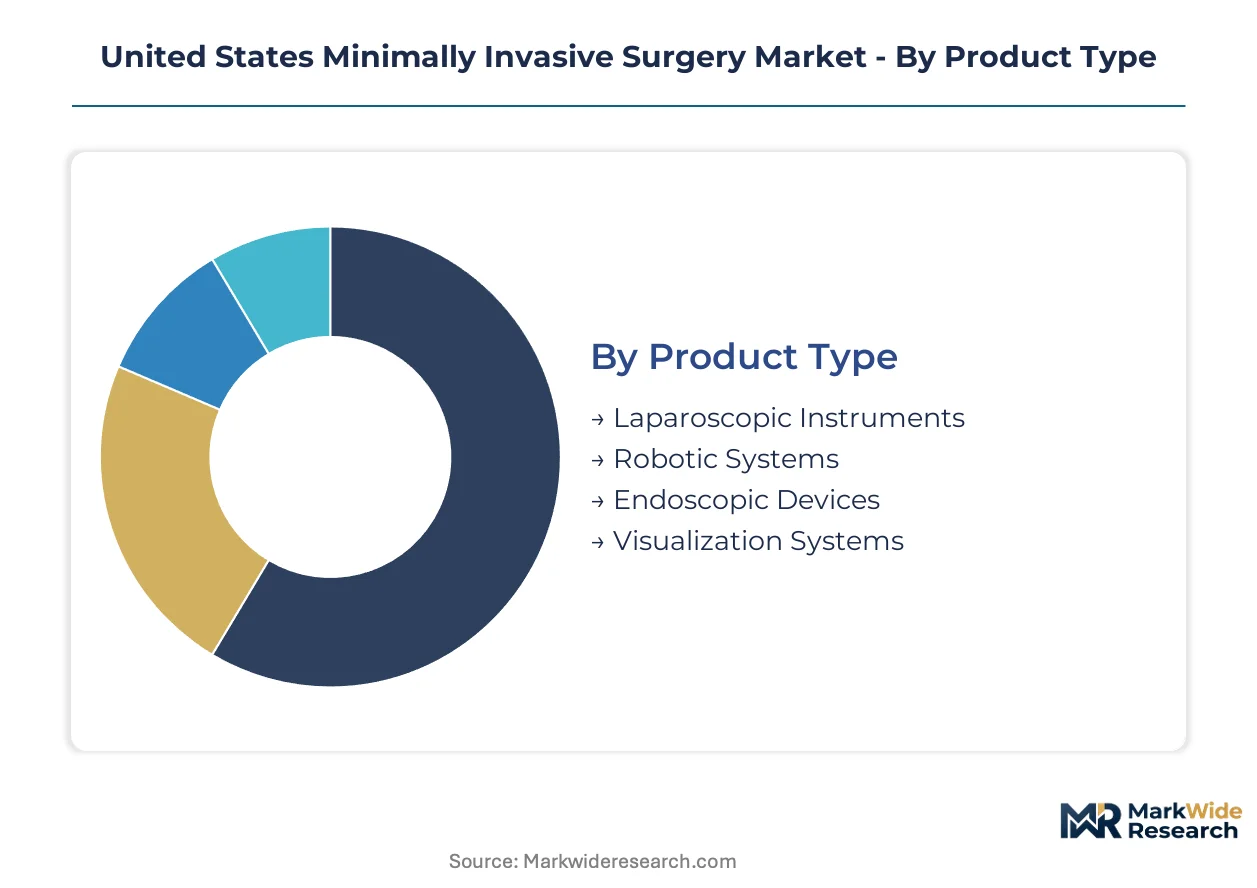
Product architecture in the United States minimally invasive surgery market determines capital allocation cycles and procurement negotiation leverage. Surgeons select platforms based on procedural volume, anatomical complexity, and institutional reimbursement contracts.
Product Type:
Cost tier stratification separates capital-intensive robotic installations from disposable instrument portfolios that anchor recurring revenue streams.
- Robotic Systems:Teleoperated consoles integrate haptic feedback with 3D visualization for sub-millimeter precision. Academic medical centers in California and Texas concentrate procurement of these platforms to attract fellowship-trained surgeons and complex case referrals.
- Laparoscopic Instruments:Handheld graspers, dissectors, and scissors constitute the procedural workhorse across general surgery departments. Midwest hospital systems leverage these familiar toolsets to maintain surgical throughput without capital expansion.
- Endoscopic Devices:Flexible scopes with integrated biopsy channels serve diagnostic and therapeutic gastroenterology applications.
- Visualization Systems:4K and fluorescence-capable displays enable real-time tissue perfusion assessment during oncologic resections.
Robotic Systems hold installed capacity. Laparoscopic Instruments is rotating up the share rankings.
Application:
Procedure volume and reimbursement rates concentrate demand within specific anatomical domains that reward precision instrumentation.
- Gastroenterology:Colorectal resections and bariatric procedures generate high robotic utilization rates. Ambulatory surgical centers in Florida are expanding same-day sleeve gastrectomy protocols under revised Medicare facility fee schedules.
- Urology:Radical prostatectomy and partial nephrectomy established robotic surgery's clinical value proposition. Residency programs now mandate console certification for graduating urology residents.
- Gynecology:Hysterectomy and myomectomy applications compete with vaginal approaches on cost-efficiency grounds.
- Cardiology:Structural heart interventions and electrophysiology ablations demand specialized catheter-based platforms distinct from abdominal surgery toolsets.
Gastroenterology commands procedure volume concentration. Urology is climbing the fastest on per-case revenue metrics.
End User:
Customer type determines purchasing authority structure and service contract negotiation complexity across the care continuum.
- Hospitals:Integrated delivery networks consolidate capital equipment decisions through centralized value analysis committees. Texas and Florida health systems bundle robotic system acquisitions with multi-year disposable supply agreements.
- Ambulatory Surgical Centers:Freestanding facilities in certificate-of-need states face regulatory barriers to surgical suite expansion. Where permitted, these centers prioritize instrument platforms that minimize sterile processing overhead.
- Specialty Clinics:Gynecology and urology-focused practices concentrate high-volume elective procedures outside hospital cost structures.
- Outpatient Facilities:Hospital-owned satellite locations extend academic medical center brand reach into suburban markets.
Hospitals retain procurement authority concentration. Ambulatory Surgical Centers is gaining share fastest on same-day discharge protocol expansion.
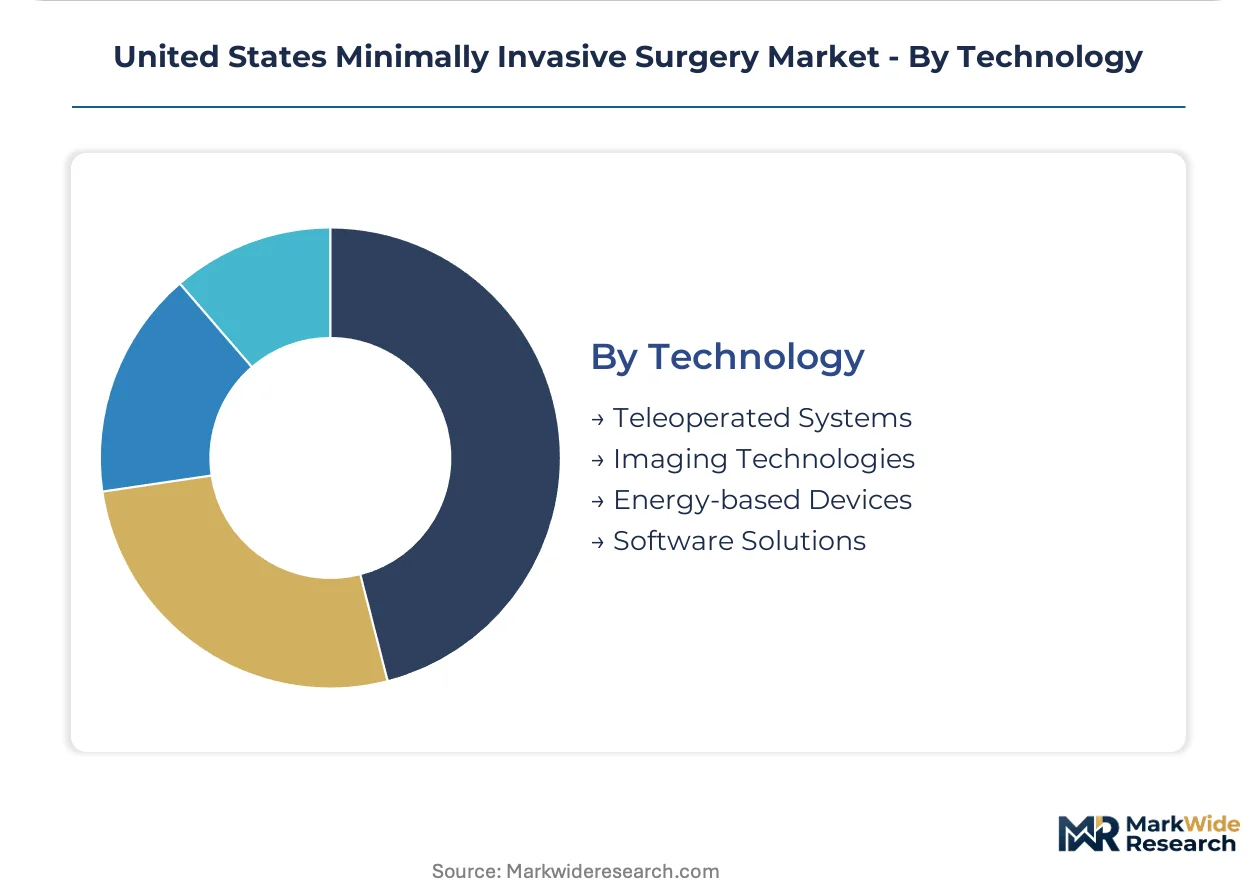
Technology:
Technology maturity separates proven platforms from emerging modalities seeking FDA 510(k) clearance and CMS coverage determination.
- Teleoperated Systems:Master-slave robotic architectures with FDA-cleared indications span multiple surgical specialties. Intuitive Surgical's da Vinci platform dominates installed base metrics across academic medical centers.
- Energy-based Devices:Advanced bipolar and ultrasonic sealing technologies reduce operative time and blood loss. These instruments command premium pricing that compresses margins under bundled payment models.
- Imaging Technologies:Intraoperative fluorescence and augmented reality overlays enable real-time anatomical navigation.
- Software Solutions:Preoperative planning algorithms and postoperative analytics platforms create recurring subscription revenue opportunities.
Teleoperated Systems anchor capital deployment. Energy-based Devices is rotating up the share rankings on per-procedure economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California health systems command premium pricing power for robotic platform placements, while Midwest hospital networks extract deeper discounts on laparoscopic instrument bundles through volume consolidation strategies.
California
Academic medical centers in Los Angeles and San Francisco drive demand for next-generation visualization systems and AI-assisted surgical planning tools. FDA breakthrough device designations accelerate commercialization timelines for manufacturers targeting West Coast institutions. The Stanford-San Francisco corridor concentrates venture capital investment in surgical robotics startups seeking clinical validation partnerships.
Texas
Integrated delivery networks in Dallas-Fort Worth and Houston bundle robotic system acquisitions with multi-year disposable supply agreements. CMS enhanced facility fee schedules for ambulatory surgical centers accelerate same-day procedure volumes across the state. The Texas Medical Center in Houston anchors one of the highest-density clusters of robotic surgical suites in the nation.
Florida
Ambulatory surgical centers in Miami and Tampa expand same-day bariatric and urologic procedure protocols under favorable Medicare reimbursement frameworks. State regulatory flexibility enables faster surgical suite expansion compared to certificate-of-need jurisdictions. The Orlando-Tampa corridor attracts private equity investment in outpatient surgical facility networks.
Illinois
Certificate-of-need regulations delay surgical suite expansion timelines by 18-24 months in Chicago despite demonstrated demand for robotic platforms. Midwest hospital systems leverage laparoscopic instrument standardization to maintain surgical throughput without capital expansion. The Illinois Medical District concentrates academic research on energy-based sealing technologies.
New York
CON restrictions in New York City limit ambulatory surgical center penetration compared to Sun Belt states, funneling complex procedures into hospital-based settings. Academic medical centers in Manhattan prioritize telepresence surgical systems for rural outreach programs. The Buffalo-Rochester corridor develops sterile processing infrastructure for specialized robotic instrument trays.
United States Minimally Invasive Surgery Market Key Industry Players
Robotic platform specialists and diversified instrument manufacturers split the market into distinct competitive spheres with limited direct overlap. Intuitive Surgical anchors the capital-intensive teleoperated systems segment through direct-to-institution sales teams. Medtronic and Stryker compete for integrated delivery network contracts with broad laparoscopic and powered instrumentation portfolios. Strategic moves concentrate on multi-year enterprise agreements bundling equipment, disposables, and service contracts.
Within the diversified instrumentation tier, Medtronic and Stryker occupy positions defined by breadth of surgical application coverage and supply chain integration depth. Intuitive Surgical exemplifies the robotic pure-play archetype with premium system placement strategies in academic medical centers. Zimmer Biomet sits within the orthopedic crossover segment, leveraging joint reconstruction expertise into adjacent minimally invasive applications.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Zimmer Biomet |
| Medtronic |
| Siemens Healthineers AG |
| Abbott Laboratories |
| Johnson & Johnson |
| Boston Scientific Corporation |
| GE HealthCare |
| Stryker Corporation |
| Others |
Cost & Logistics Intelligence
German precision optics manufacturers and Japanese sensor fabricators anchor the upstream tier for visualization and haptic feedback components, concentrating margin capture in the hands of specialized component suppliers while system integrators compete on bundled service contracts downstream.
Pricing Analysis
Configured-to-order robotic console pricing commands substantial premiums over standard laparoscopic instrument bundles. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and after-sales service bundling. Cost compression in disposable instrument lines is intensifying because ambulatory surgical centers negotiate volume commitments under bundled Medicare payment models. Mid-sized Midwest hospitals exhibit highest price sensitivity due to capital constraint, while academic medical centers in California and Texas absorb premium positioning for talent recruitment.
Supply Chain Analysis
Export-control restrictions on advanced imaging sensors and precision motion-control components limit component flows from designated technology jurisdictions. Manufacturing concentration rests on Germany and Japan for optical subsystems, with sterile disposable production anchored in Mexico and Costa Rica. Single-source vulnerability pervades robotic arm actuator supply due to specialized metallurgy requirements. Distribution runs through integrated delivery network procurement committees that consolidate multi-hospital purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switching costs embedded in surgeon training pathways and institutional credentialing frameworks create durable defensive moats for established platform providers.
For Market Incumbents: Build regulatory entrenchment through FDA breakthrough device designations that extend data exclusivity periods. Deepen backward integration into energy-sealing instrument manufacturing to capture per-procedure margin pools. Emerging telepresence surgical platforms threaten geographic market fragmentation. Prioritize certification investment in AI-assisted preoperative planning modules to anchor software subscription revenue. For New Entrants and Emerging Players: Rural hospital networks in Montana and Wyoming present underpenetration opportunity for telepresence-enabled procedure access. Veterans Health Administration reconstruction mandates offer dedicated procurement channels insulated from commercial pricing pressure. Target ambulatory surgical center instrumentation platforms that minimize sterile processing overhead as the most penetrable segment. Pursue GPO contract penetration through disposable instrument standardization rather than capital equipment displacement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outpatient facility networks in Florida and Texas seeking platform standardization across acquired locations. Five-to-ten year viability hinges on reimbursement durability under Medicare facility fee schedules. Acquisition targets should demonstrate installed base density with multi-year disposable supply agreements. Watch for CMS technology add-on payment rulings on autonomous surgical functions as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) clearance for energy-based sealing devices unlocks Medicare reimbursement at ambulatory surgical centers. |
| Hospital System Partnership | Multi-year enterprise agreements with Texas integrated delivery networks standardize instrumentation across affiliated facilities. |
| Software Companion Development | AI-assisted preoperative planning modules reduce operative time variance for complex oncologic resections. |
| Reimbursement Strategy | CMS technology add-on payment qualification accelerates capital deployment toward autonomous surgical platforms. |
| CE Marking Pathway | European regulatory approval enables cross-border clinical validation partnerships with German academic medical centers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with robotic surgery program directors, hospital value analysis committee members, GPO contracts managers, and biomedical engineering leads. Secondary validation drew from FDA 510(k) clearance databases, CMS national coverage determination records, hospital procurement databases, and ambulatory surgical center Medicare cost report filings. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data.
Calibration anchored forward projections to historical adoption curves for teleoperated surgical platforms across academic medical centers and community hospital tiers. Segmentation modeling spanned product architecture, procedural application, end-user facility type, and technology maturity tier. CAGRs were derived from regression analysis of installed base expansion correlated with surgeon training pipeline output and reimbursement schedule revisions. Forecast inputs incorporated certificate-of-need regulatory friction indices and ambulatory surgical center licensing velocity by state.
The forecast holds incumbent behavior within observed patterns; aggressive moves by autonomous surgical device developers or telepresence platform specialists would shift outcomes. Material shifts in FDA guidance on real-world performance monitoring or CMS bundled payment model restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
Robotic Surgery Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Equine Surgical Equipment Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Surgical Snare Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Endoscopic Spinal Surgery Market