
 Blood Processing Disposables Market | 2026-2036
Blood Processing Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Processing Disposables Market Outlook
Hospital procurement consolidation is expanding across integrated delivery networks in North America and Western Europe, concentrating purchasing power among fewer buyers. Fresenius Kabi leverages its vertically integrated plasma supply chain to anchor European hospital contracts. Terumo Corporation dominates Asia-Pacific blood bag supply through manufacturing scale in Japan and Thailand. Haemonetics Corporation specializes in automated collection systems that compete on workflow integration rather than commodity pricing.
Blood processing disposables comprise single-use medical devices engineered from medical-grade polymers for the collection, separation, storage, and transfusion of human blood and blood components. These products must meet biocompatibility standards including hemolysis resistance below 5% and endotoxin limits of 0.5 EU per milliliter to ensure patient safety during therapeutic procedures. Blood bags manufactured from plasticized polyvinyl chloride sustain the largest revenue pool due to universal transfusion protocol requirements, while platelet storage containers represent the fastest-expanding category as apheresis procedures displace whole-blood-derived platelet concentrates in developed markets. Hemoconcentrators occupy a specialized margin niche serving cardiac surgery centers where intraoperative autotransfusion demand is rising.
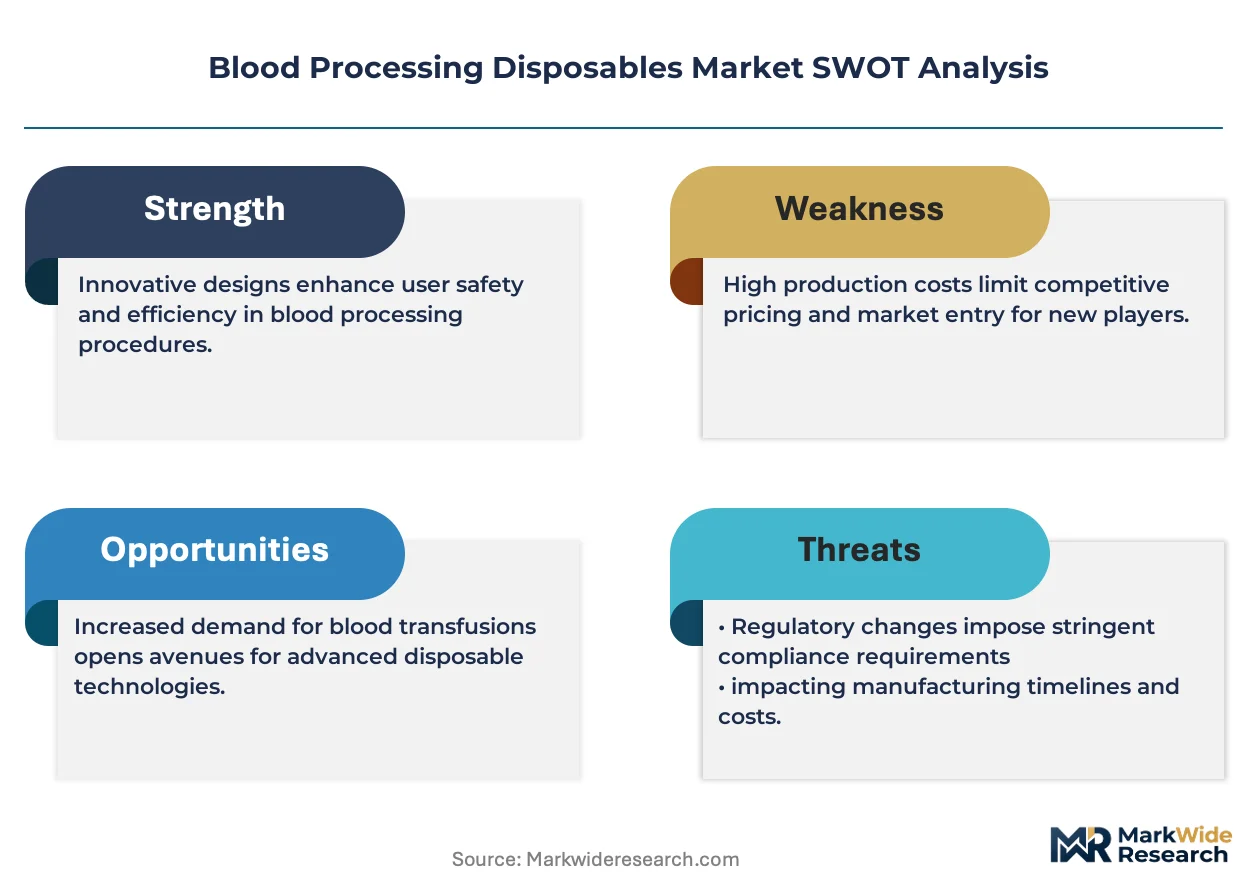
FDA 21 CFR Part 820 quality system regulations and EMA Medical Device Regulation standards enforce material traceability and sterilization validation that elevate compliance costs for new market entrants. ISO 3826 specifications for collapsible plastic containers for human blood and blood components govern dimensional stability and optical clarity requirements that directly shape polymer formulation decisions by manufacturers. Stakeholders must monitor evolving EUDAMED registration timelines and FDA digital health pre-certification pilots that could accelerate approval pathways for sensor-integrated disposables.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while plasma fractionation expansion in Germany, Japan, and the United States pulls specialized blood bag capacity toward multi-year supply agreements. This structural force is reshaping how manufacturers allocate R&D and sterilization validation resources.
Growth Catalysts
- FDA 21 CFR Part 820 enforcement:Stricter quality system mandates are accelerating hospital replacement cycles for non-compliant collection sets, expanding addressable volume for certified suppliers.
- Apheresis procedure expansion:Automated platelet collection is displacing whole-blood-derived concentrates in tertiary cardiac centers, driving platelet storage container demand.
- Polyvinyl chloride formulation advances:Medical-grade polymer suppliers in Germany and Japan are delivering improved hemolysis resistance below 3%, enabling longer shelf-life claims.
Market Restraints
- Plasticizer supply concentration:DEHP and alternative plasticizer production clusters in China create input cost volatility and forced formulation switches under REACH restrictions.
- EMA MDR compliance timeline:Extended EUDAMED registration delays are freezing new product introductions for mid-tier manufacturers lacking notified body relationships.
- Glass transition in cryopreservation:Rigid polymer brittleness at ultra-low temperatures limits blood bag utility in cord blood banking, ceding share to specialized fluoropolymer alternatives.
Strategic Opportunities
- Sensor-integrated disposables:Temperature and hemolysis monitoring chips are converging with blood bag films, creating premium positioning for integrated device manufacturers.
- Indian hospital system expansion:Underpenetrated tier-2 and tier-3 cities are building transfusion infrastructure without legacy equipment lock-in, enabling direct digital procurement relationships.
- EU Green Deal procurement criteria:Public hospital tenders are embedding recycled content thresholds, rewarding suppliers with certified circular polymer supply chains.
Industry Challenges
- Biocompatibility toxicologist scarcity:ISO 10993-5 hemolysis testing expertise concentrates in contract laboratories with 12-18 month qualification queues, delaying product launches.
- Gamma sterilization capacity bottlenecks:Cobalt-60 source replenishment constraints and facility consolidation are extending sterilization validation timelines for new bag formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Processing Disposables Market |
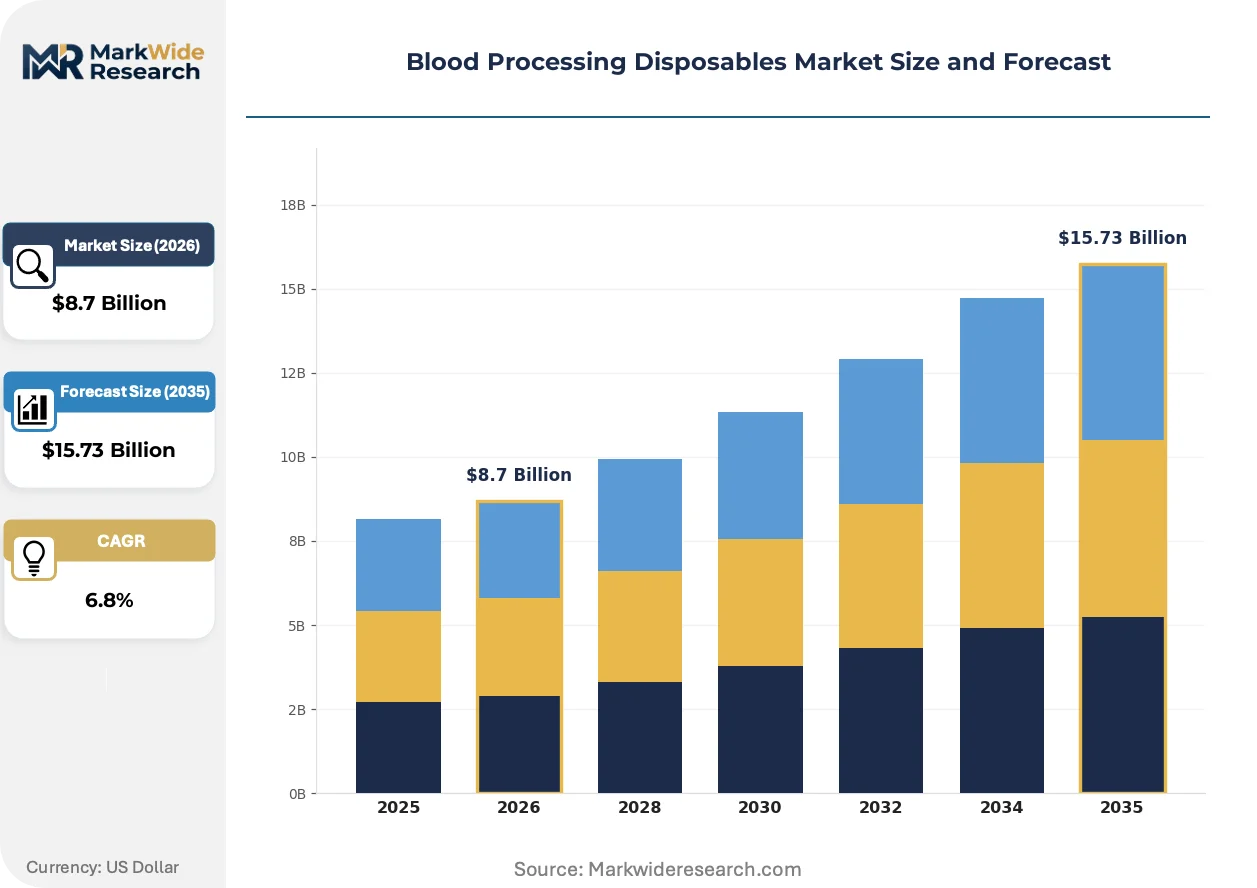
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Bags, Hemoconcentrators, IV Tubing, Platelet Storage Containers End User: Hospitals, Blood Banks, Diagnostic Laboratories, Research Institutes Material: Polyvinyl Chloride, Polyethylene, Ethylene Vinyl Acetate, Nylon Application: Transfusion Medicine, Pathology, Hematology, Sample Collection |
| Companies Covered | Haemonetics Corporation, Terumo Corporation, Grifols, Abbott, BD, Bio-Rad Laboratories, Fresenius Kabi, Macopharma, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Processing Disposables Market Strategic Shifts
Automation and material science are converging to reshape blood processing workflows, with regulatory digitization and procurement centralization acting as parallel accelerants. Three developments are compressing competitive timelines.
Radio-frequency identification tags embedded in blood bag labels are integrating with hospital inventory management systems to enable real-time cold chain tracking. Large integrated delivery networks in the United States are piloting these at scale, with Fresenius Kabi and Terumo Corporation securing multi-hospital validation contracts. This connectivity layer is integrating asset tracking with transfusion safety protocols, compressing liability exposure for blood centers.
EMA Medical Device Regulation Annex I requirements for material traceability are forcing polymer compounders to deploy blockchain-based batch records. German and French notified bodies are rejecting legacy paper documentation for new product registrations, elevating compliance costs for smaller film extruders. Blood bag manufacturers with captive compounder relationships are absorbing this friction faster than outsourced competitors.
Consolidated purchasing within North American integrated delivery networks is unbundling device procurement from service contracts, compressing vendor switching costs. Hospital systems are negotiating direct manufacturer relationships for high-volume blood bags while sourcing specialized apheresis sets through retained distributors. This bifurcation is most visible in California and Texas, where multi-hospital alliances command tiered pricing based on annual unit commitments rather than historical relationships.
Blood Processing Disposables Market Segmentation
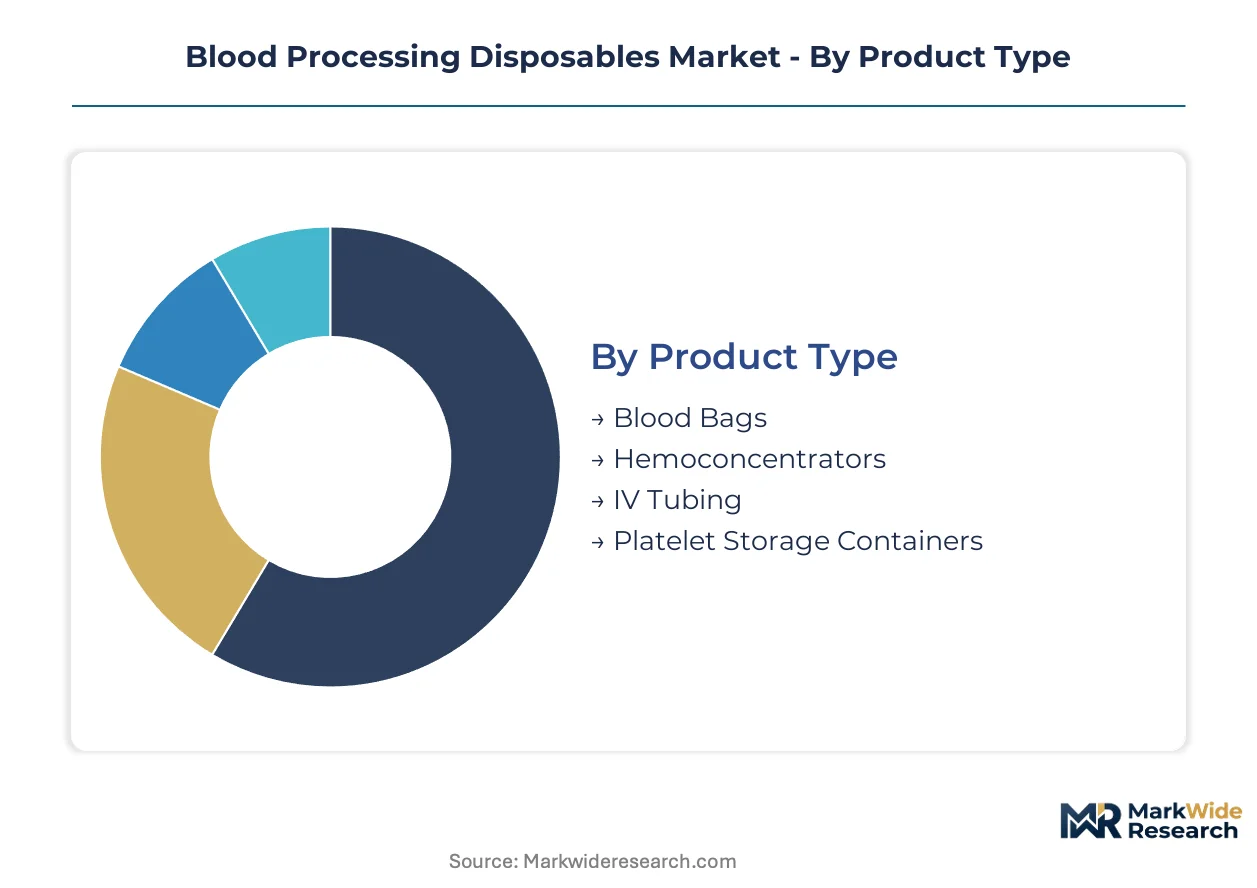
Blood processing disposables fragment across four dimensions that shape procurement workflows and regulatory compliance burdens differently. Hospital buyers weight material biocompatibility against sterilization costs, while application-specific performance requirements drive specialized manufacturing investments.
Product Type:
Procurement decisions pivot on sterilization validation timelines and shelf-life performance claims.
- Blood Bags:Plasticized polyvinyl chloride containers dominate hospital purchasing volumes due to universal transfusion protocol requirements. FDA 21 CFR Part 820 compliance and EMA MDR traceability mandates concentrate demand among German, Japanese, and US manufacturers with captive polymer supply chains.
- Platelet Storage Containers:Gas-permeable polymer films engineered for five-day platelet viability are displacing whole-blood-derived concentrates in tertiary cardiac centers. Apheresis procedure expansion in the United States and Japan pulls specialized container demand toward automated collection system integrators.
- Hemoconcentrators:Hollow-fiber membrane devices serve intraoperative autotransfusion in cardiac surgery centers where cell salvage utilization is climbing.
- IV Tubing:Medical-grade polymer conduits for blood administration face DEHP plasticizer substitution pressure under REACH restrictions.
Blood bags lead on scale; platelet storage containers lead on momentum.
End User:
Volume concentration and technical specification intensity diverge sharply across buyer categories.
- Hospitals:Integrated delivery networks in North America and Western Europe consolidate purchasing power through multi-year supply agreements. Stricter FDA and EMA sterilization mandates accelerate replacement cycles for non-compliant collection sets.
- Blood Banks:Plasma fractionation infrastructure in Germany, Japan, and the United States demands specialized bag formats with extended cryopreservation compatibility. Cobalt-60 gamma sterilization capacity constraints extend validation timelines for new product introductions.
- Diagnostic Laboratories:Sample integrity requirements drive demand for hemolysis-resistant containers with optical clarity specifications under ISO 3826.
- Research Institutes:Small-batch procurement of specialized apheresis sets occurs through retained distributors rather than direct manufacturer relationships.
Hospitals command volume leverage; blood banks impose technical complexity premiums.
Material:
Polymer formulation decisions directly shape regulatory pathway costs and end-use performance boundaries.
- Polyvinyl Chloride:Medical-grade PVC with DEHP or alternative plasticizers sustains the largest revenue pool. German and Japanese polymer suppliers deliver hemolysis resistance below 3%, enabling longer shelf-life claims for blood bag manufacturers.
- Polyethylene:Alternative polymer for cryopreservation applications where rigid polymer brittleness at ultra-low temperatures limits PVC utility in cord blood banking.
- Ethylene Vinyl Acetate:Flexible film applications in platelet storage containers where gas permeability requirements exceed PVC capabilities.
- Nylon:Reinforced layer applications in multi-laminate blood bag films requiring dimensional stability under mechanical stress.
Polyvinyl chloride anchors commercial scale; polyethylene captures substitution demand from cryopreservation expansion.
Application:
Clinical workflow integration requirements determine sensor compatibility and connectivity feature premiums.
- Transfusion Medicine:Core revenue driver encompassing whole blood, red cell, platelet, and plasma component handling. Radio-frequency identification tag integration with hospital inventory management systems is piloting at scale in US integrated delivery networks.
- Hematology:Specialized apheresis procedures requiring automated collection systems with workflow integration rather than commodity positioning.
- Pathology:Sample collection and transport containers with temperature monitoring capabilities for diagnostic integrity.
- Sample Collection:Single-use blood collection sets for diagnostic testing volumes in tier-2 and tier-3 Indian cities building transfusion infrastructure.
Transfusion medicine dominates revenue concentration; hematology commands the steepest technology premium trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biocompatibility toxicologists and polymer formulation specialists concentrate in Germany, Japan, and the United States, anchoring regional innovation capacity for blood processing disposables.
United States
FDA 21 CFR Part 820 enforcement accelerates hospital replacement cycles for non-compliant collection sets. Integrated delivery networks in California and Texas command tiered pricing through multi-hospital alliances. Plasma fractionation infrastructure in North Carolina and Illinois pulls specialized bag capacity toward multi-year supply agreements.
Germany
EMA Medical Device Regulation traceability mandates elevate compliance costs for polymer compounders deploying blockchain-based batch records. Notified bodies in Frankfurt and Munich reject legacy paper documentation for new product registrations. Medical-grade polymer suppliers in Bavaria deliver hemolysis resistance below 3%, enabling longer shelf-life claims.
Japan
PMDA sterilization validation requirements and METI industrial standards shape manufacturing investments for apheresis procedure expansion. Terumo Corporation's manufacturing scale in Tokyo and Thailand anchors Asia-Pacific blood bag supply. Automated platelet collection in Osaka and Nagoya tertiary cardiac centers drives platelet storage container demand.
India
CDSCO medical device registration pathways and hospital system expansion in tier-2 and tier-3 cities build transfusion infrastructure without legacy equipment lock-in. Maharashtra and Karnataka state health procurement programs enable direct digital procurement relationships. BIS standards compliance creates entry barriers for imported alternatives.
China
NMPA medical device quality system regulations and dual carbon goals reshape polymer formulation decisions for domestic manufacturers. DEHP and alternative plasticizer production clusters in Jiangsu and Zhejiang create input cost volatility. Gamma sterilization facility consolidation in Shanghai extends validation timelines for new bag formats.
Blood Processing Disposables Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across blood processing disposables, producing a tiered market structure where scale advantages clash with workflow integration expertise. Hospital procurement consolidation compresses vendor margins while plasma fractionation expansion pulls capacity toward long-term contracts. Three archetypes dominate: vertically integrated plasma suppliers, automated collection system integrators, and regional polymer specialists. Dominant competitive moves include backward integration into medical-grade polymer supply and sensor-integrated disposable development.
Among diversified healthcare conglomerates, Fresenius Kabi leverages its captive plasma supply chain to anchor European hospital contracts. Terumo Corporation exemplifies the Asia-Pacific manufacturing scale archetype through its Japan and Thailand production footprint. Haemonetics Corporation occupies the automated workflow integration position, competing on system compatibility rather than commodity pricing. These three anchors represent distinct strategic postures: supply chain control, geographic manufacturing density, and clinical workflow specialization.
| Leading Market Players |
|---|
| Haemonetics Corporation |
| Terumo Corporation |
| Grifols |
| Abbott |
| BD |
| Bio-Rad Laboratories |
| Fresenius Kabi |
| Macopharma |
| Beckman Coulter |
| Others |
Value Chain & Pricing Dynamics
Medical-grade polymer feedstock costs cascade through blood bag manufacturing tiers, with DEHP and alternative plasticizer price volatility in Chinese production clusters compressing margins at the commodity end while German and Japanese compounders command premium positioning through hemolysis resistance certification.
Pricing Analysis
Bundled service contracts for automated collection systems separate from unbundled blood bag procurement, with North American integrated delivery networks negotiating direct manufacturer relationships for high-volume PVC containers while retaining distributors for specialized apheresis sets. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993-5 biocompatibility certification tiers and gamma sterilization validation completeness. Cost compression in standard-grade collections intensifies because hospital procurement consolidation concentrates purchasing power among fewer buyers. Blood banks with plasma fractionation infrastructure show least price sensitivity due to multi-year supply agreement lock-in, while tier-2 Indian hospitals building transfusion infrastructure exhibit highest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with cobalt-60 gamma sterilization capacity, where facility consolidation in Shanghai and source replenishment constraints extend validation timelines for new bag formats. Manufacturing concentration clusters in Germany, Japan, and the United States, with medical-grade PVC compounding anchored in Bavaria and polymer film extrusion centered on Tokyo industrial corridors. Raw material dependencies rest on DEHP plasticizer production in Jiangsu and Zhejiang, ethylene vinyl acetate films for platelet storage, and nylon reinforcement layers for multi-laminate durability. REACH restriction exposure on phthalate plasticizers creates regulatory-driven formulation switching risk. Distribution runs through retained medical device distributors for specialized apheresis equipment and direct digital procurement portals for standard blood bag volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood processing disposables market functions as a stable compounder, with FDA and EMA sterilization mandates creating predictable replacement cycle demand that sustains revenue visibility across economic cycles.
For Market Incumbents: Cement hospital system partnerships through multi-year supply agreements that embed RFID tracking integration, defending against automated collection system integrators competing on workflow compatibility rather than commodity pricing. Prioritize captive polymer supply chain control to absorb EMA MDR blockchain traceability compliance costs faster than outsourced competitors. For New Entrants and Emerging Players: Launch via direct digital procurement relationships with Maharashtra and Karnataka state health programs in India's tier-2 and tier-3 cities, where transfusion infrastructure expansion proceeds without legacy equipment lock-in. Target sensor-integrated disposable development for premium positioning, exploiting biocompatibility toxicologist scarcity that delays incumbent product launches. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack notified body relationships for EUDAMED registration, creating acquisition opportunities for firms with sterilization validation expertise and hospital contract portfolios. Frame long-term viability around apheresis procedure displacement of whole-blood-derived concentrates. Monitor EMA MDR Annex I enforcement strictness as inflection indicator for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Disposable Development | Temperature and hemolysis monitoring chips embedded in blood bag films create premium positioning for integrated device manufacturers against commodity competitors. |
| Captive Polymer Supply Chain Control | In-house medical-grade PVC compounding accelerates EMA MDR blockchain traceability compliance and reduces formulation switching risk under REACH restrictions. |
| Hospital System Partnership Expansion | Multi-year supply agreements with integrated delivery networks in California and Texas lock in volume commitments through RFID-enabled cold chain tracking integration. |
| Gamma Sterilization Capacity Investment | Facility expansion addresses cobalt-60 source replenishment constraints and shortens validation timelines for new blood bag formats entering EUDAMED registration. |
| Direct Digital Procurement Platform Launch | Bypassing retained distributors for standard blood bag volumes captures margin compression from hospital procurement consolidation in underpenetrated Indian tier-2 cities. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down polymer supply tracking forms the analytical core, combining primary interviews with GPO contracts managers, biomedical engineers, hospital purchasing committees, and blood center operations directors with secondary validation through FDA 510(k) filings, EMA EUDAMED registration databases, hospital procurement records, and ISO 3826 compliance certifications.
Historical trendline analysis of blood bag unit volumes and apheresis procedure counts across the projection horizon informs segmentation modeling by product type, material formulation, end-user category, and application workflow, with CAGRs derived from sterilization mandate enforcement timelines and plasma fractionation infrastructure expansion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA MDR registration delay scenarios and cobalt-60 sterilization capacity bottlenecks. Forecasts reflect documented assumptions regarding hospital procurement consolidation velocity and plasticizer substitution timelines under REACH. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Medical Liners Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Medical Disposables Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Global Sterilization Wrap Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
US Hospital Consumables Market