
 GCC Minimally Invasive Surgery Market | 2026-2036
GCC Minimally Invasive Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Minimally Invasive Surgery Market Intelligence
Robotic-assisted surgical platforms is fragmenting traditional open-procedure workflows across GCC health systems, forcing hospitals to reconfigure operating theaters and retrain surgical teams. Medtronic leverages its integrated surgical ecosystem to anchor supply relationships with major hospital groups in Riyadh and Dubai. Johnson & Johnson competes through its broad endomechanical portfolio, while Intuitive Surgical dominates da Vinci system placements across premium private hospital networks in the Gulf.
Minimally invasive surgery encompasses operative techniques that limit incision size to 0.5–1.5 centimeters, employing endoscopic visualization, specialized trocar access ports, and energy-based tissue sealing to reduce perioperative trauma and accelerate patient discharge. Its primary purpose spans diagnostic intervention and therapeutic resection across cardiac, orthopedic, gastrointestinal, and urologic indications where tissue preservation directly correlates with recovery velocity. Robotic Systems command the highest capital allocation per installation and anchor vendor service revenue streams, while Laparoscopy sustains the largest procedure volume base across GCC public hospitals. Image-Guided Surgery represents the fastest-expanding technology segment as intraoperative navigation merges with preoperative imaging planning.
The Saudi Food and Drug Authority and UAE Ministry of Health and Prevention enforce medical device registration requirements that filter market access toward ISO 13485-certified manufacturers with established Gulf distributor networks. SFDA's tightened post-market surveillance protocols and UAE's mandatory adverse event reporting reshape procurement criteria, favoring suppliers with local technical service infrastructure. Stakeholders must monitor how Saudi Arabia's Health Sector Transformation Program and Qatar's National Health Strategy redirect public hospital capital budgets toward robotic and image-guided platforms versus conventional laparoscopic refresh cycles.
Market Dynamics
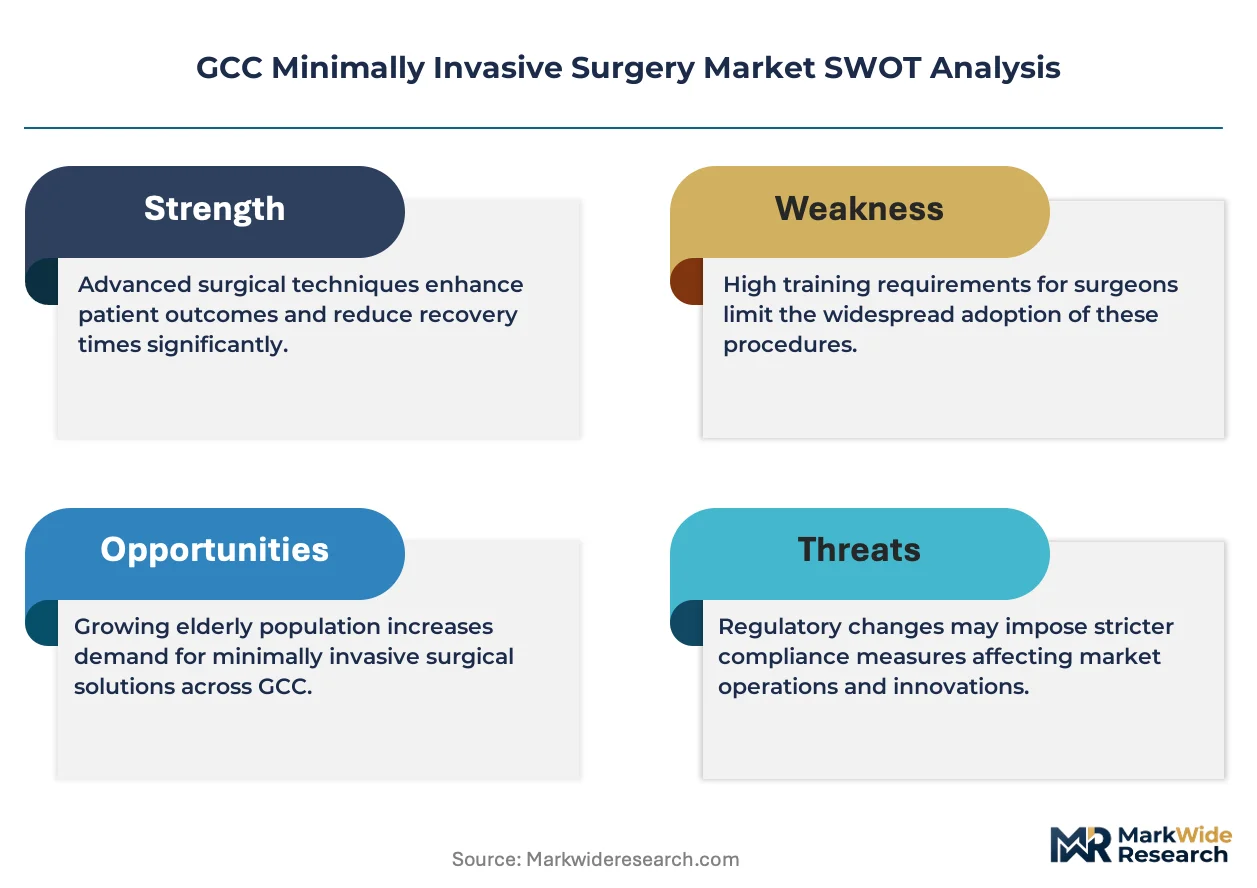
Robotic-assisted platforms are forcing GCC hospitals to reconfigure operating theaters and retrain surgical teams, compressing the traditional laparoscopic equipment refresh cycle while SFDA and MOHAP registration pathways filter vendor access toward ISO 13485-certified suppliers with established Gulf technical service infrastructure.
Growth Catalysts
- Saudi Health Sector Transformation Program:Government capital allocation prioritizes surgical modernization in Riyadh and Jeddah tertiary clusters, directing public hospital budgets toward robotic and image-guided platforms.
- Patient preference shift:Demand for shorter recovery times and reduced perioperative trauma accelerates hospital investment in laparoscopic and endoscopic procedure capacity.
- SFDA tightened post-market surveillance:Mandatory adverse event reporting and enhanced device tracking protocols favor suppliers with local distributor networks and in-country technical support capabilities.
Market Restraints
- Capital intensity per installation:Robotic surgical platforms require substantial upfront investment and dedicated facility infrastructure, limiting placement velocity in budget-constrained public hospital systems.
- Supply concentration in premium private networks:Da Vinci system placements cluster in Dubai and Riyadh premium hospital groups, creating access asymmetry across the broader GCC health system.
- Technical limitation in haptic feedback:Current robotic platforms lack full tactile sensation transfer, restricting adoption in procedures requiring fine tissue palpation.
Strategic Opportunities
- Qatar National Health Strategy redirection:Public hospital capital budgets in Doha are pivoting toward image-guided surgery platforms, creating vendor entry points outside the Saudi-UAE concentration.
- Convergence of intraoperative navigation with preoperative imaging:Image-guided surgery systems merge CT/MRI planning with real-time surgical visualization, opening new procedure categories.
- MOHAP streamlined registration for CE-marked devices:Accelerated pathway approval for European-certified platforms reduces time-to-market for compliant manufacturers.
Industry Challenges
- Robotic surgery skill certification:Surgeon training programs and proctoring requirements create bottlenecks in scaling procedure volume despite installed platform capacity.
- Integration complexity with legacy laparoscopic suites:Hybrid operating theater configurations demand simultaneous compatibility with conventional endoscopic towers and new robotic arms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Minimally Invasive Surgery Market |
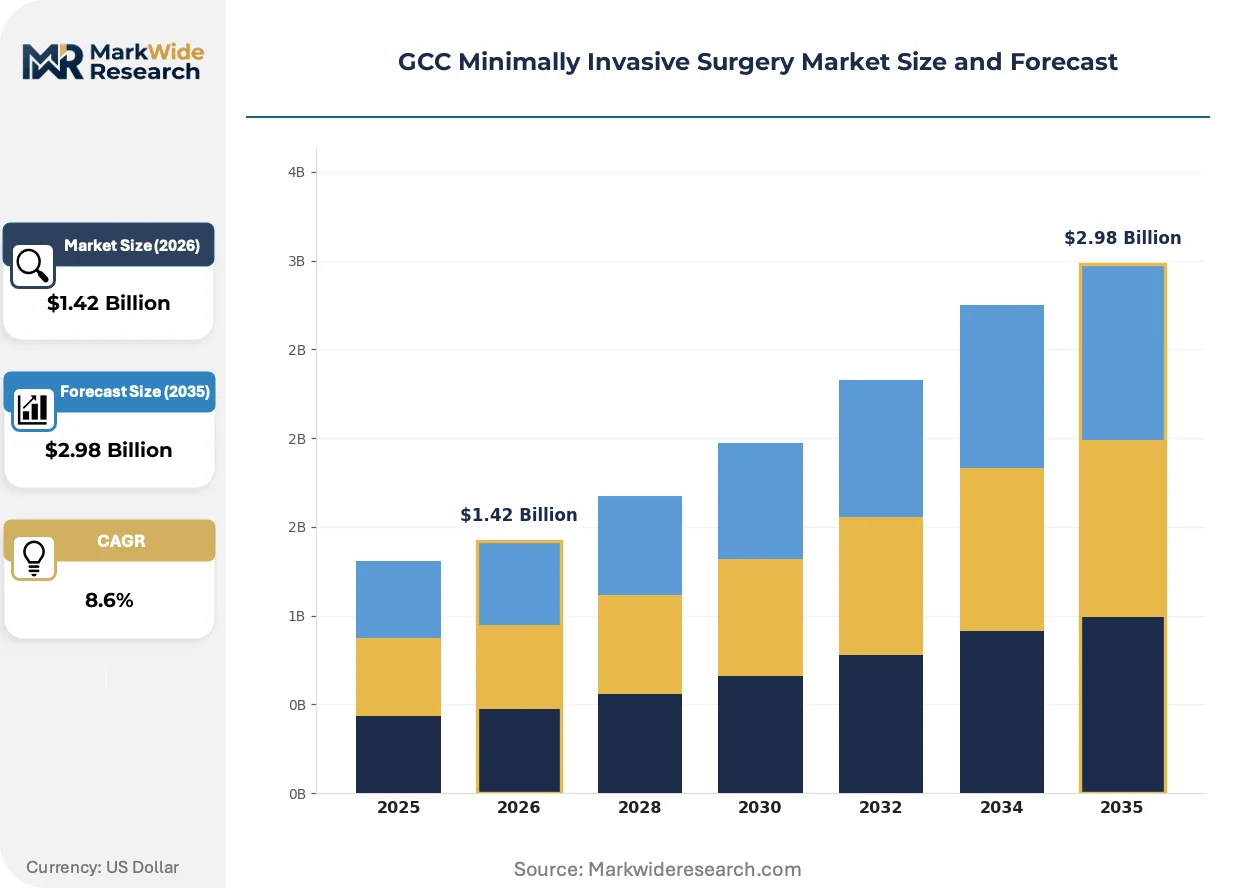
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Endoscopes, Trocar Systems, Surgical Staplers Application: Cardiac Surgery, Orthopedic Procedures, Gastrointestinal Surgery, Urologic Procedures Technology: Laparoscopy, Laser Surgery, Natural Orifice Surgery, Image-Guided Surgery End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Academic Institutes |
| Companies Covered | Medtronic, Johnson & Johnson, Stryker, Intuitive Surgical, Boston Scientific Corporation, Olympus Corporation, Smith & Nephew, Siemens Healthineers, CMR Surgical, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Minimally Invasive Surgery Market Strategic Shifts & Innovations
Single-port robotic systems and augmented reality visualization are compressing the technical gap between open and minimally invasive procedures, while regulatory harmonization efforts between SFDA and MOHAP reshape vendor compliance strategies.
Single-incision robotic platforms with wristed instrumentation and 3D high-definition visualization are rendering obsolete multi-port laparoscopic approaches for prostatectomy and hysterectomy procedures. Premium private hospital networks in Dubai and Riyadh are adopting these systems at accelerated pace. The technology is compressing average length-of-stay metrics and forcing competitors to refresh conventional laparoscopic portfolios.
SFDA's tightened medical device registration requirements now mandate ISO 13485 certification and established Gulf distributor networks for market access. This regulatory friction filters supplier participation toward manufacturers with in-country technical service infrastructure. CE-marked and FDA-cleared platforms gain accelerated pathway advantages, reshaping procurement criteria in Saudi tertiary hospital clusters.
Hospital purchasing committees are unbundling after-sales service contracts from capital equipment sales, demanding separate pricing for maintenance, software updates, and consumable supply agreements. This behavioral shift disrupts traditional vendor lock-in models. The pattern is most visible in UAE private hospital networks, where procurement teams negotiate multi-vendor service level agreements independent of initial platform acquisition.
GCC Minimally Invasive Surgery Market Segmentation
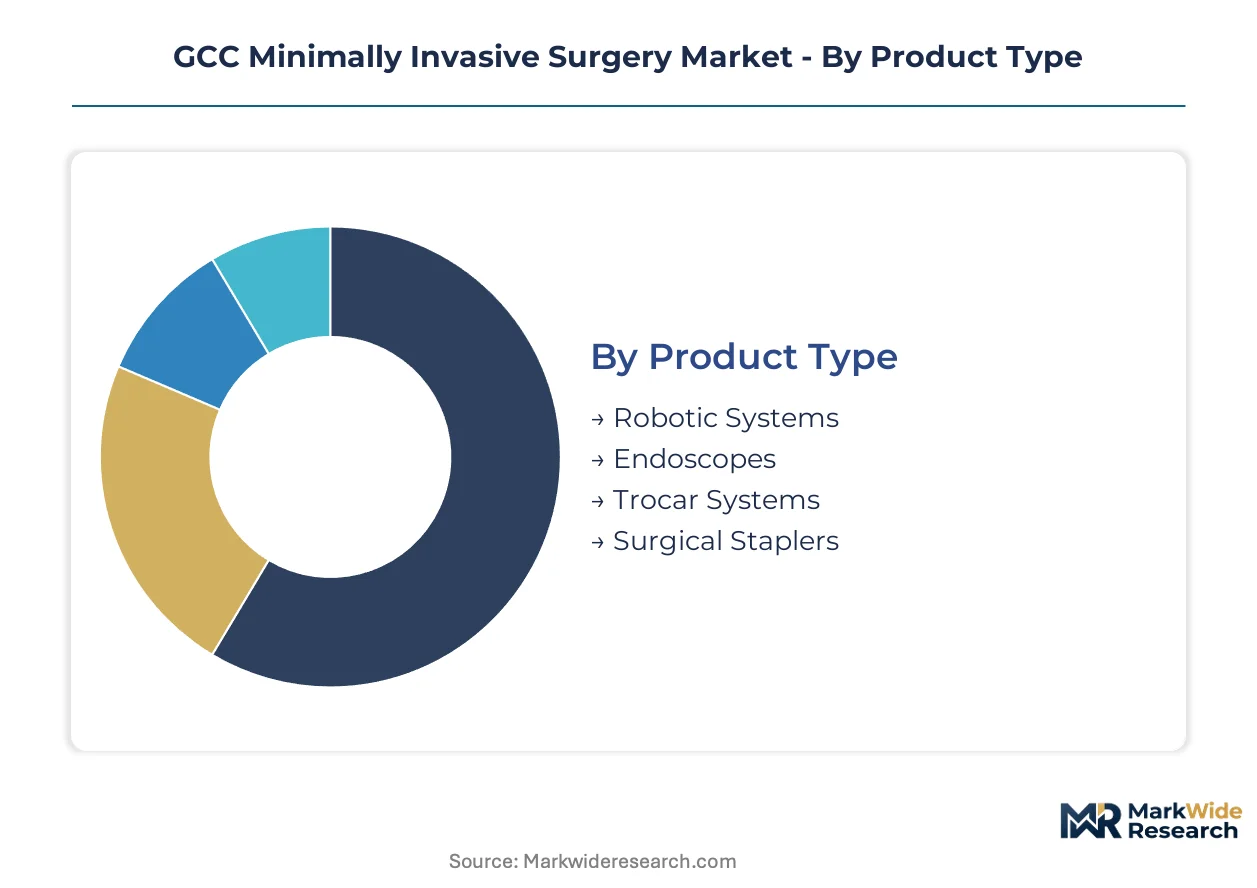
Segmentation reveals how capital allocation and clinical specialization fragment procurement patterns across GCC health systems. Product complexity, procedure type, and facility tier create distinct purchasing committees with non-overlapping vendor relationships.
Product Type:
Use-case spectrum spans high-capital robotic installations to disposable access systems, with procurement cycles ranging from seven-year depreciation schedules to quarterly consumable replenishment.
- Robotic Systems:Multi-arm platforms with 3D visualization and wristed instrumentation anchor vendor service revenue through long-term maintenance contracts. Demand concentrates in Riyadh and Dubai premium private hospital networks where government health transformation initiatives direct capital toward surgical modernization.
- Endoscopes:Flexible and rigid optical systems with high-definition imaging capabilities enable diagnostic and therapeutic visualization across gastrointestinal and urologic indications. Procurement clusters in Saudi tertiary hospital clusters undergoing laparoscopic program expansion.
- Trocar Systems:Disposable and reusable access ports with bladeless or bladed obturator designs establish minimally invasive entry points.
- Surgical Staplers:Powered and manual tissue approximation devices with variable staple line configurations.
Established volume favors Endoscopes; emerging adoption favors Robotic Systems.
Application:
Procedure complexity and reimbursement differentiation reshape equipment specifications across surgical disciplines.
- Gastrointestinal Surgery:Resection and anastomosis procedures for colorectal and upper GI malignancies leverage laparoscopic stapling and energy devices to reduce incision trauma. Volume concentrates in Saudi Arabia's public hospital systems where colorectal cancer screening expansion drives procedural growth.
- Urologic Procedures:Prostatectomy, nephrectomy, and cystectomy applications exploit robotic precision for nerve-sparing dissection in confined pelvic anatomy. Demand clusters in UAE private hospital networks where medical tourism positioning prioritizes prostate surgery outcomes.
- Cardiac Surgery:Valve repair and coronary bypass through thoracoscopic or robotic-assisted approaches.
- Orthopedic Procedures:Arthroscopic joint reconstruction and spine navigation applications.
Gastrointestinal Surgery sustains the broadest installed base; Urologic Procedures command the highest per-procedure equipment yield.
Technology:
Technical maturity and capital intensity stratify adoption curves across facility tiers.
- Laparoscopy:Conventional multi-port and single-incision approaches with 2D or 3D visualization towers constitute the procedural backbone across GCC public hospitals. Volume concentrates in Saudi tertiary clusters where refresh cycles replace aging endoscopic equipment.
- Image-Guided Surgery:Intraoperative navigation merging preoperative CT/MRI with real-time tracking enables precision in neurosurgical and orthopedic applications. Adoption accelerates in Qatar's National Health Strategy redirection toward advanced surgical platforms.
- Laser Surgery:Tissue ablation and lithotripsy applications across urologic and ophthalmic indications.
- Natural Orifice Surgery:Transoral, transvaginal, and transanal approaches eliminating abdominal wall incisions.
Laparoscopy anchors current procedure volume; Image-Guided Surgery climbs the fastest as navigation technology merges with surgical planning workflows.
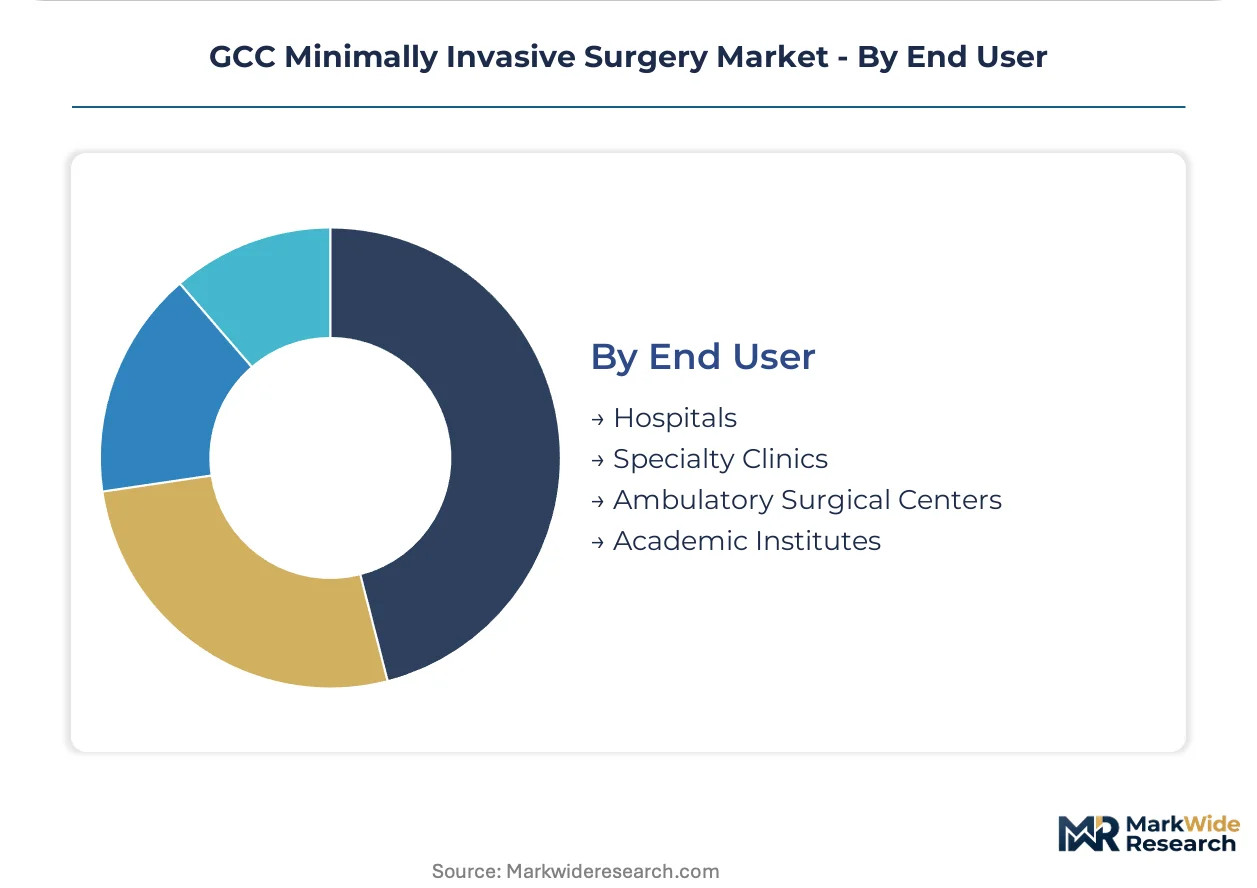
End User:
Facility scale and case mix determine capital equipment specifications and vendor contract structures.
- Hospitals:Tertiary medical centers with hybrid operating theaters integrate robotic, laparoscopic, and open-procedure capabilities within single surgical suites. Procurement concentrates in Saudi Arabia's Health Sector Transformation Program beneficiaries and UAE Ministry of Health and Prevention facilities.
- Ambulatory Surgical Centers:Same-day discharge facilities prioritize compact laparoscopic towers and disposable instrument systems for high-volume, low-acuity procedures. Expansion accelerates in Dubai and Riyadh private healthcare zones where outpatient surgery licensing has liberalized.
- Specialty Clinics:Focused endoscopy and dermatology centers with limited procedure rooms.
- Academic Institutes:Training hospitals with proctoring requirements and research mandates.
Hospitals absorb the dominant capital share; Ambulatory Surgical Centers gain share fastest as outpatient migration reshapes surgical delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees across the GCC concentrate purchasing authority in tertiary medical centers with hybrid operating theater capabilities, creating concentrated demand nodes that favor vendors with established Gulf technical service infrastructure.
Saudi Arabia
Riyadh and Jeddah tertiary hospital clusters anchor regional demand as the Health Sector Transformation Program directs public capital toward surgical modernization. SFDA tightened post-market surveillance protocols mandate ISO 13485 certification and adverse event reporting systems that filter vendor access toward manufacturers with in-country distributor networks.
United Arab Emirates
Dubai's premium private hospital networks and Abu Dhabi's Ministry of Health and Prevention facilities drive robotic platform adoption for medical tourism positioning. MOHAP streamlined registration pathways accelerate CE-marked device approvals, reducing time-to-market for European-certified surgical platforms.
Qatar
Doha's public hospital systems are redirecting capital budgets toward image-guided surgery platforms under the National Health Strategy. Hamad Medical Corporation's procurement committees prioritize intraoperative navigation systems that merge preoperative CT/MRI planning with real-time surgical visualization.
Kuwait
Government hospital networks in Kuwait City concentrate laparoscopic equipment refresh cycles as aging endoscopic towers reach replacement thresholds. The country's national pharmaceutical regulator enforces medical device registration requirements that favor suppliers with established Gulf technical service capabilities.
Bahrain
King Hamad University Hospital and private healthcare zones in Manama expand ambulatory surgical center capacity for same-day discharge procedures. Licensing liberalization for outpatient surgery facilities accelerates investment in compact laparoscopic towers and disposable instrument systems.
GCC Minimally Invasive Surgery Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where integrated surgical ecosystems anchor long-term supply relationships. The market exhibits consolidation around vendors with comprehensive service infrastructure, while mid-scale specialists capture niche procedure segments. Two strategic archetypes dominate: full-platform integrators bundling capital equipment with consumable supply agreements, and component specialists unbundling after-sales service from initial hardware sales. Competitive moves center on multi-vendor service level agreements and backward integration into consumable manufacturing.
Among US-based medical technology conglomerates, Medtronic and Johnson & Johnson occupy positions as full-platform integrators with established Gulf distributor networks. Intuitive Surgical represents the robotic-specialist archetype, with its da Vinci system placements clustering in premium private hospital networks. Stryker sits within the diversified orthopedic-surgical hybrid tier, leveraging cross-specialty equipment portfolios to secure multi-year maintenance contracts.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Stryker |
| Intuitive Surgical |
| Boston Scientific Corporation |
| Olympus Corporation |
| Smith & Nephew |
| Siemens Healthineers |
| CMR Surgical |
| Others |
Cost & Logistics Intelligence
The Jebel Ali-Dammam freight corridor's container cost dynamics compress margin structures for ISO 13485-certified manufacturers while amplifying price differentiation between CE-marked robotic platforms and conventional laparoscopic equipment across Saudi and UAE hospital procurement committees.
Pricing Analysis
Cost-plus contracts with raw material indexation to medical-grade stainless steel and optical component baskets dominate robotic system procurement, while laparoscopic consumables trade on spot-adjacent quarterly replenishment cycles. Price differentiation separates FDA-cleared premium platforms from CE-marked standard systems and economy-tier refurbished equipment, with certification grade and after-sales service bundling as primary levers. Cost compression in the laparoscopic tier intensifies as Saudi tertiary hospitals unbundle maintenance contracts from capital sales. Ambulatory surgical centers in Dubai and Riyadh private zones exhibit highest price sensitivity; premium private hospital networks in Jeddah show lowest.
Supply Chain Analysis
Supplier-financing through extended 180-day payment terms and supply-chain finance facilities anchored in Dubai's trade finance infrastructure enables vendor lock-in with major hospital groups. Component manufacturing concentrates in Germany, Japan, and the United States for robotic arm actuators, high-definition camera modules, and energy-based sealing devices. Raw material dependencies include medical-grade polymers, rare-earth magnets for motor assemblies, and specialized optical glass. Single-source vulnerability runs through Japanese precision motor suppliers for wristed instrumentation. Distribution runs through authorized Gulf distributor networks with in-country technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in Saudi Arabia's Health Sector Transformation Program procurement committees, which now consolidate robotic platform tenders across Riyadh and Jeddah tertiary clusters rather than negotiating hospital-by-hospital.
For Market Incumbents: Pre-empt emerging competition from CMR Surgical and other robotic challengers by anchoring exclusive consumable supply agreements with Hamad Medical Corporation and Saudi tertiary clusters before their next capital refresh cycles. Deepen backward integration into single-use instrument manufacturing to defend margin position against unbundling procurement trends. Accelerate ISO 13485 certification investments for distributor partners to satisfy SFDA's tightened post-market surveillance protocols.
For New Entrants and Emerging Players: Build out Qatar's image-guided surgery segment as the most penetrable white-space target, where National Health Strategy capital redirection creates vendor entry points outside Saudi-UAE concentration. Target Kuwait's aging laparoscopic equipment refresh cycle with compact tower systems priced below premium robotic alternatives. Pursue GPO contracts with Bahrain's expanding ambulatory surgical center network as the primary go-to-market angle.
For Investors and Strategic Acquirers: Component-specialist firms with CE-marking pathways and established Gulf technical service infrastructure represent the priority acquisition archetype, particularly those unbundling after-sales service from hardware sales. Long-term viability favors suppliers with software companion development capabilities and recurring revenue streams over pure capital equipment plays. Watch for SFDA-MOHAP regulatory harmonization completion as the inflection signal for accelerated market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Accelerated SFDA registration for European-certified platforms reduces Gulf time-to-market. |
| Hospital System Partnership | Exclusive consumable agreements with Saudi tertiary clusters anchor recurring revenue streams. |
| Software Companion Development | Intraoperative navigation integration with preoperative imaging planning opens procedure categories. |
| Reimbursement Strategy | Alignment with Saudi health transformation surgical modernization priorities directs capital allocation. |
| Backward Integration | In-house production of single-use instruments defends margins against unbundling procurement trends. |
Research Approach
A standing panel of hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers provided ongoing calibration across primary fieldwork, while secondary validation drew from SFDA medical device registration databases, MOHAP adverse event reporting systems, Hamad Medical Corporation procurement records, and European notified body CE marking filings. Bottom-up procedure volume modeling triangulated against top-down capital expenditure flows from national health transformation program disclosures.
Scenario-bracketing around regulatory harmonization timelines and health transformation program budget execution framed the analytical approach across the projection horizon. Segmentation dimensions spanned product type complexity tiers, application specialty, technology maturity curves, and facility tier capital allocation patterns. CAGRs derived from installed base depreciation schedules and procedure volume elasticity to platform capacity expansion. Forecast inputs included surgeon training program throughput and hybrid operating theater construction pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by robotic challengers with single-port platforms would shift outcomes beyond modeled ranges. Macroeconomic deviation in oil-revenue-dependent health budgets, regulatory restriction tightening, or breakthrough haptic feedback technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Surgical Snare Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
Surgical Rasps Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Resectoscopes Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Surgical Hemostats Market