
 Surgical Snare Market | 2026-2036
Surgical Snare Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Snare Market Intelligence
China's expanding manufacturing capacity for medical consumables is reshaping the competitive positioning of surgical snare suppliers. Boston Scientific Corporation leverages its extensive distribution network to maintain a strong presence in high-value endoscopic applications. Olympus Corporation specializes in integrated solutions, pairing its snares with its market-leading endoscopes. CONMED Corporation competes on product innovation, particularly in electrosurgical snare technology.
A surgical snare is a medical instrument featuring a wire loop designed to encircle and remove tissue, such as polyps, during minimally invasive procedures. The device operates by tightening the loop, which is often made of braided stainless steel or coated wire, to excise the targeted growth with electrical current for cauterization. Single-use snares command the largest market share, driven by infection control protocols in hospitals and ambulatory surgical centers. Demand from gastrointestinal procedures remains the dominant application, while urological procedures represent a high-growth area.
Device approval pathways are governed by agencies like the US FDA, which classifies snares as Class II devices, and China's NMPA, which has its own registration requirements. ISO 13485 standards for quality management systems are critical for market access in most developed economies, influencing manufacturing practices. Stakeholders must now evaluate the trade-offs between reusable device reprocessing costs and the higher per-procedure expense of disposable snares.
Market Dynamics
The transition toward single-use snares, driven by stringent infection control mandates in hospitals, represents the market's central dynamic. This shift is reinforced by regulatory pressures, including heightened post-market surveillance requirements under the EU's Medical Device Regulation.
Growth Catalysts
- Miniaturization in Device Design:Advances in wire loop materials enable smaller, more precise snares, improving access in complex polypectomy procedures.
- Demographic Shifts:Aging populations in Japan and Germany expand the patient pool for gastrointestinal procedures, directly increasing demand for endoscopic snares.
- Preventive Health Mandates:Government-backed colorectal cancer screenings create consistent demand for polypectomy snares by increasing the number of therapeutic colonoscopies.
Market Restraints
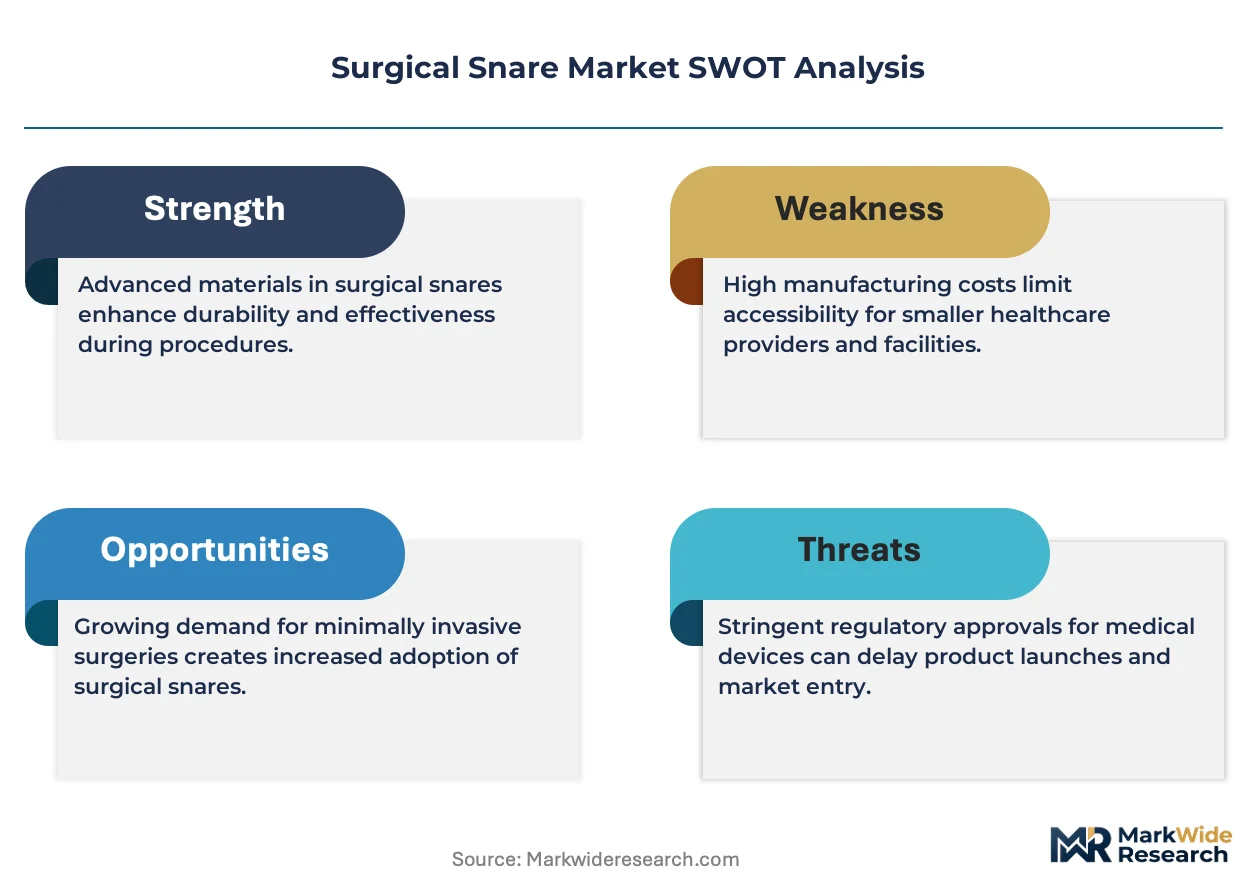
- Reprocessing Cost Structures:The high cost of sterilizing reusable snares deters adoption in hospitals focused on operational efficiency and infection control.
- Alternative Ablation Technologies:Non-snare techniques like argon plasma coagulation (APC) present a substitution threat for removing certain diminutive polyps.
- Stringent Regulatory Pathways:Navigating US FDA and EU MDR requirements increases compliance costs and delays market entry for new snare devices.
Strategic Opportunities
- Expansion into Urology:Applying snare technology to urological procedures like bladder tumor resection opens a high-growth application beyond gastroenterology.
- Smart Snare Development:Integrating sensors into snare loops for real-time feedback on tissue contact offers a path for premium product differentiation.
- Market Entry in Southeast Asia:Rising healthcare investment in nations like Vietnam and Thailand creates entry points for both premium and economy-tier snares.
Industry Challenges
- Specialized Workforce Training:A shortage of endoscopists skilled in advanced polypectomy techniques can limit the adoption of specialized snare devices designed for complex procedures.
- Raw Material Price Volatility:Fluctuations in the price of medical-grade stainless steel and wire coatings impact the manufacturing cost and margins of single-use snares.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Snare Market |
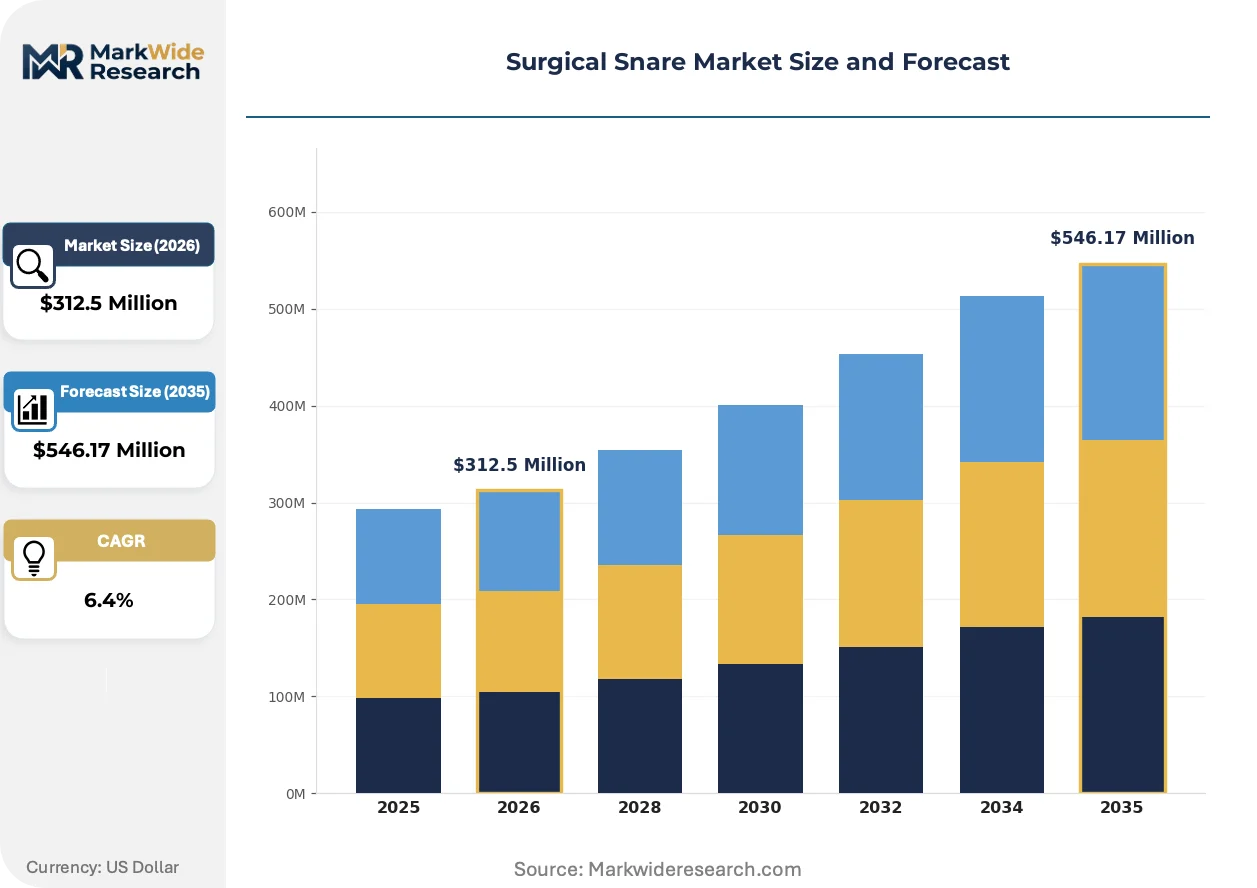
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Disposable, Electrosurgical End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Laboratories Application: Gastrointestinal Procedures, Cardiovascular Procedures, Urological Procedures, Oncology Treatments Material: Stainless Steel, Polypropylene, Nylon, Coated Wire |
| Companies Covered | CONMED Corporation, Merit Medical Systems, Medtronic, Medline Industries, Inc., Steris, Olympus Corporation, Cook, Avalign Technologies, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Snare Market Strategic Shifts & Innovations
Product evolution in the surgical snare market is defined by the dual pursuit of device miniaturization for enhanced procedural access and the integration of feedback mechanisms. These advancements aim to improve clinical outcomes and simplify complex tissue removal procedures.
Rotatable and multi-loop snare designs provide endoscopists greater control during complex polypectomies. Gastroenterologists adopt these for endoscopic mucosal resection, reducing procedural time. This evolution is virtualizing the need for multiple device exchanges and repositioning, streamlining tissue removal into a more controlled action.
The European Union's Medical Device Regulation (MDR) mandates rigorous clinical evidence and post-market surveillance for surgical snares. This regulation compels manufacturers to generate extensive data supporting safety and performance claims. Single-use snare producers are particularly affected, needing to validate device performance across diverse patient populations.
Value-based purchasing by large hospital networks and Group Purchasing Organizations (GPOs) is altering procurement for disposable medical supplies. This model prioritizes total cost of care over individual device price, challenging the traditional sales model. The shift is most pronounced in the United States, where GPOs consolidate purchasing power.
Surgical Snare Market Segmentation
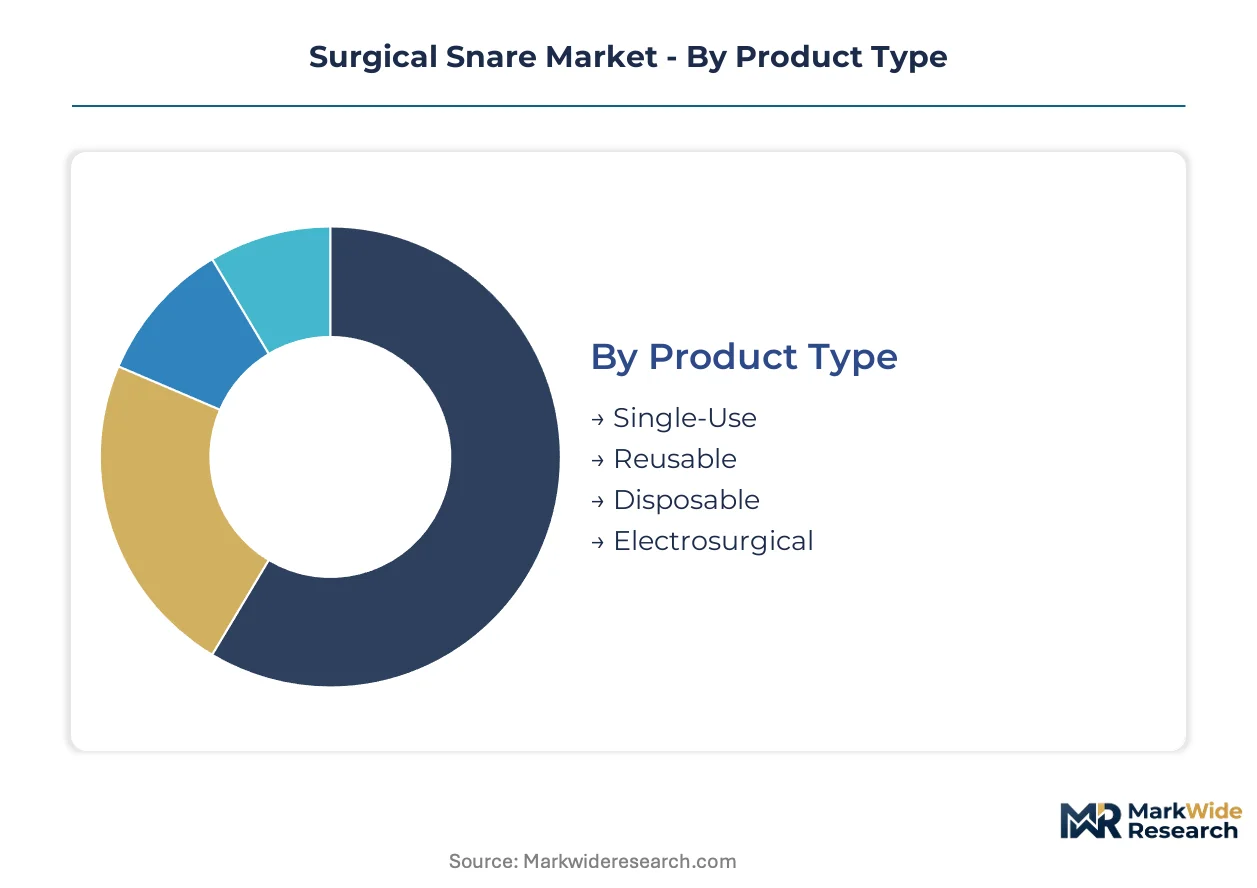
The surgical snare market's segmentation provides a granular view of product evolution and demand drivers. Understanding these distinct categories helps stakeholders identify specific growth pockets and operational efficiencies. This detailed breakdown highlights how different device characteristics, end-user environments, and procedural applications shape market dynamics.
Product Type:
The cycle time for surgical snare product types varies significantly, with single-use devices experiencing the fastest turnover due to procedural mandates and infection control protocols.
- Single-Use:These snares are designed for one-time application, ensuring sterility and eliminating reprocessing costs and risks. Demand from hospitals and ambulatory surgical centers concentrates on these devices due to stringent infection control mandates and regulatory pressures under the EU MDR.
- Electrosurgical:These snares integrate electrocautery capabilities to cut and coagulate tissue simultaneously, enhancing procedural efficiency. Product innovation in this segment, particularly by CONMED Corporation, focuses on improved control and precision during complex polypectomy procedures.
- Reusable:These devices are designed for multiple uses after thorough cleaning and sterilization, representing a lower per-procedure cost but higher reprocessing overhead.
- Disposable:This category encompasses snares intended for single-patient use, often simpler in design, addressing basic tissue removal needs across various clinical settings.
Single-Use snares dominate the installed base for new procurements. Electrosurgical snares represent where product innovation and procedural expansion concentrate.
End User:
The type and volume of surgical snare procurement vary considerably across different end-user segments, reflecting distinct operational models and patient caseloads.
- Hospitals:These institutions represent the largest volume consumers of surgical snares, driven by a broad range of complex surgical procedures and a high patient throughput. Infection control mandates heavily influence purchasing decisions for single-use devices within hospital networks.
- Ambulatory Surgical Centers:These facilities focus on outpatient procedures, driving demand for efficient, sterile, and often single-use snares to manage high procedural volumes. Their procurement patterns prioritize quick turnaround times and reduced operational overhead.
- Clinics:Smaller clinics utilize surgical snares for less complex, routine diagnostic and therapeutic interventions, often prioritizing cost-effectiveness and ease of use.
- Research Laboratories:These facilities employ specialized snares for experimental procedures, tissue sampling, and preclinical studies, with demand focusing on precision and material compatibility.
Hospitals continue to be the primary revenue generator for snare suppliers. Ambulatory Surgical Centers are demonstrating the steepest expansion trajectory in procedural volume.
Application:
The maturity and growth trajectory of surgical snare applications differ, with established procedures driving consistent demand and emerging fields presenting new opportunities.
- Gastrointestinal Procedures:This segment represents the largest application for surgical snares, primarily for polypectomy during endoscopic examinations. Government-backed colorectal cancer screenings in developed economies like Germany and Japan consistently drive demand.
- Urological Procedures:This application area is experiencing high growth, leveraging snare technology for bladder tumor resections and other minimally invasive interventions. Expansion into this field offers strategic opportunities for device manufacturers.
- Cardiovascular Procedures:Snares are used in certain cardiovascular interventions, typically for tissue removal or foreign body retrieval within vascular structures.
- Oncology Treatments:This segment utilizes snares for the removal of cancerous or precancerous lesions in various anatomical locations, often in conjunction with other ablation technologies.
Gastrointestinal procedures consistently generate the highest demand for snares. Urological procedures are expanding most quickly in clinical adoption.
Material:
The choice of material for surgical snares directly influences device performance, durability, and biocompatibility, catering to specific procedural requirements.
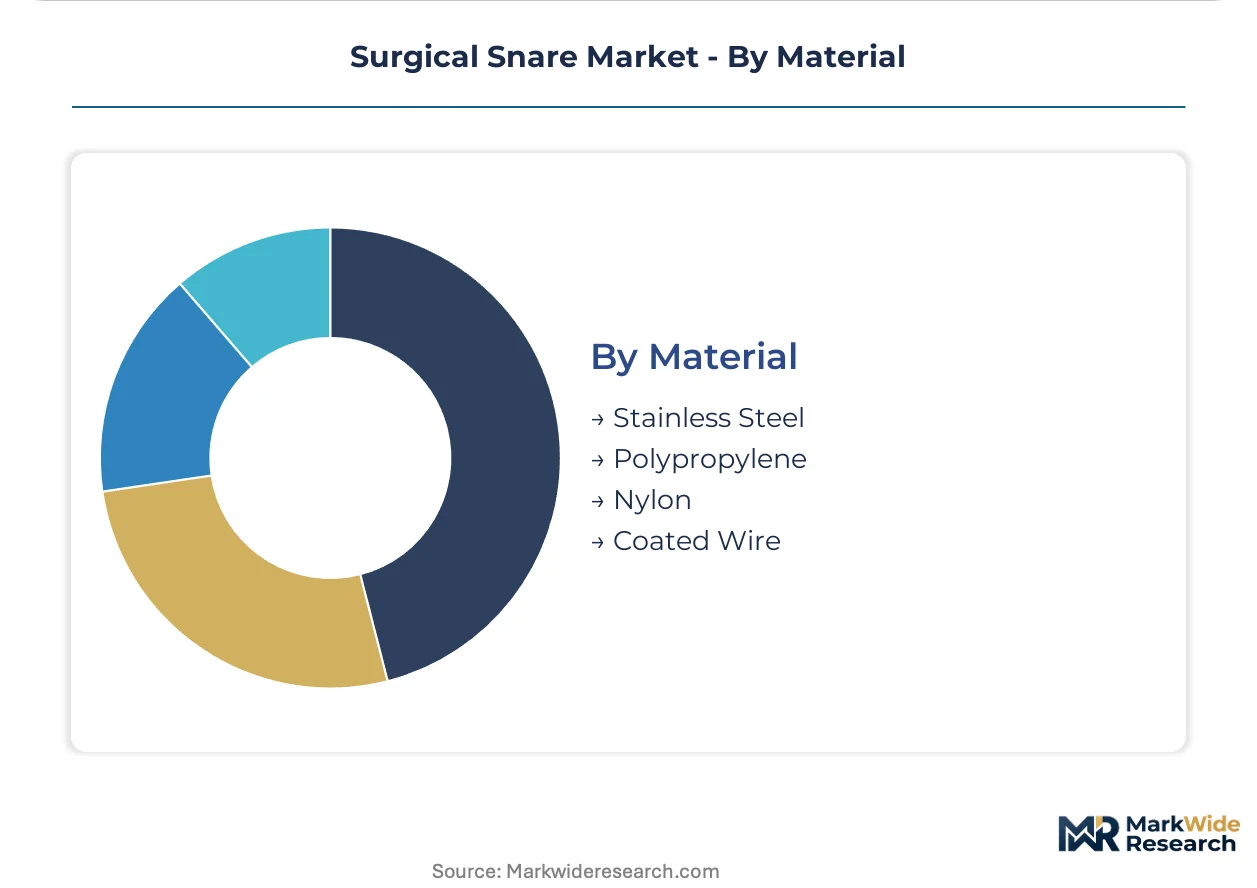
- Stainless Steel:This material forms the core of many snare designs, valued for its strength, rigidity, and biocompatibility, particularly in braided wire configurations for effective tissue excision. Its consistent properties make it a standard for general-purpose snares.
- Coated Wire:Snares incorporating coated wires, often with polymers, offer enhanced lubricity, reduced friction, and improved insulation for electrosurgical applications. These coatings facilitate smoother passage through endoscopes and provide better thermal isolation.
- Polypropylene:This polymer finds use in certain snare components or as a sheath material, offering flexibility and chemical resistance for specific non-electrosurgical applications.
- Nylon:Nylon is employed for its flexibility and tensile strength in some snare designs, particularly where non-conductive or more pliable loops are required for delicate tissue manipulation.
Stainless steel continues to be the most widely used material in snare construction. Coated wire technologies are advancing device precision and safety features.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's Medical Device Regulation (MDR) anchors market access and product design across Europe, a significant region for surgical snare adoption. This regulation influences manufacturing practices and post-market surveillance. Demand for these devices stems from various advanced healthcare systems globally.
Germany
Germany's aging population drives consistent demand for gastrointestinal procedures, increasing the need for surgical snares. The EU MDR mandates rigorous clinical evidence for devices sold in the German market. Munich serves as a hub for advanced medical technology development, attracting significant investment.
Japan
Japan's demographic shifts, with a large elderly patient pool, sustain high demand for endoscopic interventions requiring snares. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals, ensuring product safety and efficacy. The Kansai region hosts numerous medical device manufacturers, fostering innovation.
United States
The United States market sees robust demand for single-use snares, supported by a high volume of ambulatory surgical procedures. The US FDA classifies snares as Class II devices, requiring specific pre-market notification pathways. Major MedTech clusters in Boston and California drive product innovation and adoption.
China
China's expanding healthcare infrastructure and rising procedural volumes contribute to its growing demand for surgical snares. The National Medical Products Administration (NMPA) implements stringent registration requirements for medical devices. The Yangtze River Delta region is a key center for medical consumable manufacturing.
France
French hospitals prioritize infection control, boosting the adoption of single-use surgical snares for various procedures. European MDR compliance is critical for market entry and continued sales within France. The Paris region supports a strong medical device R&D ecosystem, developing new snare technologies.
Surgical Snare Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered competitive structure within the surgical snare market. This environment includes firms focused on delivering integrated endoscopic solutions, alongside specialized innovation-focused firms developing advanced electrosurgical snare technology. Companies pursue strategic partnerships to broaden their distribution networks and engage in portfolio diversification to capture new application areas like urology. Market players also engage in targeted mergers and acquisitions to consolidate technological expertise.
Among the established players, Boston Scientific Corporation exemplifies a strong presence through its extensive distribution network, supporting high-value endoscopic applications. Olympus Corporation occupies a position as a provider of integrated solutions, pairing its snares with market-leading endoscopes. CONMED Corporation represents a firm focused on product innovation, particularly in electrosurgical snare technology development.
| Leading Market Players |
|---|
| CONMED Corporation |
| Merit Medical Systems |
| Medtronic |
| Medline Industries, Inc. |
| Steris |
| Olympus Corporation |
| Cook |
| Avalign Technologies |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Underutilized manufacturing capacity in China's medical consumable sector drives intense competition among suppliers, directly influencing pricing strategies and supply chain resilience for surgical snares.
Pricing Analysis
Geographic price spreads for surgical snares vary significantly, reflecting regional regulatory hurdles and reimbursement structures. The dominant pricing model remains per-unit transactional, favoring high-volume procurement. Brand premium and CE/FDA certification levels differentiate pricing. Pricing softness stems from the increasing adoption of cost-effective single-use devices. Hospitals exhibit high price sensitivity for commodity snares, while specialized ambulatory surgical centers prioritize performance.
Supply Chain Analysis
Contract manufacturing capacity for surgical snares concentrates significantly within the Yangtze River Delta region of China. Geographic supply concentration includes China, Germany, and the United States. Raw material dependencies include medical-grade stainless steel, specialized wire coatings, and polypropylene. Single-source vulnerability for specific components represents a key structural risk. Distribution runs through established medical device distributors and direct sales forces to hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical snare market is experiencing high-growth disruption, driven by miniaturization in device design that enables more precise and complex minimally invasive procedures.
For Market Incumbents: Harden existing market positions by investing in next-generation electrosurgical snare technology, particularly for complex polypectomy applications. Expand distribution networks in emerging Southeast Asian markets to counter the rising threat from regional manufacturers. Deepen vertical integration into specialized material sourcing to mitigate raw material price volatility. Consolidate market share through strategic partnerships focused on integrated endoscopic solutions.
For New Entrants and Emerging Players: Build out specialized product portfolios targeting high-growth applications like urological procedures for bladder tumor resection. The most penetrable segment remains economy-tier single-use snares in rapidly expanding healthcare markets such as Vietnam. A go-to-market angle focusing on cost-effectiveness combined with essential performance features will resonate with budget-conscious procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated solution providers bundling snares with endoscopes and service contracts. Long-term viability in this market depends on innovation in smart snare technology and expansion into new procedural areas. Acquisition targets should focus on mid-sized firms with proprietary coating technologies or strong regional distribution. The signal to watch is the rate of adoption of sensor-integrated snares.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Smart Snares with Sensors | Integrates real-time feedback for endoscopists, improving precision during complex polypectomy procedures. |
| Expand into Urology Applications | Diversifies revenue streams beyond gastroenterology, targeting high-growth bladder tumor resection. |
| Strengthen Distribution in Southeast Asia | Captures demand from rising healthcare investment in nations like Vietnam and Thailand. |
| Invest in Electrosurgical Technology | Enhances procedural efficiency by combining cutting and coagulation, benefiting CONMED Corporation's portfolio. |
| Pursue ISO 13485 Certification | Ensures market access in developed economies, influencing manufacturing practices for single-use devices. |
Research Approach
Desk research of regulatory filings, medical journal articles, and industry reports preceded structured interviews with clinicians, hospital purchasing committees, and medical device engineers. This approach combined primary insights with secondary validation from diverse sources. We employed bottom-up and top-down triangulation to ensure data accuracy. Key secondary sources included US FDA databases, EU MDR guidance documents, and industry association publications.
Assumptions regarding healthcare spending trends and regulatory stability were held fixed across the analysis window. The analytical framework modeled market dynamics by product type, end user, application, material, and regional adoption patterns. Compound annual growth rates were derived from historical data and projected market drivers. Key inputs included demographic shifts in aging populations and colorectal cancer screening rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new entrants or large hospital networks would shift outcomes. Forecasts reflect assumptions on technology adoption and raw material stability. Raw material price volatility and unforeseen regulatory changes represent specific risk factors. Quarterly review of procedural volumes and new device approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market