
 Abdominal Open and Closure Trainer Market | 2026-2036
Abdominal Open and Closure Trainer Market Size, Share, and Industry Trends Forecast 2026-2036
Abdominal Open and Closure Trainer Market Insights
Modular trainer kits with detachable fascial layers and interchangeable closure pads is pivoting purchasing decisions away from standalone devices. Medtronic leverages its hospital contracting infrastructure to bundle trainers with suture and mesh portfolios. Limbs & Things specializes in anatomically precise tissue analogs that anchor its position in European medical school tenders. Johnson & Johnson competes through institutional relationships with academic medical centers in North America.
An abdominal open and closure trainer is a physical or hybrid simulation device replicating human abdominal wall anatomy—typically comprising synthetic skin, subcutaneous fat, fascial layers, and peritoneum—for repetitive practice of surgical incision, layered closure, and tension-free repair techniques. Hybrid models integrating haptic feedback with physical tissue analogs command premium positioning as residency programs prioritize objective skill assessment. Medical education applications dominate procurement volumes, while VR simulation technology captures the fastest expansion trajectory as programs seek scalable remote training infrastructure. Basic models retain share in resource-constrained settings where capital budgets limit technology investment.
FDA 510(k) clearance requirements for surgical simulation devices shape product development timelines and validation costs for vendors targeting the United States. EU MDR clinical evidence standards and CE marking obligations govern market access across European member states, while ISO 13485 quality management certification functions as a baseline procurement filter for institutional buyers worldwide. Stakeholders must monitor evolving accreditation body simulation mandates and anticipate which technology tier—physical, augmented, or fully virtual—aligns with forthcoming competency verification requirements.
Market Dynamics
Residency program accreditation standards now mandate simulation-based competency verification, forcing medical schools and academic medical centers to prioritize haptic-enabled hybrid trainers over basic physical models. This structural shift compresses replacement cycles and elevates procurement specifications toward objective skill assessment capabilities.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined regulatory route for surgical simulation devices accelerates vendor product launches in the United States, reducing time-to-market validation burdens.
- EU MDR Clinical Evidence Standards:Tightened requirements for training equipment create competitive moats for vendors with robust clinical validation, filtering out low-documentation suppliers across European member states.
- Haptic Feedback Integration:Hybrid models combining physical tissue analogs with sensor-based performance measurement enable objective resident assessment, driving replacement demand in United States academic medical centers.
Market Restraints
- Silicone Polymer Input Volatility:Tissue analog production depends on medical-grade silicone supply chains concentrated in East Asian chemical manufacturing clusters, exposing margins to petrochemical price swings.
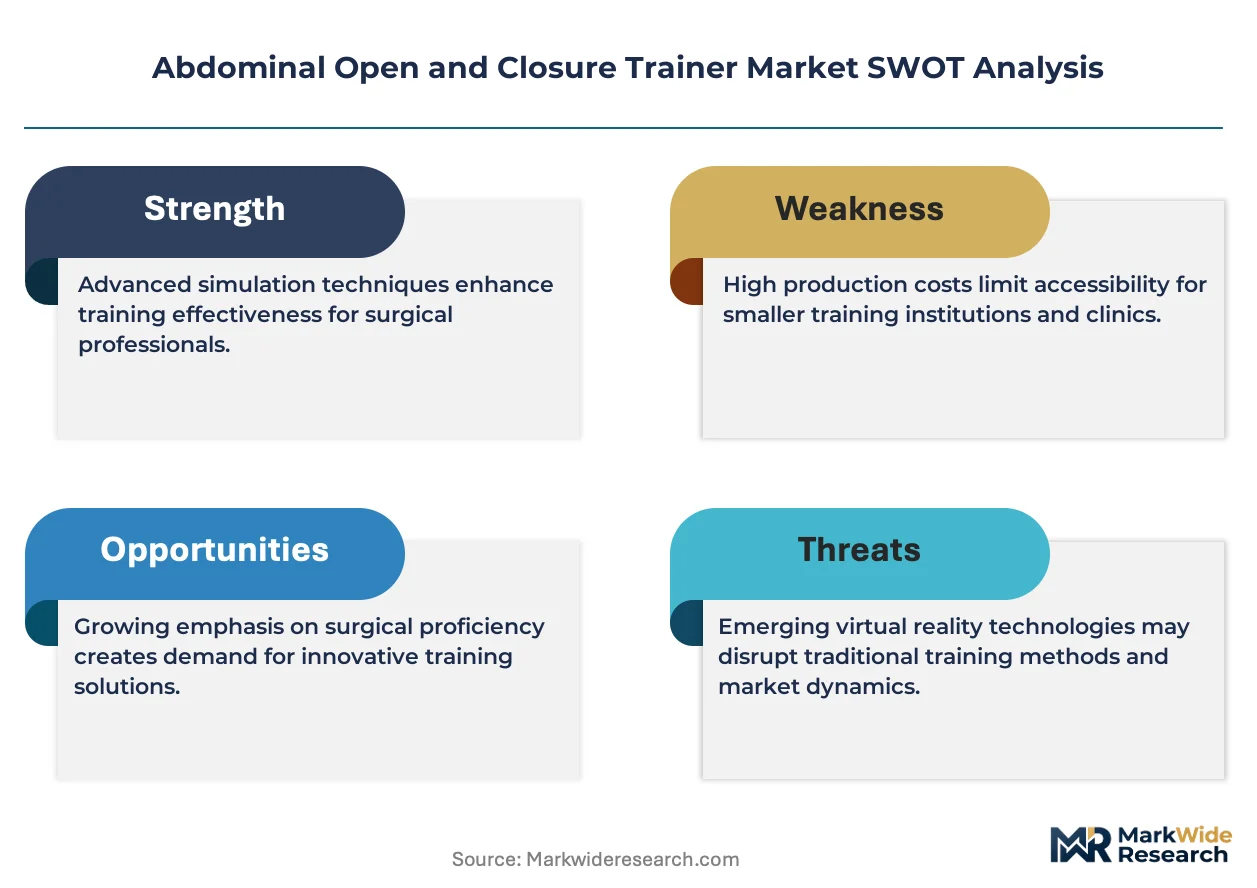
- ISO 13485 Certification Burden:Quality management system compliance functions as a baseline procurement filter, requiring substantial documentation investment from smaller vendors before institutional tender eligibility.
- VR Simulation Substitution Threat:Fully virtual platforms offering scalable remote training infrastructure capture fastest-expansion trajectory, potentially compressing physical trainer addressable market in budget-constrained settings.
Strategic Opportunities
- Modular Kit Architecture:Detachable fascial layers and interchangeable closure pads enable recurring consumable revenue streams, pivoting purchasing decisions from one-time capital expenditure to subscription-like replacement cycles.
- Rural Residency Program Expansion:United States Graduate Medical Education funding shifts toward distributed training sites create demand for portable, lower-cost trainer configurations outside major academic medical centers.
- CE Marking Acceleration:EU MDR's emphasis on clinical evidence for training equipment rewards vendors with preemptive validation studies, opening tender access across German, French, and Italian medical school procurement channels.
Industry Challenges
- Biomechanical Validation Expertise Gap:Vendors struggle to recruit engineers with simultaneous expertise in soft-tissue mechanical modeling and medical education pedagogy, slowing product development timelines.
- Legacy LMS Integration Complexity:Hybrid trainers must interface with existing learning management systems for competency tracking, requiring costly custom API development for each institutional deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abdominal Open and Closure Trainer Market |
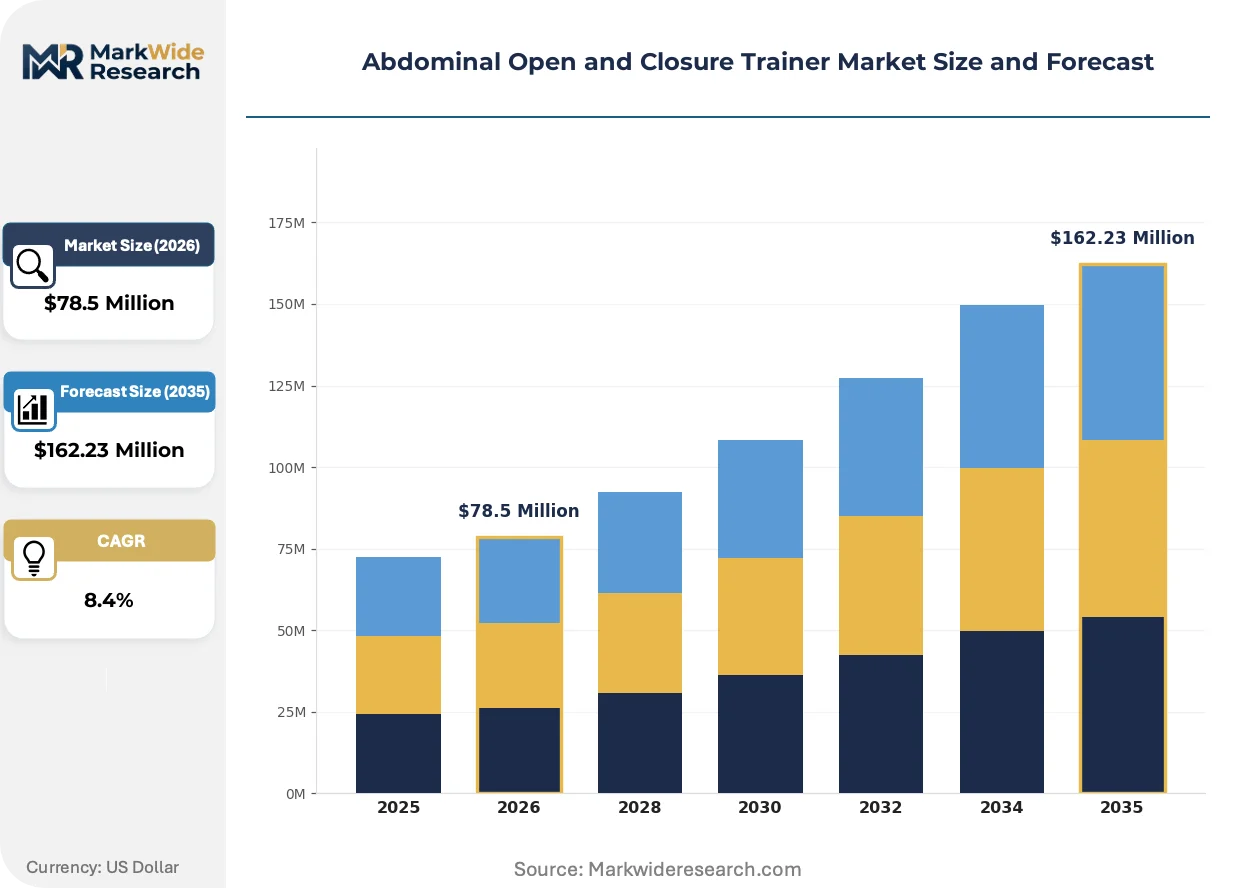
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $162.23 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Trainers, Closure Trainers, Hybrid Models, Endoscopic Trainers Application: Medical Education, Surgical Training, Simulation Practice, Disaster Response Technology: VR Simulation, Augmented Reality, Haptic Feedback, Basic Models End User: Medical Schools, Hospitals, Private Clinics, Research Institutions |
| Companies Covered | Medtronic, Teleflex Incorporated, ACell Inc., neoSurgical, AbSolutions Med, Inc., Suturion AB, Limbs & Things, AbClo Medical, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abdominal Open and Closure Trainer Market Trends and Innovations
Digital performance telemetry is embedding into physical simulation devices, transforming trainers from passive practice tools into data-generating assessment platforms. This convergence redefines value capture toward software-enabled recurring revenue.
Force-sensing matrices layered beneath synthetic tissue analogs is expanding into residency programs seeking quantified suture tension metrics. United States academic medical centers adopt these configurations fastest, replacing legacy models without haptic feedback. The technology is expanding into standardized assessment protocols that residency directors use for milestone verification.
EU MDR's tightened clinical evidence requirements for training equipment now demand peer-reviewed validation studies for CE marking renewal. Vendors must maintain active clinical collaborations with European surgical departments to sustain market access. German medical school tenders increasingly specify MDR-compliant documentation as a mandatory evaluation criterion.
Subscription-based consumable replacement programs are displacing traditional capital purchase models for fascial layer components. United States hospital procurement departments favor predictable operational expenditure structures over lump-sum equipment outlays. This pattern concentrates most visibly in multi-site residency networks seeking standardized trainer configurations across distributed training locations.
Abdominal Open and Closure Trainer Market Segmentation
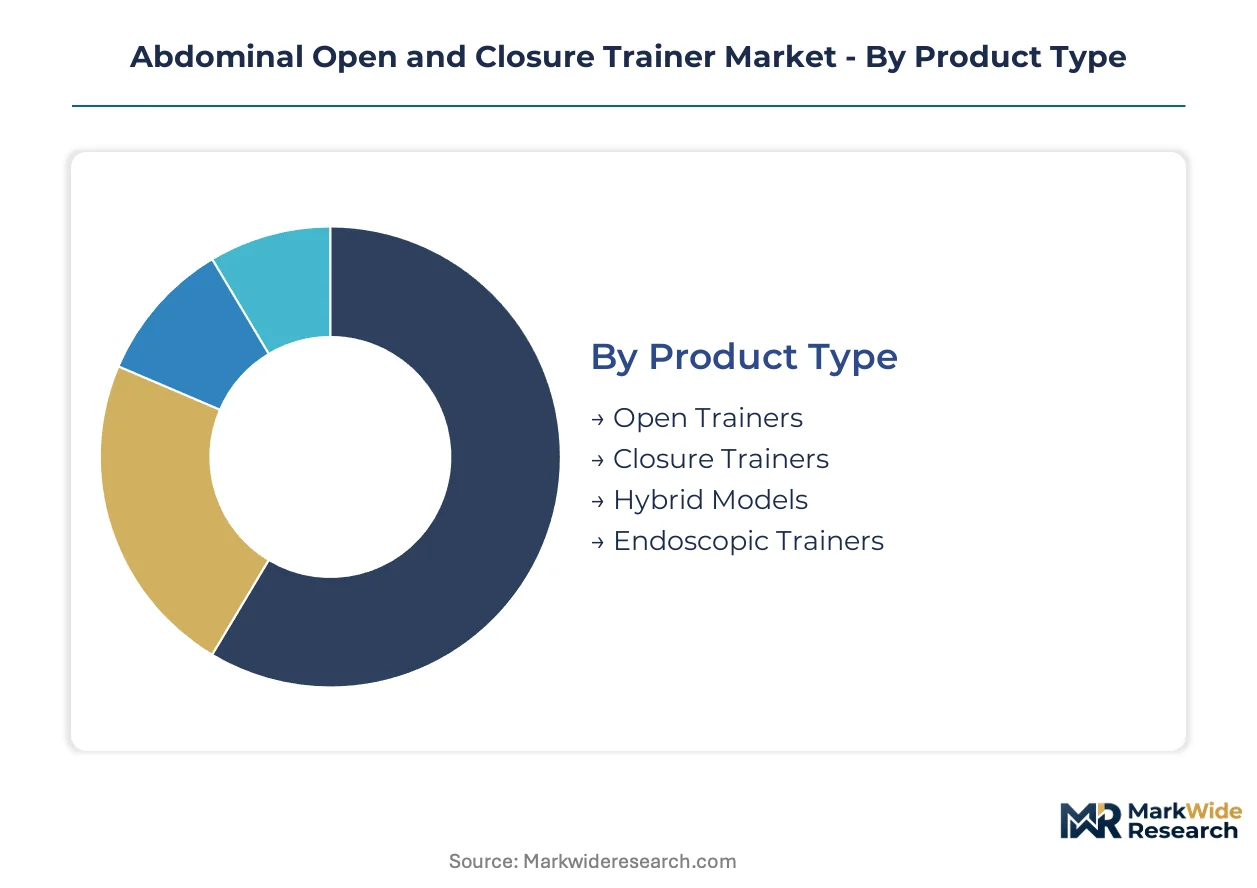
Trainer procurement splits sharply between capital-intensive hybrid systems for academic medical centers and disposable-focused basic models for distributed training sites. Segmentation reveals how technology tier, application intensity, and institutional budget tier reshape vendor go-to-market priorities across procurement channels.
Product Type:
Volume concentrates in entry-level physical trainers, while premium capture belongs to sensor-integrated hybrid architectures with embedded assessment capabilities.
- Open Trainers:Physical simulation devices replicate full abdominal wall anatomy for repeated incision practice. Demand clusters in United States medical schools where general surgery residency programs require layered fascial dissection repetition. Procurement specifications prioritize replaceable tissue pads over integrated electronics.
- Hybrid Models:These configurations merge physical tissue analogs with force-sensing matrices and digital performance telemetry. United States academic medical centers drive replacement cycles here as accreditation standards mandate objective competency verification. Premium positioning reflects haptic feedback integration and LMS connectivity requirements.
- Closure Trainers:Specialized devices focus on layered fascial approximation, subcuticular closure, and tension-free repair techniques.
- Endoscopic Trainers:Laparoscopic skill platforms incorporate trocar insertion, camera navigation, and port closure simulation.
Today's leader: Hybrid Models. Tomorrow's challenger: Open Trainers.
Application:
Medical education absorbs the bulk of institutional procurement, though disaster response and remote simulation are carving distinct specification profiles.
- Medical Education:Undergraduate and graduate medical training programs deploy trainers for milestone-based competency progression. German medical school tenders increasingly specify MDR-compliant documentation and peer-reviewed validation studies as mandatory evaluation criteria.
- Surgical Training:Residency and fellowship programs require repetitive practice infrastructure for incision, closure, and repair technique refinement. United States Graduate Medical Education funding shifts toward distributed training sites, creating demand for portable configurations outside major academic medical centers.
- Simulation Practice:Standalone skill repetition without formal curriculum integration.
- Disaster Response:Mobile training units for field surgical team preparation.
Medical Education commands current procurement volume; Surgical Training shows the steepest expansion trajectory as competency verification mandates tighten.
Technology:
Physical-digital convergence defines competitive positioning, with haptic-enabled systems capturing premium budgets and VR platforms threatening substitution at the margin.
- Haptic Feedback:Sensor arrays beneath synthetic tissue layers quantify suture tension, tissue manipulation force, and instrument trajectory. United States residency directors adopt these configurations fastest for milestone verification protocols. Force-sensing matrices enable objective resident assessment that basic physical models cannot provide.
- VR Simulation:Fully virtual platforms eliminate physical consumables and enable scalable remote training infrastructure. Budget-constrained settings and multi-site residency networks favor this trajectory for operational expenditure predictability.
- Augmented Reality:Overlay systems project anatomical guidance onto physical trainers.
- Basic Models:Passive physical simulation without integrated electronics or data capture.
Haptic Feedback dominates replacement demand; VR Simulation climbs the fastest as programs seek distributed training scalability.
End User:
Institutional scale and accreditation exposure determine technology tier selection, with research institutions driving experimental configurations and hospitals prioritizing operational reliability.
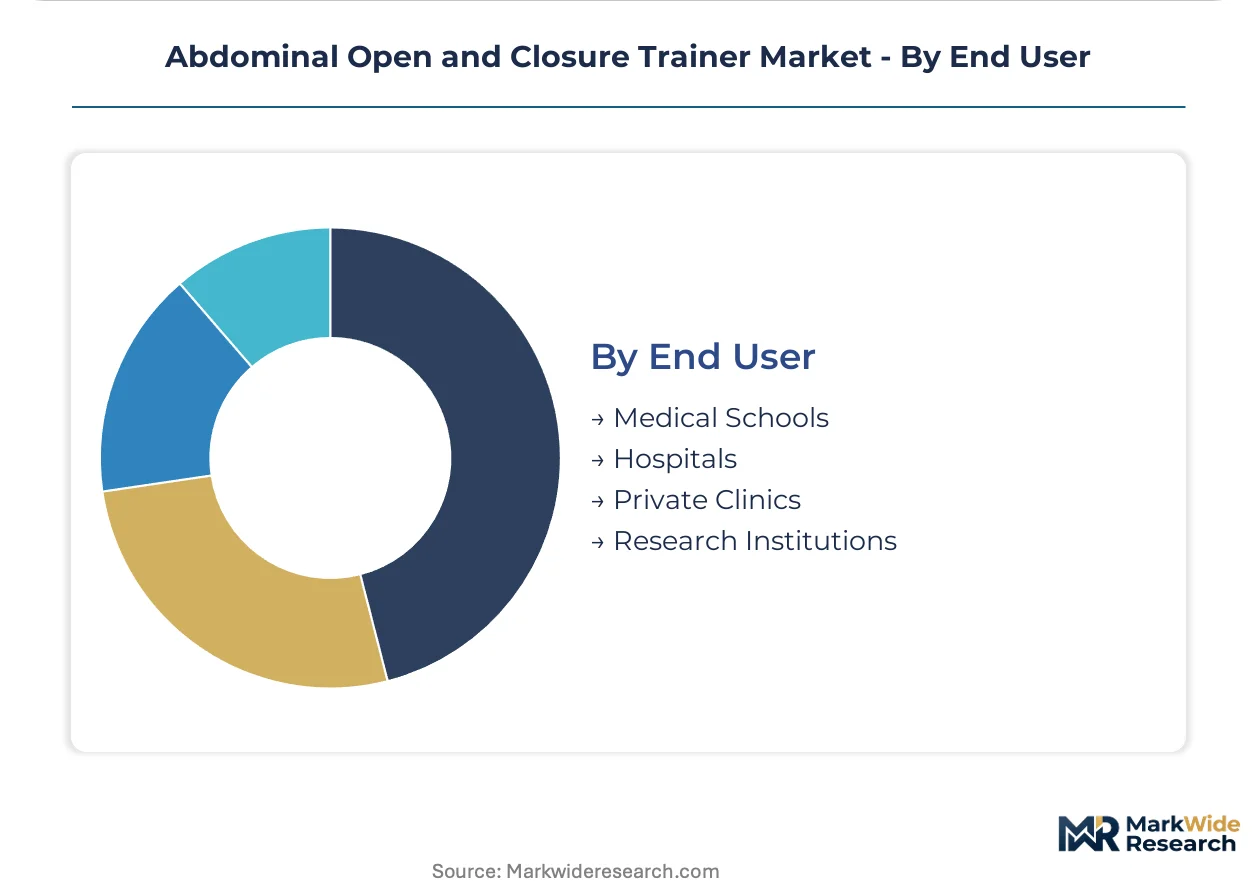
- Medical Schools:Primary procurement channel for entry-level and mid-tier trainers. Japanese medical schools are expanding haptic-enabled hybrid procurement alongside United States and German counterparts. Curriculum integration requirements favor modular architectures with detachable fascial layers.
- Hospitals:Academic medical centers and community hospitals deploy trainers for residency rotations and continuing medical education. United States hospital procurement departments increasingly favor subscription-based consumable replacement programs over lump-sum capital outlays.
- Private Clinics:Limited-volume procurement for individual practitioner skill maintenance.
- Research Institutions:Experimental platform development and validation study execution.
Medical Schools anchor current volume; Hospitals represent the fastest-growing procurement channel as residency network standardization requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical simulation training originated in academic medical centers across the United States and Germany during the 1990s, establishing procurement patterns that now propagate through residency accreditation networks worldwide.
United States
Academic medical centers in Boston and New York drive replacement cycles for haptic-enabled hybrid trainers as the Accreditation Council for Graduate Medical Education mandates simulation-based competency verification. FDA 510(k) clearance requirements accelerate vendor product launches while compressing validation timelines. Procurement concentrates in the Northeast corridor where residency program density creates clustered demand for objective skill assessment platforms.
Germany
Medical schools in Bavaria and Baden-Württemberg specify EU MDR-compliant documentation as mandatory tender evaluation criteria, filtering vendor participation. The country's national pharmaceutical regulator enforces tightened clinical evidence standards for training equipment CE marking renewal. Stuttgart-based surgical equipment clusters anchor European validation study execution for vendors seeking preemptive compliance positioning.
Japan
Tokyo and Osaka medical schools expand haptic-enabled hybrid procurement alongside curriculum modernization initiatives. METI standards for medical device quality management intersect with institutional procurement filters requiring ISO 13485 certification. The Kanto region's concentration of university hospitals creates standardized purchasing consortiums that aggregate trainer demand across multiple residency programs.
United Kingdom
London and Southeast England academic centers prioritize modular trainer architectures with detachable fascial layers for curriculum integration flexibility. MHRA regulations governing medical device market access align with institutional quality management requirements. The Midlands region's emerging medical education technology cluster attracts vendor validation partnerships seeking European clinical evidence generation.
Australia
New South Wales and Victoria residency programs adopt portable trainer configurations for distributed training site expansion under Graduate Medical Education funding shifts. TGA medical device regulations establish baseline quality management expectations for institutional procurement. Melbourne's biomedical manufacturing precinct hosts regional distribution infrastructure serving Pacific Rim medical school networks.
Abdominal Open and Closure Trainer Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established hospital contracting infrastructure. Vendor positioning fragments across three tiers: premium hybrid systems with embedded assessment capabilities, mid-range physical trainers with modular consumable architectures, and economy basic models for resource-constrained settings. Dominant competitive moves include strategic bundling of trainers with complementary surgical consumables and preemptive clinical validation investments to satisfy tightening regulatory documentation requirements.
Within the diversified conglomerate tier, Medtronic leverages hospital contracting infrastructure to bundle trainers with suture and mesh portfolios, while Johnson & Johnson occupies a position anchored in institutional relationships with academic medical centers. Limbs & Things exemplifies the specialized anatomical precision archetype, anchoring European medical school tenders through tissue analog expertise. These three entities represent distinct strategic postures: contracting scale, institutional relationship depth, and anatomical engineering specialization.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex Incorporated |
| ACell Inc. |
| neoSurgical |
| AbSolutions Med, Inc. |
| Suturion AB |
| Limbs & Things |
| AbClo Medical |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Subscription-based consumable replacement programs across United States hospital procurement departments are forcing supply chain reconfiguration toward recurring fulfillment infrastructure, compressing margins on one-time capital equipment while elevating lifetime value capture for vendors with modular architectures.
Pricing Analysis
Three-tier pricing structure across premium haptic-enabled systems, mid-range modular trainers, and economy basic models anchors the market. Price differentiation stems from FDA 510(k) clearance status and ISO 13485 certification tier, with academic medical centers least sensitive and rural distributed training sites most sensitive to cost. Pricing pressure intensifies in the mid-tier as VR simulation platforms offer operational expenditure predictability that physical trainers cannot match.
Supply Chain Analysis
Freight cost volatility from East Asian chemical manufacturing clusters to North American and European medical school networks elevates landed costs for silicone polymer-dependent tissue analogs. Production concentrates in China, South Korea, and Germany, with medical-grade silicone and force-sensing matrices as critical inputs. Single-source vulnerability in specialty sensor components threatens fulfillment timelines. Distribution runs through hospital GPO contracts and direct academic medical center procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has entered a late-cycle quality phase where EU MDR clinical evidence mandates and ACGME competency verification standards filter out undifferentiated suppliers, rewarding vendors with preemptive validation investments and haptic-integrated assessment platforms.
For Market Incumbents: Anticipate VR simulation substitution threats by deepening software telemetry capabilities that virtual platforms cannot replicate, and secure backward integration into medical-grade silicone supply to defend margin position against petrochemical input volatility. Preemptive clinical validation investments with European surgical departments create regulatory moats as EU MDR renewal cycles intensify. For New Entrants and Emerging Players: The price-point gap between premium hybrid systems and economy basic models opens white-space in portable mid-tier configurations for United States rural residency expansion and Japanese medical school consortium tenders. Target modular architectures with detachable fascial layers to capture subscription replacement revenue without competing head-to-head on haptic integration. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized anatomical engineering firms possessing active European validation partnerships and ISO 13485 certification infrastructure already embedded. Long-term viability favors acquisition targets with software-enabled recurring revenue models over pure hardware manufacturers. The signal to watch is ACGME accreditation standard revisions that mandate objective skill assessment protocols.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Validation Partnership | Preemptive peer-reviewed study execution with German surgical departments secures CE marking renewal pathways. |
| Haptic Telemetry Software Development | Force-sensing matrix integration with LMS connectivity differentiates hybrid trainers from VR substitution threats. |
| Modular Consumable Subscription Program | Detachable fascial layer replacement cycles convert capital expenditure to predictable operational revenue streams. |
| Hospital GPO Contracting Infrastructure | Established purchasing agreements with United States academic medical centers accelerate trainer bundling with surgical consumables. |
| ISO 13485 Quality Management Certification | Baseline procurement filter compliance unlocks institutional tender eligibility across Japanese and European medical school networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with residency program directors, hospital procurement managers, biomedical engineering leads, and surgical simulation curriculum designers with secondary validation against FDA 510(k) filings, EU MDR documentation databases, hospital GPO contract records, and medical school tender specifications. Bottom-up vendor shipment estimates and top-down institutional budget allocation analysis provided triangulation checks.
Comparable-period anchoring aligned the projection horizon against historical procurement cycle data and regulatory implementation timelines across the analysis window. Segmentation modeling incorporated product type tier, technology integration level, end-user institutional scale, and regional accreditation mandate intensity. CAGRs derived from installed base replacement dynamics and new program expansion trajectories, with specific weighting for haptic feedback adoption curves and VR simulation penetration rates in distributed training networks.
Caveats apply where ACGME accreditation standard revisions, EU MDR enforcement intensity shifts, or silicone polymer supply disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory mandate continuity and institutional budget stability that may not hold across all geographies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare
Belgium Pharmaceutical Market
Healthcare
Surgical Procedures Volume Market
Healthcare
Global Breast Pumps Market
Healthcare
Physiological Saline Market
Healthcare
Global Hypoparathyroidism Treatment Market
Healthcare
Hospital Acquired Disease Testing Market
Healthcare
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Healthcare
Cardiovascular Pledgets Market
Healthcare
Viral Molecular Diagnostics Market
Healthcare
Wound Care Biologics Market
Healthcare
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Healthcare
Global Pipette Tips Market
Healthcare
Insulin Resistance Market
Healthcare
Global Women's Health Diagnostics Market
Healthcare
Global Telepharmacy Market
Healthcare
United Kingdom (UK) Diabetes Drugs Market