
 Cystoscopy Needles Market | 2026-2036
Cystoscopy Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Cystoscopy Needles Market Analytics
The cystoscopy needle category is recalibrating around a widening split between premium reusable systems and commodity disposables. Laborie Medical leverages its urology-focused portfolio to dominate high-margin integrated delivery platforms. Stryker anchors its position through surgical technology bundling that extends beyond standalone needle sales. Cook Medical competes on procedural workflow specialization across outpatient and inpatient settings.
Cystoscopy needles are slender, rigid or semi-rigid instruments typically 21-25 gauge in diameter, designed for transurethral passage alongside or through a cystoscope to deliver diagnostic or therapeutic access to the bladder wall and urethral mucosa. Stainless steel biopsy needles retain the largest installed base due to durability and reprocessing economics, though coated needles and disposable material variants are capturing faster growth in infection-sensitive settings. Hospitals remain the dominant end user by procedure volume, while ambulatory surgical centers represent the fastest-expanding channel as same-day cystoscopy protocols proliferate.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for manufacturers. ISO 13485 quality management certification has become table stakes for supply contracts with integrated delivery networks. Stakeholders must monitor how reimbursement shifts toward outpatient settings reshape purchasing criteria across health systems.
Market Dynamics
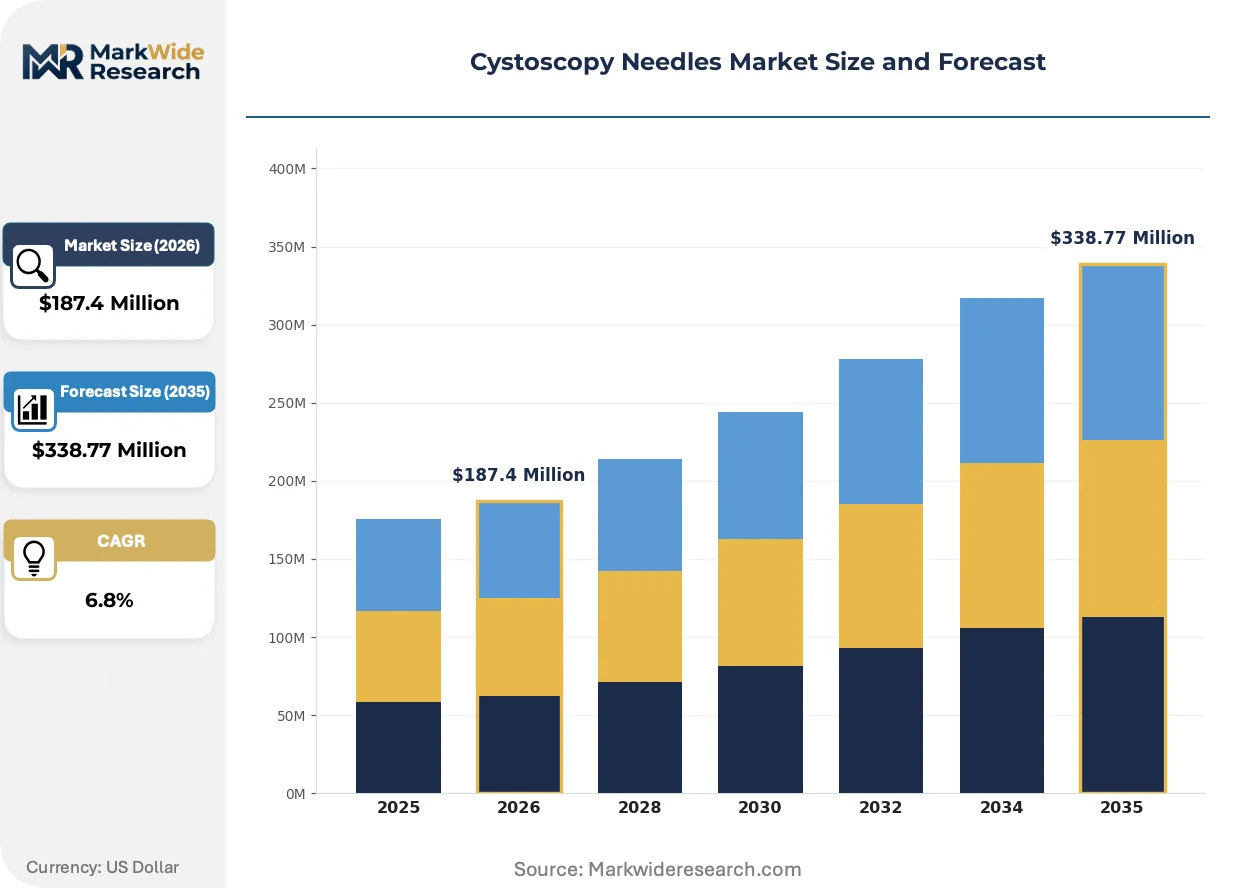
The cystoscopy needle market is restructuring around a fundamental tension between outpatient migration and escalating regulatory compliance burdens. Same-day cystoscopy protocols are compressing hospital purchasing cycles while EU MDR technical documentation requirements extend product development timelines by 12-18 months.
Growth Catalysts
- EU MDR Conformity Assessment:Stricter clinical evidence requirements for Class IIa devices are filtering out marginal suppliers and consolidating procurement around certified manufacturers with robust quality management systems.
- Ambulatory Surgical Center Expansion:Germany's ASC networks are adding dedicated urology suites, creating concentrated demand pockets for disposable needle configurations optimized for high-throughput settings.
- Coated Needle Materials:Hydrophilic and PTFE-coated variants are capturing preference in infection-sensitive procedural environments where reprocessing economics favor single-use instruments.
Market Restraints
- Stainless Steel Input Volatility:Medical-grade 304 and 316L stainless pricing fluctuates with nickel and molybdenum commodity markets, compressing margin stability for reusable instrument manufacturers.
- Supply Concentration in German Precision Manufacturing:Critical cannula grinding and tip-forming capabilities cluster in Baden-Württemberg and Bavaria, creating geographic vulnerability to regional logistics disruptions.
- Reusable System Durability:Extended instrument lifecycles of 50-100 reprocessing cycles delay replacement demand and cap volume expansion in mature hospital accounts.
Strategic Opportunities
- Underpenetrated Polish Outpatient Sector:Poland's nascent ASC regulatory framework and reimbursement liberalization for same-day urology procedures offer first-mover positioning ahead of market maturation.
- Integrated Cystoscopy-Needle Delivery Platforms:Convergence of optical imaging with precision injection systems enables premium bundling strategies that escape commodity pricing pressure in standalone needle segments.
- French Hospital-Acquired Infection Prevention Mandates:National targets for reducing catheter-associated urinary tract infections are accelerating preference shifts toward single-use, sterile-packaged needle configurations.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies face contracted laboratory capacity, extending time-to-market for material innovations.
- Legacy Sterilization Infrastructure Integration:Hospitals with entrenched ethylene oxide or steam sterilization workflows resist workflow redesigns required for novel low-temperature sterilization-compatible needle designs.
- Needle Tip Geometry Standardization Delays:Absence of harmonized international standards for bevel angles and cutting edge specifications complicates cross-border product registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cystoscopy Needles Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy Needles, Injection Needles, Aspiration Needles, Flow Control Needles End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Research Laboratories Material: Stainless Steel, Plastic, Disposable Materials, Coated Needles Application: Diagnostics, Therapeutic Procedures, Biopsies, Fluid Drainage |
| Companies Covered | Laborie Medical, Stryker, Coloplast, Richard Wolf, Cook Medical, Karl Storz, HOYA, Boston Scientific Corporation, Ambu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cystoscopy Needles Market Evolving Landscape
Active innovation in cystoscopy needles centers on material science advances, regulatory harmonization pressures, and procurement model restructuring. These forces are compressing traditional product lifecycles while opening new competitive dimensions beyond unit economics.
Coated needle technologies are converging with single-use procedural economics. Hydrophilic polymer coatings reduce tissue friction during transurethral passage, enabling smoother injection trajectories in delicate bladder wall procedures. Outpatient urology clinics in Germany and the Netherlands are adopting these variants at accelerated rates. This convergence is compressing the addressable market for traditional uncoated stainless configurations and forcing manufacturers to recalibrate production mix toward higher-margin coated SKUs.
EU MDR Article 10 technical documentation requirements are reshaping competitive access. Manufacturers must now submit clinical evaluation reports with post-market surveillance data for needle device families, elevating compliance costs disproportionately for smaller suppliers. Class IIa reclassification of certain biopsy needle configurations has extended notified body review timelines. German and French health technology assessment bodies are incorporating MDR conformity certificates into hospital tender scoring, advantaging incumbent players with established regulatory infrastructure.
Hospital procurement departments are consolidating urology consumable purchasing through integrated delivery network frameworks. Bundled contracting for cystoscopes, needles, and irrigation systems is displacing standalone needle RFPs in US academic medical centers and European hospital groups. This consolidation is most visible in Spain's regional health service procurement consortia, where multi-hospital tenders now specify single-source platform agreements rather than discrete instrument categories.
Cystoscopy Needles Market Segmentation
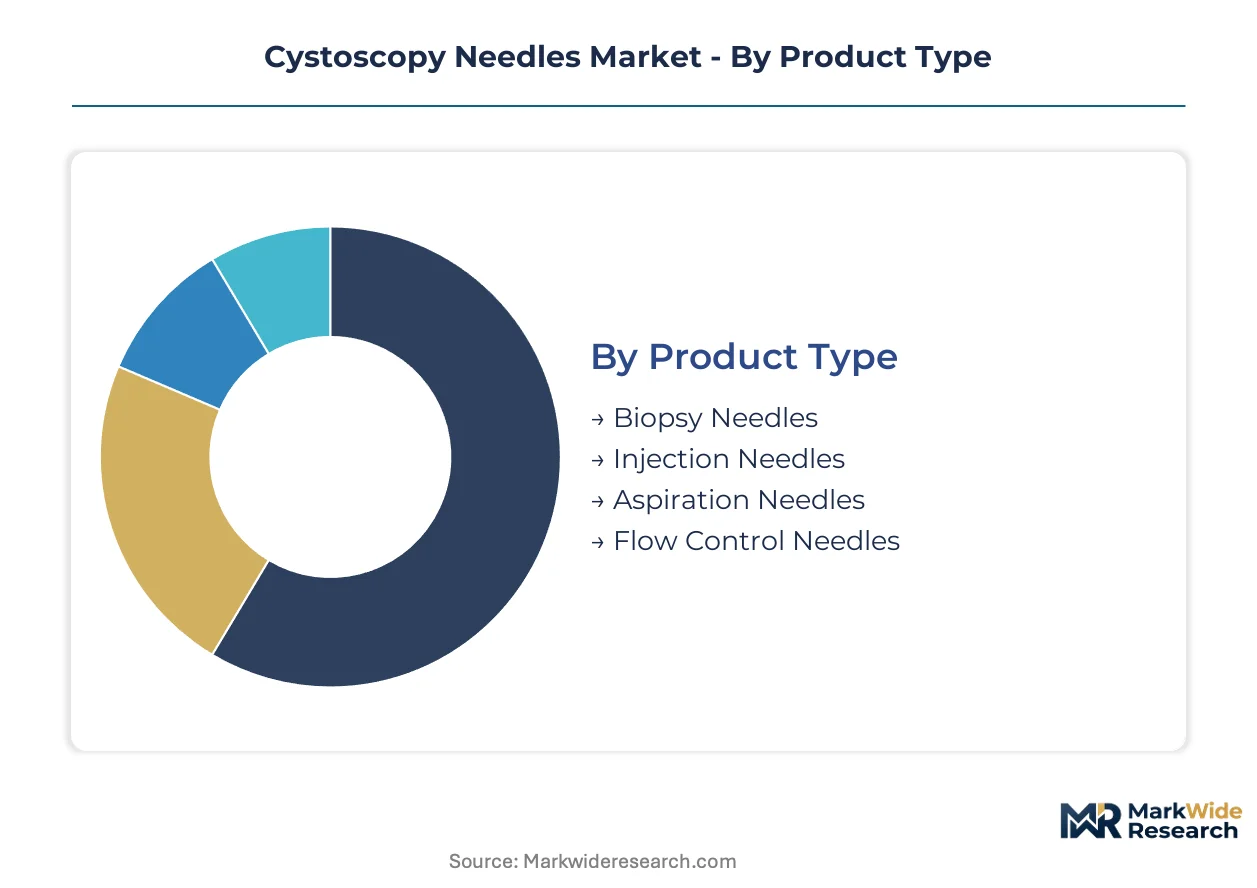
Cystoscopy needle purchasing decisions diverge sharply between capital-intensive hospital systems prioritizing instrument durability and high-throughput outpatient settings optimizing for turnover speed. Segmentation mapping reveals where margin concentration aligns with procedural volume expansion.
Product Type:
Clinicians select needle configurations based on whether the procedure demands tissue extraction, pharmaceutical delivery, or fluid management.
- Biopsy Needles:These rigid stainless steel instruments feature precision-ground cutting edges for transurethral bladder wall tissue sampling. Demand clusters in German academic medical centers where histopathological confirmation drives diagnostic protocols for hematuria workups.
- Injection Needles:Slender 21-25 gauge delivery systems enable submucinal pharmaceutical administration during cystoscopic surveillance. Outpatient urology suites in the Netherlands favor hydrophilic-coated variants for reduced tissue trauma in high-frequency surveillance cystoscopy programs.
- Aspiration Needles:Hollow-bore configurations designed for cyst fluid extraction and cytological sampling.
- Flow Control Needles:Specialized cannulae managing irrigation pressure during extended procedural sequences.
Biopsy Needles lead on scale; Injection Needles lead on momentum.
End User:
Facility reimbursement structures determine whether procurement favors reusable capital equipment or disposable convenience.
- Hospitals:Integrated delivery networks with captive sterilization infrastructure amortize instrument costs across high procedural volumes. These accounts dominate premium reusable system procurement in France and Germany.
- Ambulatory Surgical Centers:Same-day discharge protocols in Germany's expanding ASC networks are accelerating preference for sterile-packaged disposable configurations that eliminate reprocessing bottlenecks.
- Outpatient Clinics:Independent urology practices with limited capital budgets.
- Research Laboratories:Specialized procurement for preclinical and translational studies.
Hospitals anchor revenue concentration; Ambulatory Surgical Centers are climbing the fastest.
Material:
Raw material selection trades off durability economics against infection prevention mandates.
- Stainless Steel:Medical-grade 304 and 316L alloys deliver 50-100 reprocessing cycles with maintained tip geometry. German hospital procurement consortia specify these for high-volume academic centers with established sterilization workflows.
- Coated Needles:Hydrophilic polymer and PTFE surface treatments reduce friction coefficients by 40-60 percent during transurethral passage. French infection control mandates are accelerating single-use coated needle preference in catheter-associated UTI reduction programs.
- Plastic:Polymer-based configurations for cost-sensitive disposable applications.
- Disposable Materials:Comprehensive single-use sterile packaging for ASC environments.
Stainless Steel retains installed base dominance; Coated Needles gain share fastest.
Application:
Procedural intent shapes whether needles serve diagnostic confirmation or interventional therapy.
- Diagnostics:Tissue acquisition and cytological sampling for malignancy detection. German statutory health insurance reimbursement frameworks prioritize histopathological confirmation, concentrating demand in hospital-based urology departments.
- Therapeutic Procedures:Botulinum toxin injection and pharmaceutical delivery for overactive bladder management. Outpatient clinics in Bavaria are expanding these services as same-day therapeutic cystoscopy protocols proliferate.
- Biopsies:Specific tissue extraction procedures for histological analysis.
- Fluid Drainage:Cyst aspiration and irrigation management applications.
Diagnostics commands volume concentration; Therapeutic Procedures show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters anchor the European cystoscopy needle supply base, with specialized grinding and tip-forming capabilities concentrated in Baden-Württemberg and Bavaria.
United States
FDA 510(k) clearance pathways shape market access timelines for new entrants. Academic medical centers in Boston and the Research Triangle are consolidating urology consumable purchasing through integrated delivery network frameworks. Ambulatory surgical center expansion in Florida and Texas is accelerating demand for sterile-packaged disposable configurations.
Germany
EU MDR conformity assessment requirements are filtering out marginal suppliers and consolidating procurement around certified manufacturers. Statutory health insurance reimbursement frameworks prioritize histopathological confirmation, concentrating diagnostic needle demand in hospital-based urology departments. The Stuttgart and Munich metropolitan regions host critical cannula grinding capabilities serving European OEMs.
France
ANSM infection control mandates are accelerating preference shifts toward single-use, sterile-packaged needle configurations in catheter-associated UTI reduction programs. Health technology assessment bodies are incorporating MDR conformity certificates into hospital tender scoring. The Lyon-Grenoble corridor supports precision instrument manufacturing for urology applications.
Netherlands
Outpatient urology suites in Amsterdam and Rotterdam are adopting hydrophilic-coated needle variants at accelerated rates for reduced tissue trauma in high-frequency surveillance cystoscopy programs. The country's centralized procurement consortia favor platform bundling over standalone needle tenders. Eindhoven's medical technology cluster drives coating technology innovation.
Poland
A nascent ASC regulatory framework and reimbursement liberalization for same-day urology procedures offer first-mover positioning ahead of market maturation. The country's central bank monitors healthcare infrastructure investment flows into outpatient surgical capacity. Warsaw and Krakow are emerging as distribution hubs for Central European urology consumables.
Cystoscopy Needles Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the cystoscopy needle category. The market structure tilts toward consolidation at the premium integrated platform tier while fragmenting among commodity disposable suppliers. Three archetypes dominate: diversified surgical technology conglomerates bundling needles within endoscopy ecosystems; specialized urology-focused instrument manufacturers; and regional precision metalworking firms supplying cannula components. Competitive moves center on M&A for regulatory infrastructure acquisition and strategic partnerships for coating technology access.
Among diversified surgical technology conglomerates, Stryker and Boston Scientific Corporation occupy positions anchoring premium platform bundling strategies. Laborie Medical exemplifies the urology-focused specialist archetype, while Cook Medical represents procedural workflow specialization across outpatient and inpatient settings. These named companies illustrate how competitive positioning diverges between integrated delivery platform providers and standalone instrument specialists.
| Leading Market Players |
|---|
| Laborie Medical |
| Stryker |
| Coloplast |
| Richard Wolf |
| Cook Medical |
| Karl Storz |
| HOYA |
| Boston Scientific Corporation |
| Ambu |
| Others |
Value Network & Pricing Analysis
Hydrophilic coating technology adoption is compressing cost structures for single-use configurations while concentrating procurement leverage among German ASC networks that negotiate volume-based sterilization exemptions. This dual shift simultaneously elevates margin pressure on uncoated stainless steel suppliers and rewards manufacturers with captive coating capabilities in Baden-Württemberg.
Pricing Analysis
Bundled platform contracts versus standalone needle tenders splits cystoscopy needle pricing into divergent models. Three-tier pricing structure across premium integrated systems, standard coated disposables, and economy uncoated configurations dominates hospital procurement in Germany and France. Price differentiation hinges on EU MDR certification tier and sterilization workflow compatibility. Cost compression in economy stainless steel segments is intensifying because nickel and molybdenum commodity volatility erodes reprocessing economics. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement caps, while academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Precision grinding specialist availability constrains capacity expansion in Baden-Württemberg and Bavaria, where medical cannula tip-forming expertise clusters around Stuttgart and Munich. Manufacturing draws from medical-grade 304 and 316L stainless steel feedstock, hydrophilic polymer coating inputs, and sterile packaging materials. Single-source vulnerability concentrates in specialized grinding equipment dependent on Swiss and German machine tool suppliers. Distribution runs through integrated delivery network procurement consortia in Spain and France, with direct manufacturer relationships dominating German hospital system contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance cost differentials between established German manufacturers and Polish assembly operations create geographic-arbitrage opportunities for capital-light entrants targeting Central European ASC expansion.
For Market Incumbents: Extend regulatory infrastructure advantages by acquiring notified body relationships and MDR technical documentation libraries from distressed mid-tier suppliers. Consolidate coating technology capabilities through backward integration into polymer formulation to defend margin position against commodity stainless steel competitors. Prioritize capacity addition in Poland to capture reimbursement liberalization momentum before local manufacturing ecosystems mature. For New Entrants and Emerging Players: Launch via direct-to-ASC distribution partnerships bypassing entrenched hospital GPO contracts in Germany. Target Poland's nascent outpatient urology sector where regulatory frameworks favor first-mover sterile packaging suppliers. Pursue white-label manufacturing arrangements with Baden-Württemberg precision metalworkers lacking coating capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among regional precision metalworking firms with cannula grinding expertise but absent EU MDR certification infrastructure. Long-term viability over the next decade hinges on successful MDR transition completion and coating technology access. Watch Polish ASC reimbursement rate announcements as the critical inflection signal for Central European demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Notified body relationships filter market access to certified manufacturers in Germany and France. |
| Hydrophilic Coating Technology Partnership | Polymer formulation alliances enable premium SKU migration away from commodity stainless configurations. |
| Polish Distribution Infrastructure Buildout | First-mover sterile packaging positioning captures ASC regulatory liberalization ahead of local competition. |
| Integrated Delivery Network Contracting | Platform bundling with cystoscope manufacturers displaces standalone needle tenders in Spanish hospital consortia. |
| Precision Grinding Capacity Expansion | Baden-Württemberg equipment investments address bottleneck in cannula tip-forming capabilities. |
Research Methodology
Coverage spans Germany, France, the Netherlands, Poland, and the United States, with primary inputs from each market gathered through structured interviews with urology department heads, ASC operations directors, hospital procurement committee members, and biomedical engineering specialists. Secondary validation draws from FDA 510(k) filings, EU MDR notified body registers, hospital procurement database extracts, and German statutory health insurance reimbursement schedules. Bottom-up procedure volume modeling triangulates against top-down manufacturer revenue assessments.
Granularity-level modeling operates at the product-type, end-user facility category, material composition, and application intent dimensions across the analysis window. CAGRs derive from logistic curve fitting to procedural volume trajectories with elasticity adjustments for reimbursement regime shifts. Industry-specific forecast inputs incorporate EU MDR transition timelines and Polish ASC regulatory development milestones.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU MDR enforcement or Polish reimbursement reversal scenarios. Projections reflect documented assumptions regarding outpatient migration speed and coating technology cost curves. Material deviation in MDR notified body capacity or Central European healthcare infrastructure investment flows warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Global Bone Wax Market