
 Hydrosurgery Systems Market | 2026-2036
Hydrosurgery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrosurgery Systems Market Analytics
Germany is rewriting the competitive map for hydrosurgery manufacturing as Erbe Elektromedizin GmbH leverages its precision electrosurgical heritage to anchor European supply chains. Smith & Nephew plc sustains a broad orthopedic portfolio that competes across multiple application areas, while Medtronic plc dominates hospital procurement channels through its integrated surgical ecosystem. Arthrex Inc. specializes in sports medicine applications where waterjet precision reduces collateral tissue damage during minimally invasive procedures.
Hydrosurgery systems deploy high-velocity sterile saline jets operating at pressures typically ranging from 300 to 1,000 bar to selectively resect tissue while preserving adjacent structures. Console systems command the largest installed base due to their integration with operating room infrastructure and reusable handpiece economics, though consumables generate recurring revenue streams that outperform capital equipment margins. Hospitals remain the dominant end-user channel, while orthopedic surgery applications attract the fastest procedural growth as surgeons adopt waterjet technology for cartilage debridement and soft tissue resection.
FDA premarket notification requirements and the EU Medical Device Regulation impose divergent clinical evidence burdens that shape product launch sequencing and market access timelines. ISO 13485 quality management standards govern manufacturing consistency across all major supply regions, while national health technology assessment bodies in Germany and France condition reimbursement on demonstrated cost-effectiveness versus conventional modalities. Stakeholders must monitor evolving sterilization validation protocols and single-use accessory regulations that could alter the economics of reusable versus disposable system architectures.
Market Dynamics
Console-based hydrosurgery platforms are displacing standalone units as hospitals prioritize OR integration and reusable handpiece economics over capital flexibility, compressing vendor margins while locking in long-term consumable revenue streams.
Growth Catalysts
- EU MDR harmonization:The Medical Device Regulation's centralized conformity assessment is streamlining cross-border hospital procurement across Germany, France, and the Netherlands, reducing vendor registration friction.
- Ambulatory surgical centers:Freestanding ASCs in Texas and Florida are converting procedure rooms to waterjet-based tissue dissection, drawn by reduced thermal collateral damage and faster patient turnover.
- Saline jet pressure optimization:Advances in pump engineering now deliver 300-1,000 bar precision across variable tissue densities, expanding addressable procedures beyond orthopedic debridement into general surgery.
Market Restraints
- Capital equipment intensity:Console systems require $150,000-$400,000 upfront investment, freezing adoption at mid-tier hospitals with constrained equipment replacement budgets.
- German supply concentration:Precision pump manufacturing clusters around Stuttgart and Tuttlingen, creating single-source vulnerability for pressure-generation subassemblies.
- Laser tissue ablation:Holmium and thulium fiber lasers compete for urological and soft tissue applications, leveraging established reimbursement codes and surgeon familiarity.
Strategic Opportunities
- Japan's aging surgical workforce:METI's healthcare productivity initiatives are incentivizing automation-friendly platforms that reduce hand fatigue during extended cartilage procedures.
- Veterinary orthopedic surgery:Companion animal specialty clinics represent an untapped channel where waterjet precision commands premium pricing for cruciate ligament and joint procedures.
- Single-use handpiece economics:Disposable cartridge architectures bypass sterilization validation burdens while capturing higher per-procedure margins from outpatient settings.
Industry Challenges
- Sterilization validation backlog:FDA 510(k) submissions for reusable handpiece architectures face extended review timelines as the agency tightens bioburden testing standards for saline-contact components.
- OR integration complexity:Legacy electrosurgical setups in established hospitals require costly electrical and fluid management retrofits to accommodate console-based hydrosurgery infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrosurgery Systems Market |
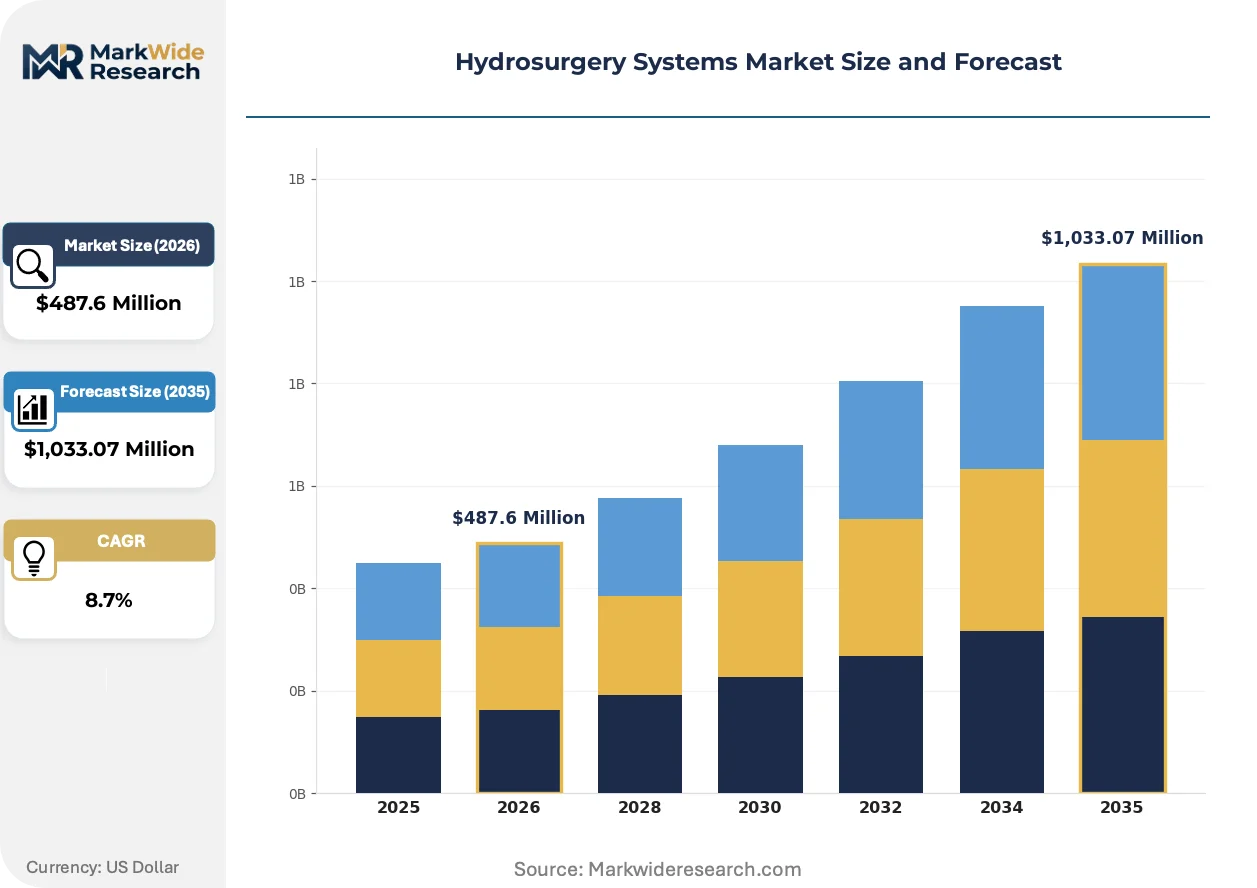
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Console Systems, Accessories, Consumables End User: Hospitals, Surgical Centers, Clinics, Ambulatory Surgical Units Technology: Ultrasound, Laparoscopic, Robotic, Electrosurgical Application: Orthopedic Surgery, Dental Surgery, Cosmetic Procedures, Urological Surgery |
| Companies Covered | Smith & Nephew plc, Erbe Elektromedizin GmbH, HydroCision Inc., Inmito Meditech Pvt. Ltd., Medtronic plc, Johnson & Johnson, BD, Conmed Corporation, Arthrex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrosurgery Systems Market Evolving Landscape
Waterjet tissue interaction modeling is collapsing the gap between open and minimally invasive precision, while regulatory evidence requirements and procurement centralization are simultaneously reshaping how vendors access hospital customers.
Real-time pressure feedback algorithms are collapsing the learning curve for junior surgeons by automating tissue density recognition and jet modulation. Academic medical centers in Boston and Cleveland are piloting these systems for resident training programs, compressing the time required to achieve procedural independence from months to weeks. This capability is collapsing the historical trade-off between precision and speed that limited waterjet adoption beyond subspecialist hands.
The EU Medical Device Regulation's clinical evidence requirements are forcing manufacturers to generate prospective data on tissue-specific outcomes rather than predicate-device equivalence. German notified bodies are demanding extended follow-up for orthopedic debridement procedures, extending time-to-market by 12-18 months for novel indications. Vendors are responding by prioritizing 510(k) pathways in the United States for initial revenue generation while accumulating European datasets.
Hospital procurement departments are consolidating vendor relationships through integrated delivery networks, unbundling equipment purchasing from consumable supply agreements. IDNs in California and Illinois are negotiating multi-year sole-source contracts that lock in saline cartridge pricing while demanding console placement at zero capital cost. This concentration is most visible in the southeastern United States, where regional health systems are standardizing across ambulatory surgery networks to leverage volume-based rebates.
Hydrosurgery Systems Market Segmentation
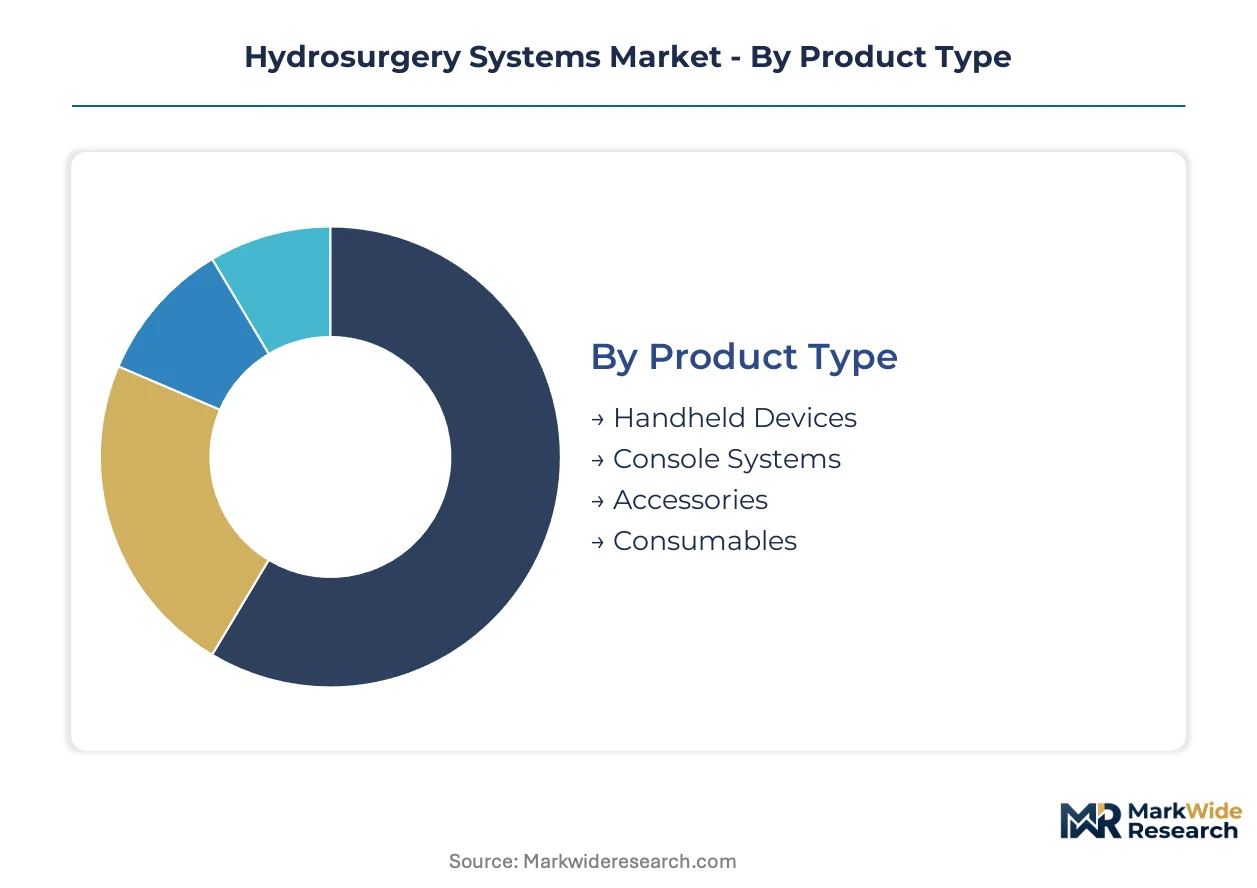
Hydrosurgery systems fragment across four intersecting dimensions that determine procurement economics and clinical deployment. Product architecture dictates capital intensity and recurring revenue mix, while end-user channel selection shapes sterilization protocols and reimbursement pathways. Technology integration and application specificity further stratify vendor positioning across surgical subspecialties.
Product Type:
Console systems anchor high-throughput hospital installations, while handheld variants serve cost-constrained settings and mobile surgical teams.
- Handheld Devices:Battery-powered or pneumatic units deliver 300-600 bar saline jets through pistol-grip ergonomics optimized for field-deployable trauma surgery and veterinary applications. Demand concentrates in rural Texas surgical cooperatives and military medical units where OR infrastructure remains limited.
- Console Systems:Floor-standing platforms integrate pressure-generation pumps, real-time feedback displays, and multi-handpiece docking stations within standardized OR footprints. German hospitals in Stuttgart and Tuttlingen clusters prioritize these units for orthopedic volume centers, locking in 7-10 year consumable supply agreements.
- Accessories:Foot pedals, tubing sets, and filtration modules complete system configurations.
- Consumables:Sterile saline cartridges and single-use handpiece tips generate recurring revenue.
The dominant share belongs to Console Systems, while Consumables is closing the gap fastest through ASC conversion to disposable architectures.
End User:
Channel selection follows reimbursement density and procedure volume concentration across facility types.
- Hospitals:Academic medical centers and community hospitals with 200+ beds deploy console systems across multiple service lines, amortizing capital across orthopedic, general surgery, and wound care departments. Cleveland Clinic and Mayo Clinic campuses standardize on single-vendor platforms to streamline procurement and training standardization.
- Surgical Centers:Multi-specialty ASCs in Florida and Texas convert procedure rooms to waterjet-based dissection for sports medicine and soft tissue procedures, attracted by faster patient turnover and reduced thermal damage liability.
- Clinics:Dermatology and podiatry practices deploy handheld units for limited-scope procedures.
- Ambulatory Surgical Units:Hospital-owned outpatient facilities balance capital constraints against procedural expansion needs.
Hospitals retain the dominant installed base, though Ambulatory Surgical Units are expanding most quickly as IDNs consolidate outpatient networks.
Technology:
Integration modality determines learning curve, capital requirements, and addressable procedure range.
- Ultrasound:Cavitation-enhanced saline jets improve tissue selectivity in dense fibrotic structures. Academic centers in Boston pilot these systems for revision orthopedic cases where scar tissue complicates standard waterjet dissection.
- Laparoscopic:Articulating handpieces with 5mm shaft diameters enable minimally invasive abdominal and thoracic applications. German surgeons at Charité Berlin leverage these platforms for hepatobiliary procedures where thermal spread risks bile duct injury.
- Robotic:Pressure modulation integrates with haptic feedback arms for submillimeter precision.
- Electrosurgical:Hybrid platforms combine saline jets with bipolar energy for hemostasis control.
Laparoscopic configurations command the dominant procedure volume, while Robotic systems are gaining share fastest through da Vinci ecosystem partnerships.
Application:
Clinical indication determines pressure-parameter optimization and regulatory evidence requirements.
- Orthopedic Surgery:Cartilage debridement, meniscal resection, and soft tissue release procedures utilize 600-1,000 bar jets for selective tissue removal without thermal necrosis. German volume hospitals and US sports medicine centers drive procedural adoption as surgeons document faster recovery versus mechanical shavers.
- Dental Surgery:Piezoelectric-enhanced waterjet systems perform bone cutting and implant site preparation with reduced risk of neurovascular injury. Swiss and Japanese dental schools incorporate these platforms into implantology curricula.
- Cosmetic Procedures:Liposuction and body contouring applications leverage lower-pressure jets for adipose tissue emulsification.
- Urological Surgery:Holmium laser competition limits waterjet penetration in prostate and stone procedures.
Orthopedic Surgery holds the dominant revenue position, while Dental Surgery is climbing the fastest as implantology volumes expand across aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification requirements anchor the United States as the dominant geography for hydrosurgery system deployment. Console-based platforms concentrate in high-volume orthopedic centers across Texas and Florida. German precision manufacturing clusters supply critical pressure-generation subassemblies to global vendors.
United States
Ambulatory surgical centers in Texas and Florida drive conversion from electrosurgical tools to waterjet-based tissue dissection systems. FDA 510(k) pathways offer faster initial revenue generation than European regulatory routes. Cleveland Clinic and Mayo Clinic campuses standardize on single-vendor platforms to streamline procurement.
Germany
Precision pump manufacturing clusters around Stuttgart and Tuttlingen anchor European supply chains for pressure-generation subassemblies. EU Medical Device Regulation clinical evidence requirements extend time-to-market by 12-18 months for novel indications. German notified bodies demand extended follow-up for orthopedic debridement procedures.
Japan
METI healthcare productivity initiatives incentivize automation-friendly platforms that reduce hand fatigue during extended cartilage procedures. Aging surgical workforce demographics accelerate adoption of real-time pressure feedback algorithms. Academic medical centers in Tokyo pilot these systems for resident training programs.
United Kingdom
Integrated delivery networks in London and the Southeast negotiate multi-year sole-source contracts for saline cartridge pricing. NHS procurement centralization favors vendors offering zero-capital console placement. Regional health systems standardize across ambulatory surgery networks to leverage volume-based rebates.
Switzerland
Dental schools in Zurich and Geneva incorporate piezoelectric-enhanced waterjet systems into implantology curricula. Swissmedic maintains alignment with EU MDR standards while offering streamlined conformity assessment for innovative devices. Precision manufacturing heritage supports component sourcing for handheld unit producers.
Hydrosurgery Systems Market Competitive Landscape
Integrated surgical ecosystem providers and precision electrosurgical heritage specialists split the market between hospital procurement channel dominance and manufacturing supply chain anchoring. The competitive structure concentrates around vendors with reusable handpiece economics and consumable revenue streams. Three archetypes define positioning: console platform integrators, handheld device specialists, and precision component suppliers. Strategic moves center on multi-year sole-source contract negotiations and single-use handpiece architecture transitions.
Among heritage electrosurgical manufacturers, Erbe Elektromedizin GmbH exemplifies the precision engineering archetype rooted in German manufacturing clusters. Smith & Nephew plc and Medtronic plc occupy positions as diversified surgical portfolio anchors with broad hospital procurement access. Arthrex Inc. represents the subspecialist tier focused on sports medicine applications where waterjet precision reduces collateral tissue damage.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Erbe Elektromedizin GmbH |
| HydroCision Inc. |
| Inmito Meditech Pvt. Ltd. |
| Medtronic plc |
| Johnson & Johnson |
| BD |
| Conmed Corporation |
| Arthrex Inc. |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's container cost dynamics expose how Stuttgart-Tuttlingen manufacturing clusters translate supply concentration into tiered pricing power, while mid-tier hospitals face capital equipment premiums that disposable cartridge architectures partially offset.
Pricing Analysis
German-manufactured console systems command price premiums against Asian-assembled alternatives, with differentiation anchored in ISO 13485 certification tier and precision pump engineering heritage. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales service bundling and reusable handpiece validation status. Pricing pressure stems from laser tissue ablation systems competing for urological procedures with established reimbursement codes. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize OR integration over capital cost.
Supply Chain Analysis
Extended payment terms from German pump manufacturers to console assemblers reveal working capital stress concentrated in pressure-generation subassembly procurement. Precision manufacturing draws from Germany, Switzerland, and the United States for ceramic pump components, high-pressure tubing, and real-time feedback sensors. Single-source vulnerability concentrates around Stuttgart-area precision machining clusters. Distribution runs through integrated delivery networks negotiating multi-year saline cartridge supply agreements with zero-capital console placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
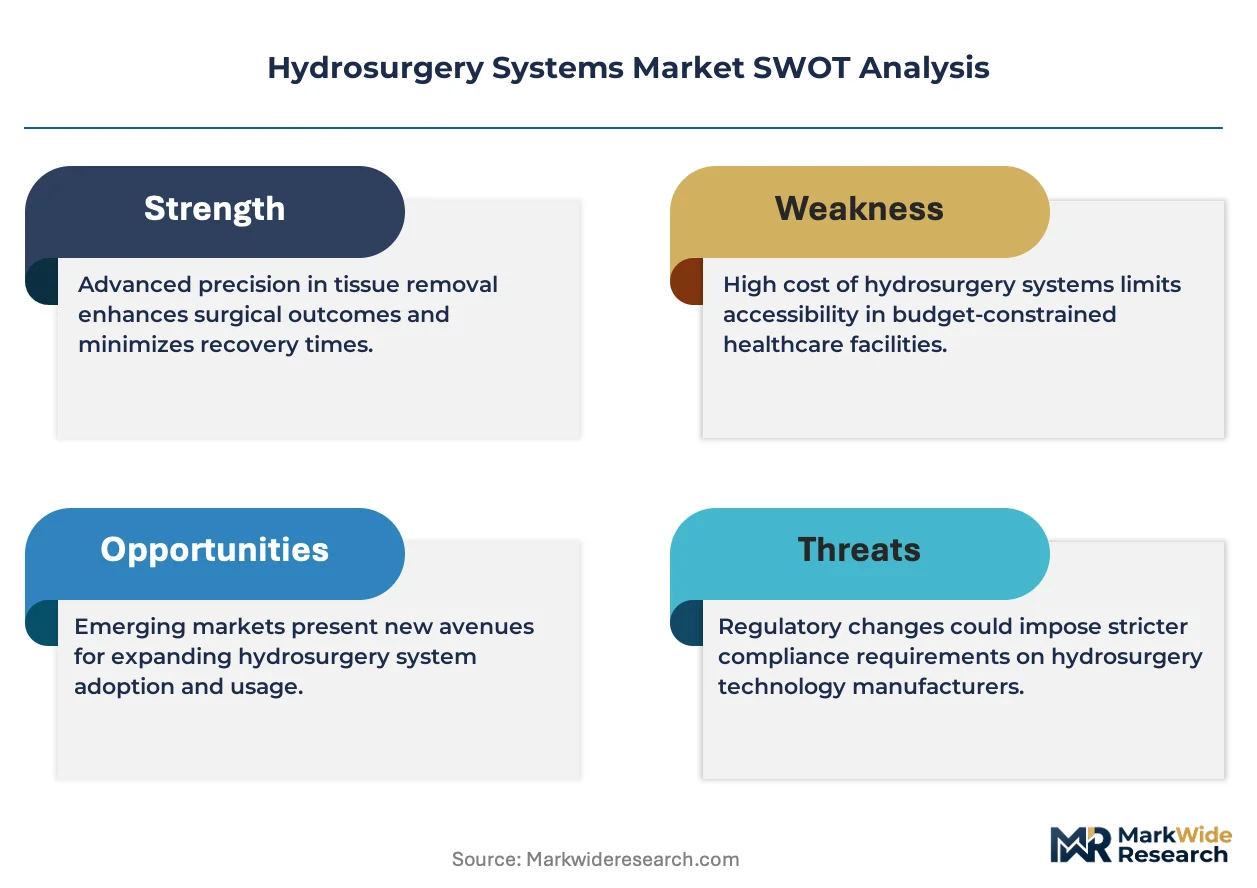
Hydrosurgery systems sit in early-cycle expansion as ambulatory surgical centers convert procedure rooms from electrosurgical tools, with waterjet precision reducing thermal collateral damage liability and accelerating patient throughput.
For Market Incumbents: Harden consumable revenue streams by locking multi-year sole-source contracts with southeastern US integrated delivery networks before disposable cartridge architectures commoditize saline supply agreements. Deepen backward integration into precision pump manufacturing to offset German supply concentration risk. Prioritize FDA 510(k) pathway acceleration against EU MDR's extended clinical evidence timelines.
For New Entrants and Emerging Players: Pursue veterinary orthopedic surgery as the most penetrable white-space channel, where companion animal specialty clinics command premium pricing for cruciate ligament procedures. Target Japan's aging surgical workforce with automation-friendly platforms reducing hand fatigue. Enter through single-use handpiece economics bypassing sterilization validation burdens that stall reusable architecture approvals.
For Investors and Strategic Acquirers: Precision component suppliers with captive ceramic pump manufacturing offer the strongest acquisition target archetype for vertical consolidation plays. Long-term viability hinges on consumable recurring revenue ratios exceeding capital equipment margins. Monitor FDA sterilization validation backlog resolution as inflection indicator for reusable handpiece architecture economics.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Pathway | Extended German notified body follow-up requirements delay novel indication launches by 12-18 months. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic standardization creates procurement template for IDN consolidation. |
| Software Companion Development | Real-time pressure feedback algorithms compress resident training timelines from months to weeks. |
| Reimbursement Strategy | CMS code alignment for cartilage debridement determines ASC conversion economics versus mechanical shavers. |
| CE Marking Pathway | Swissmedic streamlined assessment offers faster European access for innovative handheld architectures. |
Research Methodology
The analysis maps console systems, handheld devices, consumables, and accessories segments, each validated through orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interview intelligence combines with FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS reimbursement code records. Bottom-up unit economics triangulate against top-down expenditure flows across the analysis window.
Assumption sets held regulatory pathway timelines and saline cartridge pricing fixed while varying ASC conversion rates and reusable handpiece adoption curves. Segmentation dimensions span product architecture, end-user channel, technology integration, and application specificity. CAGRs derive from procedure volume projections and per-procedure consumable capture rates. Modeling incorporates pump engineering cost curves and sterilization validation backlog scenarios.
Sensitivities concentrate around FDA bioburden testing standard tightening and EU MDR orthopedic debridement follow-up extensions. Forecasts reflect documented assumptions on ASC network consolidation velocity and laser competition intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Middle East and Africa General Surgical Devices Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Resectoscopes Market
Surgical Instruments
Japan General Surgical Devices Market