

Knee Surgical Impactor Market Size, Share, and Industry Trends Forecast 2026-2036
Knee Surgical Impactor Market Insights
Software-defined torque calibration is rebalancing how manufacturers monetize knee surgical impactors, shifting revenue from hardware sales toward recurring service contracts. Stryker leverages its installed base to sustain premium positioning across academic medical centers. Zimmer Biomet anchors its portfolio through deep specialization in power-assisted systems with integrated feedback sensors. Johnson & Johnson MedTech competes by controlling distribution density in high-volume orthopedic corridors.
A knee surgical impactor is a precision instrument that delivers controlled mechanical force to seat prosthetic components during arthroplasty, typically fabricated from surgical-grade stainless steel with carbide-tipped striking surfaces and ergonomic polymer handles designed for repeated sterilization cycles. Its primary commercial purpose is to ensure accurate component positioning while minimizing bone trauma and operative time. Manual impactors retain the largest volume share due to lower capital requirements and universal compatibility, though power-assisted impactors with torque control technology command the deepest margin pools as hospitals prioritize reproducible outcomes. Feedback sensors and impact energy control systems represent the fastest-expanding technology segments, driven by surgeon demand for real-time performance validation.
FDA 510(k) clearance requirements govern powered instrument safety profiles in the United States, while the EU MDR imposes stricter clinical evidence standards on reusable surgical devices entering European markets. ISO 13485 quality management certification functions as a baseline threshold for supplier qualification across both jurisdictions. Stakeholders must monitor how regulatory divergence between FDA and notified body interpretations affects product registration timelines and geographic launch sequencing.
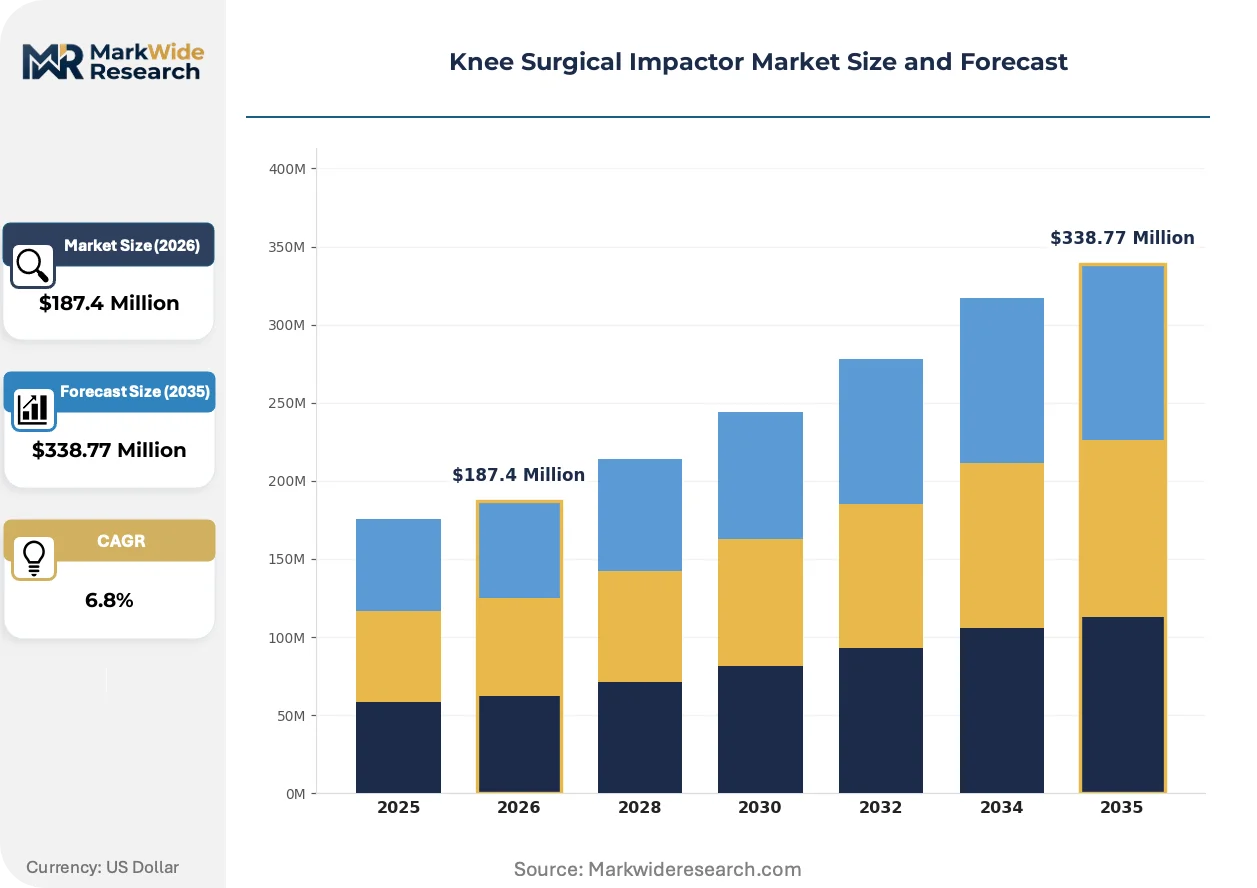
Market Dynamics
Software-defined torque calibration is compressing hardware margins while expanding recurring revenue pools, forcing manufacturers to restructure commercial models around service attachment rates rather than capital equipment sales.
Growth Catalysts
- Aging surgical volumes:Demographic expansion in the United States, Germany, and Japan generates predictable arthroplasty demand that sustains replacement instrument procurement cycles.
- EU MDR compliance:Stricter clinical evidence standards for reusable surgical devices elevate barriers for marginal suppliers, consolidating procurement decisions around established manufacturers with robust quality systems.
- Feedback sensor integration:Real-time impact energy validation technology commands premium positioning as ambulatory surgical centers prioritize reproducible outcomes and reduced revision risk.
Market Restraints
- Surgical-grade stainless steel volatility:Raw material input costs for carbide-tipped striking surfaces fluctuate with nickel and chromium commodity markets, compressing margin predictability.
- Supply concentration in German precision machining:Critical component fabrication clusters in Baden-Württemberg and Bavaria create geographic vulnerability to regional logistics disruptions.
- 510(k) pathway friction:FDA clearance timelines for powered instruments with novel sensor architectures extend product launch windows, deferring revenue recognition.
Strategic Opportunities
- Japanese outpatient migration:METI incentives for same-day joint replacement procedures expand addressable demand for compact, sterilization-optimized instrument sets.
- CE-MDR clinical evidence services:Manufacturers can monetize regulatory compliance infrastructure by offering notified body navigation support to smaller competitors.
- Sensor-telemetry convergence:Integration of impact force data with hospital information systems creates post-operative analytics revenue streams.
Industry Challenges
- Sterilization validation expertise:ISO 17664 documentation requirements for reusable surgical instruments demand specialized technical writing capacity that outstrips available talent pools.
- Legacy instrument compatibility:Power-assisted system adoption requires seamless interface with existing manual impactor trays, complicating engineering validation protocols.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knee Surgical Impactor Market Trends and Innovations
Digital instrumentation is displacing analog feedback mechanisms across arthroplasty suites, while regulatory evidence requirements and procurement centralization reshape how manufacturers commercialize precision surgical tools.
Embedded piezoelectric force sensors are absorbing the variability that previously required surgeon tactile interpretation, converting subjective striking technique into quantifiable data streams. Academic medical centers in the United States and university hospitals in Germany are adopting these systems at replacement-cycle pace, typically within 18-month capital refresh windows. This standardization is absorbing experiential knowledge gaps among less tenured surgical staff and compressing training curve differentials between high and low-volume arthroplasty centers.
The EU MDR's expanded clinical evidence requirements for Class IIa reusable surgical devices are extending technical documentation timelines by 8-14 months for manufacturers without predicate device strategies. Industrial consequence includes accelerated consolidation of European distribution partnerships around notified body-certified suppliers. Power-assisted impactor portfolios face the steepest compliance burden, as novel sensor architectures trigger higher scrutiny levels than manual instrument equivalents.
Ambulatory surgical centers are consolidating instrument procurement through group purchasing organizations that unbundle capital equipment from maintenance contracts. This channel compression displaces direct manufacturer relationships and shifts margin capture toward service providers with localized sterilization infrastructure. The pattern is most visible in the United States, where ASC joint replacement volumes now exceed 40% of total arthroplasty procedures in several metropolitan statistical areas.
Knee Surgical Impactor Market Segmentation
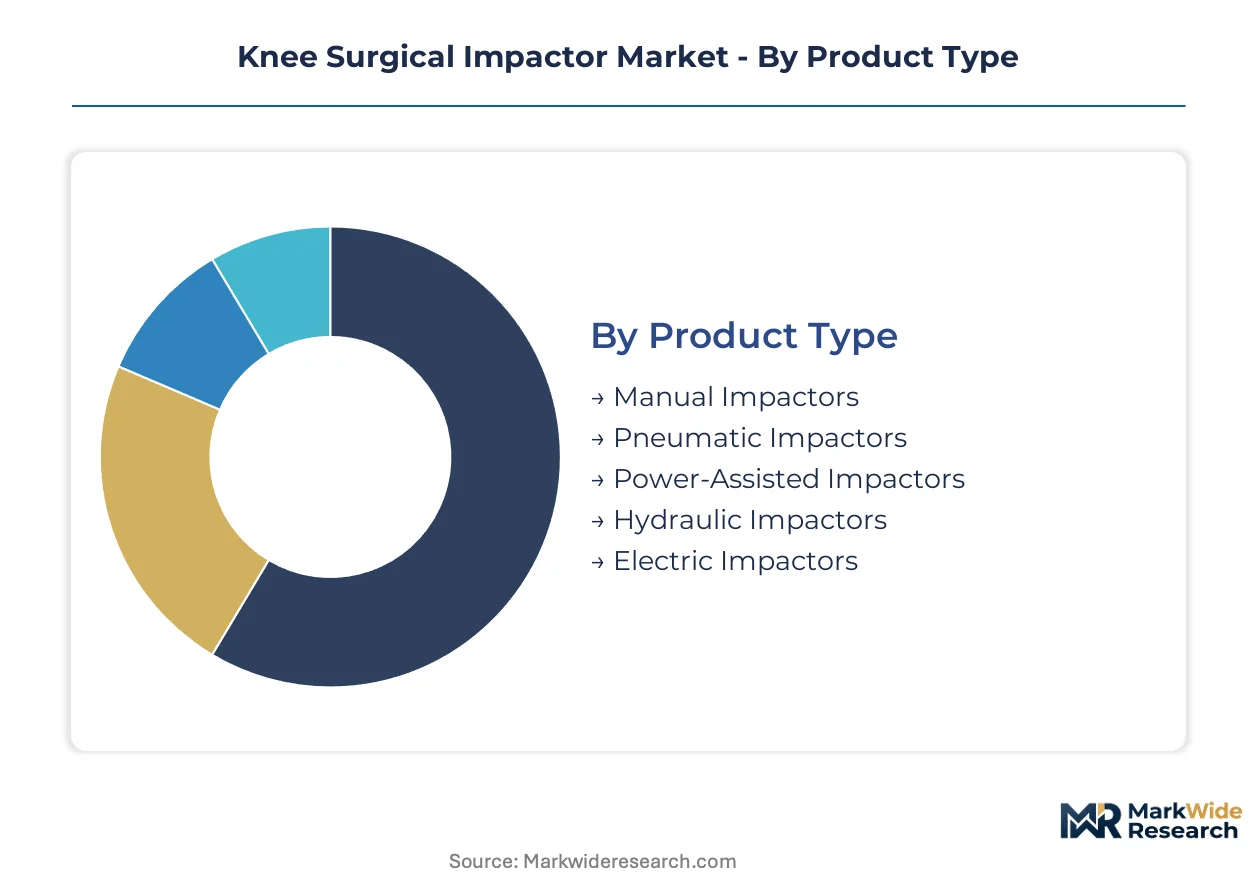
Segmentation reveals how procurement priorities diverge across clinical settings and technological sophistication tiers. Upgrade cycles for knee surgical impactors vary dramatically by product type and end-user infrastructure maturity, creating distinct commercial entry points for manufacturers.
Product Type:
Replacement cycles accelerate where capital equipment refresh windows compress and sterilization throughput demands intensify.
- Manual Impactors:Fabricated from surgical-grade stainless steel with carbide-tipped striking surfaces and ergonomic polymer handles designed for repeated autoclave cycles. Demand concentrates in ambulatory surgical centers across the United States and Germany where lower capital requirements and universal tray compatibility sustain procurement volume despite margin compression.
- Power-Assisted Impactors:Integrate torque control technology with integrated feedback sensors enabling real-time impact energy validation. Academic medical centers in Japan and university hospitals in Germany adopt these systems within compressed 18-month capital refresh windows as they prioritize reproducible outcomes and reduced revision risk.
- Pneumatic Impactors:Compressed air-driven systems offering intermediate force control for high-volume arthroplasty suites.
- Hydraulic Impactors:Fluid-pressure mechanisms delivering sustained force application for complex revision procedures.
- Electric Impactors:Battery-powered portable units gaining traction in outpatient migration scenarios.
Manual Impactors sits at the top of the volume ranking, with Power-Assisted Impactors climbing the fastest.
Technology:
Technology tiers stratify by data capture capability and surgeon training infrastructure requirements.
- Feedback Sensors:Embedded piezoelectric force sensors convert subjective striking technique into quantifiable data streams, absorbing experiential knowledge gaps among less tenured surgical staff. Academic medical centers in the United States deploy these systems to compress training curve differentials between high and low-volume arthroplasty centers.
- Torque Control:Software-defined calibration mechanisms enabling programmable force limits with sterilization-optimized housing designs. German orthopedic departments prioritize these systems where MDR compliance documentation demands traceable performance validation.
- Impact Energy Control:Real-time modulation of striking force based on bone density feedback.
- Oscillating Mechanism:Rotational impact delivery reducing linear force trauma to surrounding tissue.
- Angle Adjustment:Articulating head designs accommodating anatomical variation in component seating.
Feedback Sensors commands the deepest margin pools, with Torque Control expanding most quickly among replacement-cycle purchasers.
Application:
Application segments track procedure volume concentration and reimbursement pathway stability.
- Osteoarthritis Reconstruction:Primary and revision total knee arthroplasty procedures representing the dominant procedural category. Demand clusters in the United States, Germany, and Japan where aging demographics expand surgical volumes and sustain instrument procurement cycles through predictable replacement timelines.
- Meniscal Repair:Arthroscopic and open procedures addressing traumatic and degenerative meniscal pathology. Ambulatory surgical centers in the United States drive adoption of compact instrument sets optimized for same-day discharge protocols.
- Ligament Repair:ACL and PCL reconstruction procedures requiring precise tunnel placement.
- Patellar Realignment:Procedures addressing patellofemoral instability and maltracking.
- Cartilage Restoration:Autologous chondrocyte implantation and microfracture techniques.
Osteoarthritis Reconstruction anchors procurement volume, with Meniscal Repair gaining share fastest as outpatient migration accelerates.
End User:
End-user categories diverge by sterilization infrastructure scale and capital allocation authority.
- Academic Medical Centers:Teaching institutions with dedicated research budgets and 18-month capital refresh cycles. These facilities in the United States and Germany adopt power-assisted systems with sensor integration to standardize resident training and generate publishable outcome data.
- Orthopedic Surgeons:Individual practitioners and small group practices with direct procurement authority. Demand concentrates in metropolitan statistical areas where joint replacement volumes exceed regional thresholds and justify dedicated instrument investment.
- Surgical Centers:Ambulatory facilities consolidating procurement through group purchasing organizations.
- Specialty Clinics:Focused orthopedic practices with limited sterilization throughput.
- Private Hospitals:Community hospitals balancing capital constraints with competitive positioning.
Orthopedic Surgeons represents the broadest addressable base, with Academic Medical Centers capturing the steepest technology upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States deploy divergent procurement models for knee surgical impactors, with German university hospitals prioritizing MDR-validated power-assisted systems while US ambulatory surgical centers favor manual instrument sets optimized for rapid sterilization turnover.
United States
FDA 510(k) clearance pathways govern powered instrument safety profiles for knee surgical impactors entering US markets. Ambulatory surgical centers in metropolitan statistical areas now exceed 40% of total arthroplasty volumes, consolidating procurement through group purchasing organizations that unbundle capital equipment from maintenance contracts. The Southeast corridor from Florida through Georgia anchors demand concentration for compact, sterilization-optimized instrument sets.
Germany
EU MDR compliance imposes stricter clinical evidence standards on reusable surgical devices than predecessor directives, extending technical documentation timelines by 8-14 months for manufacturers without predicate device strategies. Baden-Württemberg and Bavaria host critical precision machining clusters for carbide-tipped striking surfaces, creating geographic concentration vulnerability to regional logistics disruptions. University hospitals in these states adopt power-assisted systems within compressed 18-month capital refresh windows.
Japan
METI incentives for same-day joint replacement procedures expand addressable demand for portable, battery-powered knee surgical impactor units optimized for outpatient migration scenarios. PMDA regulatory frameworks govern powered medical instrument safety validation. The Kanto region surrounding Tokyo concentrates academic medical center procurement authority, while Kansai-based orthopedic departments prioritize torque control systems with integrated feedback sensors for resident training standardization.
United Kingdom
NHS procurement frameworks centralize orthopedic instrument acquisition decisions around established manufacturers with robust ISO 13485 quality management certification. London and Southeast England concentrate private hospital demand for premium power-assisted systems, while Midlands-based NHS trusts balance capital constraints with competitive positioning through manual impactor standardization. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for manufacturers.
Switzerland
Swissmedic certification requirements for powered surgical instruments demand traceable performance validation documentation that favors manufacturers with embedded sensor architectures. The Basel-Zurich corridor concentrates orthopedic research institutions adopting feedback sensor systems to generate publishable outcome data. Cantonal hospital procurement authorities prioritize sterilization-optimized housing designs that withstand repeated autoclave cycles without calibration drift.
Knee Surgical Impactor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement authority at academic medical centers favoring established instrument houses while ambulatory surgical centers fragment demand across price-tiered suppliers. The vendor base stratifies into three archetypes: diversified orthopedic conglomerates with full arthroplasty portfolios, precision machining specialists with sterilization-optimized component expertise, and regional fabricators serving localized group purchasing organizations. Competitive moves concentrate on M&A-driven portfolio completeness and sterile processing service attachments that capture recurring revenue beyond capital equipment sales.
Among diversified orthopedic conglomerates, Stryker and Zimmer Biomet exemplify archetypes that leverage installed base relationships to sustain premium positioning across academic medical centers. Johnson & Johnson MedTech occupies a position within the distribution density tier, competing through control of high-volume orthopedic corridors rather than instrument specialization alone. These three entities represent distinct strategic postures: Stryker anchors the integrated feedback sensor vector, Zimmer Biomet exemplifies power-assisted system specialization, and Johnson & Johnson MedTech demonstrates procurement channel consolidation.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Medtronic |
| Johnson & Johnson MedTech |
| Smith & Nephew |
| Arthrex |
| B. Braun Melsungen |
| Exactech |
| Orthofix Medical |
| Others |
Pricing and Supply Chain Analysis
Surgical-grade stainless steel input costs cascade through three distinct pricing tiers for knee surgical impactors, with nickel and chromium commodity volatility compressing margin pools at the manual instrument level while power-assisted systems retain pricing power through embedded sensor differentiation.
Pricing Analysis
Capacity additions in German precision machining hubs are reshaping price floors for carbide-tipped striking surfaces, though FDA 510(k) clearance burdens for powered instruments sustain premium capture at the top tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with ISO 13485-validated systems commanding measurable uplifts. Pricing pressure stems from group purchasing organization consolidation in United States ambulatory surgical centers, where capital equipment unbundling intensifies cost scrutiny. Academic medical centers exhibit lowest price sensitivity due to research budget insulation, while independent orthopedic surgeons face acute capital constraint.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital purchasing committees mandate qualified supplier redundancy for critical impactor components, forcing manufacturers to maintain parallel fabrication relationships. Component fabrication clusters in Germany, Japan, and Switzerland anchor precision machining capacity for carbide-tipped inserts and sensor housings. Raw material dependencies on nickel-chromium alloys, medical-grade polymers, and piezoelectric ceramics tether production schedules to commodity and semiconductor supply cycles. Single-source vulnerability concentrates in Baden-Württemberg machining corridors, where regional logistics disruptions propagate through tier-one supplier networks. Distribution runs through orthopedic-focused group purchasing organizations and direct hospital contracts, with sterilization service providers capturing downstream margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory escalation, with EU MDR clinical evidence requirements extending documentation timelines and consolidating procurement around established quality systems.
For Market Incumbents: Lock in sterilization validation expertise through captive technical writing capacity, addressing ISO 17664 documentation demands that outstrip available talent pools. Defend installed base relationships at academic medical centers by embedding feedback sensor architectures that trigger higher regulatory scrutiny for competitor entry. Priority rests on backward integration into carbide-tipped striking surface fabrication, mitigating raw material volatility exposure.
For New Entrants and Emerging Players: Ambulatory surgical centers in Japanese metropolitan corridors represent the most penetrable buyer archetype, where METI incentives for same-day joint replacement procedures expand addressable demand for portable, battery-powered units. White-space targets include CE-MDR clinical evidence services for smaller competitors lacking notified body navigation infrastructure, and compact instrument sets optimized for rapid sterilization turnover. Go-to-market angle should emphasize localized sterilization service partnerships that capture recurring revenue beyond capital equipment.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance burdens eliminate marginal suppliers without predicate device strategies or robust quality management certification. Long-term viability favors precision machining specialists with sterilization-optimized component expertise and established notified body relationships over regional fabricators dependent on price-tiered competition. Acquisition target archetype: mid-cap manufacturers with embedded sensor capabilities and incomplete distribution reach. Signal to watch: FDA 510(k) clearance timeline extensions for novel powered instrument architectures, which would accelerate procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Clinical Evidence Pathway | Stricter documentation requirements favor established manufacturers with predicate device strategies in European markets. |
| Hospital System Partnership | Academic medical centers in Germany and the United States drive adoption of power-assisted systems with integrated feedback sensors. |
| FDA 510(k) Submission | Clearance timelines for powered instruments with novel sensor architectures extend product launch windows and defer revenue. |
| Software Companion Development | Integration of impact force data with hospital information systems creates post-operative analytics revenue streams. |
| Reimbursement Strategy | METI incentives for same-day joint replacement in Japan expand demand for outpatient-optimized instrument sets. |
Research Methodology
Multiple input streams — primary interviews with orthopedic surgeons and hospital purchasing committees, secondary validation through FDA 510(k) filings and EU MDR technical documentation databases, and trade data from German precision machining clusters — were reconciled to construct market estimates. Clinicians, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at notified bodies provided procedure-volume and procurement-pattern intelligence. Secondary sources included hospital procurement databases, ISO 13485 certification registries, and customs records for surgical-grade stainless steel imports. Bottom-up instrument shipment analysis and top-down arthroplasty procedure modeling were cross-validated.
Data-stream reconciliation across product type, technology tier, application segment, and end-user infrastructure maturity informed the analytical framework over the projection horizon. Segmentation dimensions modeled included manual versus power-assisted instrument categories, feedback sensor integration levels, osteoarthritis reconstruction versus meniscal repair applications, and academic medical center versus ambulatory surgical center procurement authority. CAGRs were derived from replacement cycle analysis and capital equipment refresh patterns. Industry-specific forecast inputs encompassed EU MDR documentation timeline extensions and METI outpatient migration incentive trajectories.
Underlying measurement precision varies by segment; power-assisted impactor forecasts carry tighter precision than manual instrument projections due to concentrated manufacturer disclosure. Forecasts reflect assumptions regarding regulatory clearance pathway stability, raw material cost trajectories, and arthroplasty volume demographics. Deviation in FDA 510(k) review intensity or EU MDR notified body capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.