
 Medical Imaging Displays Market | 2026-2036
Medical Imaging Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Imaging Displays Market Outlook
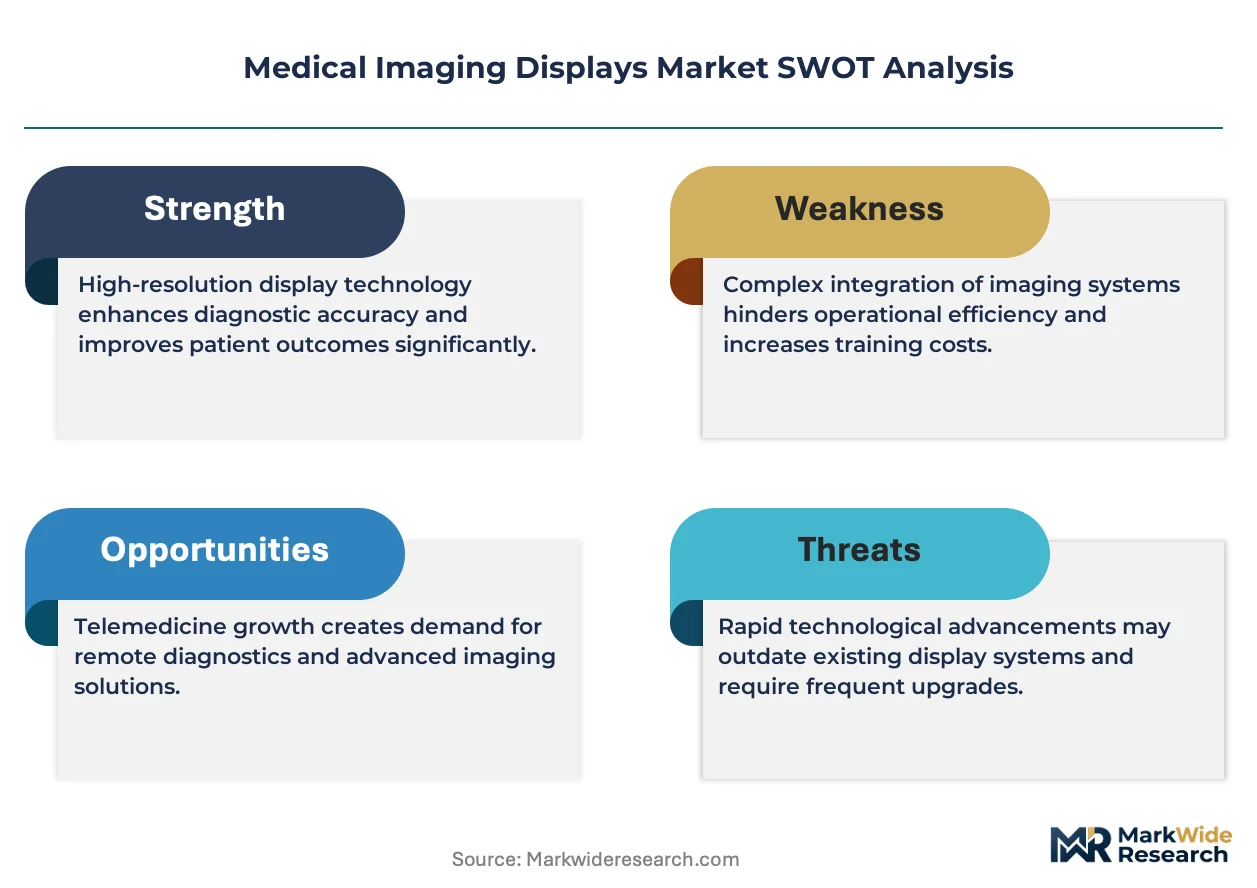
Panel sourcing strategy is shifting from single-source LCD procurement toward dual-qualified OLED and mini-LED supply chains to mitigate component risk. Barco sustains its dominance in diagnostic grayscale displays through captive calibration software and radiologist workflow integration. EIZO Corporation specializes in color-critical pathology and surgical displays with factory-level uniformity correction. NEC Display Solutions leverages its broad display portfolio to compete across both enterprise healthcare IT and embedded clinical workstations.
Medical imaging displays are high-precision visualization devices engineered to deliver consistent luminance, grayscale calibration, and color accuracy for clinical diagnosis, typically achieving DICOM Part 14 compliance and luminance ratios exceeding 250 cd/m² for primary interpretation. LCD Monitors retain the largest installed base across radiology departments due to mature supply chains and established service networks, though OLED Screens are capturing premium segments where absolute black levels and contrast ratios improve detection of subtle pathologies. Wall-Mounted installations dominate fixed reading rooms, while Mobile Carts are expanding fastest in hybrid operating suites and point-of-care ultrasound workflows where flexibility outweighs permanent infrastructure investment.
FDA 21 CFR Part 820 quality system requirements and DICOM GSDF calibration standards shape product design, forcing manufacturers to maintain traceable luminance testing protocols for market access in the United States. The EU Medical Device Regulation (MDR) and CE marking obligations impose additional clinical evidence and post-market surveillance burdens on display vendors shipping into European healthcare systems. Stakeholders must monitor evolving cybersecurity guidance from FDA and Health Canada as networked displays integrate with hospital information systems and cloud-based PACS architectures.
Market Dynamics
Dual-qualified OLED and mini-LED supply chains are displacing single-source LCD procurement as the dominant sourcing strategy, forcing display vendors to restructure component qualification workflows and inventory buffers around luminance stability requirements.
Growth Catalysts
- FDA 21 CFR Part 820:Mandatory quality system documentation for luminance traceability drives recurring calibration software subscriptions and service revenue streams among installed base customers.
- Germany's university hospital networks:Systematic replacement cycles for color-calibrated diagnostic workstations generate predictable demand for premium grayscale panels with factory-level uniformity correction.
- Mammography imaging protocols:Expansion of high-resolution grayscale panel procurement across diagnostic centers accelerates demand for DICOM GSDF-compliant displays with luminance ratios exceeding 250 cd/m².
Market Restraints
- Panel supply concentration:Limited qualified suppliers for medical-grade OLED substrates in East Asia create vulnerability to allocation constraints and extended lead times.
- EU MDR clinical evidence burdens:Post-market surveillance obligations and notified body review timelines extend product registration cycles by 12-18 months for new display introductions.
- LED backlight component volatility:Mini-LED chip pricing fluctuations and quantum dot material scarcity compress gross margins on premium diagnostic panels.
Strategic Opportunities
- Hybrid operating suites:Mobile cart configurations for point-of-care ultrasound workflows represent underpenetrated demand where flexibility requirements override permanent infrastructure investment.
- Cybersecurity guidance convergence:FDA and Health Canada networked device frameworks create first-mover advantage for vendors integrating hardware-level encryption with PACS architectures.
- Pathology digitization:Whole-slide imaging adoption in academic medical centers opens adjacent demand for color-critical displays with extended color gamut coverage.
Industry Challenges
- DICOM calibration technician scarcity:Specialized expertise in GSDF curve validation and luminance meter traceability limits service network expansion and extends installation timelines.
- Legacy PACS integration complexity:Hospital information system heterogeneity forces customized software middleware development for each enterprise deployment, inflating implementation costs.
- CE marking documentation:Technical file maintenance and clinical evaluation report updates under EU MDR impose ongoing regulatory affairs overhead without direct revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Imaging Displays Market |
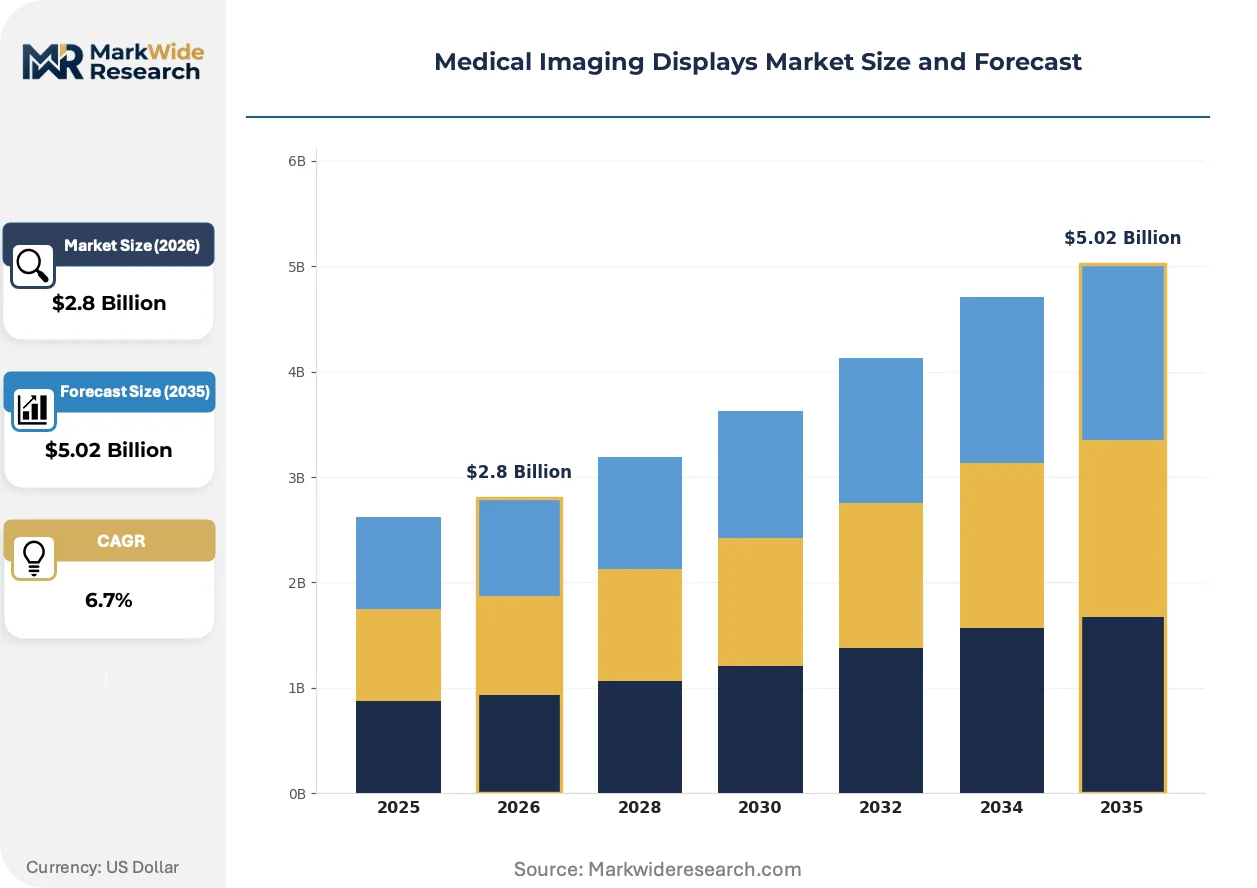
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Displays, LCD Monitors, OLED Screens, CRT Monitors Therapy Area: Radiology, Cardiology, Oncology, Neurology End User: Hospitals, Diagnostic Centers, Research Facilities, Clinics Installation Type: Wall-Mounted, Mobile Carts, Ceiling-Mounted, Portable Units |
| Companies Covered | Siemens Healthineers, NEC Display Solutions, Barco, Dell Technologies, Advantech Co., Ltd., EIZO Corporation, LG Electronics, BenQ Medical Technology, Sony Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Imaging Displays Market Strategic Shifts
Mini-LED backlight arrays are actively restructuring competitive differentiation around local dimming precision and power efficiency, compressing the performance gap with OLED while preserving LCD supply chain maturity.
Mini-LED zone-dimming architectures are electrifying the premium diagnostic segment through sub-millimeter backlight control that achieves near-OLED contrast without sacrificing luminance stability. Radiology departments in tertiary care centers are adopting these panels for chest imaging workstations where subtle parenchymal detail detection is critical. The technology is electrifying vendor R&D roadmaps by enabling a single platform strategy across grayscale and color-calibrated product lines.
EU MDR Article 10 technical documentation requirements are forcing display manufacturers to maintain clinical evidence libraries for every luminance performance claim across their product portfolios. Notified bodies now require periodic safety and performance updates that tie software release cycles to regulatory submission timelines. German university hospitals and radiology networks are responding by consolidating vendor relationships around suppliers with established European authorized representative infrastructure.
Hospital procurement departments are compressing replacement cycles from seven-year standards to five-year agreements, unbundling extended warranty and calibration service contracts from hardware acquisition. This shift is restructuring vendor revenue recognition toward recurring service streams and away from upfront equipment margins. The pattern is most visible in United States health systems responding to capital expenditure pressure from Medicare reimbursement compression.
Medical Imaging Displays Market Segmentation
Display procurement patterns diverge sharply across clinical settings, with replacement cycles and upgrade priorities varying by product generation, therapy complexity, and infrastructure constraints. Understanding these fault lines enables vendors to align R&D roadmaps with predictable refresh timelines.
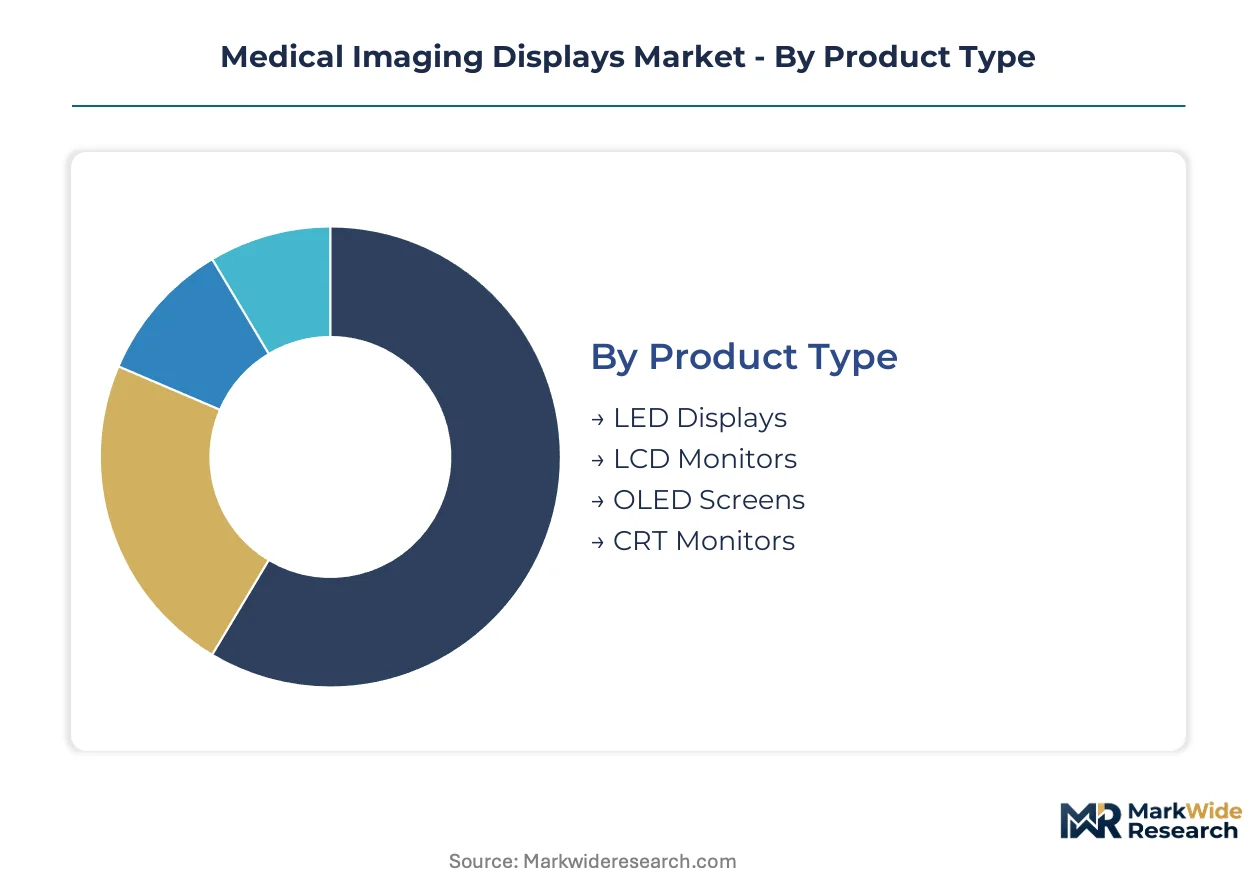
Product Type:
Upgrade cycles for primary diagnostic workstations now compress from seven-year standards toward five-year intervals, driven by luminance degradation concerns and evolving DICOM calibration requirements.
- LCD Monitors:These panels dominate radiology department installations through mature supply chains and established service networks. German university hospitals and diagnostic centers in the United States sustain replacement demand for high-resolution grayscale configurations compliant with mammography imaging protocols.
- OLED Screens:Absolute black levels and contrast ratios exceeding conventional alternatives improve detection of subtle pathologies in tertiary care settings. Academic medical centers in Japan and South Korea prioritize these panels for pathology digitization workflows where extended color gamut coverage is essential.
- LED Displays:Backlight-stabilized variants serve secondary review stations and clinical consultation areas where cost constraints outweigh primary interpretation requirements.
- CRT Monitors:Legacy installations persist only in isolated archival imaging environments and developing-market facilities with extended capital depreciation schedules.
LCD Monitors sit at the top of the volume ranking, with OLED Screens climbing the fastest.
Therapy Area:
Application-specific luminance and color accuracy requirements create tiered pricing structures that separate premium diagnostic tiers from standard clinical review configurations.
- Radiology:Chest imaging and mammography protocols demand DICOM GSDF-compliant displays with luminance ratios exceeding 250 cd/m². Diagnostic centers across the United States and Germany concentrate procurement of high-resolution grayscale panels for these workstations.
- Cardiology:Dynamic range requirements for catheterization laboratory visualization drive demand for color-calibrated panels with rapid refresh rates. Hybrid operating suites in university hospital networks prioritize these specifications.
- Oncology:Multi-modality fusion imaging requires balanced grayscale and color performance for PET-CT and MRI correlation studies.
- Neurology:Functional MRI and intraoperative navigation applications favor portable and mobile configurations for flexibility in surgical and interventional settings.
Radiology commands the largest installed base, while Cardiology displays the steepest expansion trajectory.
End User:
Customer-type concentration determines service contract bundling strategies and calibration software subscription penetration rates.
- Hospitals:Enterprise health systems in the United States unbundle extended warranty and calibration service contracts from hardware acquisition, restructuring vendor revenue toward recurring streams. Medicare reimbursement compression accelerates this shift.
- Diagnostic Centers:Specialized imaging facilities concentrate procurement of high-resolution grayscale panels for mammography and chest imaging, with systematic replacement cycles generating predictable demand.
- Research Facilities:Academic medical centers drive adoption of color-critical pathology displays with factory-level uniformity correction for whole-slide imaging protocols.
- Clinics:Point-of-care ultrasound workflows in hybrid operating suites favor mobile cart configurations where flexibility requirements override permanent infrastructure investment.
Hospitals anchor procurement volume, with Diagnostic Centers gaining share fastest.
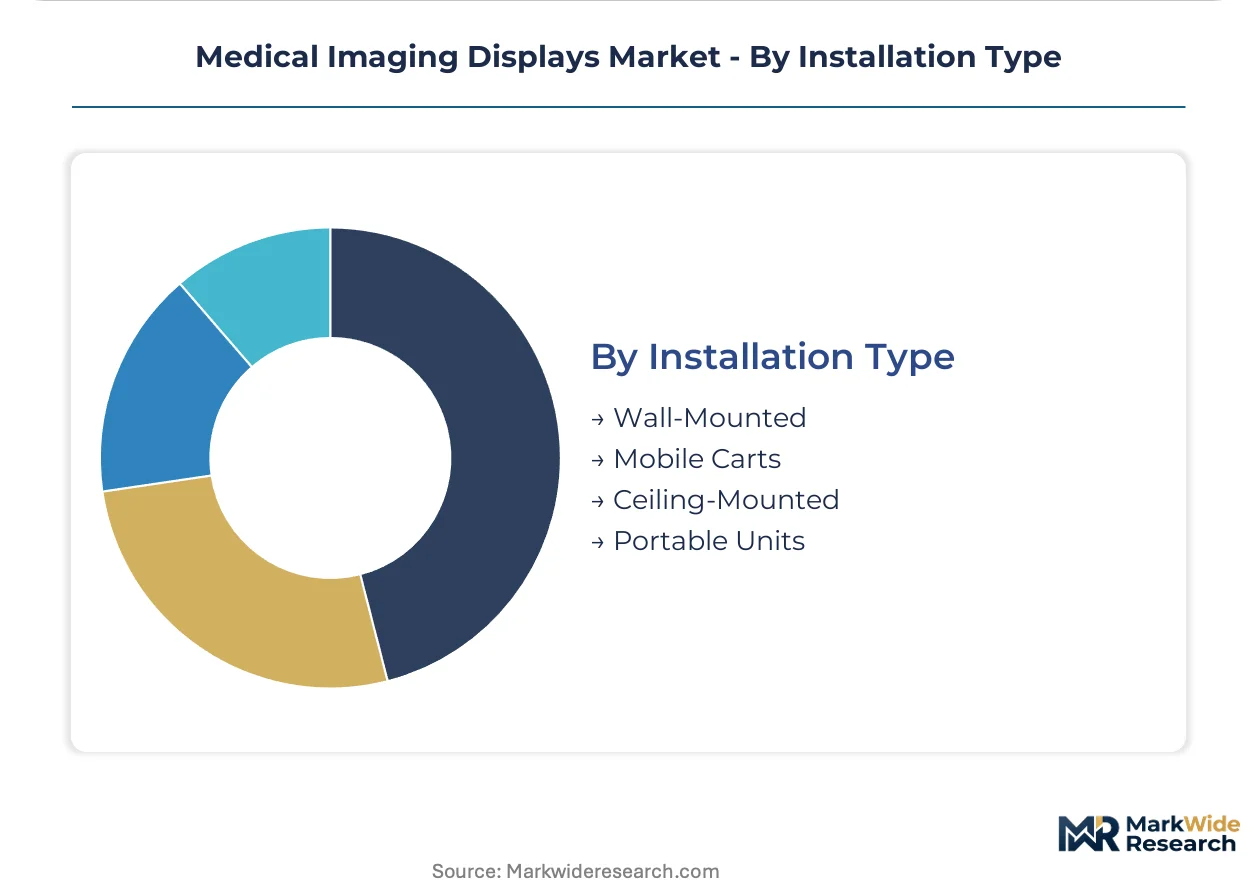
Installation Type:
Physical mounting configurations reflect infrastructure maturity and workflow mobility requirements across fixed and flexible clinical environments.
- Wall-Mounted:Fixed reading room installations dominate radiology departments where permanent infrastructure supports dedicated diagnostic workstations. These configurations prioritize cable management and ergonomic positioning for extended interpretation sessions.
- Mobile Carts:Battery-powered configurations with integrated computing expand fastest in hybrid operating suites and point-of-care ultrasound workflows. Flexibility requirements in tertiary care centers override permanent infrastructure investment.
- Ceiling-Mounted:Surgical suites and interventional laboratories favor suspended displays for optimized sightlines and floor space conservation.
- Portable Units:Compact diagnostic panels serve emergency departments and field deployment scenarios where rapid relocation is essential.
Wall-Mounted installations hold the volume lead, with Mobile Carts expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as vendors relocate calibration and final assembly operations to jurisdictions with streamlined quality system documentation. Production gravity is shifting toward regions where FDA 21 CFR Part 820 compliance costs diverge from EU MDR clinical evidence burdens.
United States
Medicare reimbursement compression is accelerating hospital procurement unbundling across enterprise health systems. FDA enforces strict calibration standards under 21 CFR Part 820, pushing vendors toward continuous compliance investment. The Greater Boston and Pacific Northwest clusters concentrate radiology network headquarters driving replacement cycles for diagnostic workstations.
Germany
University hospital networks and radiology networks sustain systematic demand for color-calibrated diagnostic workstations with factory-level uniformity correction. EU MDR Article 10 technical documentation requirements extend product registration cycles through notified body review timelines. The Bavaria and North Rhine-Westphalia regions anchor procurement concentration for high-resolution grayscale panels.
Japan
Academic medical centers prioritize OLED panels for pathology digitization workflows requiring extended color gamut coverage. METI standards and PMDA quality system requirements shape local market access protocols. The Kanto region around Tokyo and the Kansai cluster near Osaka drive adoption of whole-slide imaging displays.
South Korea
Domestic display panel manufacturing creates captive supply advantages for medical-grade OLED substrate qualification. MFDS medical device regulations impose post-market surveillance obligations on networked display deployments. The Seoul Capital Area concentrates tertiary care centers adopting premium diagnostic panels for multi-modality fusion imaging.
China
Diagnostic centers are expanding procurement of high-resolution configurations for mammography and chest imaging protocols. NMPA quality system regulations and GB standards govern luminance traceability requirements for market access. The Yangtze River Delta and Pearl River Delta clusters concentrate both manufacturing capacity and hospital network procurement.
Medical Imaging Displays Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in mobile cart configurations and point-of-care workflows. The vendor base stratifies across three tiers: integrated healthcare technology conglomerates with captive display divisions, specialized visualization firms with radiologist workflow integration, and diversified electronics manufacturers leveraging component scale. Two dominant competitive moves are reshaping positioning: dual-qualified supply chain restructuring around OLED and mini-LED sources, and unbundling of hardware acquisition from recurring calibration service contracts.
Within the specialized visualization tier, Barco and EIZO Corporation exemplify contrasting strategic positions. Barco anchors the diagnostic grayscale segment through captive calibration software ecosystems. EIZO Corporation occupies a position in color-critical pathology and surgical applications. Among diversified electronics manufacturers, NEC Display Solutions represents the portfolio-breadth archetype competing across enterprise healthcare IT and embedded clinical workstations.
| Leading Market Players |
|---|
| Siemens Healthineers |
| NEC Display Solutions |
| Barco |
| Dell Technologies |
| Advantech Co., Ltd. |
| EIZO Corporation |
| LG Electronics |
| BenQ Medical Technology |
| Sony Electronics |
| Others |
Value Chain & Pricing Dynamics
Enterprise health systems in the United States anchor procurement volume and impose unbundling of extended warranty and calibration service contracts from hardware acquisition, restructuring vendor revenue recognition toward recurring service streams and compressing upfront equipment margins.
Pricing Analysis
Distributor margins on medical-grade panels typically range between 15-22 percent before calibration software bundling. Three-tier pricing structure across premium, standard, and economy levels separates DICOM GSDF-certified primary interpretation displays from secondary review stations and archival consultation monitors. Price differentiation hinges on luminance stability certification and factory-level uniformity correction. Cost compression in premium diagnostic tiers is intensifying because hospital procurement departments compress replacement cycles from seven-year standards to five-year agreements. Diagnostic centers exhibit highest price sensitivity due to capital expenditure constraints, while academic medical centers prioritize performance over unit economics.
Supply Chain Analysis
Refurbishment flows for end-of-life diagnostic displays concentrate in South Korea and Taiwan, where panel manufacturers maintain captive remanufacturing capabilities for luminance-degraded units. Medical-grade OLED substrate production draws from Japan and South Korea, with mini-LED chip sourcing anchored in Taiwan and China. Quantum dot material supply rests on rare earth processing concentrated in China. Single-source vulnerability for medical-grade OLED substrates in East Asia creates allocation risk during demand surges. Distribution runs through specialized medical device distributors with FDA 21 CFR Part 820 quality system certification, bypassing consumer electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR clinical evidence burdens extend product registration cycles by 12-18 months, while FDA 21 CFR Part 820 compliance costs diverge toward recurring calibration service investments.
For Market Incumbents: Acquire calibration software ecosystems to deepen radiologist workflow integration and defend against emerging entrants pursuing mobile cart configurations. Barco sustains dominance through captive calibration protocols; EIZO Corporation specializes in factory-level uniformity correction. Counter substitution threat from mini-LED backlight arrays by accelerating OLED luminance stability roadmaps. Prioritize certification investment in EU MDR notified body relationships to compress registration timelines. For New Entrants and Emerging Players: Distributor partnerships with specialized medical device channels represent the most penetrable entry vector for point-of-care ultrasound mobile cart configurations. Hybrid operating suites in tertiary care centers offer white-space demand where flexibility requirements override permanent infrastructure investment. Pathology digitization workflows in academic medical centers present adjacent entry through color-critical displays with extended color gamut coverage. Pursue software companion development for PACS integration to bypass legacy hardware replacement cycles. For Investors and Strategic Acquirers: Healthcare technology conglomerates with captive display divisions are the most active acquirer in this space, seeking radiologist workflow integration capabilities. Long-term viability over a multi-year horizon rests on recurring service revenue streams displacing upfront equipment margins. Target acquisition archetype: specialized visualization firms with established European authorized representative infrastructure and DICOM GSDF calibration software libraries. Monitor FDA cybersecurity guidance convergence for networked displays as inflection indicator for hardware-level encryption valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Qualified Supply Chain Restructuring | Mitigates allocation risk from limited East Asian OLED substrate suppliers through mini-LED parallel qualification. |
| Calibration Software Subscription Unbundling | Restructures vendor revenue toward recurring streams as US health systems compress replacement cycles under Medicare pressure. |
| EU Authorized Representative Infrastructure Investment | Compresses MDR Article 10 technical documentation timelines for German university hospital network procurement. |
| Hardware-Level Encryption Integration | Captures first-mover advantage under FDA and Health Canada networked device cybersecurity frameworks. |
| Pathology Digitization Display Development | Opens adjacent demand from whole-slide imaging adoption in Japan and South Korean academic medical centers. |
Study Parameters
Coverage spans the United States, Germany, Japan, South Korea, and China, with primary inputs from each market combining structured interviews with radiologists, hospital procurement committees, biomedical engineers, and GPO contracts managers alongside secondary validation. Primary fieldwork drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract repositories, and CMS Medicare reimbursement data. Secondary sources included SEC 10-K disclosures from listed display manufacturers, Japanese PMDA quality system registrations, and South Korean MFDS post-market surveillance reports. Bottom-up triangulation across installed base estimates and top-down validation through vendor shipment disclosures anchored volume and value outputs.
Rate-of-change decomposition across the analysis window segmented growth by display technology type, clinical therapy area, end-user facility category, and installation configuration. Modeled dimensions included grayscale versus color-calibrated product lines, primary diagnostic versus secondary review station applications, and fixed versus mobile mounting architectures. CAGRs were derived through logistic diffusion curves for technology substitution and replacement cycle elasticity models for refresh demand. Industry-specific forecast inputs incorporated DICOM calibration technician scarcity constraints and EU MDR notified body review timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to mini-LED chip pricing volatility and quantum dot material scarcity. Projections reflect assumptions around hospital capital expenditure trajectories under Medicare reimbursement compression and EU MDR clinical evidence burden evolution. Practitioners should monitor FDA cybersecurity guidance finalization and OLED substrate allocation announcements from East Asian suppliers for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
India Mammography Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Italy Digital X-Ray Market