
 Surgical Stents Market | 2026-2036
Surgical Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Stents Market Analysis
Asset-light leasing models for cath lab equipment are reshaping how smaller hospitals enter interventional cardiology, lowering capital barriers for stent-intensive procedures. Medtronic leverages its integrated supply chain to sustain bulk purchasing contracts with integrated delivery networks across North America. Boston Scientific anchors its position through specialized drug-eluting stent platforms that dominate complex lesion segments. Abbott competes via diversified material science capabilities spanning metallic and bioresorbable scaffold portfolios.
Surgical stents are tubular prosthetic devices typically fabricated from stainless steel, cobalt-chromium alloys, or polymeric matrices, designed to scaffold luminal structures and restore patency in occluded vessels or ducts. Manufacturers deploy laser cutting and electropolishing to achieve strut thickness below 100 micrometers, minimizing endothelial disruption while maintaining radial strength. Coronary stents command the largest revenue share as aging populations and diabetes prevalence expand the addressable patient pool for percutaneous coronary intervention. Biodegradable materials represent the fastest-expanding segment, with polylactic acid and tyrosine-derived polymers enabling temporary scaffolding that eliminates long-term inflammatory risks. Drug-eluting platforms concentrate margin pools through proprietary polymer-drug combinations that command premium positioning in reimbursement frameworks.
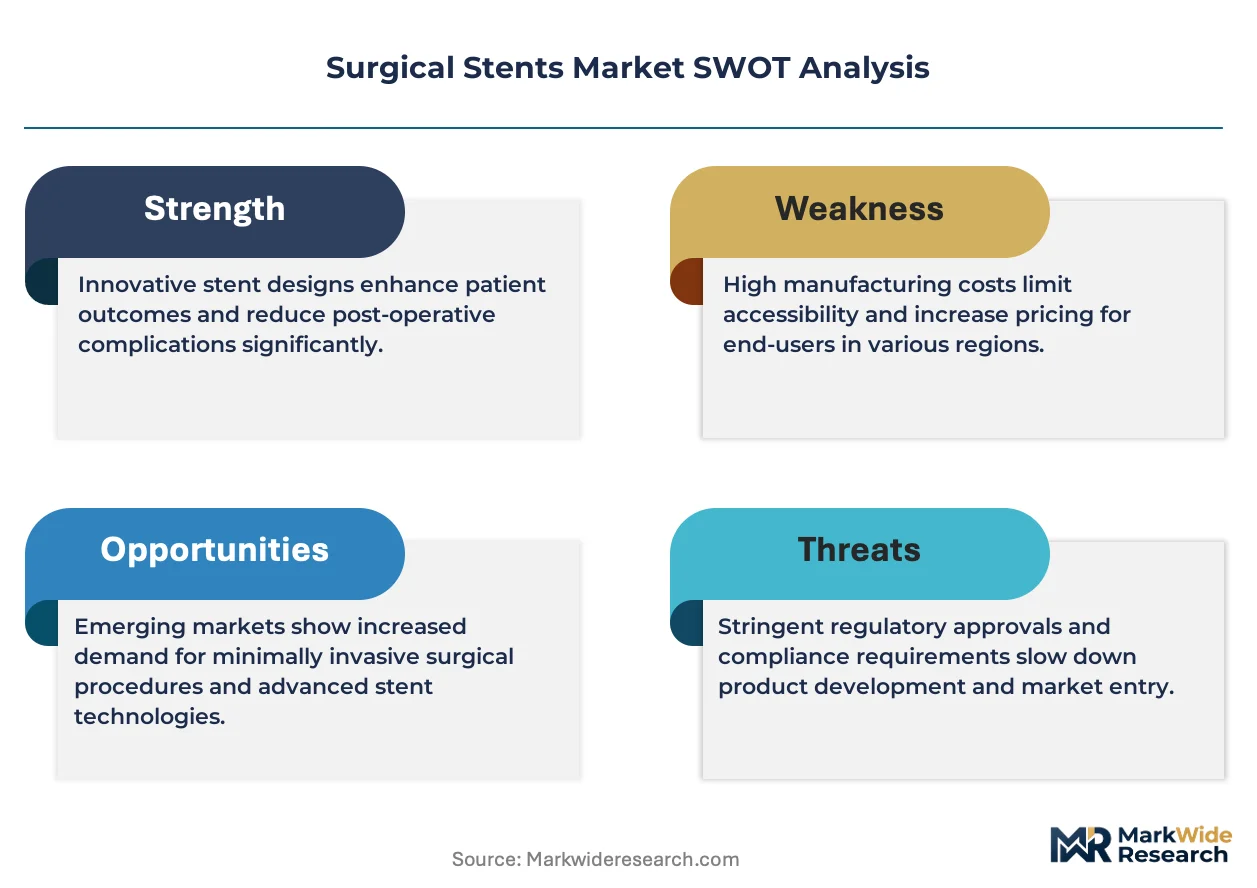
FDA premarket approval and EMA CE marking under the Medical Device Regulation govern stent safety, biocompatibility, and clinical efficacy requirements, with both agencies intensifying scrutiny of durable polymer coatings. The EU AI Act and FDA software-as-medical-device guidance are beginning to intersect with computational modeling used in stent design validation, adding compliance layers for simulation-dependent manufacturers. Stakeholders must monitor evolving biodegradable scaffold durability data and corresponding reimbursement decisions by national health technology assessment bodies.
Market Dynamics
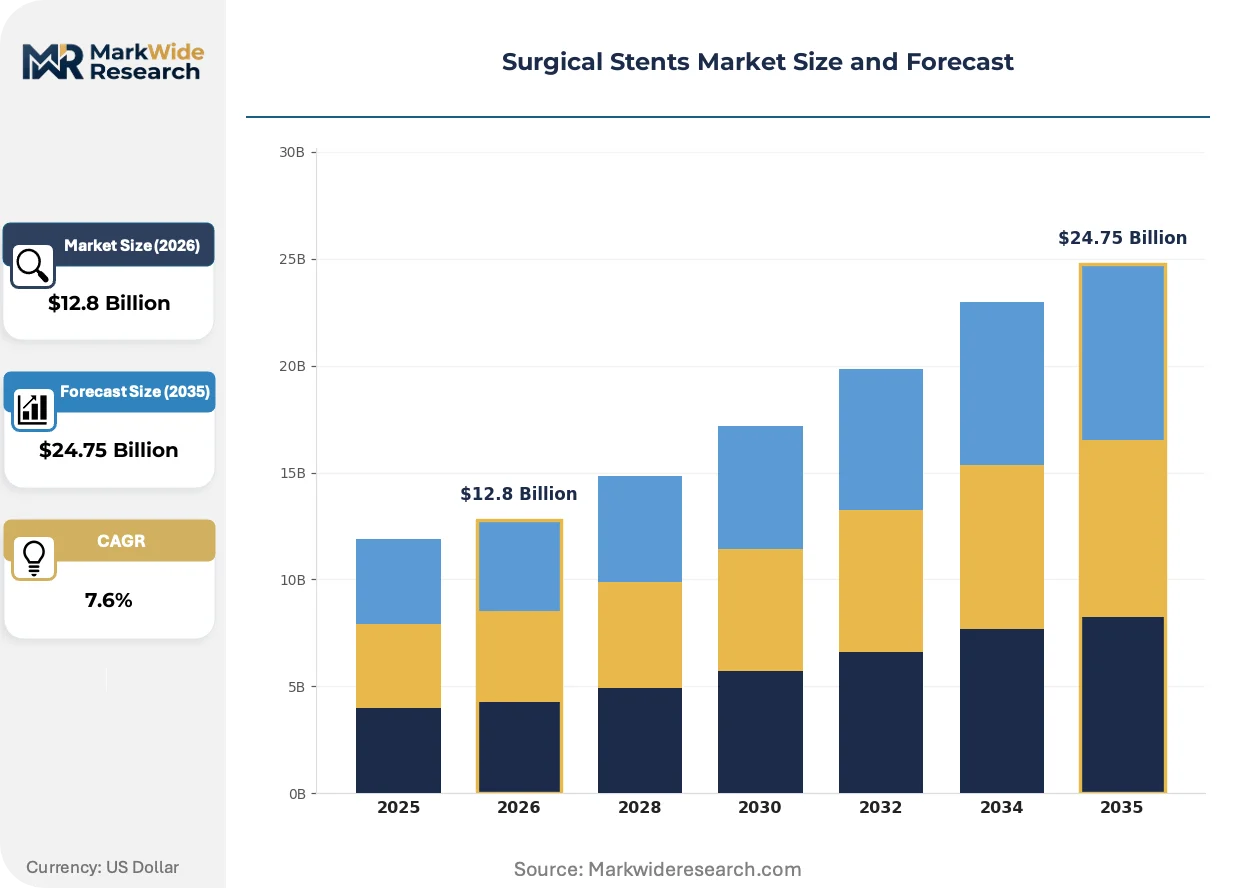
Drug-eluting stent platforms are displacing bare-metal alternatives across cardiovascular centers, compressing procurement cycles while FDA and EMA premarket pathways for biodegradable scaffolds lengthen development timelines. This technological transition concentrates purchasing power within integrated delivery networks.
Growth Catalysts
- Diabetes prevalence expansion:Rising diabetic populations in aging demographics enlarge the addressable patient pool for percutaneous coronary intervention, particularly in United States and German hospital systems.
- EU Medical Device Regulation:Stricter CE marking requirements under MDR are accelerating consolidation among manufacturers with robust clinical data portfolios, favoring established drug-eluting platforms.
- Biodegradable polymer innovation:Polylactic acid and tyrosine-derived scaffolds enable temporary vascular support without long-term inflammatory risks, attracting reimbursement attention from national health technology assessment bodies.
Market Restraints
- Premarket approval timeline extension:FDA and EMA intensified scrutiny of durable polymer coatings and biodegradable scaffold durability data delays commercialization by 18-36 months for novel platforms.
- Cobalt-chromium alloy concentration:Supply of specialized alloys for thin-strut stent fabrication concentrates among a limited set of European and East Asian metallurgical suppliers, exposing manufacturers to input volatility.
- Balloon angioplasty resurgence:Drug-coated balloon technology advances present a viable substitute for certain lesion types, particularly in cost-sensitive reimbursement environments.
Strategic Opportunities
- Chinese interventional cardiology buildout:Provincial hospital networks in China are expanding cath lab capacity, creating procurement entry points for drug-eluting stent manufacturers with localized regulatory support from NMPA.
- Asset-light equipment leasing:Cath lab equipment leasing models reduce capital barriers for smaller hospitals, enabling stent-intensive procedure adoption in secondary and tertiary medical centers.
- AI-enabled computational modeling:Convergence of finite element analysis with machine learning streamlines stent design validation, though EU AI Act compliance adds new layers for simulation-dependent manufacturers.
Industry Challenges
- Biocompatibility certification complexity:ISO 10993 biological evaluation requirements for novel polymer-drug combinations demand extended testing protocols, compressing R&D efficiency.
- Electropolishing and laser cutting specialization:Achieving sub-100 micrometer strut thickness requires precision manufacturing talent that concentrates among a narrow pool of European and Japanese equipment operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Stents Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coronary Stents, Peripheral Stents, Biliary Stents, Uretheral Stents Material: Metal, Polymer, Drug-eluting, Biodegradable End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Installation Method: Endovascular, Open Surgery, Laparoscopic, Percutaneous |
| Companies Covered | Medtronic, Boston Scientific, Abbott, Terumo Corporation, B Braun, Biotronik, Cook Medical, MicroPort Scientific Corporation, BIOTRONIK SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Stents Market Emerging Trajectories
Bioresorbable scaffold technology is hybridizing with metallic platform performance, while regulatory frameworks evolve to capture software-as-medical-device intersections in computational design. These forces are compressing traditional competitive moats.
Bioresorbable vascular scaffolds fabricated from poly-L-lactide and magnesium alloys provide temporary luminal support that fully resorbs within 24-36 months. Major cardiovascular centers in Germany and the United States are piloting these platforms for younger patients with simple lesions. The technology is hybridizing drug-eluting capabilities with absorbable matrices, collapsing the historical trade-off between durable scaffolding and long-term vessel restoration.
EMA Medical Device Regulation and FDA software-as-medical-device guidance are converging on computational modeling used for stent fatigue and corrosion prediction. Manufacturers must now validate simulation outputs as clinical evidence, extending documentation requirements. European notified bodies are applying this most aggressively to biodegradable scaffolds where in-silico performance prediction replaces certain animal studies.
Integrated delivery networks are consolidating stent procurement through volume-based contracting with preferred manufacturers, displacing individual hospital purchasing autonomy. This concentration is most visible across North American health systems where Medtronic, Boston Scientific, and Abbott compete for multi-year supply agreements. Smaller hospitals access interventional cardiology through cath lab equipment leasing partnerships that bundle stent supply commitments.
Surgical Stents Market Segmentation
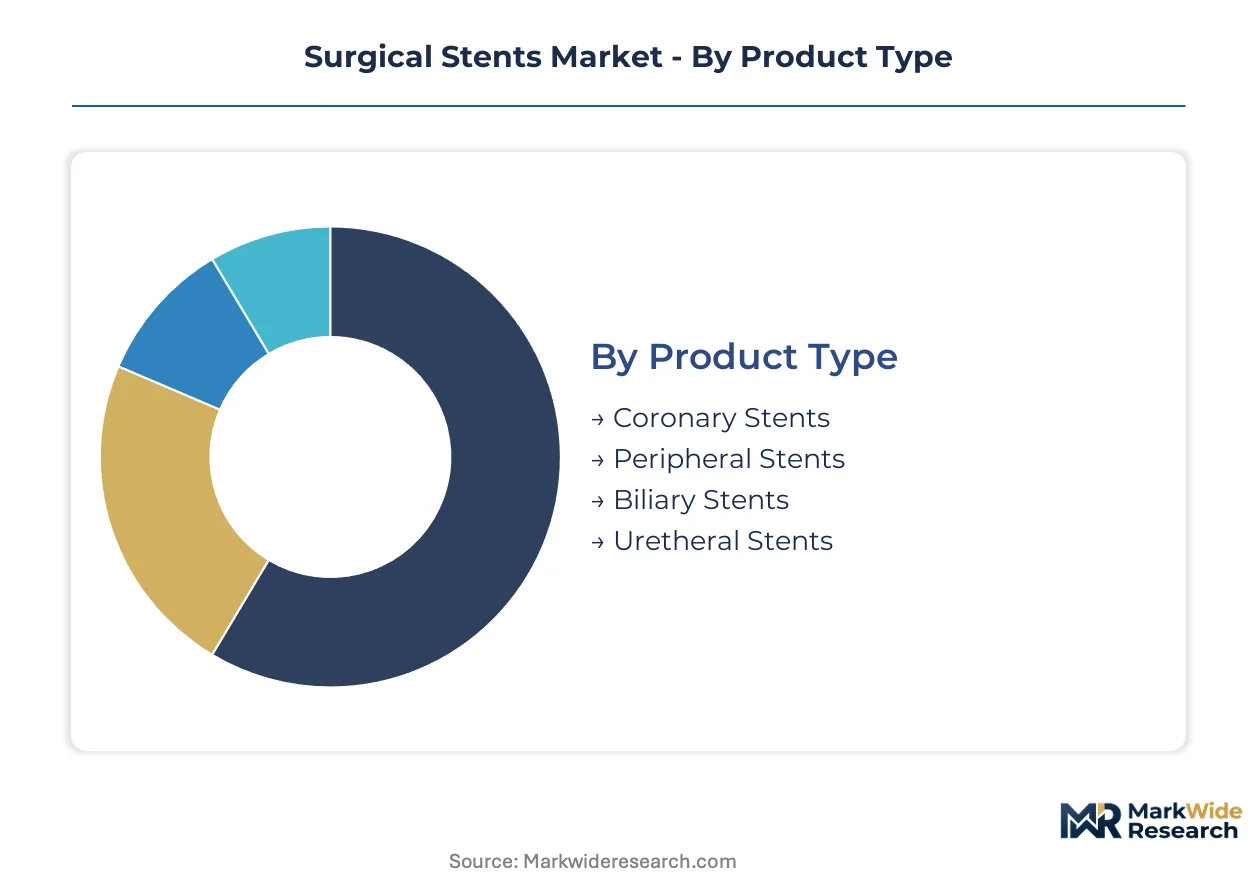
Surgical stent procurement patterns diverge sharply across clinical settings and material platforms. Manufacturers calibrate R&D portfolios and pricing architectures around these dimensional splits, as reimbursement pathways and technical specifications vary by segment.
Product Type:
Application focus determines stent design specifications, with cardiovascular interventions commanding distinct engineering priorities compared to biliary or urological deployments.
- Coronary Stents:Fabricated from cobalt-chromium alloys or stainless steel with strut thickness below 100 micrometers, these devices restore patency in occluded coronary arteries. Demand concentrates in United States and German hospital systems as aging populations and diabetes prevalence expand the addressable patient pool for percutaneous coronary intervention. Drug-eluting platforms dominate complex lesion segments through proprietary polymer-drug combinations.
- Peripheral Stents:Engineered for larger vessel diameters in femoral, popliteal, and renal arteries, these devices require enhanced flexibility and fracture resistance. United States cardiovascular centers are expanding procurement as interventional cardiology networks build out peripheral intervention capabilities. Nitinol self-expanding designs command preference in tortuous anatomies.
- Biliary Stents:Plastic or metallic devices relieve obstruction in the bile duct from malignancy or stricture. Endoscopic retrograde cholangiopancreatography suites in tertiary hospitals drive procurement.
- Urethral Stents:Temporary or permanent devices address prostatic hyperplasia or urethral stricture. Urology clinics and ambulatory surgical centers generate procedure volume.
Coronary stents command the established base. The steepest expansion runs through biodegradable scaffold platforms across all product categories.
Material:
Material science capabilities differentiate competitive positioning, with each matrix presenting distinct biocompatibility profiles and manufacturing complexity.
- Metal:Cobalt-chromium alloys and stainless steel provide durable radial strength through laser-cut tubular structures. German and Japanese metallurgical suppliers concentrate supply, exposing manufacturers to input volatility for thin-strut fabrication.
- Polymer:Permanent polymeric matrices offer MRI compatibility and reduced inflammatory response compared to metallic alternatives. Specialty clinics in United States health systems pilot these platforms for patients with metal sensitivity.
- Drug-eluting:Proprietary polymer-drug combinations release antiproliferative agents to suppress neointimal hyperplasia. FDA and EMA intensified scrutiny of durable polymer coatings extends premarket timelines.
- Biodegradable:Polylactic acid and tyrosine-derived polymers enable temporary scaffolding that fully resorbs within 24-36 months. National health technology assessment bodies in Germany and United States are evaluating reimbursement frameworks for these platforms.
Drug-eluting configurations anchor current revenue pools. Biodegradable materials are climbing the fastest as clinical data accumulates on long-term vessel restoration outcomes.
End User:
Customer type shapes procurement scale and contracting sophistication, with integrated delivery networks concentrating purchasing power away from fragmented independent facilities.
- Hospitals:Cardiovascular centers within hospital systems generate the highest procedure volumes and negotiate multi-year supply agreements with preferred manufacturers. United States integrated delivery networks bundle stent procurement with cath lab equipment leasing partnerships.
- Ambulatory Surgical Centers:Freestanding facilities perform lower-acuity interventions with streamlined supply chains. Asset-light equipment leasing models are reducing capital barriers for these centers to enter interventional cardiology.
- Specialty Clinics:Cardiology and vascular specialty practices concentrate elective procedures. Chinese provincial networks are expanding this tier through localized NMPA regulatory support.
- Rehabilitation Centers:Post-acute facilities manage stent monitoring and secondary prevention programs. Patient flow connections to implanting hospitals influence device brand loyalty.
Hospitals retain volume concentration. Ambulatory surgical centers are gaining share fastest as procedure migration accelerates toward lower-cost settings.
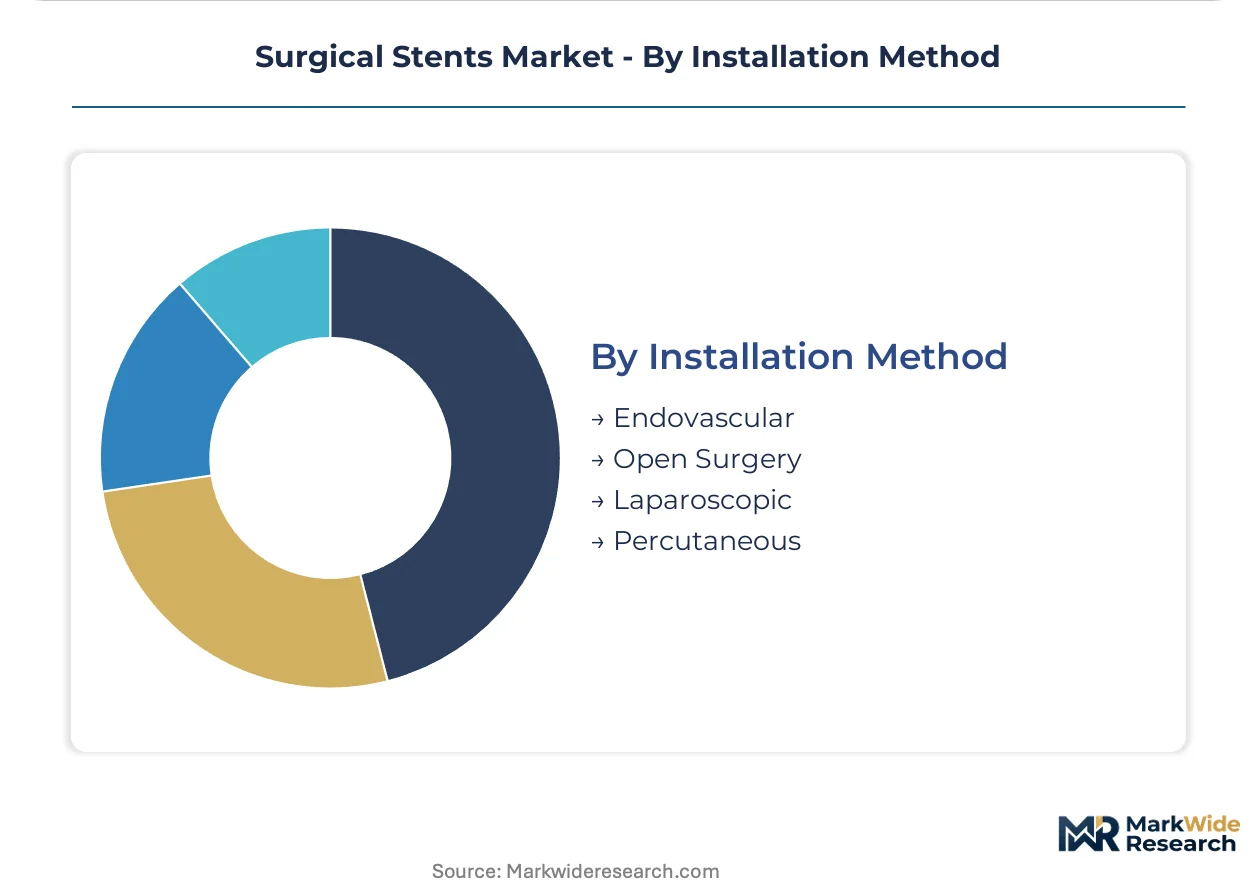
Installation Method:
Deployment technique dictates device design parameters and operator training requirements, with minimally invasive approaches displacing open surgical alternatives.
- Endovascular:Catheter-based delivery through femoral or radial access dominates coronary and peripheral interventions. United States and German catheterization laboratories standardize on this approach for drug-eluting stent deployment.
- Open Surgery:Direct vessel exposure for stent graft placement persists in aortic aneurysm repair and complex redo operations. Tertiary referral centers maintain surgical volume.
- Laparoscopic:Minimally invasive abdominal access supports biliary and ureteral stent placement. Specialty surgical centers deploy these techniques for selected anatomies.
- Percutaneous:Needle-based access without vessel exposure enables rapid intervention. Emergency departments and critical care units utilize this approach for urgent decompression procedures.
Endovascular methods anchor procedural volume. Percutaneous techniques are expanding most quickly across emergency and critical care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of cobalt-chromium alloys and finished stent systems concentrate from German and Japanese metallurgical suppliers toward United States and Chinese assembly operations, creating interdependent regional value chains that shape procurement patterns across cardiovascular centers.
United States
Aging demographics and diabetes prevalence expansion drive percutaneous coronary intervention volumes through integrated delivery networks. FDA premarket approval pathways for biodegradable scaffolds intensify scrutiny of durable polymer coatings, extending commercialization timelines. The Cleveland Clinic and Mayo Clinic cardiovascular centers in Ohio and Minnesota pilot bioresorbable vascular scaffold platforms for younger patient cohorts.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia anchor European demand for drug-eluting stent platforms as interventional cardiology networks expand. EMA Medical Device Regulation CE marking requirements under MDR accelerate consolidation toward manufacturers with robust clinical data portfolios. The Mannheim and Heidelberg university hospital clusters concentrate catheterization laboratory capacity and specialized electropolishing manufacturing partnerships.
China
Provincial hospital networks in Jiangsu and Guangdong provinces are building cath lab capacity through NMPA-supported regulatory pathways for localized stent manufacturing. The country's national pharmaceutical regulator has streamlined approval timelines for domestic drug-eluting platforms. Shanghai and Shenzhen industrial zones concentrate precision laser cutting equipment operators serving both domestic and export-oriented stent fabricators.
Japan
Metallurgical suppliers in the Chubu region around Nagoya specialize in cobalt-chromium alloy refinement for sub-100 micrometer strut fabrication. PMDA marketing approval processes emphasize long-term durability data for biodegradable scaffolds, aligning with the country's aging population risk profiles. Tokyo and Osaka cardiovascular centers maintain preference for ultra-thin strut metallic platforms in complex lesion interventions.
Switzerland
Swissmedic regulatory frameworks attract specialized polymer-drug combination developers seeking premium market positioning within European reimbursement structures. The Basel and Zurich medical technology clusters concentrate precision manufacturing talent for bioresorbable scaffold fabrication. Tertiary hospitals in Geneva and Lausanne participate in multi-center clinical trials evaluating tyrosine-derived polymer resorption timelines.
Surgical Stents Market Vendor Landscape
On the supply side, the industry is consolidating around integrated delivery network contracting power, with procurement concentration favoring manufacturers possessing diversified material science capabilities and established regulatory approval portfolios. Three strategic archetypes dominate: diversified medical technology conglomerates with cath lab equipment bundling capacity, specialized cardiovascular device developers with proprietary polymer-drug platforms, and precision metallurgical suppliers controlling alloy refinement for thin-strut fabrication. Competitive moves center on multi-year supply agreements with health systems and backward integration into cobalt-chromium alloy supply chains to secure input stability.
Within the diversified conglomerate tier, Medtronic and Boston Scientific exemplify positioning through integrated supply chain control and specialized platform development respectively. Abbott occupies a position bridging metallic and bioresorbable scaffold portfolios. Among precision manufacturing specialists, Terumo Corporation and MicroPort Scientific Corporation represent geographic anchoring in Japanese and Chinese industrial clusters. The competitive dynamic situates these named entities as archetype anchors rather than exhaustive market coverage, with additional participants including B Braun, Cook Medical, and BIOTRONIK SE & Co. KG occupying positions across standard and premium-tier segments.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Abbott |
| Terumo Corporation |
| B Braun |
| Biotronik |
| Cook Medical |
| MicroPort Scientific Corporation |
| BIOTRONIK SE & Co. KG |
| Others |
Supply Flow & Price Mechanics
Undercapacity in German and Japanese electropolishing facilities for sub-100 micrometer strut fabrication is compressing margins across cobalt-chromium alloy stent platforms while amplifying pricing leverage for precision metallurgical suppliers serving United States and Chinese manufacturers.
Pricing Analysis
Integrated delivery network buyers anchor a contract-based pricing structure that stratifies across premium drug-eluting, standard metallic, and economy bare-metal tiers. Price differentiation hinges on FDA premarket approval tier and cath lab equipment bundling scale. Cost compression in standard metallic tiers is intensifying because Chinese provincial networks are negotiating localized NMPA-supported supply agreements. Ambulatory surgical centers exhibit highest price sensitivity; tertiary cardiovascular centers in Germany and the United States show lowest sensitivity due to bundled procurement agreements.
Supply Chain Analysis
Contract manufacturing for laser-cut stent fabrication concentrates among precision equipment operators in Germany, Japan, and Switzerland. Raw material sourcing draws from cobalt-chromium alloy refiners in the Chubu region of Japan and specialized polymer compounders in Basel. Supply chain risk centers on single-source vulnerability for electropolishing capacity serving thin-strut platforms. Distribution runs through integrated delivery network procurement committees and GPO contracts managers in United States hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in cath lab equipment leasing and procedural training contracts are expanding faster than hardware revenue as asset-light models penetrate secondary hospitals.
For Market Incumbents: Build regulatory data moats through biodegradable scaffold durability portfolios that exceed EMA MDR and FDA software-as-medical-device documentation requirements. Deepen backward integration into cobalt-chromium alloy supply chains to neutralize Japanese metallurgical supplier concentration. Secure multi-year supply agreements with Chinese provincial networks before NMPA localization mandates harden. For New Entrants and Emerging Players: Establish a beachhead in ambulatory surgical center stent procurement through asset-light equipment leasing partnerships that bundle training and inventory management. Chinese interventional cardiology buildout in Jiangsu and Guangdong provinces offers the most penetrable geography. Target GPO contracts managers with outcome-based reimbursement narratives for biodegradable platforms. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with cath lab equipment leasing partnerships and multi-year IDN supply agreements. Five-to-ten year viability favors precision metallurgical specialists with captive electropolishing capacity. Monitor NMPA approval timelines for domestic Chinese drug-eluting platforms as inflection signal for competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance accelerates consolidation toward manufacturers with robust clinical data portfolios. |
| Hospital System Partnership | Integrated delivery network contracting bundles stent procurement with cath lab equipment leasing. |
| Backward Integration | Cobalt-chromium alloy supply control neutralizes concentration risk among Japanese and German metallurgical suppliers. |
| Software Companion Development | AI-enabled computational modeling for stent fatigue prediction triggers EU AI Act compliance requirements. |
| Reimbursement Strategy | National health technology assessment body decisions on biodegradable scaffolds determine premium tier access. |
Methodological Framework
Operator-level perspectives from interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) and PMA filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Scenario-bracketing framed projections across the analysis window through segmented modeling of product type, material platform, end-user facility tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating diabetes prevalence trajectories and cath lab capacity expansion schedules. Biodegradable scaffold durability data accumulation and NMPA localization policy evolution served as key forecast inputs.
Sensitivities concentrate around EMA MDR enforcement intensity, Chinese provincial procurement localization timelines, and biodegradable scaffold long-term vessel restoration outcomes. Quarterly review of FDA premarket approval queue depth and NMPA domestic manufacturer certification rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Surgical Stapling Devices Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Surgical Broaches Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Surgical Hemostats Market