
 Europe Minimally Invasive Surgery Market | 2026-2036
Europe Minimally Invasive Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Minimally Invasive Surgery Market Intelligence
The Europe minimally invasive surgery landscape is pivoting between premium robotic-assisted platforms and commodity-priced handheld instruments. Medtronic leverages its integrated surgical ecosystem to sustain pricing power across European procurement networks. Siemens Healthineers anchors its position through advanced imaging-to-navigation workflows that differentiate high-end installations. Smith & Nephew competes in arthroscopy and sports medicine segments where specialized instrument portfolios command loyalty.
Minimally invasive surgery encompasses operative techniques performed through small incisions using specialized instruments, visualization systems, and energy devices, typically limiting access ports to under two centimeters while preserving tissue planes and reducing postoperative recovery. Laparoscopic technique and endoscopic procedure represent mature technology foundations, whereas robotic systems capture expanding capital budgets as hospitals amortize platform costs across higher surgical volumes. Visualization systems concentrate margin pools where 4K and fluorescence-capable modalities command upgrade cycles, while handheld devices face commoditization pressure from regional manufacturers.
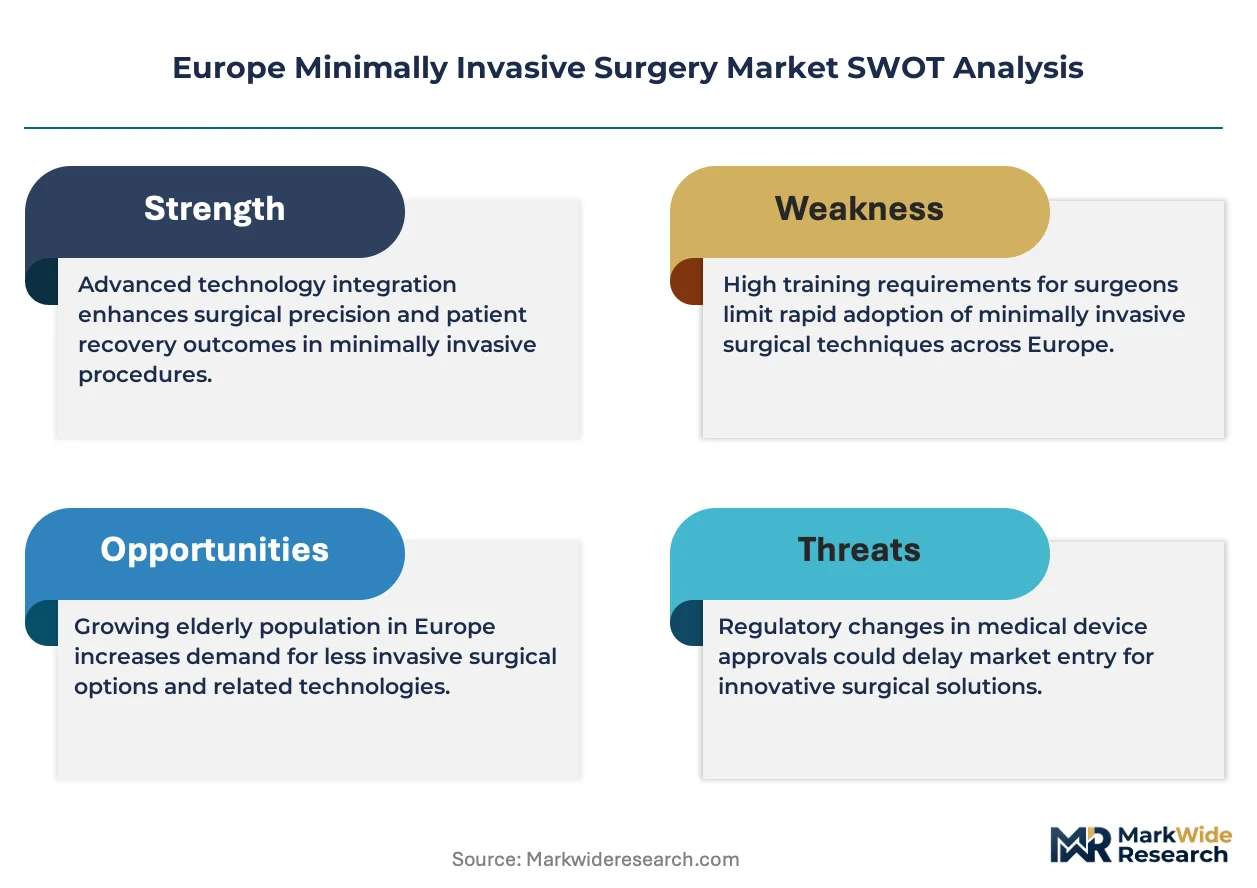
EMA coordinates clinical evaluation standards for novel surgical devices across member states, while the EU Medical Device Regulation mandates unique device identifiers and strengthened post-market surveillance that elevates compliance costs for instrument suppliers. REACH and RoHS frameworks constrain material selections in reusable device manufacturing, particularly affecting polymers and coatings in sterilization-intensive environments. Stakeholders must monitor how notified body capacity constraints reshape market access timelines for innovative surgical technologies.
Market Dynamics
Hospital consolidation across Germany, France, and the Netherlands is compressing vendor lists and forcing instrument suppliers to defend procurement slots through bundled service contracts rather than standalone device sales.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation mandates unique device identifiers and strengthened post-market surveillance, accelerating replacement cycles for legacy instruments as facilities preempt conformity gaps.
- Ambulatory surgical center expansion:Same-day discharge protocols in France and Spain are driving capital allocation toward compact, portable visualization systems that fit constrained facility footprints.
- Fluorescence-guided surgery:Near-infrared imaging capabilities are penetrating oncology and reconstructive procedures as surgeons seek real-time tissue perfusion data without open-field exposure.
Market Restraints
- Notified body capacity bottlenecks:EU MDR implementation has strained conformity assessment infrastructure, extending market access timelines for novel surgical technologies by 12-18 months.
- Reusable instrument sterilization costs:REACH and RoHS constraints on polymer and coating selections have elevated per-cycle reprocessing expenses for laparoscopic device fleets.
- Robotic platform capital intensity:Amortization requirements for da Vinci and comparable systems limit penetration to high-volume academic medical centers, excluding community hospitals.
Strategic Opportunities
- Poland and Romania hospital modernization:EU cohesion fund inflows are financing surgical suite upgrades in Eastern European markets where laparoscopic penetration remains below Western benchmarks.
- Disposable instrument conversion:Single-use trocars and clip appliers are capturing share from reprocessing-dependent alternatives as facilities prioritize infection control and workflow efficiency.
- AI-assisted preoperative planning:Machine learning segmentation of imaging data is converging with surgical navigation to reduce operative time variability in complex oncologic resections.
Industry Challenges
- Robotic console operator certification:Proctoring requirements and case volume thresholds are constraining effective utilization rates for installed surgical robot bases.
- Interoperability with legacy imaging archives:PACS integration complexity is delaying deployment of advanced visualization modalities in renovated European hospital campuses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Minimally Invasive Surgery Market |
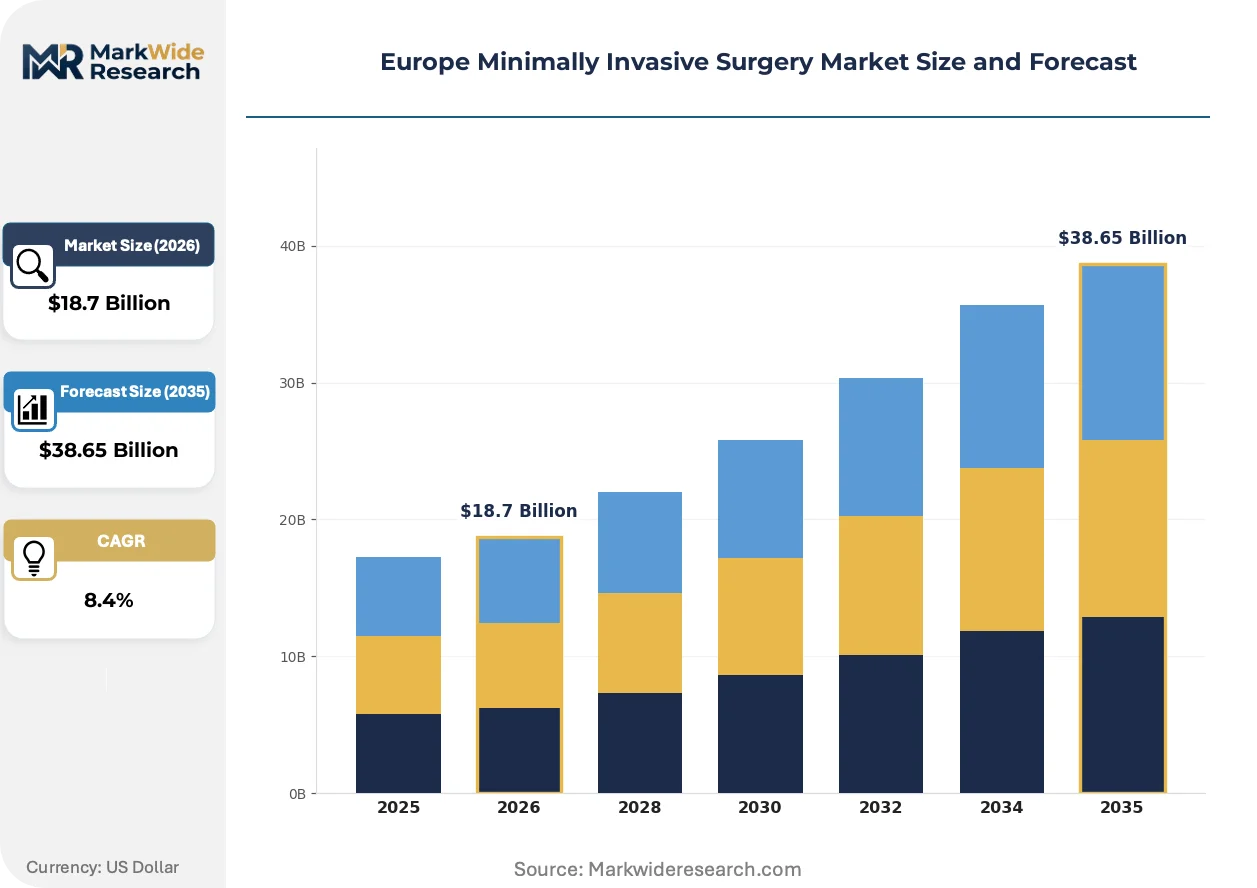
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Surgical Instruments, Visualization Systems, Handheld Devices End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Application: Cardiac Surgery, Orthopedic Surgery, Gastrointestinal Surgery, Urologic Surgery Technology: Laser Technology, Laparoscopic Technique, Endoscopic Procedure, Radiofrequency Energy |
| Companies Covered | Olympus Corporation, Koninklijke Philips NV, Medtronic, Smith & Nephew, General Electric Company (GE Healthcare), Intuitive Surgical, Siemens Healthineers, Zimmer Biomet, Stryker Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Minimally Invasive Surgery Market Strategic Shifts & Innovations
Digital surgery ecosystems are displacing standalone instrument sales as European procurement networks prioritize vendor ecosystems that bundle hardware, software, and outcome analytics under multi-year contracts.
Single-port robotic platforms are converging with advanced energy devices to enable reduced-access oncologic procedures through 2.5-centimeter umbilical incisions. Academic medical centers in Germany and Italy are piloting these configurations for colorectal and gynecologic resections. The technology is converging with fluorescence navigation to compress operative time and postoperative length-of-stay metrics.
REACH substance restrictions are forcing reformulation of sterilization-resistant polymers used in reusable instrument handles and insulation layers. ECHA's candidate list expansion is accelerating substitution of bisphenol-A derivatives and certain phthalates in device manufacturing. Suppliers with early alternative material certifications are securing preferred supplier status in Nordic and German procurement networks.
Centralized purchasing consortia in France and the Netherlands are unbundling service contracts from capital equipment leases, pressuring vendors to compete on transparent per-procedure cost structures. Hospital groups are deploying internal value-analysis teams to benchmark instrument utilization against published episode-of-care data. This behavioral shift is most pronounced in Belgium, where federal budget constraints have intensified scrutiny of surgical supply spend.
Europe Minimally Invasive Surgery Market Segmentation
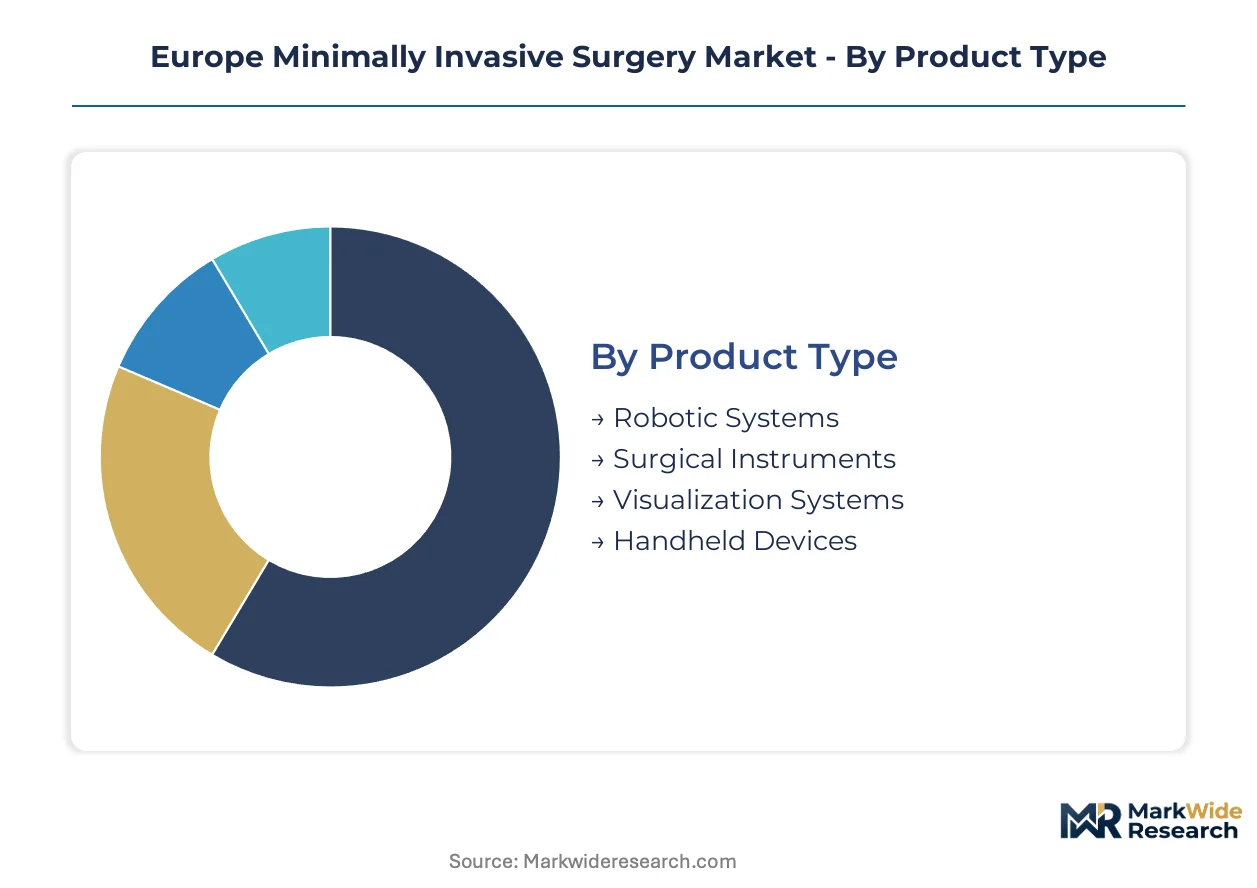
Procurement patterns across Europe diverge sharply between capital-intensive robotic platforms and high-volume consumables. Hospital consolidation in Germany and France is compressing vendor lists and forcing suppliers to defend positions through bundled contracts rather than standalone device sales.
Product Type:
Capital allocation decisions separate premium robotic installations from commodity instrument purchases as facilities amortize platform costs across surgical volumes.
- Robotic Systems:Computer-assisted surgical platforms integrate haptic feedback, tremor filtration, and 3D visualization to enable precise instrument manipulation through small incisions. Demand concentrates in German academic medical centers where case volume thresholds justify da Vinci and comparable system amortization.
- Surgical Instruments:Graspers, dissectors, clip appliers, and staplers constitute the procedural workhorse category, with single-use variants capturing share from reprocessing-dependent alternatives. French and Dutch hospital groups prioritize disposable trocars to eliminate sterilization bottlenecks and infection control liabilities.
- Visualization Systems:4K and fluorescence-capable imaging modalities command upgrade cycles in renovated surgical suites.
- Handheld Devices:Manual laparoscopic instruments face commoditization pressure from regional manufacturers in Poland and Turkey.
Volume sits with Surgical Instruments; growth tilts toward Robotic Systems.
End User:
Facility type dictates equipment specifications, with ambulatory centers demanding compact footprints and hospitals prioritizing multi-specialty versatility.
- Hospitals:Multi-disciplinary institutions anchor demand for integrated surgical ecosystems combining robotics, advanced imaging, and navigation. German hospital consolidation is driving centralized procurement of platforms serving colorectal, gynecologic, and urologic specialties.
- Ambulatory Surgical Centers:Same-day discharge protocols in France and Spain require portable, space-efficient visualization systems with rapid turnover capabilities. EU cohesion fund inflows are financing ASC conversions in Eastern European markets.
- Clinics:Office-based procedures utilize compact endoscopic systems for diagnostic and minor interventional applications.
- Research Institutions:Academic medical centers in Italy and the Netherlands pilot single-port robotic configurations and fluorescence-guided techniques.
Procurement volume clusters in Hospitals; ASC expansion is climbing the fastest.
Application:
Procedure complexity determines technology selection, with oncologic resections requiring navigation integration and sports medicine favoring specialized arthroscopic portfolios.
- Cardiac Surgery:Minimally invasive valve repair and coronary bypass procedures demand robotic precision for beating-heart operations. German and Swiss centers lead adoption of endoscopic saphenous vein harvesting and mitral valve reconstruction.
- Orthopedic Surgery:Arthroscopic joint repair and reconstruction represent mature, high-volume applications with established reimbursement pathways. Smith & Nephew and specialized competitors command loyalty through instrument portfolio depth in sports medicine segments.
- Gastrointestinal Surgery:Laparoscopic colectomy and bariatric procedures drive utilization of advanced energy devices and stapling platforms.
- Urologic Surgery:Prostatectomy and nephrectomy applications pioneered robotic adoption in European urology departments.
Orthopedic Surgery holds installed base dominance; Cardiac Surgery is gaining share fastest through precision-demanding procedures.
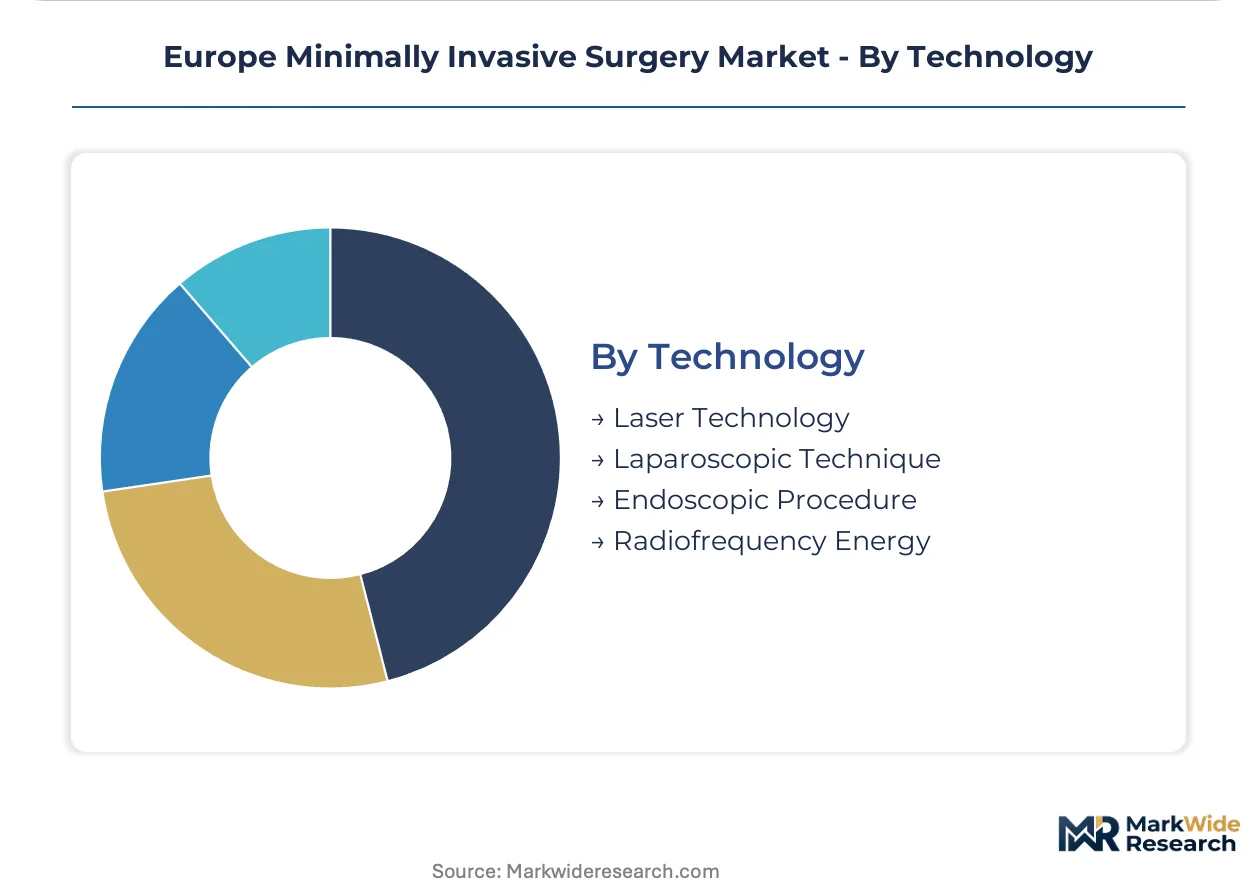
Technology:
Energy modality selection shapes tissue interaction characteristics, with thermal spread and hemostatic performance driving surgeon preference.
- Laser Technology:Precise tissue ablation with minimal collateral thermal damage enables delicate procedures in otolaryngology and ophthalmology. Nordic procurement networks prioritize laser platforms for outpatient surgical suites.
- Laparoscopic Technique:Multi-port abdominal access through 5-12mm trocars remains the foundational minimally invasive approach across general surgery. Belgian and Dutch value-analysis teams benchmark laparoscopic instrument utilization against episode-of-care data.
- Endoscopic Procedure:Natural orifice and transluminal techniques reduce access trauma for gastrointestinal and thoracic interventions.
- Radiofrequency Energy:Tissue ablation and vessel sealing applications leverage controlled thermal delivery for hemostasis and lesion creation.
Laparoscopic Technique commands procedure volume; Laser Technology is expanding most quickly in precision-specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr-Rhine corridor anchors European minimally invasive surgery demand, with university hospitals in Essen and Düsseldorf driving robotic platform adoption across colorectal and gynecologic specialties.
Germany
Hospital consolidation across North Rhine-Westphalia and Bavaria is compressing vendor lists as centralized procurement teams negotiate multi-year robotic platform leases. The EU Medical Device Regulation is accelerating replacement cycles for legacy laparoscopic instruments as facilities preempt conformity gaps. The Berlin-Brandenburg medical technology cluster is piloting AI-assisted preoperative planning tools for complex oncologic resections.
France
Ambulatory surgical center expansion in Île-de-France and Auvergne-Rhône-Alpes is driving capital allocation toward compact, portable visualization systems with rapid turnover capabilities. ANSM post-market surveillance requirements are elevating compliance costs for reusable instrument suppliers. The Lyon surgical corridor is emerging as a testing ground for single-port robotic configurations in colorectal procedures.
United Kingdom
NHS England's centralized procurement frameworks are unbundling service contracts from capital equipment leases, pressuring vendors on transparent per-procedure cost structures. MHRA recognition of EU MDR certificates is streamlining market access for notified body-approved devices. The Oxford-Cambridge-London golden triangle is concentrating research institution pilot programs for fluorescence-guided surgery.
Italy
Regional health authority budget constraints in Lombardy and Emilia-Romagna are intensifying scrutiny of surgical supply spend through internal value-analysis teams. ECHA REACH substance restrictions are forcing reformulation of sterilization-resistant polymers in reusable instrument manufacturing. The Milan-Turin medical device corridor is hosting pilot deployments of near-infrared imaging capabilities for oncologic procedures.
Netherlands
Hospital group consolidation in the Randstad region is driving bundled service contracts rather than standalone device sales for laparoscopic instrument fleets. Dutch healthcare procurement consortia are benchmarking instrument utilization against published episode-of-care data. The Eindhoven medical technology cluster is advancing interoperability standards for advanced visualization modalities with legacy PACS archives.
Europe Minimally Invasive Surgery Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the European minimally invasive surgery landscape. Integrated surgical ecosystem vendors hold pricing power through bundled hardware-software-service contracts, while specialized instrument manufacturers defend positions through portfolio depth in narrow application segments. Three archetypes dominate: diversified medtech conglomerates with full-stack capabilities, pure-play visualization specialists, and regional disposable instrument fabricators. Competitive moves concentrate on strategic partnerships for AI integration and capacity expansion in Eastern European manufacturing zones.
Within the diversified conglomerate tier, Medtronic and Siemens Healthineers exemplify integrated ecosystem positioning across European procurement networks. Smith & Nephew occupies a specialist anchor position in arthroscopy and sports medicine segments where instrument portfolio breadth commands procurement loyalty. Among robotics-focused innovators, Intuitive Surgical represents the capital-intensive platform archetype whose installed base amortization models concentrate demand in high-volume academic medical centers.
| Leading Market Players |
|---|
| Olympus Corporation |
| Koninklijke Philips NV |
| Medtronic |
| Smith & Nephew |
| General Electric Company (GE Healthcare) |
| Intuitive Surgical |
| Siemens Healthineers |
| Zimmer Biomet |
| Stryker Corporation |
| Others |
Cost & Logistics Intelligence
Robotic platform premiumization against handheld instrument commoditization bifurcates procurement economics across European surgical networks, with Germany's centralized hospital groups extracting per-procedure discounts from vendors while Eastern European facilities absorb higher landed costs for imported consumables. This divergence manifests in bundled service contracts anchoring high-end installations versus spot purchasing of disposable trocars, and in supply chains that cluster precision manufacturing in Germany and Switzerland while sourcing commodity polymers from regional fabricators in Poland and Turkey.
Pricing Analysis
Outcome-linked value anchors dominate robotic system negotiations, with German hospital consortia benchmarking per-case costs against length-of-stay reductions and complication rate improvements. Three-tier pricing structure across premium, standard, and economy levels separates da Vinci installations from compact visualization systems and unbranded handheld instruments. Cost compression in disposable trocars intensifies as French ASCs prioritize infection control over instrument longevity. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with amortization capacity show lowest.
Supply Chain Analysis
Freight cost differentials between precision-engineered robotic consoles and lightweight disposable instruments reshape distribution economics, with capital equipment requiring white-glove installation teams while consumables move through medical distributor networks. Supply concentrates in Germany, Switzerland, and the United States for robotic platforms; Poland, Turkey, and China for commodity handheld devices. Raw material dependencies span medical-grade stainless steel, high-performance polymers, and rare-earth elements for imaging sensors. Single-source vulnerability sits with fluorescence-capable camera modules. Distribution runs through specialized medical device distributors serving consolidated hospital purchasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-port robotic configurations are displacing multi-port laparoscopic systems across European oncology departments, compressing upgrade cycles for installed visualization fleets and rewriting procurement specifications for surgical suite renovations.
For Market Incumbents: Deploy AI-assisted preoperative planning as a bundling lever to defend procurement slots against pure-play software entrants. Deepen service contract penetration in Dutch and Belgian hospital groups where value-analysis teams benchmark utilization rigorously. Counter disposable instrument conversion by demonstrating total cost-of-ownership advantages for sterilization-validated reusable fleets under REACH-compliant polymer formulations.
For New Entrants and Emerging Players: Enter via fluorescence-navigation modules that retrofit legacy 4K visualization systems in Italian and Spanish facilities delaying full platform replacement. Target Poland and Romania where EU cohesion fund inflows finance surgical suite modernization but Western vendor presence remains thin. Pursue GPO contracts with emerging Eastern European hospital networks before incumbent ecosystem lock-in solidifies.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified medtech conglomerates seeking visualization-to-navigation workflow integration. Long-term viability favors suppliers with certified alternative polymers ahead of ECHA candidate list expansions. Watch EMA guidance on AI-enabled surgical devices as the inflection signal for regulatory-premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment accelerates replacement cycles for legacy instrument fleets. |
| Hospital System Partnership | Bundled contracts with German consolidated groups secure multi-year robotic platform utilization. |
| Software Companion Development | AI-assisted preoperative planning reduces operative time variability in complex oncologic resections. |
| Reimbursement Strategy | Same-day discharge protocol alignment drives ASC demand for compact visualization systems. |
| Backward Integration into Polymer Formulation | In-house REACH-compliant material development secures preferred supplier status in Nordic procurement networks. |
Research Approach
Independent corroboration across hospital procurement databases, GPO contract filings, and EMA device registrations underwrites the qualitative findings on vendor positioning and compliance timelines. Primary interviews with hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation through notified body capacity reports, REACH substance restriction updates, and customs trade data on surgical instrument imports. Bottom-up procedure volume estimates and top-down capital expenditure tracking triangulate market sizing.
Rate-of-change decomposition across product type, end user facility tier, application specialty, and technology modality structures the analytical framework over the projection horizon. CAGRs derive from segmented volume trajectories weighted by ASP evolution in robotic versus handheld categories. Forecast inputs incorporate EU MDR implementation pace, cohesion fund disbursement schedules for Eastern European hospital modernization, and fluorescence imaging adoption curves in oncologic procedures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity constraints extending market access timelines or accelerated REACH substance bans forcing emergency polymer reformulation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Special Purpose Needles Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Global Arthroscopy Instruments Market