
 Laparoscopic Needle Holder Robotic Devices Market | 2026-2036
Laparoscopic Needle Holder Robotic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Laparoscopic Needle Holder Robotic Devices Market Analytics
North American surgical instrument manufacturers is recalibrating production schedules to address backlogs in robotic-assisted platform components. Stryker Corporation leverages its integrated operating-room ecosystem to bundle needle holders with navigation systems. Intuitive Surgical dominates the installed-base logic by tying instrument compatibility to its da Vinci platform architecture. Medtronic anchors European procurement channels through its distributed surgical robotics service network.
Laparoscopic needle holder robotic devices are precision electromechanical instruments designed to grasp, rotate, and drive suture needles through tissue during minimally invasive procedures, typically featuring force-feedback sensors and articulating wrist mechanisms with seven degrees of freedom. These devices serve the primary commercial purpose of reducing surgeon fatigue and standardizing suturing consistency in complex laparoscopic operations. Electromechanical holder systems command the dominant share of product-type revenue due to their integration with robotic surgical platforms. Gynecological surgery represents the fastest-growing application segment as myomectomy and hysterectomy volumes shift to minimally invasive approaches. Hospitals absorb the majority of end-user spending through capital equipment budgets and long-term service contracts.
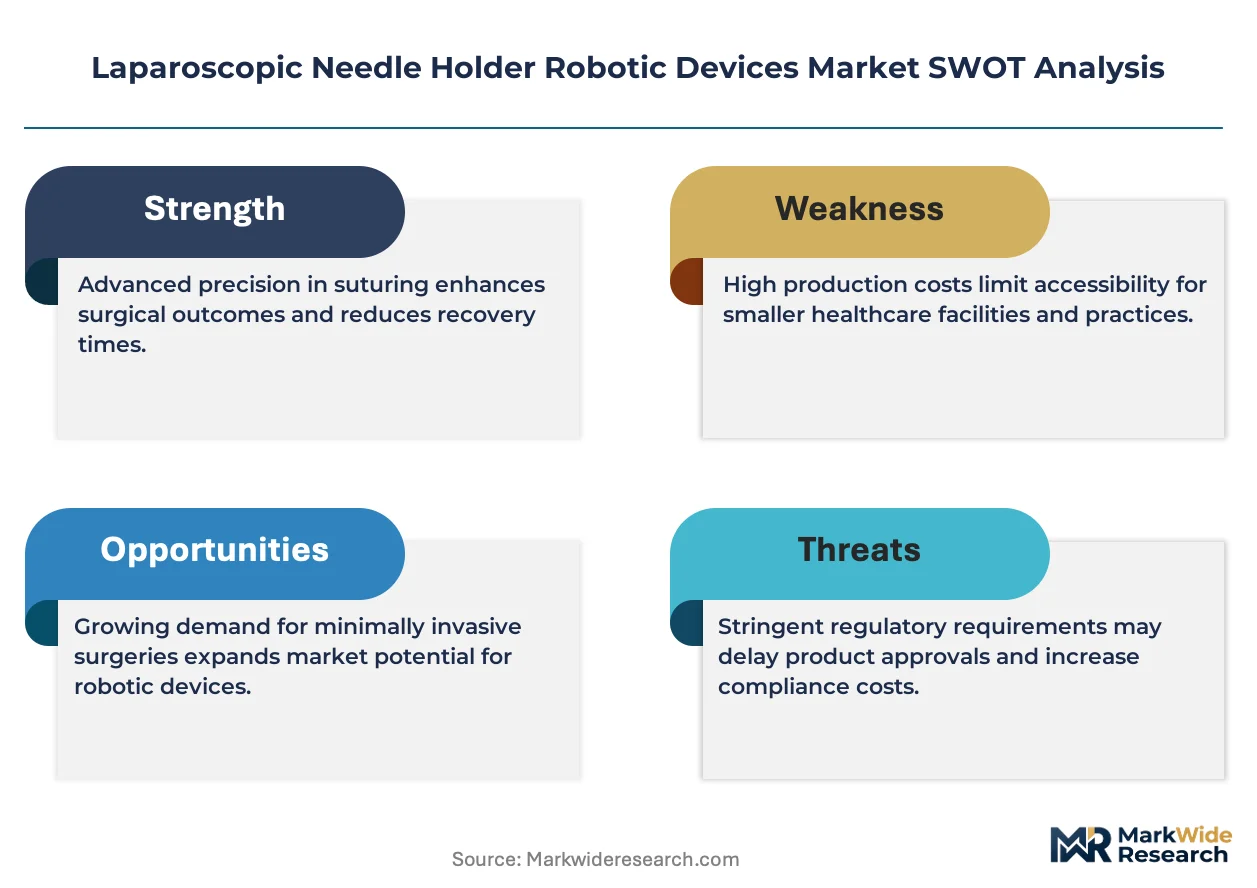
FDA 510(k) clearance requirements and the EU MDR conformity assessment process govern market access for robotic needle holders, with both frameworks mandating biocompatibility testing and electrical safety validation under IEC 60601 standards. Japan's PMDA imposes additional clinical performance benchmarks for novel articulation mechanisms before reimbursement approval. ISO 13485 quality management certification has become a baseline procurement filter for hospital systems evaluating vendor qualification. Stakeholders must monitor how evolving software-as-medical-device interpretations affect cloud-connected instrument validation obligations.
Market Dynamics
The da Vinci platform's proprietary instrument architecture has created a closed-ecosystem dynamic where hospital capital commitments to Intuitive Surgical's installed base lock in recurring needle holder revenue streams and deter multi-vendor procurement strategies.
Growth Catalysts
- EU MDR compliance deadlines:European tertiary hospitals are accelerating robotic platform procurement ahead of stricter conformity assessment timelines for Class II surgical instruments, compressing sales cycles for electromechanical suturing systems.
- Myomectomy volume migration:Gynecological departments in United States academic medical centers are shifting open hysterectomy procedures to minimally invasive approaches, expanding robotic needle holder utilization rates per operating room.
- Force-feedback sensor maturation:Haptic resolution improvements in seven-degree-of-freedom wrist mechanisms are reducing surgeon training time and expanding addressable operator pools beyond fellowship-trained specialists.
Market Restraints
- Precious metal input volatility:Electromechanical holder production relies on platinum-iridium electrodes and surgical-grade stainless steel, exposing manufacturers to commodity price swings that compress gross margins on single-use instrument contracts.
- Platform-specific sterilization protocols:Each robotic ecosystem demands proprietary reprocessing workflows, fragmenting hospital sterile processing department capacity and limiting vendor switching flexibility.
- Reimbursement lag in Japan:PMDA clinical performance benchmarks for novel articulation mechanisms delay national health insurance listing, extending payback periods for capital equipment investments in Japanese prefectural hospitals.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentive structures for high-value surgical instruments are attracting contract manufacturers to establish electromechanical assembly capacity serving domestic tertiary care networks.
- Cloud-connected instrument validation:Software-as-medical-device interpretations are creating pathways for remote firmware updates and predictive maintenance contracts, shifting revenue from hardware sales to recurring SaaS models.
- Ambulatory surgical center expansion:Freestanding outpatient facilities in Germany are procuring compact robotic platforms with integrated needle holders, opening a channel previously dominated by inpatient hospital capital budgets.
Industry Challenges
- Mechatronics engineering scarcity:The intersection of surgical instrument design, IEC 60601 electrical safety compliance, and ISO 13485 quality systems requires specialized talent pools that medical device manufacturers compete for against automotive and aerospace sectors.
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies for novel polymer coatings on articulating wrist housings extend product development timelines by eight to fourteen months.
- Legacy platform integration friction:Third-party needle holders must achieve electromagnetic compatibility certification with existing da Vinci patient-side cart architectures, creating technical validation dependencies on incumbent ecosystem owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laparoscopic Needle Holder Robotic Devices Market |
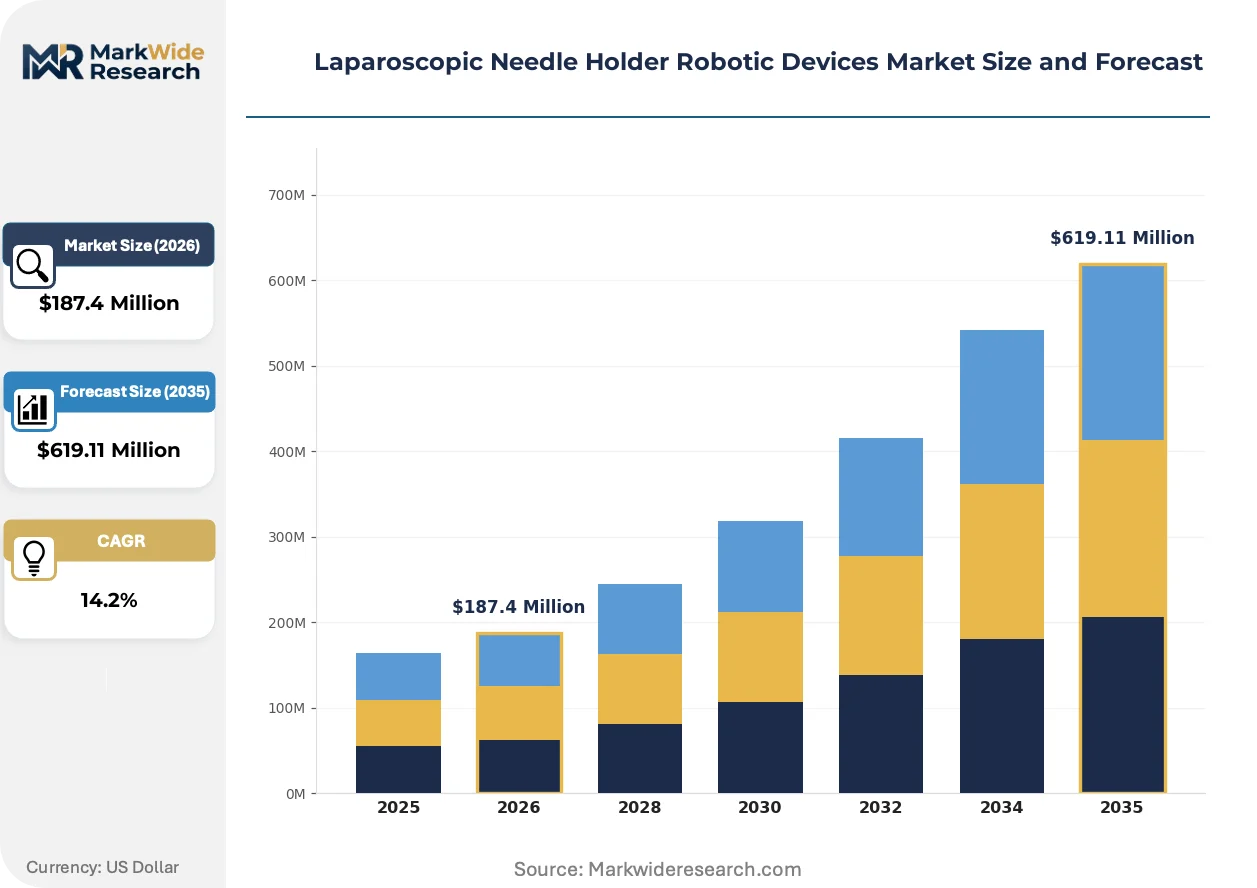
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Assist Devices, Manual Needle Holders, Electromechanical Holders, Disposable Holder Systems Technology: Electromechanical, Pneumatic, Hydraulic, Robotic Application: General Surgery, Bariatric Surgery, Gynecological Surgery, Urological Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Stryker Corporation, Olympus Corporation, Intuitive Surgical, CMR Surgical, Smith & Nephew, Johnson & Johnson (Ethicon), Karl Storz SE & Co. KG, Asensus Surgical, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laparoscopic Needle Holder Robotic Devices Market Evolving Landscape
Electromechanical precision is merging with data-centric service models across robotic surgical platforms. Manufacturers are embedding sensor arrays that capture instrument-tissue interaction metrics, enabling outcome-linked contracting and remote technical support.
Machine learning algorithms trained on suture placement kinematics are converging with real-time haptic feedback systems. United States teaching hospitals are piloting these augmented guidance modules to standardize resident training curves. The convergence is compressing the gap between novice and expert operative metrics, potentially expanding the addressable surgeon population beyond traditional fellowship pipelines.
FDA 510(k) clearance pathways for electromechanical surgical instruments are tightening software documentation requirements under evolving SaMD guidance. Manufacturers must now submit algorithm validation protocols for force-limiting safety interlocks. Class II instrument sponsors are responding by embedding quality management systems that trace each software build to specific hardware configurations, increasing regulatory submission costs but reducing post-market surveillance liabilities.
Hospital capital committees are unbundling instrument service contracts from platform purchase agreements. German hospital procurement associations now negotiate needle holder availability guarantees separately from robotic system warranties, pressuring vendors to maintain regional spare-part inventories. The unbundling is most advanced in Bavaria and North Rhine-Westphalia, where centralized purchasing cooperatives aggregate demand across multiple university hospital networks.
Laparoscopic Needle Holder Robotic Devices Market Segmentation
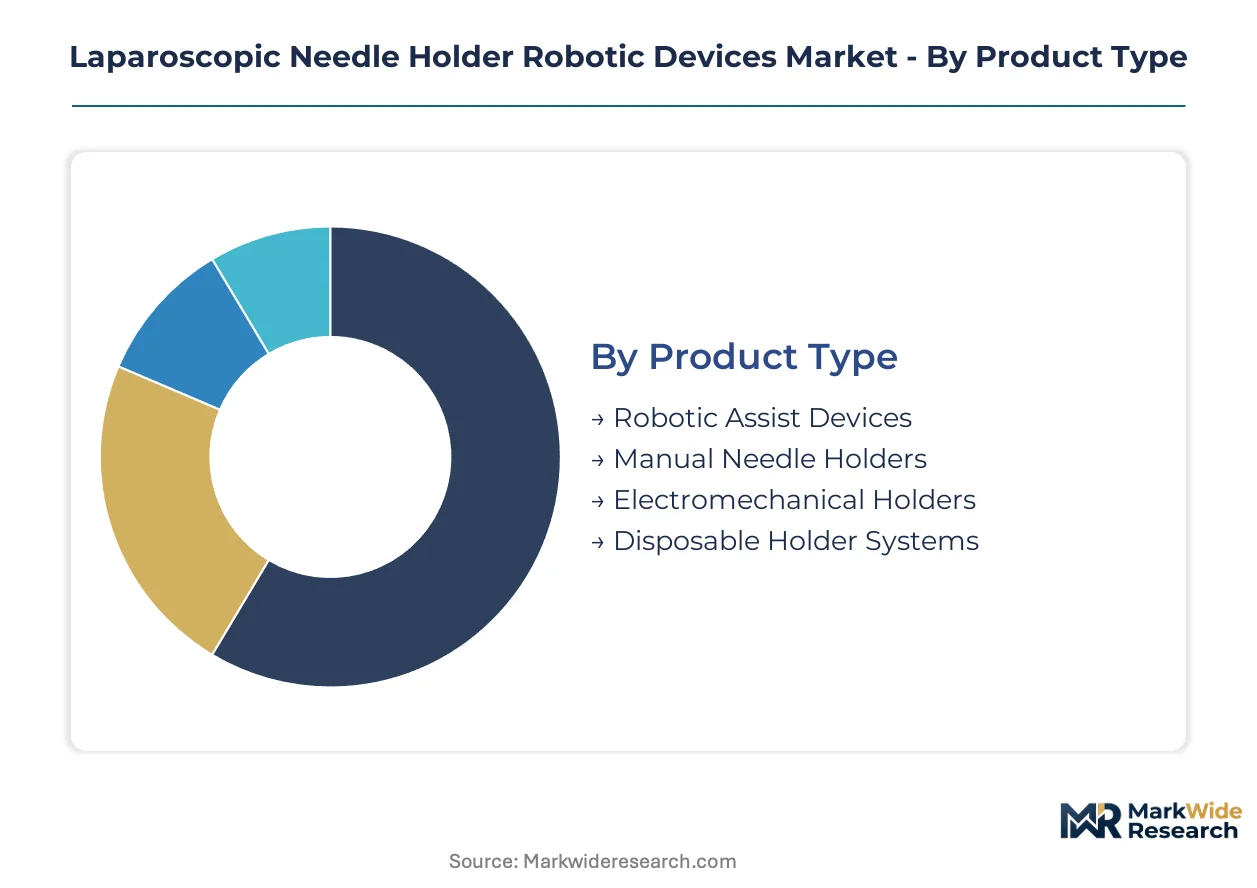
Segmentation in laparoscopic needle holder robotic devices reveals how regulatory pathways, capital intensity, and procedural specialization fragment procurement decisions across hospital systems. Each dimension carries distinct certification burdens that shape vendor qualification timelines and contract structures.
Product Type:
FDA 510(k) clearance requirements vary sharply across this category, with electromechanical systems facing Class II scrutiny while manual holders bypass premarket notification entirely.
- Electromechanical Holders:Precision motor-driven instruments with force-feedback sensors and articulating wrist mechanisms. United States academic medical centers dominate procurement as da Vinci platform compatibility becomes a non-negotiable specification.
- Robotic Assist Devices:Semi-autonomous systems that augment surgeon hand movements through motion scaling. German university hospitals absorb the majority of European installations, driven by EU MDR conformity assessment deadlines compressing procurement cycles for validated platforms.
- Manual Needle Holders:Conventional laparoscopic graspers without electromechanical actuation.
- Disposable Holder Systems:Single-use instruments eliminating sterilization workflow complexity.
Electromechanical holders sit at the top of the volume ranking, with robotic assist devices climbing the fastest.
Technology:
Capital deployment patterns across this dimension track the trade-off between haptic fidelity and maintenance infrastructure, with pneumatic systems demanding compressed air architecture that many older operating rooms lack.
- Electromechanical:Servo-motor actuation with seven-degree-of-freedom wrist articulation and real-time force sensing. Japanese prefectural hospitals concentrate demand where PMDA reimbursement benchmarks favor proven kinematic platforms over novel mechanisms.
- Robotic:Fully integrated platforms with proprietary instrument architectures and software-mediated control loops. United States integrated delivery networks lock in recurring revenue through long-term service contracts tied to installed-base expansion.
- Pneumatic:Compressed air-driven actuation with simpler mechanical construction.
- Hydraulic:Fluid-pressure transmission systems offering high force density in compact form factors.
Electromechanical technology commands the dominant revenue share, while fully robotic systems are gaining share fastest through platform bundling strategies.
Application:
Procedure-specific reimbursement codes determine addressable market size within each segment, with gynecological surgery benefiting from CMS valuation shifts toward minimally invasive hysterectomy approaches.
- Gynecological Surgery:Myomectomy and hysterectomy procedures requiring fine suture placement in confined pelvic anatomy. United States teaching hospitals drive volume as resident training programs migrate open cases to laparoscopic approaches.
- General Surgery:Broad procedural category spanning cholecystectomy, hernia repair, and colorectal resection. German hospital procurement associations negotiate availability guarantees across Bavaria and North Rhine-Westphalia networks.
- Bariatric Surgery:Gastric bypass and sleeve gastrectomy applications demanding robust tissue grasping.
- Urological Surgery:Prostatectomy and nephrectomy procedures with deep pelvic dissection requirements.
General surgery sits at the top of the volume ranking, with gynecological surgery expanding most quickly through procedure migration.
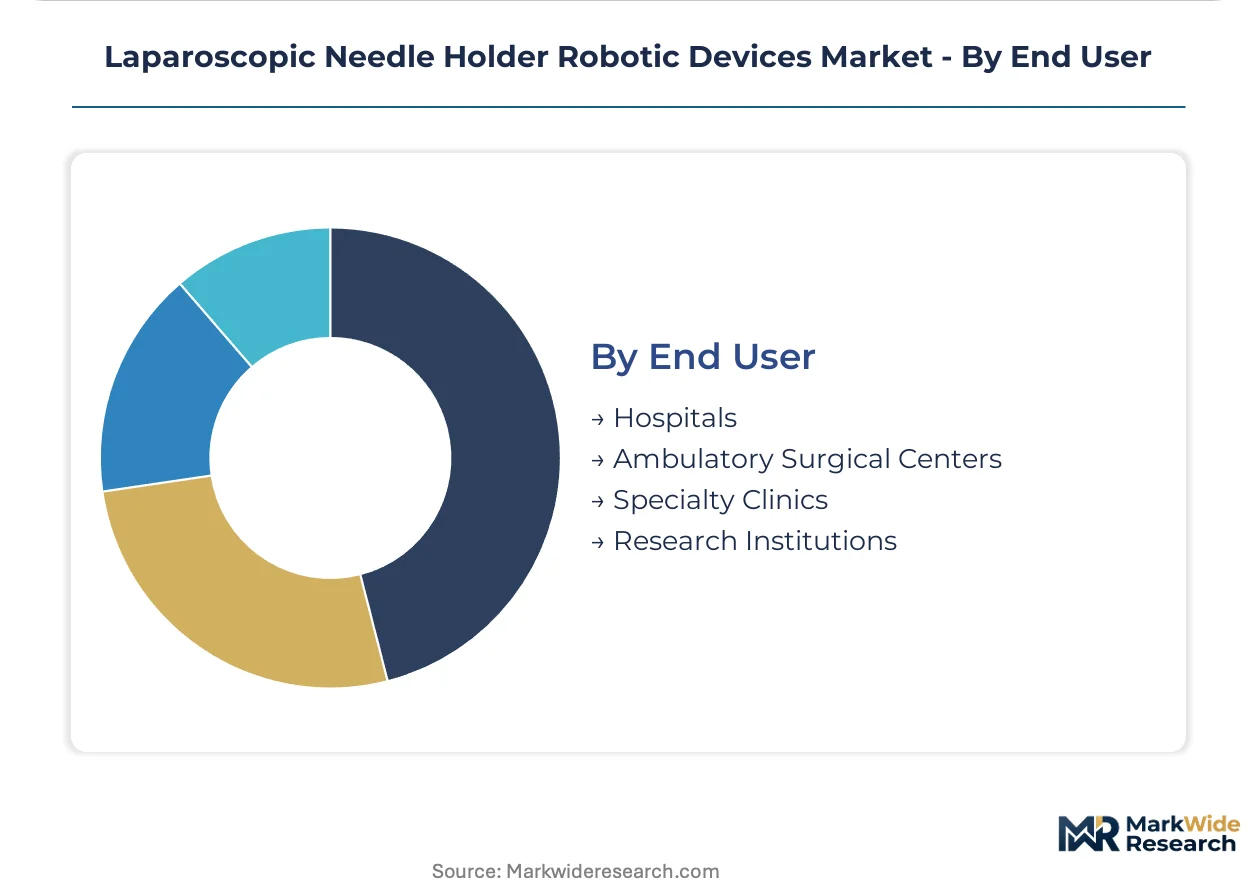
End User:
Budget authority and sterilization capacity differentiate procurement behavior, with ambulatory surgical centers prioritizing compact footprints and simplified reprocessing over advanced haptic features.
- Hospitals:Tertiary care systems with capital equipment budgets and dedicated sterile processing departments. United States health systems amortize platform costs across high-volume service lines including oncology and gynecology.
- Ambulatory Surgical Centers:Freestanding outpatient facilities with limited physical footprint and same-day discharge protocols. German ASCs in North Rhine-Westphalia are procuring compact robotic platforms with integrated needle holders, opening a channel previously reserved for inpatient budgets.
- Specialty Clinics:Focused surgical practices with narrower procedure mixes.
- Research Institutions:Academic centers prioritizing training and protocol development over throughput metrics.
Hospitals sit at the top of the volume ranking, with ambulatory surgical centers climbing the fastest as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting electromechanical assembly investment toward jurisdictions with streamlined medical device conformity pathways. Manufacturers now site production facilities where ISO 13485 certification overhead aligns with regional procurement scale.
United States
Integrated delivery networks in Texas and California are consolidating robotic platform purchasing through multi-hospital service contracts. FDA 510(k) clearance timelines for Class II surgical instruments compress vendor qualification windows. The Minneapolis-St. Paul corridor anchors electromechanical component fabrication serving Midwestern academic medical centers.
Germany
Bavarian university hospitals are accelerating needle holder procurement ahead of EU MDR conformity assessment deadlines for legacy platform recertification. The country's national pharmaceutical regulator maintains stringent biocompatibility testing protocols under MDR Annex I. The Tuttlingen surgical instrument cluster concentrates precision machining capacity for articulating wrist mechanisms.
Japan
Prefectural hospitals in Kanto and Kansai regions face extended PMDA reimbursement listing timelines for novel articulation mechanisms. METI industrial policy channels subsidies toward domestic robotic surgical platform development. The Nagoya medical device corridor houses electromechanical actuator assembly serving domestic OEMs.
India
Tertiary care networks in Maharashtra and Karnataka are expanding minimally invasive surgery departments through government health insurance expansion. CDSCO medical device rules harmonize with ISO 13485 for quality management certification. The PLI scheme for high-value surgical instruments attracts contract manufacturers to Gujarat pharmaceutical zones.
Switzerland
Cantonal hospital procurement associations negotiate instrument availability guarantees separately from platform warranties. Swissmedic maintains abbreviated review pathways for electromechanical devices with prior FDA or EMA authorization. The Basel biomedical cluster integrates precision engineering heritage with surgical robotics component supply.
Laparoscopic Needle Holder Robotic Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular compatibility with incumbent platform architectures. The vendor base stratifies across three tiers: integrated platform owners with captive instrument ecosystems, independent electromechanical specialists, and contract manufacturers serving regional OEMs. Dominant competitive moves include backward integration into precision actuator production and strategic partnerships with teaching hospitals for clinical validation protocols.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic occupy positions emphasizing integrated operating-room ecosystems. Intuitive Surgical exemplifies the platform-centric archetype through proprietary instrument architecture tied to installed-base expansion. Olympus Corporation and Karl Storz SE & Co. KG represent optical-surgical hybrid specialists with endoscopic heritage extending into robotic-assisted platforms.
| Leading Market Players |
|---|
| Stryker Corporation |
| Olympus Corporation |
| Intuitive Surgical |
| CMR Surgical |
| Smith & Nephew |
| Johnson & Johnson (Ethicon) |
| Karl Storz SE & Co. KG |
| Asensus Surgical |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Platform-captive instrument tiers split the market into proprietary ecosystems and modular alternatives, with each tier commanding distinct supply chain configurations and margin structures. United States hospital systems absorb premium pricing for da Vinci-compatible holders while German procurement associations negotiate availability guarantees that compress distributor markups across Bavaria and North Rhine-Westphalia networks.
Pricing Analysis
Distributor margins on electromechanical holders typically range 15-25 percent for integrated platform bundles versus 8-12 percent for standalone instrument sales to ambulatory surgical centers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, ISO 13485 certification grade, and after-sales service bundling. Pricing pressure stems from platinum-iridium electrode cost volatility and compressed procurement cycles ahead of EU MDR deadlines. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraint, while United States academic medical centers prioritize platform compatibility over unit cost.
Supply Chain Analysis
Refurbishment flows for electromechanical wrist mechanisms create secondary supply channels serving cost-constrained Japanese prefectural hospitals and Indian tertiary care networks. Precision actuator fabrication concentrates in Germany's Tuttlingen surgical instrument cluster, Japan's Nagoya medical device corridor, and Switzerland's Basel biomedical hub. Raw material dependencies include surgical-grade stainless steel, platinum-iridium electrodes, and biocompatible polymer coatings for articulating housings. Single-source vulnerability persists for seven-degree-of-freedom wrist mechanisms where electromagnetic compatibility certification ties third-party manufacturers to incumbent platform architectures. Distribution runs through regional surgical robotics service networks and GPO contracts with availability guarantee clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as laparoscopic procedural volumes migrate from open approaches across gynecological and general surgery service lines, locking in recurring instrument revenue through platform-installed-base expansion.
For Market Incumbents: Lock in sterile processing department capacity through proprietary reprocessing workflow certification, limiting hospital vendor switching flexibility. Deepen backward integration into precision actuator production to offset platinum-iridium cost volatility. Prioritize electromagnetic compatibility certification for third-party holder integration to defend against modular competitors. For New Entrants and Emerging Players: Enter via India's PLI scheme for high-value surgical instruments, establishing electromechanical assembly capacity serving Maharashtra and Karnataka tertiary care networks. Target ambulatory surgical centers in Germany's North Rhine-Westphalia region where compact platform procurement is displacing inpatient capital budgets. Pursue cloud-connected instrument validation pathways to shift revenue toward recurring SaaS models. For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics engineering talent scarcity intersects with ISO 13485 certification overhead and IEC 60601 electrical safety compliance requirements. Long-term viability favors platform-agnostic electromechanical specialists with validated articulation mechanisms and teaching hospital clinical validation partnerships. Monitor PMDA reimbursement listing timelines for novel wrist mechanisms as early indicator of Japanese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Class II surgical instrument clearance compresses vendor qualification windows for United States academic medical centers. |
| EU MDR Conformity Assessment | Annex I biocompatibility testing requirements accelerate procurement cycles ahead of legacy platform recertification deadlines. |
| Hospital System Partnership | Integrated delivery networks in Texas and California consolidate multi-hospital service contracts with availability guarantees. |
| Software Companion Development | Machine learning algorithms for suture placement kinematics standardize resident training curves at United States teaching hospitals. |
| Reimbursement Strategy | CMS valuation shifts toward minimally invasive hysterectomy approaches expand gynecological surgery addressable market. |
Research Methodology
Direct dialogue with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and sterile processing department supervisors grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EU MDR conformity assessment databases, CMS Medicare reimbursement schedules, and hospital procurement cooperative records. Bottom-up and top-down triangulation reconciled instrument shipment data with capital equipment budget disclosures across United States integrated delivery networks and German university hospital associations.
Bottom-up modeling segmented volume and value across product type, technology, application, and end user dimensions, with additional stratification by regional regulatory cluster and platform ecosystem compatibility. Top-down analysis anchored market sizing to tertiary care network capital expenditure patterns and laparoscopic procedural volume migration trends. CAGRs were derived from installed-base expansion trajectories and instrument utilization rates per operating room across the analysis window. Forecast inputs incorporated PMDA reimbursement benchmark timelines and EU MDR compliance deadline effects on procurement cycle compression.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time instrument utilization telemetry introduce uncertainty bands around per-procedure revenue estimates. Forecasts reflect assumptions regarding procedural volume migration rates and regulatory pathway stability. Practitioners should monitor PMDA novel mechanism approval velocity and platinum-iridium commodity price indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market
Surgical Instruments
Neovaginal Surgery Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Global Biopsy Needles Market
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Homecare Surgical Drains Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Laparotomy Sponges Market