
 Surgical Headband Market | 2026-2036
Surgical Headband Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Headband Market Analytics
Aftermarket service revenue for headband refurbishment and LED module replacement is rewriting margin allocation across the surgical illumination value chain. HEINE Optotechnik GmbH & Co. KG leverages its German manufacturing base to sustain premium positioning in optical assemblies. Integra LifeSciences Corporation anchors its portfolio through broad surgical instrument distribution networks. Aspen Surgical competes on disposable headband volumes while navigating hospital procurement consolidation.
A surgical headband is a wearable illumination device that positions a focused light source at the operator's line of sight, typically employing fiber-optic cables or LED arrays with adjustable intensity between 50,000 and 100,000 lux for tissue visualization during procedures. The device serves otolaryngologists, plastic surgeons, and dental specialists requiring hands-free, shadow-free operative lighting. LED Integrated headbands command expanding margin pools as facilities prioritize energy efficiency and reduced heat emission over halogen alternatives. Reusable metal-frame configurations retain dominance in developed hospital systems where capital equipment cycles span seven to ten years. Disposable plastic variants penetrate ambulatory settings where infection control protocols favor single-use instrumentation.
FDA 510(k) clearance pathways and EU MDR Class I designation govern market access for surgical headbands in the United States and Europe, with CE marking now requiring updated clinical evaluation under the Medical Device Regulation. Japan's PMDA enforces JIS standards for optical performance and biocompatibility of materials contacting skin during extended procedures. Stakeholders must monitor regulatory divergence between FDA's predicate device framework and MDR's stricter clinical evidence demands when configuring product development pipelines.
Market Dynamics
LED module standardization is compressing replacement cycles across surgical headband fleets, forcing manufacturers to reconfigure service revenue models around refurbishment rather than new unit sales.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter CE marking requirements under the Medical Device Regulation are filtering out marginal suppliers, concentrating procurement among certified vendors in German and French hospital systems.
- Ambulatory surgical center expansion:Freestanding ASCs in the United States are procuring disposable headband variants to align with same-day discharge protocols and reduced sterilization infrastructure.
- Fiber-optic to LED conversion:Heat reduction and energy efficiency gains from solid-state illumination are displacing halogen-tethered systems in otolaryngology suites.
Market Restraints
- Optical component supply concentration:Precision lens assemblies and LED driver chips concentrate among East Asian contract manufacturers, exposing procurement timelines to single-source fragility.
- EU MDR transition costs:Updated technical documentation and notified body fees for Class I reclassification are compressing margins for mid-tier European producers.
- Capital equipment replacement inertia:Seven-to-ten year depreciation cycles in developed hospital systems delay LED upgrade decisions despite operational superiority.
Strategic Opportunities
- Japan's aging surgical workforce:Ergonomic lightweight headband designs address musculoskeletal strain among veteran practitioners in Tokyo and Osaka metropolitan hospital networks.
- Remote surgical assistance integration:Head-mounted camera modules converging with 5G transmission enable real-time telementoring in rural United States trauma centers.
- India PLI scheme for medical devices:Production-linked incentives for domestic manufacturing create localized supply capacity for South Asian export markets.
Industry Challenges
- Biocompatibility certification timelines:Skin-contact material validation under ISO 10993 extends product launch schedules by twelve to eighteen months.
- Legacy fiber-optic inventory integration:Hybrid headband configurations must accommodate existing light source consoles without full infrastructure replacement.
- Optical engineer talent scarcity:Specialized illumination design expertise concentrates among German and Japanese technical institutes, constraining R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Headband Market |
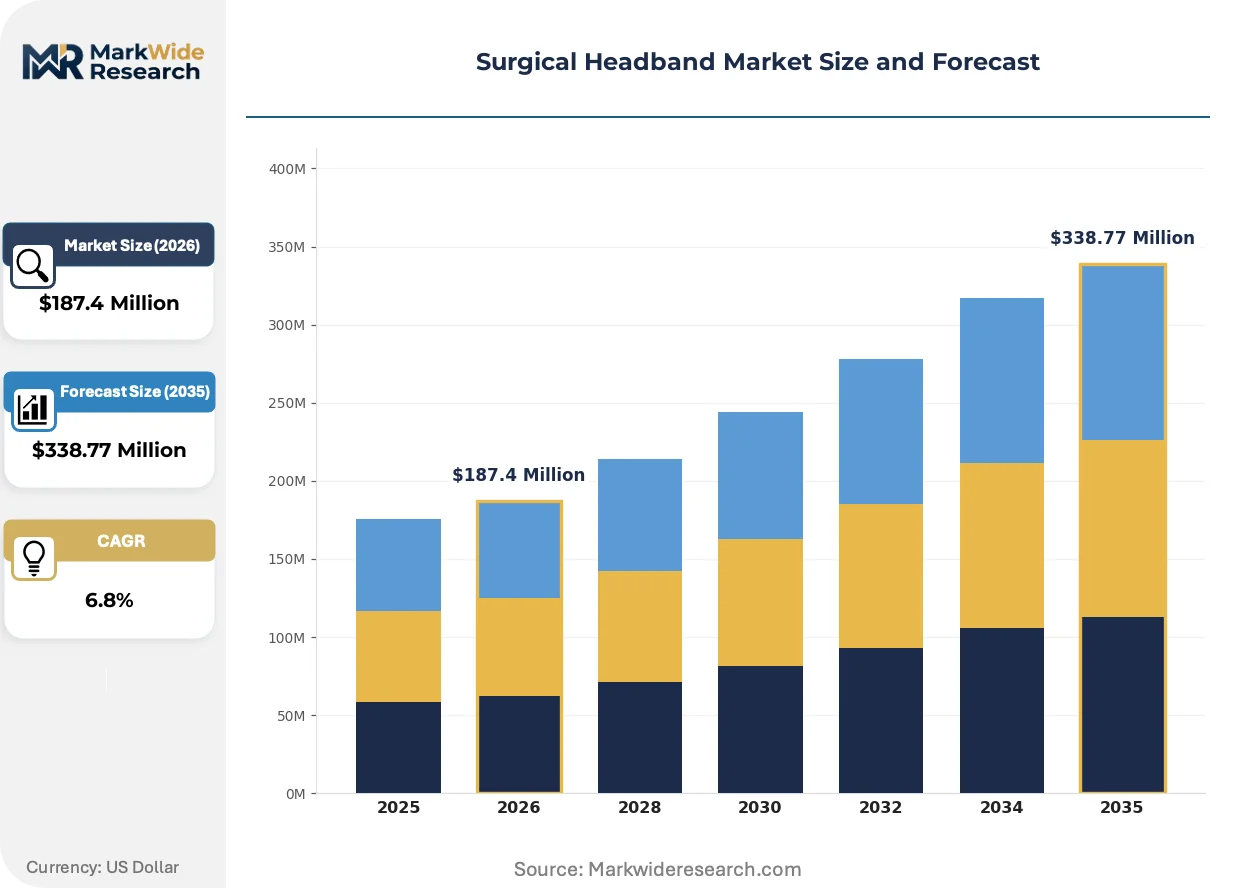
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Adjustable, LED Integrated End User: Hospitals, Surgical Centers, Dental Clinics, outpatient facilities Material: Plastic, Metal, Fabric, Silicone Feature: Lightweight, Ergonomic, Waterproof, Anti-fog |
| Companies Covered | HEINE Optotechnik GmbH & Co. KG, Integra LifeSciences Corporation, Aspen Surgical, Surgitel, Orascoptic, BFW Inc., General Scientific Corporation, Enova Illumination, SheerVision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Headband Market Evolving Landscape
Illumination control architectures are migrating from analog dimmers to software-defined interfaces, enabling procedure-specific lighting presets and usage telemetry capture.
Wireless battery-integrated LED headbands are digitizing operating room workflows by eliminating tethered light source consoles and fiber-optic cable management. Ambulatory surgery centers in the United States are adopting these untethered configurations for orthopedic and plastic surgery suites. The technology is digitizing capital allocation patterns as facilities redirect spending from centralized light source infrastructure toward distributed wearable units.
Japan's PMDA has tightened JIS T 0601-1 electromagnetic compatibility requirements for battery-powered surgical illumination, mandating updated shielding validation for RF-emitting devices. Domestic manufacturers in Nagoya and Osaka industrial clusters are absorbing compliance costs through modular platform redesigns. Dental surgery applications face the steepest recertification burden due to proximity to sensitive electronic dental equipment.
Hospital procurement departments are consolidating surgical illumination purchasing into multi-year capital equipment frameworks, bundling headbands with endoscopes and surgical microscopes. Independent distributors in the United States are losing access to IDN contracts as health systems centralize vendor management through GPO-affiliated procurement offices. Germany's university hospital networks exhibit the most advanced bundling sophistication, negotiating total cost-of-ownership metrics across seven-to-ten year service agreements.
Surgical Headband Market Segmentation
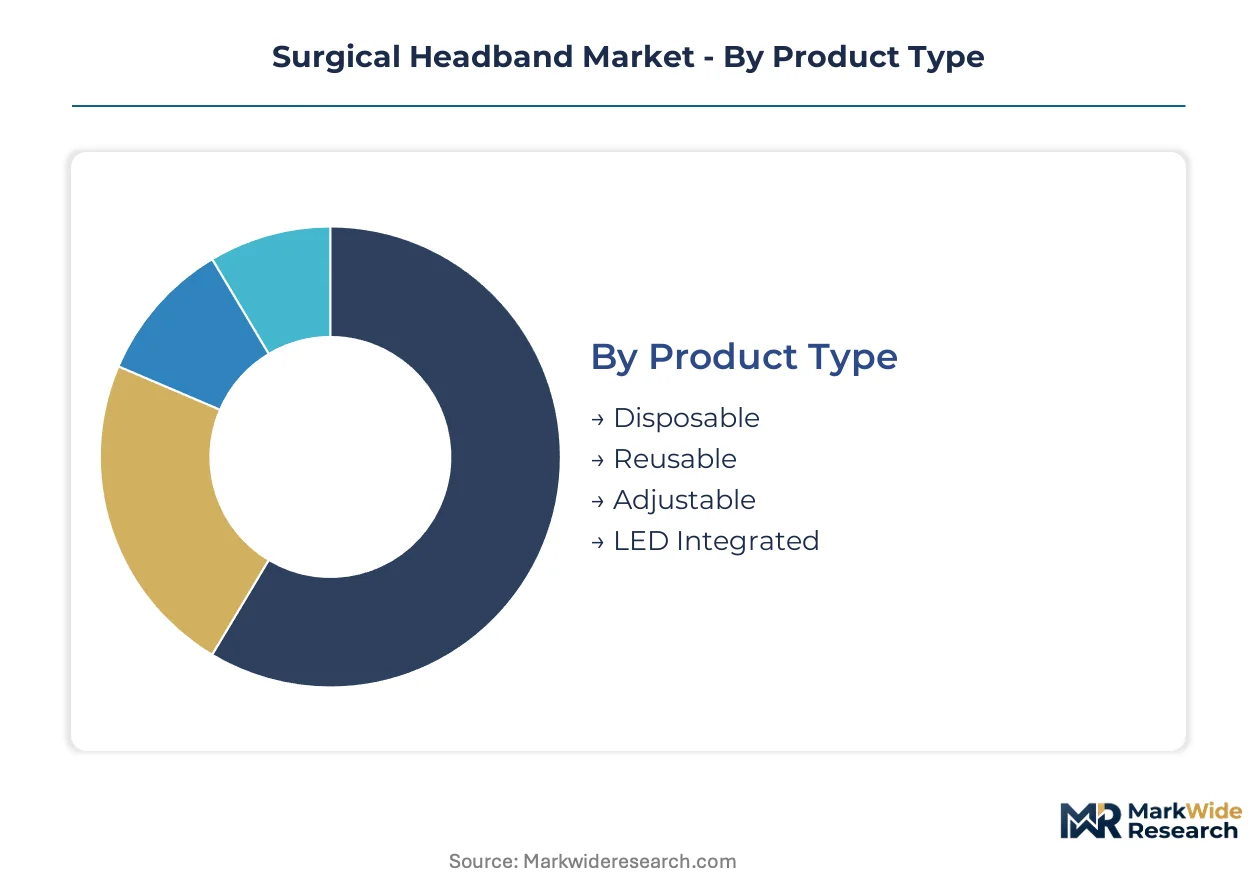
Segmentation in surgical headbands reveals how procurement priorities diverge between capital-intensive hospital systems and throughput-focused ambulatory operators. Material choices and illumination architectures determine compliance pathways, replacement economics, and service revenue potential across the installed base.
Product Type:
Cost tier differentiation separates capital equipment from consumable procurement models, with reimbursement structures and depreciation cycles driving portfolio positioning.
- Disposable:Single-use polymer headbands eliminate sterilization logistics and cross-contamination risk in high-turnover settings. Ambulatory surgical centers in the United States favor these configurations for same-day discharge protocols where instrument reprocessing infrastructure is limited.
- Reusable:Metal-frame constructions with modular LED arrays support seven-to-ten year capital cycles in German and Japanese university hospital networks. Stainless steel chassis designs accommodate repeated autoclave cycles while maintaining optical alignment precision.
- Adjustable:Ratcheting headband mechanisms adapt to operator cranial geometry across diverse surgical teams. These configurations concentrate in multi-specialty hospitals where shared equipment pools serve rotating staff.
- LED Integrated:Solid-state illumination modules with 50,000 to 100,000 lux output displace fiber-optic tethered systems through reduced heat emission and energy efficiency. Demand clusters in otolaryngology and plastic surgery suites where tissue proximity demands shadow-free visualization.
Reusable metal-frame configurations hold installed capacity. LED Integrated is rotating up the share rankings.
End User:
Customer type determines purchasing authority, with consolidated health systems exercising different vendor selection criteria than independent specialty practices.
- Hospitals:Integrated delivery networks negotiate multi-year capital frameworks bundling headbands with endoscopes and surgical microscopes. Procurement offices affiliated with group purchasing organizations in the United States are consolidating vendor panels to three to five approved suppliers.
- Surgical Centers:Freestanding ambulatory facilities prioritize disposable variants and wireless battery-integrated designs to align with reduced sterilization infrastructure and rapid room turnover. These operators represent the steepest expansion trajectory for untethered LED configurations.
- Dental Clinics:Oral surgery applications demand electromagnetic compatibility with sensitive electronic dental equipment under tightened PMDA JIS T 0601-1 requirements in Japan. Lightweight ergonomic designs address musculoskeletal strain during extended procedures.
- Outpatient Facilities:Minor procedure rooms in multi-specialty clinics require cost-optimized illumination for dermatology and wound care applications. Procurement concentrates in value-tier configurations with simplified intensity controls.
Hospitals dominate capital allocation volumes. Surgical Centers are climbing the fastest in unit shipment growth.
Material:
Supply concentration and biocompatibility certification timelines differentiate material selection across regulatory jurisdictions.
- Plastic:Injection-molded polymer chassis enable single-use economics and color-coded inventory management for infection control protocols. These materials dominate disposable segment production with twelve-to-eighteen month ISO 10993 validation cycles.
- Metal:Anodized aluminum and stainless steel constructions provide structural rigidity for precision optical alignment through repeated sterilization cycles. German manufacturing clusters specialize in these configurations for premium reusable segments.
- Fabric:Textile headband components with moisture-wicking properties improve operator comfort during prolonged procedures. Demand concentrates in ergonomic-focused designs for Japan's aging surgical workforce.
- Silicone:Skin-contact grade elastomers reduce pressure point irritation and accommodate biocompatibility requirements for extended wear. These materials penetrate premium adjustable configurations where operator comfort drives purchasing decisions.
Metal constructions anchor the reusable installed base. Silicone is gaining share fastest in ergonomic premium tiers.
Feature:
Performance tier differentiation separates commodity procurement from premium positioning through measurable functional attributes.
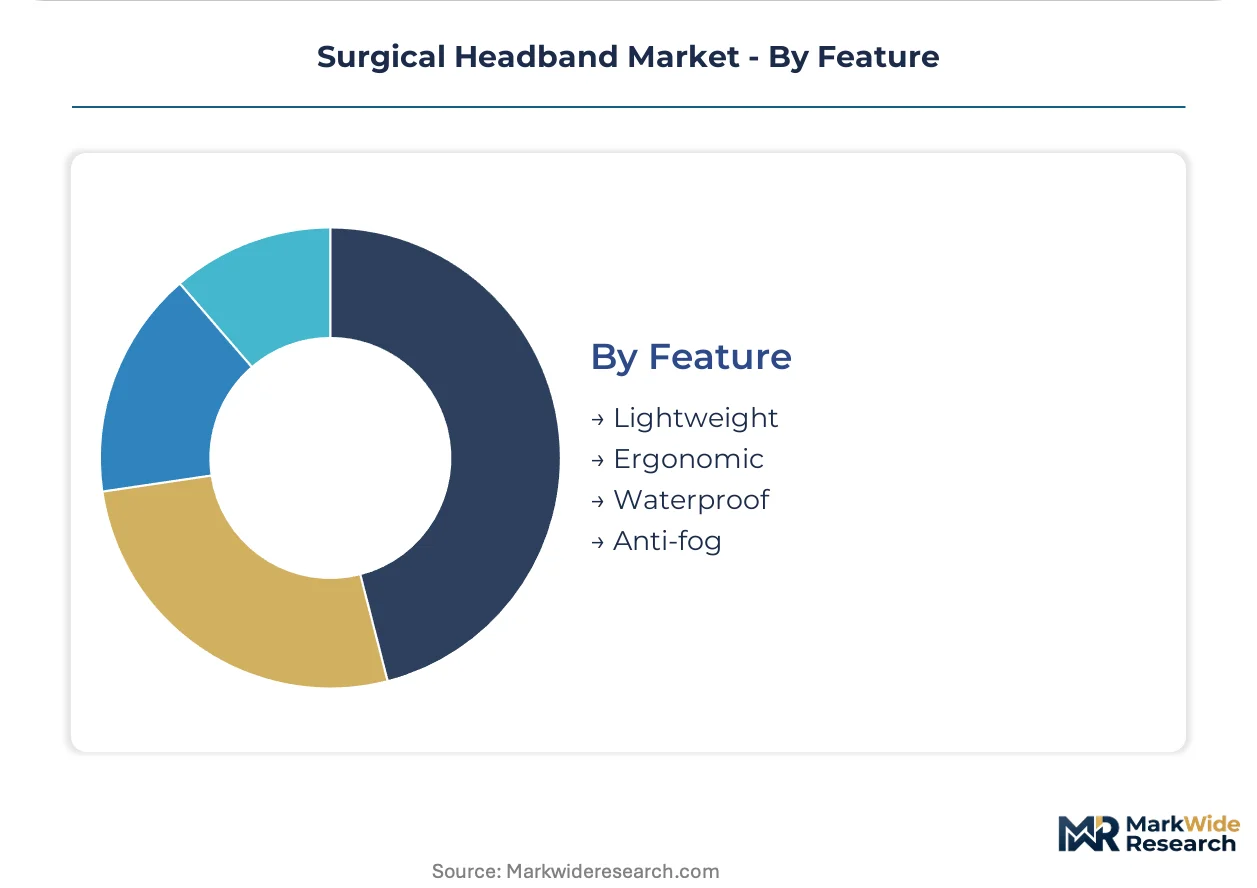
- Lightweight:Sub-200 gram total system mass reduces cervical strain during multi-hour procedures. Japanese metropolitan hospital networks prioritize these specifications for veteran practitioner retention.
- Ergonomic:Adjustable pivot mechanisms and balanced weight distribution accommodate diverse operator anthropometrics. These features command premium pricing in specialized surgical instrument clusters.
- Waterproof:Sealed optical enclosures withstand blood and irrigation fluid exposure without degradation. This specification is mandatory for orthopedic and trauma surgery applications.
- Anti-fog:Heated lens elements or hydrophilic coatings maintain visualization clarity through temperature differentials between operator and sterile field. These features concentrate in ENT and plastic surgery suites where precision tissue work demands uninterrupted sightlines.
Lightweight configurations hold mature market presence. Ergonomic designs are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in surgical headband procurement varies sharply across geographies. German university hospitals absorb premium LED-integrated configurations through extended depreciation cycles. Ambulatory operators in the United States prioritize disposable variants to minimize sterilization infrastructure investment.
United States
Integrated delivery networks consolidate procurement through group purchasing organization frameworks, reducing vendor panels to three to five approved suppliers. FDA 510(k) clearance pathways govern market access for LED-integrated and wireless battery-powered configurations. Greater Boston and Pacific Northwest medical device clusters concentrate telementoring technology development for head-mounted camera modules.
Germany
University hospital networks negotiate total cost-of-ownership metrics across seven-to-ten year service agreements bundling headbands with surgical microscopes. EU MDR Class I reclassification mandates updated clinical evaluation and notified body engagement for CE marking renewal. Baden-Württemberg manufacturing clusters specialize in precision optical assemblies for premium reusable metal-frame configurations.
Japan
Metropolitan hospital networks in Tokyo and Osaka prioritize ergonomic lightweight designs to address musculoskeletal strain among veteran practitioners. PMDA enforces JIS T 0601-1 electromagnetic compatibility requirements for battery-powered surgical illumination, mandating updated shielding validation. Nagoya industrial clusters absorb compliance costs through modular platform redesigns for dental surgery applications.
India
Ambulatory surgery centers in Maharashtra and Karnataka represent emerging demand for cost-optimized disposable headband configurations. Production-linked incentive schemes for domestic medical device manufacturing create localized supply capacity for South Asian export markets. Gujarat pharmaceutical and medical device clusters expand contract manufacturing capabilities for plastic chassis injection molding.
United Kingdom
National Health Service procurement frameworks emphasize value-tier configurations with simplified intensity controls for minor procedure rooms. MHRA operates recognition routes for EU MDR-certified devices during post-Brexit regulatory transition periods. London and Southeast England hospital networks pilot wireless battery-integrated headbands for orthopedic day surgery units.
Surgical Headband Market Competitive Landscape
Capability concentration sits with German and Japanese optical specialists; scale advantage sits with broad surgical instrument distributors. The market structures around three tiers: premium optical assembly manufacturers, diversified surgical device conglomerates, and disposable-focused volume suppliers. Strategic archetypes include precision engineering specialists leveraging manufacturing heritage, platform players bundling illumination with adjacent surgical equipment, and contract manufacturers serving private-label ambulatory demand. Competitive moves concentrate on multi-year service agreement negotiation and modular platform redesigns for regulatory recertification.
Among German precision engineering specialists, HEINE Optotechnik GmbH & Co. KG exemplifies capability concentration in optical assembly manufacturing. Integra LifeSciences Corporation occupies a position within the diversified surgical device tier, anchoring portfolio breadth through distribution network scale. Aspen Surgical represents the disposable-focused volume supplier archetype, serving ambulatory procurement consolidation with polymer chassis configurations. These three entities illustrate how geographic manufacturing heritage, platform diversification, and single-use economics segment competitive positioning across the surgical illumination value chain.
| Leading Market Players |
|---|
| HEINE Optotechnik GmbH & Co. KG |
| Integra LifeSciences Corporation |
| Aspen Surgical |
| Surgitel |
| Orascoptic |
| BFW Inc. |
| General Scientific Corporation |
| Enova Illumination |
| SheerVision |
| Others |
Value Network & Pricing Analysis
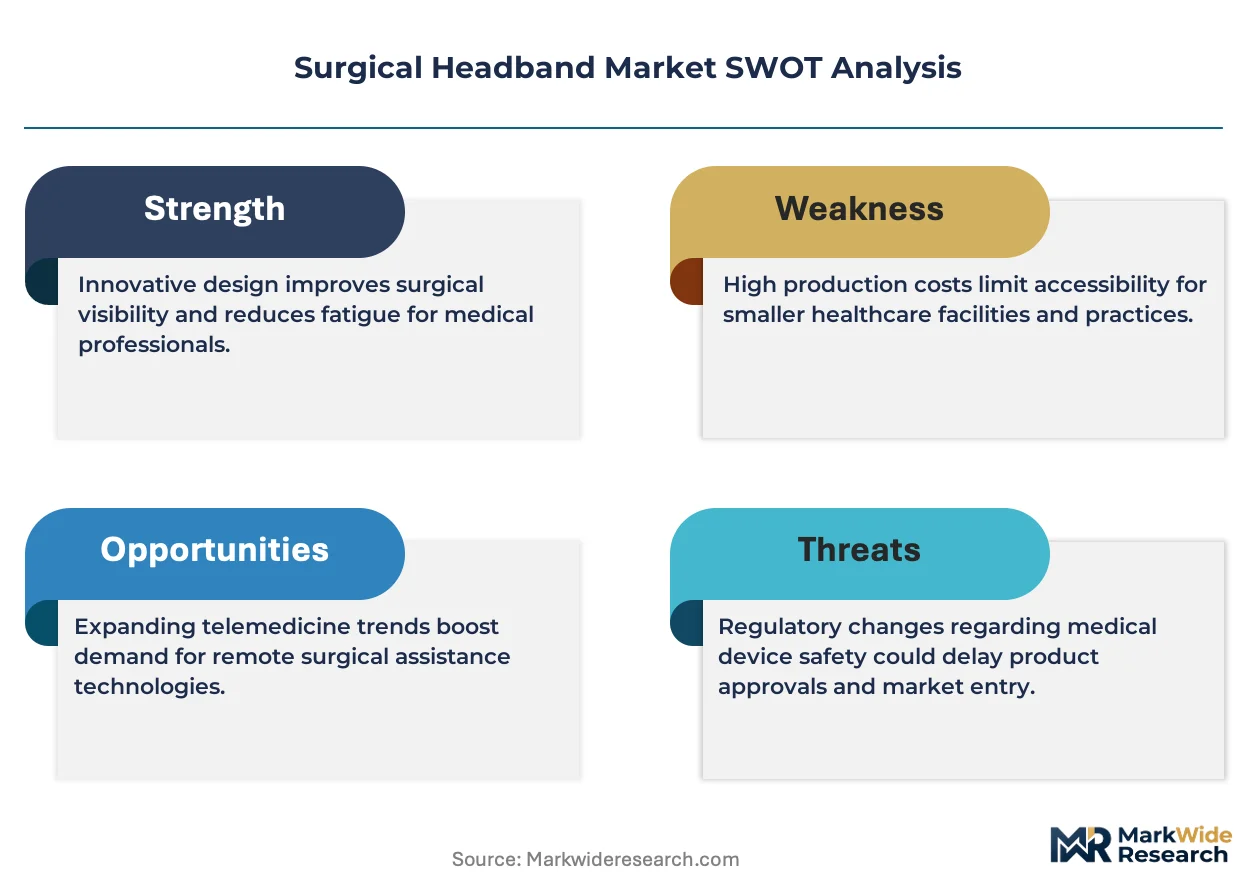
Overcapacity in East Asian LED driver chip fabrication is compressing component costs while simultaneously eroding supplier pricing power across German and Japanese headband assembly operations. This utilization dynamic forces mid-tier manufacturers to absorb margin compression or exit premium positioning entirely.
Pricing Analysis
Long-term offtake agreements dominate procurement between German university hospitals and precision optical suppliers, locking in seven-to-ten year service bundles that insulate premium vendors from spot-market volatility. Price differentiation rests on FDA 510(k) certification tier and optical assembly precision grade, with CE-marked MDR-compliant configurations commanding measurable premiums over legacy Class I devices. Cost compression in disposable polymer segments is intensifying because ambulatory surgical centers in the United States are consolidating purchasing through group purchasing organizations. Surgical centers exhibit highest price sensitivity due to reimbursement constraints, while Japanese metropolitan hospital networks show lowest sensitivity given ergonomic specifications for veteran practitioner retention.
Supply Chain Analysis
Extended payment terms from German university hospital procurement offices are stretching working capital cycles for precision optical assemblers, forcing supply-chain finance facility adoption among Baden-Württemberg manufacturing clusters. Component sourcing draws from China for LED driver chips, Taiwan for precision lens assemblies, and Japan for optical-grade polymers. Raw material dependencies center on rare-earth phosphors for LED color rendering, medical-grade silicone for skin-contact components, and anodized aluminum alloys for sterilization-durable chassis. Single-source vulnerability concentrates in East Asian contract manufacturing for LED modules. Distribution runs through group purchasing organization-affiliated procurement offices in the United States, direct hospital system contracts in Germany, and specialized surgical instrument distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized illumination design expertise concentrates among technical institutes in Germany and Japan, creating a bottleneck that constrains R&D scaling and rewards firms with captive optical engineering capabilities.
For Market Incumbents: Insulate premium positioning by deepening backward integration into precision lens assembly manufacturing and securing exclusive supply agreements with Nagoya-area optical polymer suppliers. LED module standardization threatens replacement-cycle revenue; counter this by bundling refurbishment services into multi-year hospital system contracts. Certification investment in EU MDR clinical evidence documentation serves as a defensive moat against mid-tier European competitors facing margin compression from notified body fees. For New Entrants and Emerging Players: Pursue white-space opportunity in India's production-linked incentive scheme for domestic medical device manufacturing, where localized plastic chassis injection molding capacity is expanding in Gujarat clusters. Disposable headband configurations for Maharashtra and Karnataka ambulatory surgery centers represent the most penetrable segment given limited sterilization infrastructure and same-day discharge protocols. Go-to-market angle should emphasize cost-optimized value-tier positioning with simplified intensity controls for outpatient facility procurement. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because optical engineer talent scarcity and regulatory recertification burdens favor scaled platforms with modular redesign capabilities. Acquisition target archetype: mid-tier reusable metal-frame manufacturers in Baden-Württemberg with established CE marking pathways but limited LED integration expertise. Signal to watch: PMDA enforcement actions on JIS T 0601-1 electromagnetic compliance that accelerate battery-powered headband recertification timelines and strain smaller Japanese domestic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Updated technical documentation filters marginal suppliers from German hospital procurement panels. |
| Modular Platform Redesign | Platform flexibility absorbs PMDA electromagnetic compliance costs for Nagoya dental surgery manufacturers. |
| Hospital System Partnership | Multi-year service agreements with United States integrated delivery networks consolidate vendor panels to three-to-five approved suppliers. |
| Backward Integration into Optical Assembly | In-house precision lens manufacturing insulates German incumbents from East Asian contract manufacturer single-source fragility. |
| Software Companion Development | Procedure-specific lighting presets and usage telemetry capture differentiate LED-integrated configurations from commodity alternatives. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body technical documentation, and Japanese PMDA JIS standard filings preceded structured interviews with hospital procurement managers, biomedical engineers, ambulatory surgery center operations directors, and group purchasing organization contracts specialists. Secondary validation drew from surgical instrument trade association reports, hospital capital equipment expenditure surveys, and optical component import-export customs records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, end user, material, and feature segmentation dimensions.
Assumptions held fixed across the modeling period include regulatory pathway timelines for FDA predicate device frameworks and EU MDR Class I reclassification, while LED module cost curves and ambulatory surgery center expansion rates were varied under sensitivity scenarios. Segmentation modeling incorporated product type tiering, end-user purchasing authority structures, material biocompatibility certification cycles, and feature performance differentiation. CAGRs were derived from fitted growth curves anchored to disclosed capital equipment replacement cycles and procurement consolidation patterns. Industry-specific forecast inputs included German university hospital depreciation schedules and United States same-day discharge protocol adoption rates.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure budgets, medical device reimbursement rates, or trade policy affecting East Asian optical component flows would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and LED technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Global Gauze Swabs Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Surgical Rasps Market