
 Ophthalmic Handheld Surgical Instruments Market | 2026-2036
Ophthalmic Handheld Surgical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Handheld Surgical Instruments Market Intelligence
Aftermarket service revenue is narrowing as original equipment manufacturers tighten control over calibration and refurbishment protocols. Alcon Inc. leverages its direct service infrastructure to capture recurring instrument maintenance contracts. Haag-Streit Group anchors its position through precision manufacturing of diagnostic-linked surgical tools. BVI Medical competes by specializing in single-use instrument alternatives that bypass refurbishment economics entirely.
Ophthalmic handheld surgical instruments comprise manually operated precision tools—typically manufactured from titanium or medical-grade stainless steel with tolerances below 50 microns—designed for incision, manipulation, and tissue removal during microsurgical procedures of the eye. Scissors and forceps dominate current procurement volumes due to their universal deployment across anterior segment procedures, while retina surgery applications command premium pricing through specialized tip geometries and diamond-dusted surfaces. The titanium material segment sustains above-average margins because of its non-magnetic properties and biocompatibility profile in high-frequency surgical environments.
The FDA governs premarket notification pathways for these devices under 21 CFR 886, while ISO 13485 certification shapes supplier qualification criteria for hospital procurement committees. The EU Medical Device Regulation mandates unique device identification and enhanced clinical evidence for reusable surgical instruments entering European markets. Stakeholders must monitor how notified body capacity constraints and evolving sterilization validation requirements reshape competitive access across major ophthalmic device markets.
Market Dynamics
The FDA's updated 510(k) requirements for reusable surgical instruments are compressing product development timelines and forcing manufacturers to absorb validation costs that previously fell on hospital sterilization departments. This regulatory recalibration is redistributing economic risk across the ophthalmic instrument supply chain.
Growth Catalysts
- Outpatient Procedure Migration:Ambulatory surgical centers in Germany and the United States are expanding instrument procurement as cataract and glaucoma surgeries shift away from inpatient settings. These facilities prioritize instrument durability and rapid turnaround.
- EU MDR Implementation:The EU Medical Device Regulation's enhanced clinical evidence requirements for reusable surgical instruments are creating competitive moats for manufacturers with established notified body relationships. Early certifiers capture procurement committee preference.
- Titanium Material Superiority:Non-magnetic titanium alloys sustain premium positioning in high-frequency surgical environments where MRI compatibility and biocompatibility are non-negotiable. Material science advances are expanding viable titanium applications.
Market Restraints
- Notified Body Bottlenecks:EU MDR capacity constraints are extending certification timelines for reusable instrument lines, freezing new product introductions and straining working capital for mid-tier manufacturers.
- Single-Use Substitution:Specialized single-use instrument alternatives are bypassing refurbishment economics entirely in cost-sensitive procurement segments, compressing addressable market for reusable titanium portfolios.
- Precision Manufacturing Concentration:Sub-50-micron tolerance grinding capabilities concentrate in Swiss and German supplier clusters, creating geographic supply risk and limiting price competition at the premium tier.
Strategic Opportunities
- Direct Service Infrastructure:Original equipment manufacturers capturing recurring instrument maintenance contracts through proprietary calibration and refurbishment protocols are building annuity revenue streams that resist price commoditization.
- Diagnostic-Surgical Convergence:Precision manufacturing of diagnostic-linked surgical tools creates bundled procurement opportunities as eye hospitals consolidate vendor relationships. Haag-Streit Group anchors this integration strategy.
- Unique Device Identification Mandates:EU MDR and FDA UDI requirements for instrument traceability are opening software and data services adjacencies for manufacturers with digital infrastructure investments.
Industry Challenges
- ISO 13485 Talent Scarcity:Quality management system expertise for medical device manufacturing concentrates in established European and North American hubs, constraining geographic expansion for emerging suppliers.
- Sterilization Validation Complexity:Validated reprocessing protocol development for complex tip geometries requires specialized microbiology and materials science capabilities that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Handheld Surgical Instruments Market |
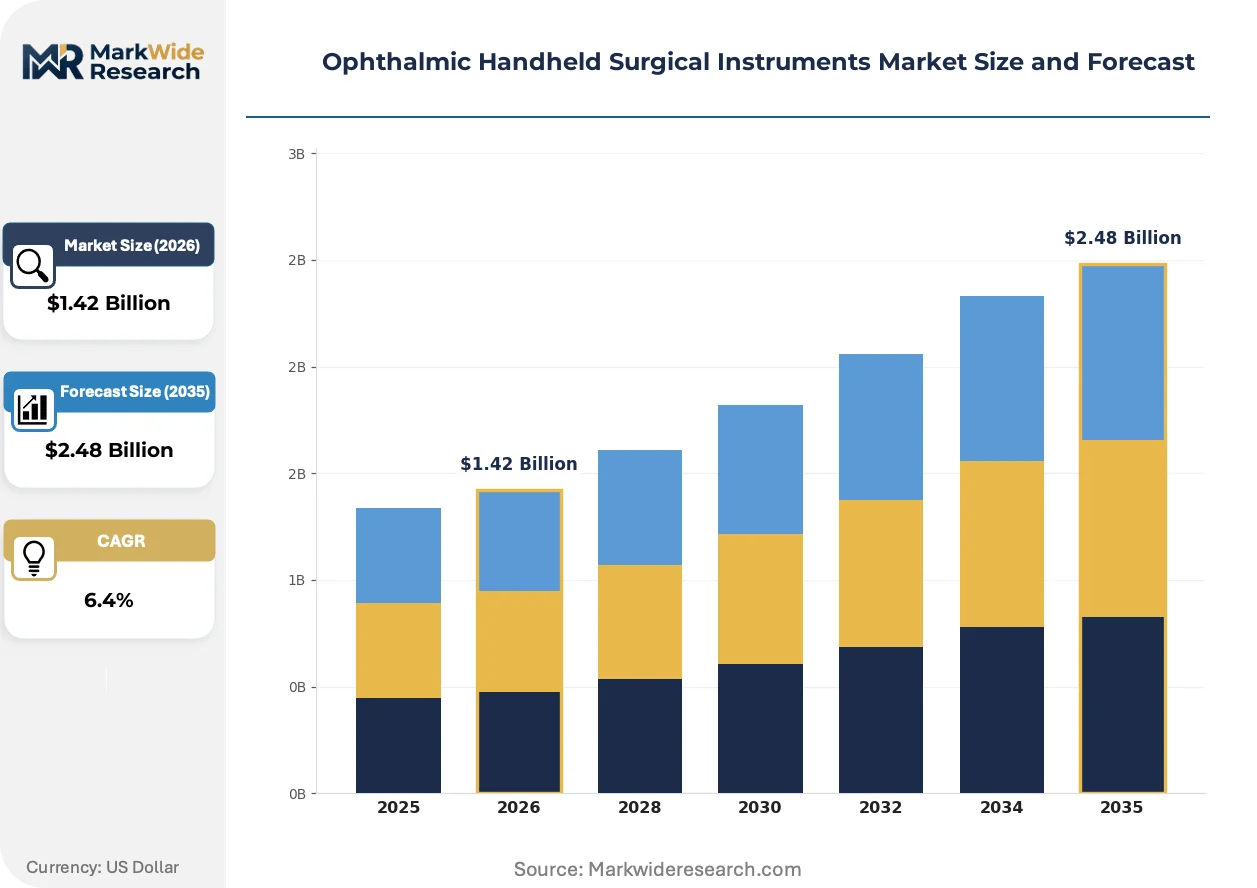
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissors, Forceps, Knives, Specula Material: Stainless Steel, Plastic, Titanium, Alloy End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Application: Cataract Surgery, Retina Surgery, Glaucoma Surgery, Corneal Surgery |
| Companies Covered | Carl Zeiss Meditec AG, Haag-Streit Group, BVI Medical, Katalyst Surgical, Appasamy Associates, Accutome Inc., Alcon Inc., ASICO LLC, Katena Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Handheld Surgical Instruments Market Strategic Shifts & Innovations
Digital traceability and precision manufacturing advances are converging to reshape how ophthalmic instruments are specified, procured, and maintained across surgical workflows.
Smart instrument embedding is digitizing surgical workflow documentation through RFID and sensor integration in forceps and scissors handles. Academic medical centers in Germany and the United States are piloting these connected tools for usage tracking and predictive maintenance scheduling. The technology is digitizing compliance evidence collection for hospital accreditation while compressing manual documentation labor.
EU MDR's enhanced clinical evidence requirements are mandating post-market surveillance systems that capture real-world performance data across reusable instrument lifecycles. Manufacturers must now maintain clinical follow-up infrastructure that was previously discretionary. Retina surgery applications with specialized diamond-dusted surfaces face the steepest evidence requirements due to their extended use patterns and higher consequence of failure.
Hospital procurement committees are consolidating vendor panels around suppliers offering integrated instrument-maintenance-service bundles. Single-source contracting is displacing fragmented multi-vendor purchasing in German specialized eye hospitals and US academic centers. This concentration is most visible in anterior segment procedure categories where scissors and forceps dominate procurement volumes and standardization yields inventory efficiency gains.
Ophthalmic Handheld Surgical Instruments Market Segmentation
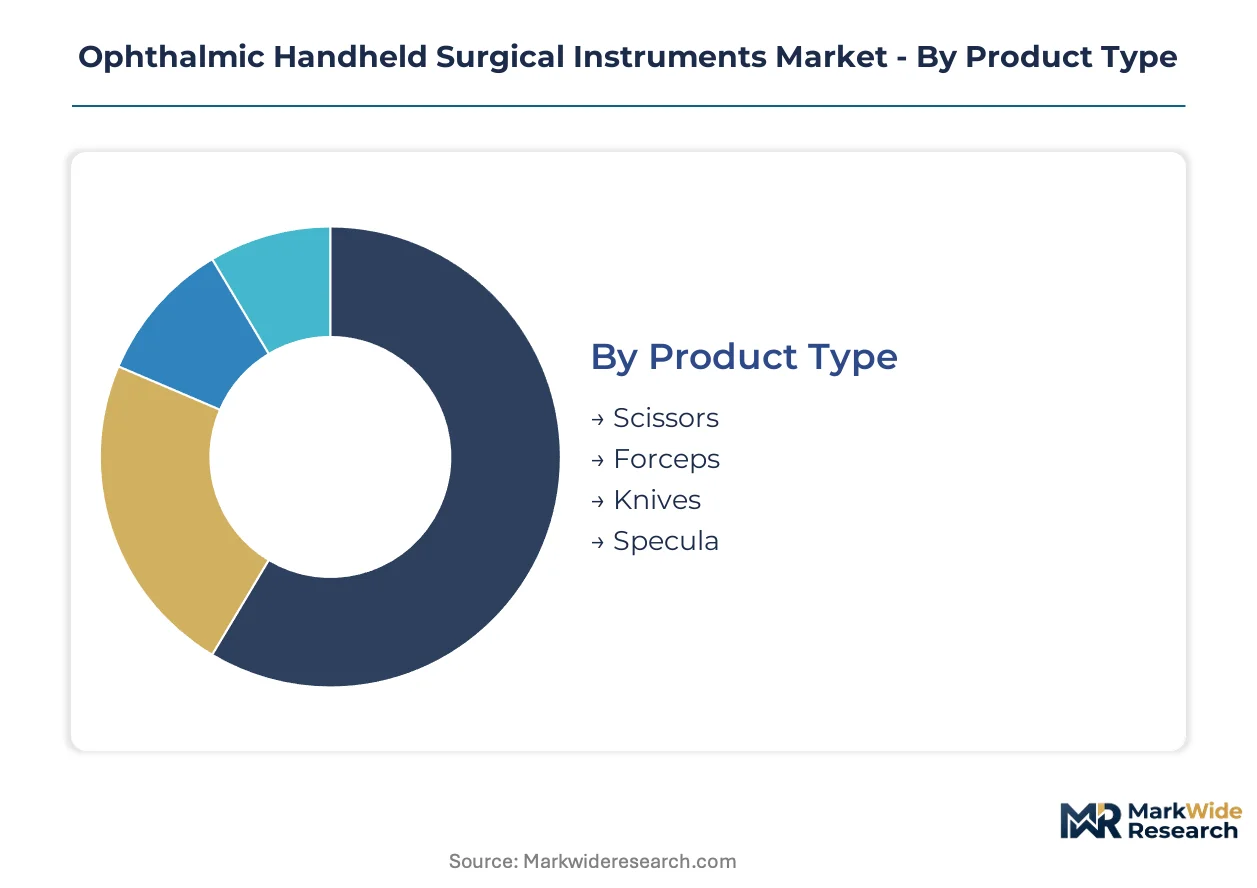
Segmentation in ophthalmic handheld surgical instruments reveals how procurement committees balance durability requirements against reprocessing economics across procedure types. Material science and end-use setting create divergent performance specifications that manufacturers must reconcile within constrained development timelines.
Product Type:
Mature categories dominate procurement volumes while emerging tip geometries reshape premium tier competition.
- Scissors:Micro-serrated titanium blades with sub-50-micron edge tolerances enable precise capsulorhexis execution in cataract workflows. German specialized eye hospitals drive replacement cycles for premium-grade variants with diamond-dusted cutting surfaces.
- Forceps:Non-magnetic titanium alloys with platform-specific jaw geometries dominate anterior segment instrument procurement. Ambulatory surgical centers in the United States prioritize rapid-turnover forceps with validated sterilization protocols.
- Knives:Diamond and sapphire blade configurations serve specialized incision requirements in corneal and refractive procedures.
- Specula:Wire and solid-blade designs provide eyelid retraction across anterior segment workflows with varying patient comfort specifications.
Scissors handle the majority of throughput; Forceps is the fastest mover on share.
Material:
Cost tier stratification separates premium biocompatible alloys from commodity stainless alternatives in procurement specifications.
- Titanium:Non-magnetic Grade 5 titanium alloys sustain premium positioning through MRI compatibility and corrosion resistance in high-frequency surgical environments. FDA-validated reprocessing protocols for complex titanium tip geometries are compressing supplier margins.
- Stainless Steel:Medical-grade 300-series stainless dominates volume procurement in cost-sensitive clinic settings where instrument longevity exceeds magnetic compatibility concerns.
- Plastic:Single-use polymer instruments bypass refurbishment economics entirely in specific anterior segment applications.
- Alloy:Cobalt-chrome and specialized metal blends serve niche applications requiring hardness beyond pure titanium capabilities.
Titanium commands margin concentration; Plastic alternatives are expanding most quickly in single-use substitution segments.
End User:
Customer type determines service bundling requirements and instrument standardization scope in procurement negotiations.
- Hospitals:Academic medical centers in Germany and the United States consolidate vendor panels around integrated instrument-maintenance-service bundles with predictive maintenance scheduling.
- Ambulatory Surgical Centers:Outpatient facilities prioritize rapid instrument turnaround and durability validation over premium feature sets.
- Clinics:Private ophthalmology practices concentrate procurement in standard scissors and forceps categories with extended replacement cycles.
- Research Institutions:Specialized tip geometries for experimental procedures drive small-batch manufacturing relationships with Swiss precision suppliers.
Hospitals anchor procurement value; Ambulatory Surgical Centers are gaining share fastest as procedure migration accelerates.
Application:
Procedure complexity dictates tolerance specifications and evidence requirements across the surgical instrument portfolio.
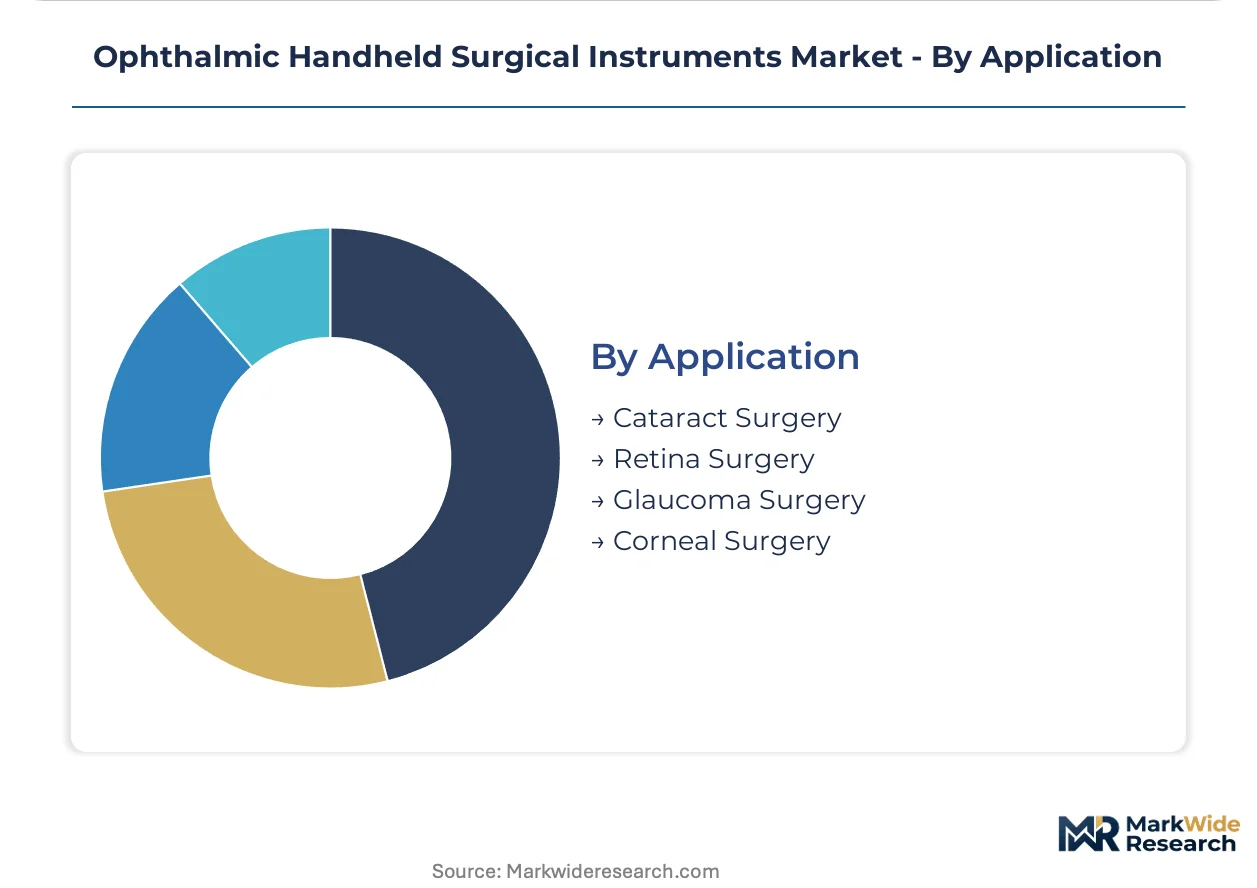
- Cataract Surgery:Capsulorhexis forceps and corneal scissors constitute the highest-volume instrument category with standardized procurement specifications across facility types.
- Retina Surgery:Diamond-dusted micro-forceps and specialized scissors command premium pricing through sub-25-micron tolerances required for vitreoretinal manipulation.
- Glaucoma Surgery:Trabeculectomy and MIGS procedures utilize specialized instrument sets with distinct sterilization validation requirements.
- Corneal Surgery:Lamellar dissection instruments and trephine systems serve transplant and refractive workflows with procedure-specific geometric constraints.
Cataract Surgery handles the majority of throughput; Retina Surgery shows the steepest expansion trajectory on premium instrument demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the lowest price elasticity, absorbing premiums for sub-50-micron tolerance instruments, while procurement committees in India and Brazil prioritize cost-efficient stainless steel alternatives over titanium portfolios.
United States
Ambulatory surgical centers in Texas and Florida are accelerating instrument procurement as cataract procedures migrate outpatient. FDA's updated 510(k) requirements for reusable surgical instruments are compressing product development timelines for domestic manufacturers. The Boston-Cambridge corridor concentrates precision grinding capabilities serving academic medical centers with predictive maintenance contracts.
Germany
Specialized eye hospitals in Bavaria and Baden-Württemberg drive premium replacement cycles for diamond-dusted micro-forceps. EU Medical Device Regulation mandates unique device identification and enhanced clinical evidence for reusable instruments entering European markets. The Tuttlingen surgical instrument cluster anchors sub-25-micron tolerance manufacturing for retina surgery applications.
Switzerland
Research institutions in Basel and Zurich procure specialized tip geometries for experimental vitreoretinal procedures. Swissmedic maintains stringent certification requirements that reinforce competitive moats for established precision manufacturers. The Jura Arc watchmaking region has repurposed micro-mechanical expertise into medical device grinding capabilities.
India
Private ophthalmology clinics in Maharashtra and Tamil Nadu concentrate procurement in standard scissors and forceps categories with extended replacement cycles. CDSCO regulations for medical device manufacturing are tightening quality management system requirements for domestic suppliers. The Pune-Ahmednagar corridor hosts emerging instrument fabricators serving cost-sensitive South Asian markets.
Japan
Academic medical centers in Tokyo and Osaka consolidate vendor panels around integrated instrument-maintenance-service bundles. PMDA's post-market surveillance requirements align with EU MDR's enhanced clinical evidence standards for reusable devices. The Nagoya precision manufacturing belt supplies specialized alloys for anterior segment procedure instruments.
Ophthalmic Handheld Surgical Instruments Market Key Industry Players
Capability concentration sits with Swiss and German precision manufacturers commanding sub-50-micron grinding tolerances; scale advantage sits with diversified ophthalmic device conglomerates capturing recurring service revenue. The market structures around three tiers: integrated diagnostic-surgical platforms, specialized single-use instrument specialists, and precision forging subcontractors. Dominant competitive moves include direct service infrastructure investments and diagnostic-surgical convergence bundling.
Among Germany-based precision manufacturers, Carl Zeiss Meditec AG exemplifies the integrated diagnostic-surgical platform archetype. Haag-Streit Group occupies a position within the diagnostic-linked surgical tool segment. Alcon Inc. represents the diversified ophthalmic device conglomerate tier with direct service infrastructure capabilities.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Haag-Streit Group |
| BVI Medical |
| Katalyst Surgical |
| Appasamy Associates |
| Accutome Inc. |
| Alcon Inc. |
| ASICO LLC |
| Katena Products Inc. |
| Others |
Cost & Logistics Intelligence
The Rhine-Alpine freight corridor's container cost dynamics amplify pricing power for Swiss and German precision manufacturers while compressing margins for mid-tier suppliers dependent on Asian titanium sourcing. Downstream price differentiation stratifies across instrument tiers as procurement committees weigh validated reprocessing protocols against single-use alternatives.
Pricing Analysis
Recurring calibration and refurbishment contracts drive lifetime value capture for original equipment manufacturers with direct service infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates diamond-dusted titanium micro-forceps from medical-grade stainless alternatives and polymer single-use instruments. Cost compression in the stainless steel tier intensifies as Indian fabricators expand export capacity. Ambulatory surgical centers in the United States exhibit highest price sensitivity, while Bavarian specialized eye hospitals absorb premiums for sub-25-micron tolerance instruments.
Supply Chain Analysis
Export-control restrictions on precision grinding equipment limit technology transfer to emerging manufacturing hubs, entrenching Swiss and German supplier dominance. Sub-50-micron tolerance manufacturing draws from the Tuttlingen cluster in Germany, the Jura Arc region in Switzerland, and select Nagoya-area facilities in Japan. Raw material supply rests on Grade 5 titanium sponge from Ukrainian and Russian sources, medical-grade 300-series stainless from Chinese and Indian mills, and synthetic diamond grit for specialized tip coatings. Single-source vulnerability concentrates in Swiss precision grinding equipment. Distribution runs through hospital procurement committees and group purchasing organizations with consolidated vendor panel authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery driven by deferred instrument replacement cycles following EU MDR certification bottlenecks. Procurement normalization will favor suppliers with validated reprocessing infrastructure.
For Market Incumbents: Harden proprietary calibration protocols against independent service competitors by embedding RFID traceability and predictive maintenance algorithms. Capture recurring revenue through exclusive refurbishment contracts that lock out third-party servicers. Expand direct service infrastructure into ambulatory surgical centers before single-use alternatives capture outpatient volume. For New Entrants and Emerging Players: Pursue white-space opportunities in plastic single-use instrument alternatives for cost-sensitive anterior segment procedures in India and Brazil. Target the fastest-growing ambulatory surgical center segment with rapid-turnover forceps bundles that bypass complex sterilization validation. Establish manufacturing partnerships with Pune-area fabricators to serve South Asian private clinic demand. For Investors and Strategic Acquirers: Precision forging subcontractors with ISO 13485 certification and established notified body relationships represent the most defensible acquisition targets. Long-term viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Watch EU notified body capacity expansion as the signal for accelerated new product introduction timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Early EU MDR certification captures procurement committee preference in German eye hospitals. |
| Hospital System Partnership | Integrated instrument-maintenance-service bundles displace fragmented multi-vendor purchasing. |
| Software Companion Development | RFID-enabled traceability systems satisfy FDA UDI mandates while creating data services revenue. |
| Reimbursement Strategy | Outpatient procedure codes in US ambulatory settings accelerate instrument procurement cycles. |
| Backward Integration | In-house titanium forging secures supply continuity against Grade 5 sponge market volatility. |
Research Approach
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, ambulatory surgical center administrators, and ophthalmic surgeons and refined through secondary validation against FDA 510(k) filings, EU MDR notified body registers, hospital procurement databases, and GPO contract disclosures. Bottom-up instrument shipment estimates were triangulated against top-down procedure volume projections.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by scissors, forceps, and specialized tip geometries; material tiers spanning titanium, stainless steel, and polymer alternatives; end-user categories including hospitals, ambulatory surgical centers, and private clinics; and application-specific requirements for cataract, retina, glaucoma, and corneal procedures. CAGRs were derived from instrument replacement cycle analysis and procedure migration trends. Forecast inputs included EU notified body capacity constraints and FDA reprocessing validation timelines.
Sensitivities concentrate around EU MDR certification bottlenecks, single-use substitution rates in cost-sensitive markets, and titanium sponge supply disruptions. Forecasts reflect documented assumptions regarding outpatient procedure migration and regulatory harmonization timelines. Material shifts in reimbursement policy toward ambulatory settings or breakthrough single-use materials would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Broaches Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Laparoscopic Power Morcellators Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
GCC Minimally Invasive Surgery Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Cryosurgery Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Global Surgical Stapler Market