
 Global Myomectomy Market | 2026-2036
Global Myomectomy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Myomectomy Market Foresight
Multi-source procurement of electrosurgical devices and morcellators is restructuring supply relationships between specialized hospitals and device manufacturers. Johnson & Johnson leverages its broad surgical portfolio to sustain integrated service contracts across health systems. Hologic Inc. specializes in diagnostic-to-surgical workflows that anchor its position in women's health clinics. Medtronic PLC competes through energy-based device platforms that extend into robotic-assisted procedure suites.
A myomectomy is a surgical procedure for removing uterine fibroids while preserving the uterus, typically performed through abdominal incisions, laparoscopic ports, or hysteroscopic channels with tissue morcellation and electrosurgical sealing as core technical elements. The procedure serves fertility preservation and symptom relief in reproductive-age patients. Laparoscopic myomectomy holds mature volume leadership in procedure counts across developed health systems. Robotic-assisted myomectomy captures premium positioning as capital investment in da Vinci systems expands. Digital imaging systems within the technology segment represent the fastest-growing margin pool as intraoperative navigation demands intensify.
FDA 510(k) clearance pathways govern electrosurgical device and morcellator market entry in the United States, while EMA MDR compliance shapes commercialization timelines for European surgical equipment manufacturers. The EU AI Act introduces new scrutiny for autonomous features in robotic surgical platforms, affecting R&D prioritization for vendors with European market exposure. Stakeholders must monitor reimbursement policy evolution for outpatient myomectomy procedures as site-of-service economics determine technology adoption trajectories.
Market Dynamics
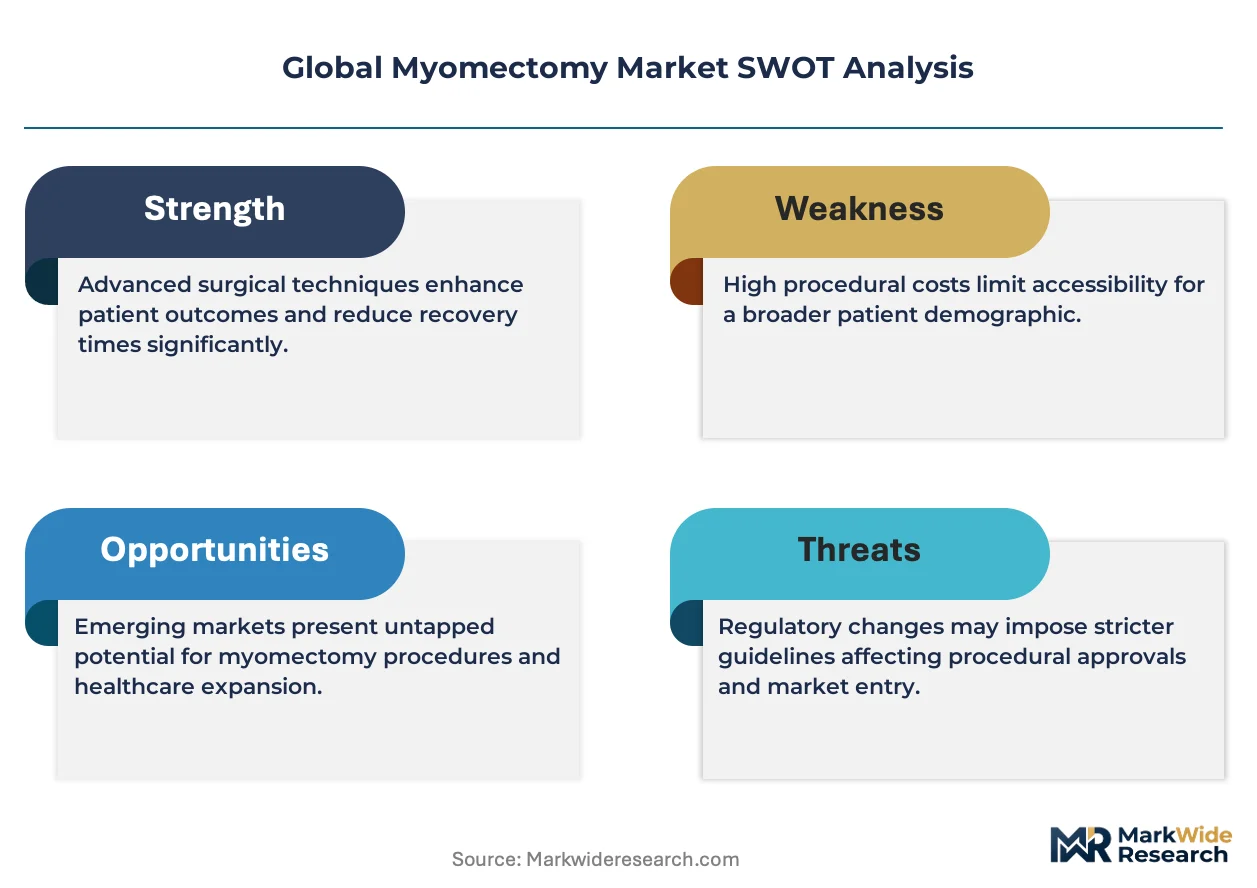
Robotic-assisted surgical platforms are fragmenting the capital equipment hierarchy in myomectomy procedures, forcing hospitals to reconfigure operating room layouts and retrain surgical teams around integrated visualization and energy-delivery ecosystems.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for next-generation morcellators and electrosurgical generators are compressing product development cycles for US manufacturers.
- Fertility preservation demand:Reproductive-age patients in the United States, Germany, and Japan are electing uterus-sparing procedures over hysterectomy at elevated rates.
- Laparoscopic technique maturation:Standardized training curricula and simulator-based credentialing are expanding the addressable surgeon pool across ambulatory surgery centers.
Market Restraints
- Capital intensity of robotic systems:da Vinci platform acquisition and maintenance costs exceed $2 million per installation, restricting deployment to tertiary academic centers and large health systems.
- Single-source morcellator dependence:Concentrated supply of containment systems from specialized manufacturers creates vulnerability for laparoscopic procedure volumes.
- EMA MDR compliance timelines:Extended conformity assessment procedures for Class IIb surgical devices are delaying European market entry for novel energy platforms.
Strategic Opportunities
- India outpatient infrastructure:Greenfield ambulatory surgery center construction in Mumbai and Delhi is creating first-mover advantage for portable laparoscopic tower configurations.
- EU AI Act autonomous features:Regulatory clarity on machine-vision guidance systems is opening development pathways for intraoperative navigation software vendors.
- Tele-proctoring convergence:Real-time surgical mentoring platforms are reducing training barriers for community hospital adoption of minimally invasive techniques.
Industry Challenges
- Robotic console operator certification:Proctored case volume requirements and maintenance-of-privilege standards are constraining surgeon throughput in high-volume centers.
- Interoperability with legacy imaging archives:DICOM integration failures between proprietary robotic systems and hospital PACS networks are generating workflow friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Myomectomy Market |
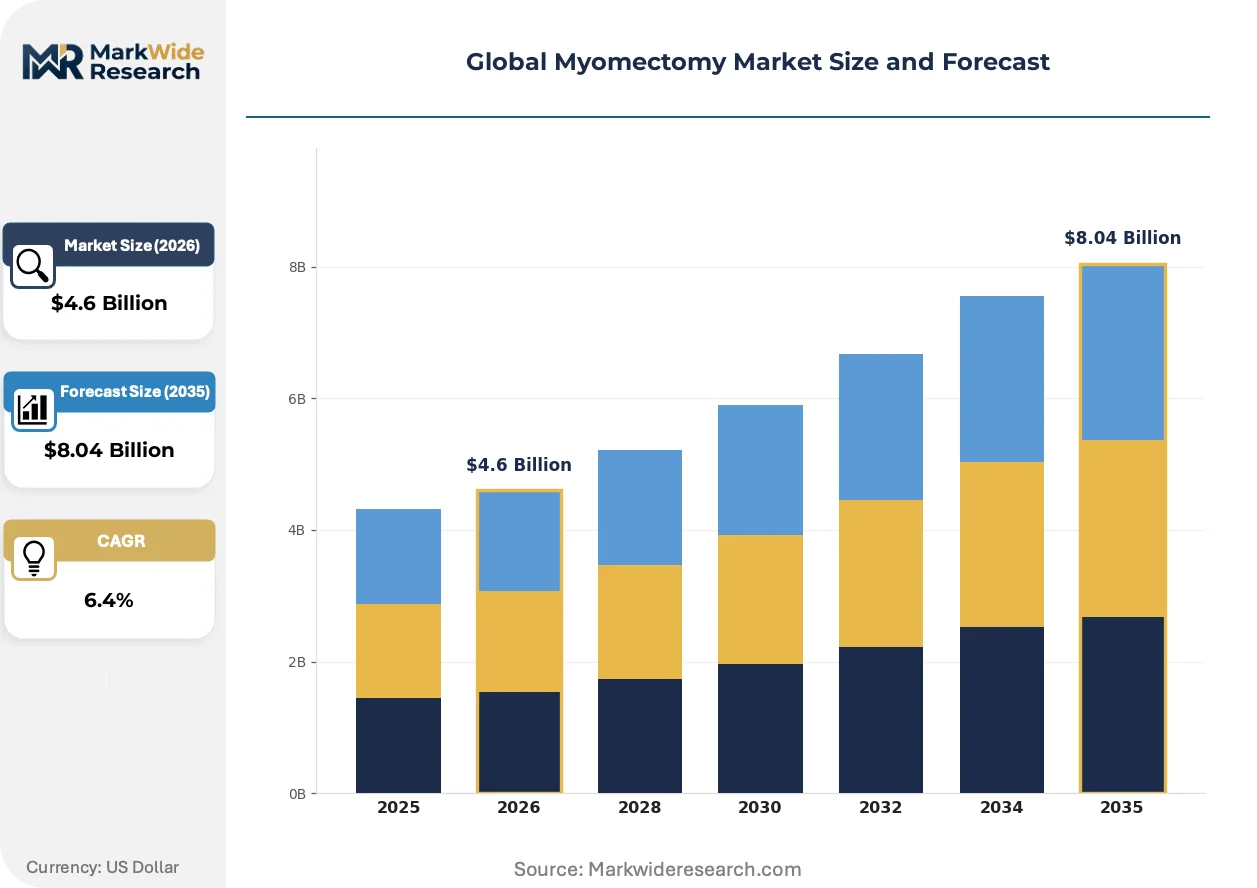
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $8.04 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Open Myomectomy, Laparoscopic Myomectomy, Hysteroscopic Myomectomy, Robotic-Assisted Myomectomy Application: Uterine Fibroids Removal, Fertility Preservation, Symptom Relief, Size Reduction End User: Gynecologic Surgeons, Women’s Health Clinics, Ambulatory Surgery Centers, Specialized Hospitals Technology: Ultrasonic Scalpel, Electrosurgical Devices, Morcellators, Digital Imaging Systems |
| Companies Covered | Johnson & Johnson, Hologic Inc., Medtronic PLC, B. Braun Melsungen AG, ConMed Corporation, Stryker Corporation, Karl Storz SE & Co. KG, The Cooper Companies Inc., Intuitive Surgical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Myomectomy Market Shifts & Advancements
Digital surgical ecosystems are displacing standalone device procurement, creating integrated hardware-software-service bundles that lock in hospital customers through training dependencies and data analytics subscriptions.
Intraoperative fluorescence imaging is modularizing the visualization stack in laparoscopic myomectomy, enabling real-time tissue perfusion assessment. Gynecologic oncology units in academic medical centers are adopting this capability fastest, with adoption curves compressing from five-year to eighteen-month implementation cycles. Modular integration is allowing hospitals to upgrade existing towers rather than replacing entire capital installations.
The EU AI Act's risk classification framework for autonomous surgical features is forcing vendors to restructure R&D roadmaps around human-in-the-loop validation requirements. European manufacturers with CE-marked robotic platforms are front-loading clinical evidence generation for machine-vision applications. German notified bodies are experiencing assessment backlogs that extend commercialization timelines by eight to fourteen months.
Hospital procurement committees are consolidating vendor relationships around single-source service contracts that bundle devices, disposables, and training. Integrated delivery networks in the United States are displacing traditional capital purchase models with per-procedure leasing arrangements. This shift is most pronounced in Texas and Florida health systems where ambulatory surgery center joint ventures dominate facility planning.
Global Myomectomy Market Segmentation
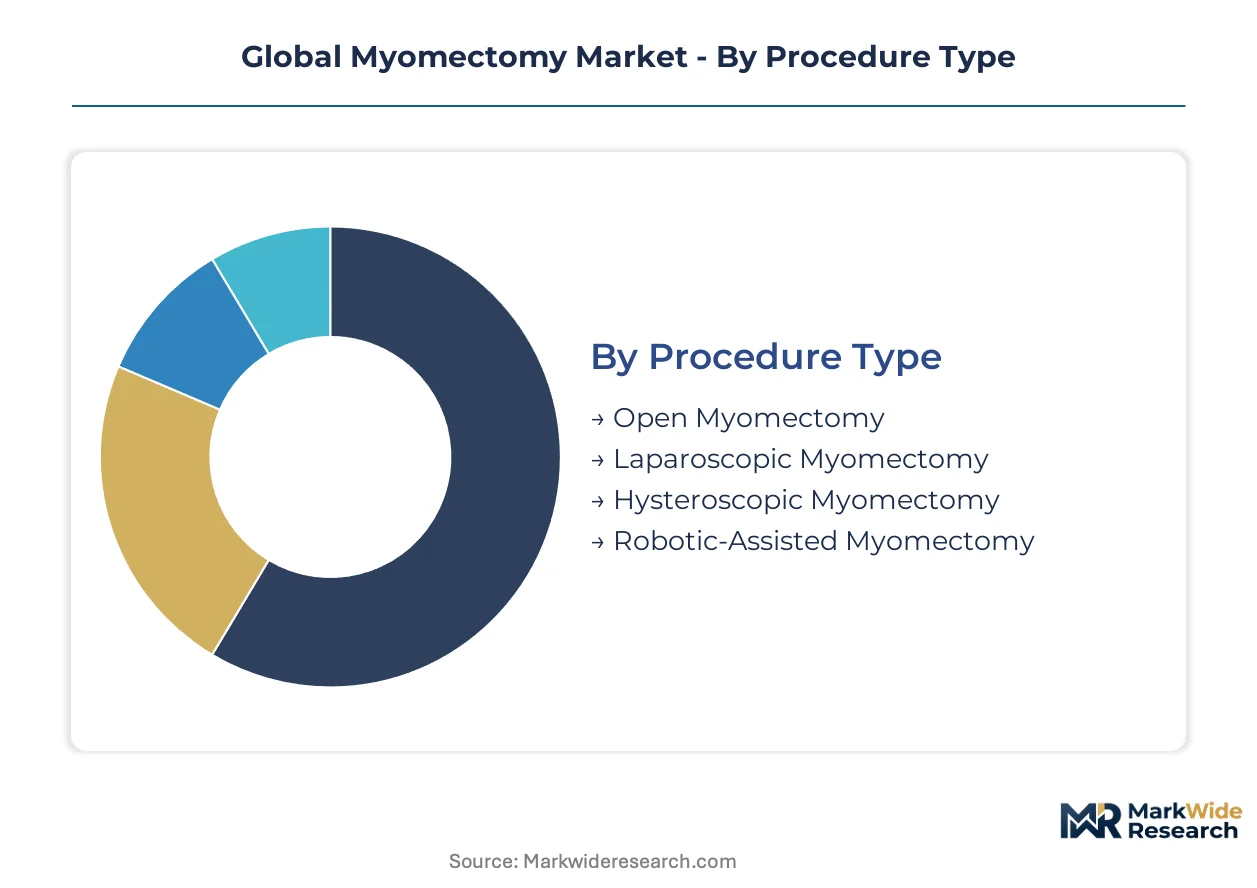
Myomectomy procedure economics vary sharply by surgical approach and technology stack. Device procurement patterns differ between high-volume ambulatory centers and capital-intensive academic hospitals. Understanding segment boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Procedure Type:
Standalone procedures dominate outpatient revenue while embedded robotic systems reshape tertiary hospital economics.
- Laparoscopic Myomectomy:Multi-port abdominal access with carbon dioxide insufflation and electrosurgical tissue sealing. Demand concentrates in German and Japanese ambulatory surgery centers where standardized training curricula expand surgeon pools. Mature technique status limits device premium capture but sustains high procedural volumes.
- Robotic-Assisted Myomectomy:da Vinci console-controlled articulating instruments with 3D visualization and tremor filtration. United States academic medical centers absorb capital costs exceeding two million dollars per installation to attract reproductive-age patients seeking fertility preservation. Human-in-the-loop certification requirements constrain throughput expansion.
- Open Myomectomy:Traditional abdominal incision for large fibroid burdens or complex anatomical presentations.
- Hysteroscopic Myomectomy:Transcervical resectoscope access for submucosal lesions without abdominal entry.
Laparoscopic myomectomy leads volumes today; robotic-assisted myomectomy is gaining share fastest.
Application:
Clinical indication intensity determines reimbursement tiering and technology investment justification.
- Fertility Preservation:Uterus-sparing intervention for reproductive-age patients prioritizing future pregnancy. Demand concentrates in United States metropolitan markets where delayed childbearing trends elevate fibroid prevalence among women over thirty-five. Insurance coverage mandates in several states reinforce procedure economics.
- Uterine Fibroids Removal:Definitive excision of leiomyomas regardless of reproductive intent. Specialized hospitals in India and Germany perform highest volumes where hysterectomy alternatives face cultural or clinical resistance. Symptom severity thresholds determine surgical candidacy.
- Symptom Relief:Menorrhagia, pelvic pressure, and pain reduction without fertility motivation.
- Size Reduction:Preoperative volume diminishment to enable minimally invasive conversion.
Uterine fibroids removal leads volumes today; fertility preservation is climbing the fastest.
End User:
Site-of-service economics fragment procurement authority across institutional types with divergent capital constraints.
- Ambulatory Surgery Centers:Freestanding facilities optimized for same-day discharge and lower fixed-cost structures. Texas and Florida health systems deploy portable laparoscopic tower configurations to capture joint venture revenue. Per-procedure leasing arrangements displace traditional capital purchase models.
- Specialized Hospitals:Tertiary referral centers with gynecologic oncology integration and fellowship training programs. Japanese and German academic institutions absorb robotic system maintenance costs through research funding cross-subsidies. Complex case referrals sustain premium positioning.
- Gynecologic Surgeons:Individual practitioners or small group practices with procedure-specific privileges.
- Women's Health Clinics:Diagnostic and counseling facilities with limited operative capacity.
Specialized hospitals lead volumes today; ambulatory surgery centers are expanding most quickly.
Technology:
Energy delivery modality and visualization capability define competitive differentiation in device markets.
- Digital Imaging Systems:High-definition laparoscopes with fluorescence overlay for tissue perfusion assessment. Gynecologic oncology units in United States academic centers compress adoption curves from five-year to eighteen-month implementation cycles. Modular integration allows tower upgrades without full replacement.
- Electrosurgical Devices:Bipolar and monopolar generators with vessel sealing algorithms. FDA 510(k) pathway streamlining accelerates clearance timelines for next-generation platforms. Integrated service contracts bundle generators with disposable electrodes.
- Morcellators:Mechanical tissue fragmentation with containment systems for specimen extraction.
- Ultrasonic Scalpel:Vibrating blade technology for simultaneous cutting and coagulation.
Electrosurgical devices lead volumes today; digital imaging systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers of electrosurgical devices and morcellators face divergent compliance costs across jurisdictions, prompting strategic facility placement near high-volume surgical markets with favorable regulatory timelines. The FDA's streamlined 510(k) pathway attracts development investment toward United States distribution networks. EMA MDR conformity assessments in Europe extend commercialization schedules, shifting some production planning toward Asian markets with faster device registration.
United States
Academic medical centers in Houston and Boston drive robotic-assisted procedure volumes as fertility preservation demand climbs among reproductive-age patients. FDA 510(k) clearance timelines for next-generation morcellators compress product development cycles for domestic manufacturers. Dallas-Fort Worth ambulatory surgery centers deploy portable laparoscopic configurations through per-procedure leasing arrangements with integrated delivery networks.
Germany
Specialized hospitals in Munich and Berlin absorb da Vinci system maintenance costs through research funding cross-subsidies while expanding fellowship training programs. EMA MDR compliance timelines for Class IIb surgical devices delay market entry for novel energy platforms, prompting manufacturers to front-load clinical evidence generation. The Baden-Württemberg industrial corridor concentrates electrosurgical generator production for European distribution.
Japan
Tokyo and Osaka metropolitan markets exhibit elevated laparoscopic myomectomy volumes as delayed childbearing trends elevate fibroid prevalence among women over thirty-five. PMDA consultation pathways for software-as-medical-device features shape development roadmaps for machine-vision guidance systems. Nagoya-based academic institutions anchor gynecologic oncology training pipelines that sustain premium robotic system utilization.
India
Mumbai and Delhi greenfield ambulatory surgery center construction creates first-mover opportunity for portable laparoscopic tower configurations targeting outpatient infrastructure expansion. CDSCO medical device registration timelines for Class C electrosurgical equipment remain shorter than European alternatives, attracting import-focused distributors. Karnataka's medical technology manufacturing zones supply cost-competitive morcellator containment systems to Southeast Asian markets.
United Kingdom
London teaching hospitals integrate fluorescence imaging modules into existing laparoscopic towers, compressing adoption curves from five-year to eighteen-month implementation cycles. MHRA convergence with EMA MDR standards extends conformity assessment durations for novel surgical energy platforms. The Oxford-Cambridge arc anchors digital surgical ecosystem development partnerships between academic medical centers and visualization technology vendors.
Global Myomectomy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular imaging and autonomous guidance capabilities that bypass capital-intensive robotic console economics. The vendor base stratifies across integrated surgical conglomerates, specialized women's health device manufacturers, and robotic platform originators. Three archetypes dominate: diversified medical technology holding companies with broad surgical portfolios, diagnostic-to-surgical workflow specialists, and energy-based device platform competitors extending into robotic suites. Consolidation pressures favor acquisition of fluorescence imaging and machine-vision navigation assets; strategic partnerships between tower manufacturers and software vendors accelerate integrated bundle formation.
Among diversified surgical conglomerates, Johnson & Johnson and Stryker Corporation exemplify integrated service contract strategies that lock hospital customers through training dependencies and disposable supply arrangements. Hologic Inc. and Intuitive Surgical Inc. occupy distinct positioning archetypes—Hologic anchoring diagnostic-to-surgical workflow integration in women's health clinics, Intuitive representing capital-intensive robotic platform economics that reshape tertiary hospital operating room configurations. Medtronic PLC sits within the energy-based device tier, competing through generator and sealing technology platforms that extend across laparoscopic and robotic-assisted procedure suites. Karl Storz SE & Co. KG and B. Braun Melsungen AG demonstrate German-origin specialization in visualization and electrosurgical instrumentation respectively.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Hologic Inc. |
| Medtronic PLC |
| B. Braun Melsungen AG |
| ConMed Corporation |
| Stryker Corporation |
| Karl Storz SE & Co. KG |
| The Cooper Companies Inc. |
| Intuitive Surgical Inc. |
| Others |
Supply & Pricing Matrix
Academic medical center procurement committees concentrate purchasing authority for robotic-assisted myomectomy platforms, enforcing per-procedure leasing arrangements that displace traditional capital purchase models across United States health systems. This buyer concentration amplifies price transparency and compresses margins for electrosurgical device manufacturers competing through integrated service contracts.
Pricing Analysis
Distributor margins on electrosurgical generators and morcellator containment systems typically absorb 15-25 points before hospital delivery, though direct-to-manufacturer contracts for da Vinci system disposables bypass this layer entirely. Pricing stratifies across premium robotic console attachments, standard laparoscopic tower configurations, and economy-grade reusable instruments. Cost compression in reusable instrument reprocessing is intensifying because ambulatory surgery centers prioritize capital efficiency over device longevity. Community hospital procurement teams demonstrate highest price sensitivity, while Japanese academic medical centers absorb premium positioning for fertility preservation programs.
Supply Chain Analysis
Workforce availability for precision electrosurgical component assembly concentrates in Germany's Baden-Württemberg corridor and Karnataka's medical technology zones, where specialized technician training programs feed device manufacturing clusters. Raw material dependencies center on surgical-grade stainless steel from Swedish mills, high-purity ceramics for insulation, and specialized polymers for morcellator containment bags. Single-source vulnerability for fluorescence imaging sensor modules creates supply chain risk given concentrated production in Japanese optoelectronics facilities. Distribution runs through specialized surgical device distributors with GPO contracting relationships, though direct manufacturer-to-hospital logistics are gaining share for high-value robotic platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Myomectomy Market functions as a stable compounder anchored by irreversible demographic shifts toward delayed childbearing that sustain fertility preservation demand across developed health systems. Procedure volume growth in ambulatory settings provides defensive revenue visibility regardless of macroeconomic cycles.
For Market Incumbents: Acquire fluorescence imaging and machine-vision navigation assets to preempt modular upgrade cycles that threaten integrated robotic system lock-in. Johnson & Johnson and Stryker Corporation must deepen backward integration into disposable electrode manufacturing before emerging entrants capture ambulatory surgery center procurement committees with cost-competitive alternatives. Priority lever rests on securing exclusive GPO contracts that bundle training dependencies with device supply.
For New Entrants and Emerging Players: Tele-proctoring platforms offer the most penetrable entry vector, enabling remote surgical mentoring that reduces training barriers for community hospital laparoscopic adoption without requiring da Vinci console capital expenditure. Target India outpatient infrastructure in Mumbai and Delhi where greenfield ambulatory surgery center construction lacks incumbent service relationships. Go-to-market angle should emphasize portable laparoscopic tower configurations with per-procedure financing that mirrors United States leasing arrangements.
For Investors and Strategic Acquirers: Diversified surgical conglomerates with broad energy-based device portfolios are the most active acquirers in this space, seeking diagnostic-to-surgical workflow integration capabilities. Long-term viability over a five-to-ten year window rests on regulatory capture through FDA 510(k) pathway familiarity and EMA MDR technical documentation depth. Acquisition target archetype: modular imaging specialists with CE-marked fluorescence overlay systems. Signal to watch is reimbursement policy evolution for outpatient myomectomy procedures, as site-of-service economics determine technology adoption trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery networks in Texas and Florida consolidate vendor relationships through exclusive service contracts. |
| Software Companion Development | Machine-vision guidance systems must satisfy EU AI Act human-in-the-loop requirements for European market access. |
| CE Marking Pathway | German notified body assessment backlogs extend commercialization timelines for novel electrosurgical energy platforms. |
| Reimbursement Strategy | State-level insurance coverage mandates for fertility preservation reinforce procedure economics in United States metropolitan markets. |
| FDA Submission | Streamlined 510(k) clearance for next-generation morcellators compresses product development cycles for domestic manufacturers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gynecologic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling and top-down device revenue triangulation anchored market size estimates.
Segment-weighting approaches distributed value across procedure type, application indication, end-user facility category, and technology platform, with fertility preservation demand intensity and robotic system penetration rates as cross-cutting variables. CAGRs were derived from logistic adoption curves for minimally invasive techniques and capital equipment replacement cycles. Forecast inputs incorporated PMDA consultation timelines for software-as-medical-device features and CDSCO registration patterns for Indian market entry.
The model assumes a particular technology adoption path; alternative pathways for autonomous robotic features under EU AI Act scrutiny would alter the outlook. Forecasts reflect assumptions regarding reimbursement stability, regulatory pathway continuity, and surgeon training pipeline expansion that could shift materially with policy intervention. Material deviation in FDA clearance timelines, EMA notified body capacity, or outpatient procedure reimbursement rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Global Microsurgery Market