
 Needle Holders Market | 2026-2036
Needle Holders Market Size, Share, and Industry Trends Forecast 2026-2036
Needle Holders Market Foresight
German surgical instrument manufacturing is expanding its precision-forging capacity for needle holders and allied laparoscopic tools. Karl Storz leverages its heritage in minimally invasive surgery to dominate European supply channels for tungsten carbide-tipped instruments. Stryker Corporation sustains North American hospital contracts through integrated surgical workflow solutions. B. Braun Melsungen AG anchors Central European demand with vertically controlled stainless steel sourcing and in-house sterilization validation.
Needle holders are grasping instruments engineered with locking ratchet mechanisms and carbide-inserted jaws to secure suture needles during wound closure, typically manufactured from surgical-grade stainless steel or titanium alloys with Rockwell hardness exceeding 40 HRC for jaw durability. Tungsten carbide needle holders command premium positioning due to superior grip longevity in high-volume surgical settings, while disposable plastic variants capture outpatient clinic volume where reprocessing economics prove unfavorable. Stainless steel and titanium material segments split procurement budgets across hospitals prioritizing instrument lifecycle cost against upfront capital outlay.
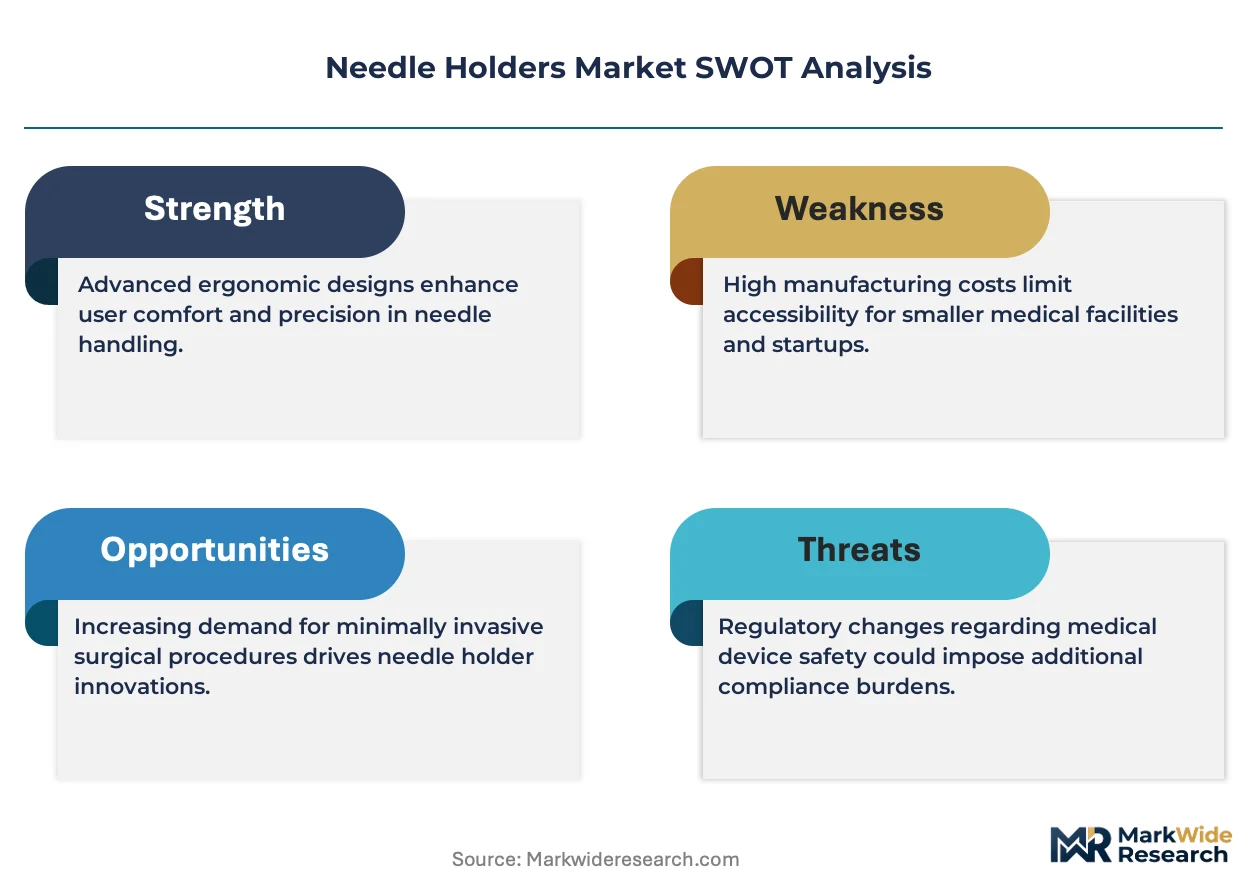
FDA 510(k) clearance requirements and CE marking under the EU Medical Device Regulation govern market access for reusable needle holders, with ISO 13485 quality management certification now baseline for contract eligibility at major hospital purchasing groups. The EPA and OSHA frameworks indirectly shape demand through sterilization chemical exposure limits that favor instrument designs compatible with low-temperature hydrogen peroxide plasma cycles. Stakeholders must monitor evolving MDR vigilance reporting obligations and FDA guidance on reusable device reprocessing validation as these frameworks intensify documentation burdens for manufacturers serving regulated markets.
Market Dynamics
EU Medical Device Regulation vigilance reporting obligations are intensifying documentation burdens for reusable instrument manufacturers, compressing product development timelines and favoring suppliers with established quality management systems.
Growth Catalysts
- Tungsten carbide jaw inserts:Tertiary hospitals in the United States prioritize these inserts for superior grip longevity during high-volume surgical workflows.
- CE marking under EU MDR:This framework accelerates procurement standardization across German and French hospital purchasing groups.
- Minimally invasive surgery expansion:Laparoscopic procedure volumes in Japan are driving demand for precision-forged needle holders with extended shaft designs.
Market Restraints
- Surgical-grade stainless steel price volatility:Nickel and chromium input costs fluctuate with commodity markets, squeezing margin structures for mid-tier manufacturers.
- German precision-forging concentration:Tungsten carbide insert supply depends on a limited cluster of specialized forges in Solingen and Tuttlingen.
- FDA 510(k) clearance timelines:Reusable device reprocessing validation requirements extend approval cycles by 12-18 months for novel designs.
Strategic Opportunities
- Outpatient clinic disposable penetration:Plastic single-use variants capture volume in United States ambulatory surgical centers where reprocessing economics prove unfavorable.
- ISO 13485 certification gaps:Emerging manufacturers in India can access contract eligibility at major hospital purchasing groups by achieving this baseline quality standard.
- Low-temperature sterilization compatibility:Hydrogen peroxide plasma cycle designs open procurement channels constrained by EPA and OSHA chemical exposure limits.
Industry Challenges
- Rockwell hardness testing expertise:Jaw durability validation requires specialized metallurgical laboratories, creating bottlenecks for new market entrants.
- Legacy instrument reprocessing integration:New locking ratchet mechanisms must demonstrate compatibility with existing hospital sterilization infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Needle Holders Market |
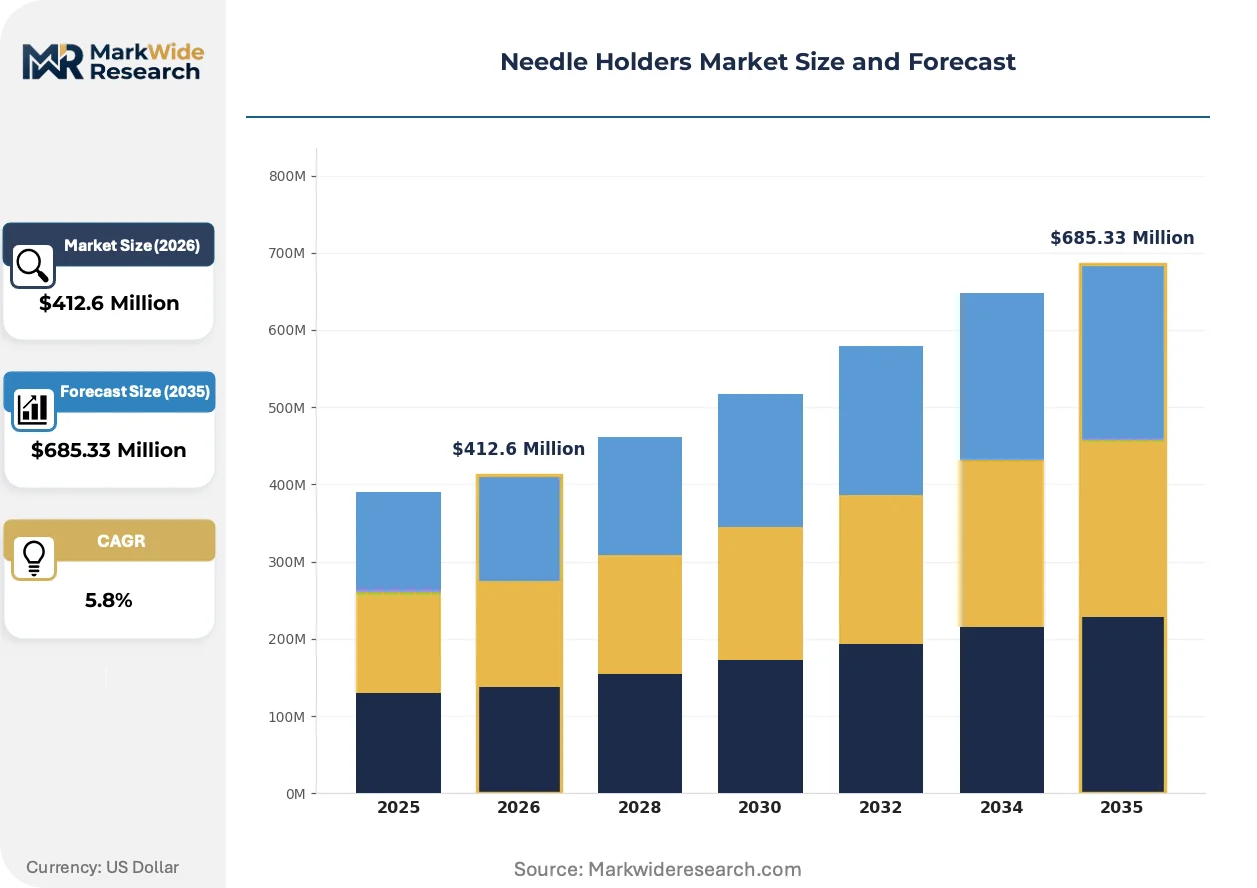
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Needle Holders, Tungsten Carbide Needle Holders, Disposable Needle Holders, Curved Needle Holders Material: Stainless Steel, Plastic, Titanium, Alloy Application: Surgical Procedures, Emergency Medicine, Veterinary Use, Laboratory Procedures End User: Hospitals, Clinics, Laboratories, Research Institutions |
| Companies Covered | Karl Storz, Stryker Corporation, B. Braun Melsungen AG, Medtronic plc, Smith & Nephew plc, Olympus Corporation, Integra LifeSciences Holdings Corporation, Stille AB, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Needle Holders Market Shifts & Advancements
Active reshaping of the needle holder landscape centers on material science advances, regulatory documentation automation, and procurement model compression across hospital systems.
Robotic suturing platforms are automating needle handling sequences in tertiary hospitals, reducing reliance on manual instrument manipulation during laparoscopic procedures. Academic medical centers in the United States are piloting these systems for complex minimally invasive surgeries. This automation is compressing demand for conventional needle holders in high-complexity settings while sustaining volume in open surgery and rural facilities.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for reusable surgical instruments. German manufacturers are restructuring quality management departments to handle expanded vigilance reporting obligations. Class IIa needle holders face the steepest compliance cost increases, prompting portfolio consolidation among mid-tier European suppliers.
Hospital value analysis committees are consolidating vendor contracts around integrated surgical instrument sets rather than individual SKU procurement. This behavioral shift concentrates purchasing power with suppliers offering comprehensive grasping instrument portfolios. The United States exhibits the most pronounced consolidation, with tertiary systems reducing active needle holder vendors from eight to three per facility.
Needle Holders Market Segmentation
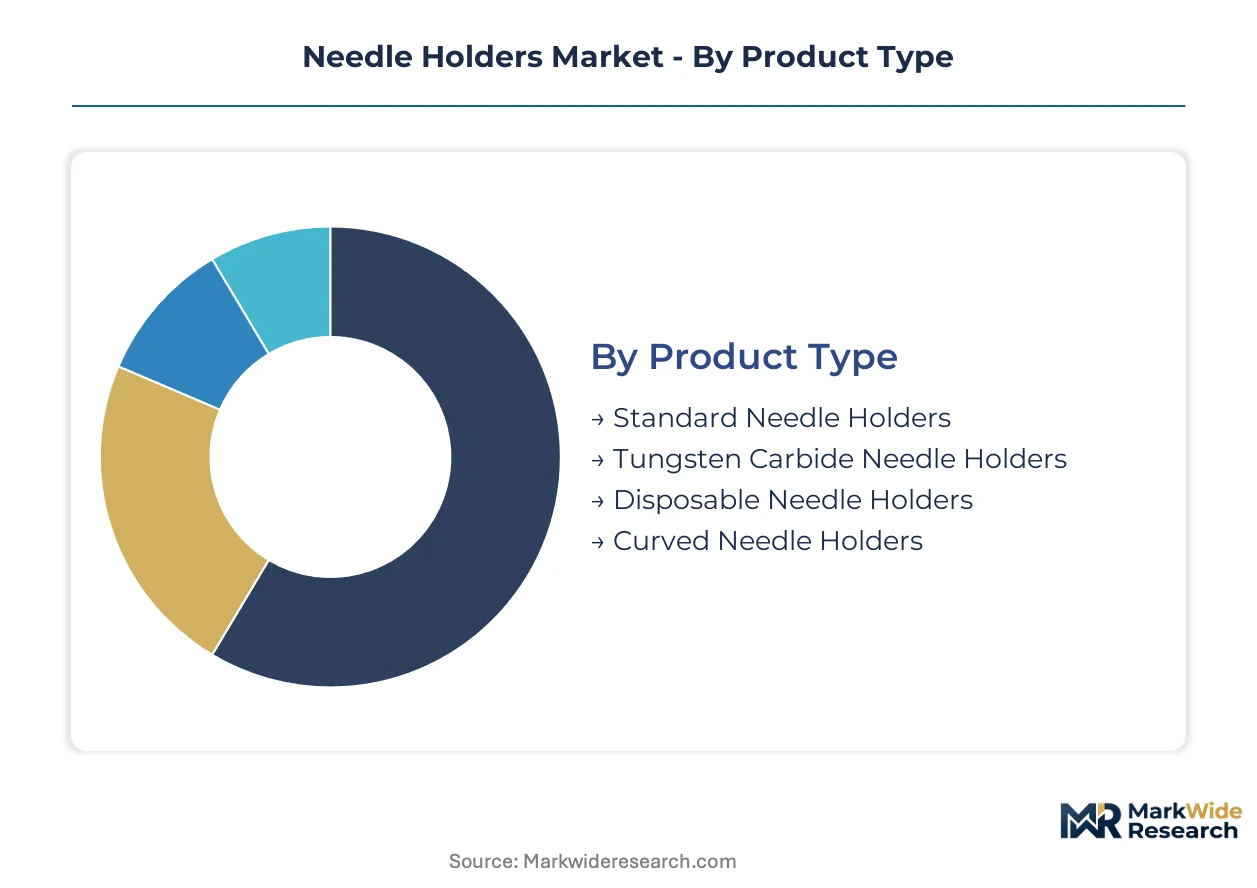
Needle holder procurement splits across four distinct axes: instrument durability versus disposability, metallurgical grade, procedural setting, and institutional purchasing power. Each axis carries different margin structures and regulatory burdens that reshape competitive positioning.
Product Type:
Engineering sophistication defines competitive tiers, with jaw insert technology separating premium positioning from commodity procurement.
- Tungsten Carbide Needle Holders:Carbide-inserted jaws deliver Rockwell hardness exceeding 60 HRC for grip longevity in high-volume surgical workflows. Tertiary hospitals in the United States prioritize these instruments for cardiac and orthopedic suturing where needle slippage carries catastrophic risk.
- Standard Needle Holders:Surgical-grade stainless steel construction with ratchet locking mechanisms serves general surgery and training programs. Procurement concentrates in mid-tier hospitals across Germany and Japan where instrument lifecycle cost outweighs premium positioning.
- Disposable Needle Holders:Single-use plastic variants eliminate reprocessing validation for outpatient clinics.
- Curved Needle Holders:Angled jaw configurations facilitate deep cavity access in laparoscopic procedures.
Mature deployment sits with Standard Needle Holders. Newer deployment is concentrated in Disposable Needle Holders.
Material:
Cost-to-performance ratios and sterilization compatibility determine procurement budgets across institutional tiers.
- Stainless Steel:Austenitic 300-series alloys dominate reusable instrument manufacturing, balancing corrosion resistance against forging workability. German precision forges in Solingen and Tuttlingen anchor global supply for this grade.
- Titanium:Biocompatible alloys reduce instrument weight for prolonged surgical procedures. Demand clusters in Japanese academic medical centers prioritizing surgeon ergonomics during complex minimally invasive surgeries.
- Plastic:Medical-grade polymers enable single-use economics for ambulatory settings.
- Alloy:Proprietary metallurgical blends target niche performance specifications.
Volume leadership belongs to Stainless Steel. Titanium commands the steepest expansion trajectory among reusable grades.
Application:
Procedural complexity and sterility requirements fragment demand across four distinct use environments.
- Surgical Procedures:Operating room deployment demands instruments validated for steam, ethylene oxide, and hydrogen peroxide plasma sterilization cycles. FDA 510(k) clearance and CE marking under EU MDR govern market access for this segment.
- Emergency Medicine:Trauma bays require rapid instrument turnover with simplified reprocessing protocols. Field hospitals and military medical units drive portable sterilization-compatible designs.
- Veterinary Use:Animal health applications tolerate lower specification tolerances than human surgery.
- Laboratory Procedures:Research settings prioritize precision handling over sterilization durability.
Revenue concentration rests with Surgical Procedures. Emergency Medicine is gaining share fastest as pre-hospital care capabilities expand.
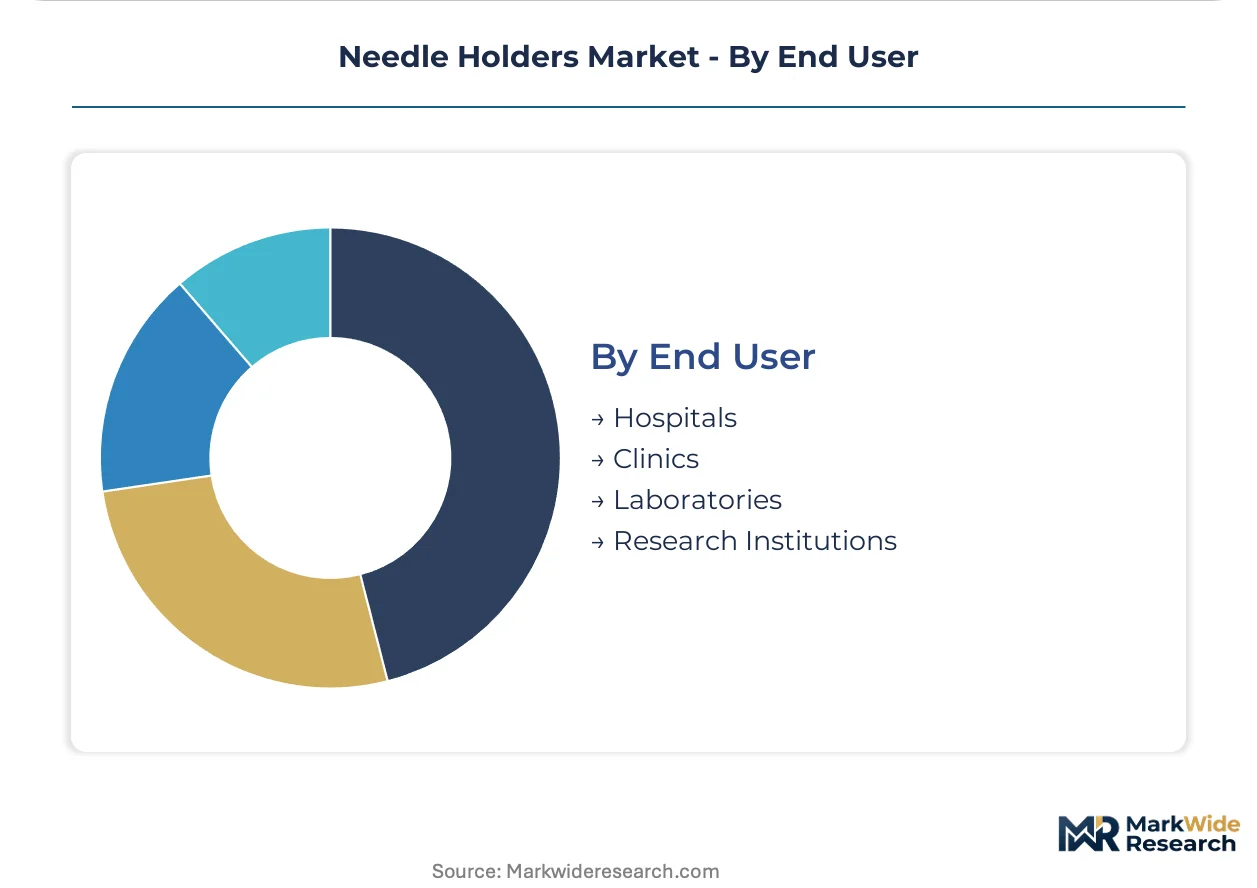
End User:
Purchasing scale and regulatory sophistication create distinct vendor qualification barriers across institutional types.
- Hospitals:Tertiary systems consolidate vendor contracts around integrated surgical instrument sets, reducing active needle holder suppliers from eight to three per facility in the United States. ISO 13485 certification is baseline for contract eligibility.
- Clinics:Ambulatory surgical centers favor disposable variants where reprocessing economics prove unfavorable. Outpatient volume in United States ASCs is climbing the fastest among end-user categories.
- Laboratories:Research institutions procure specialized instruments for microsurgical applications.
- Research Institutions:Academic medical centers pilot robotic suturing platforms that compress manual instrument demand.
Procurement standardization is most advanced at Hospitals. Clinics represent the fastest-growing volume opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solingen and Tuttlingen in Germany anchor precision-forging capacity for tungsten carbide inserts, while stainless steel feedstock flows from Chinese mills and Indian specialty alloy producers shape regional cost structures.
United States
Tertiary hospital systems in Cleveland and Houston drive procurement of carbide-inserted instruments for cardiac and orthopedic workflows. FDA 510(k) clearance requirements extend approval cycles for novel locking ratchet designs. Academic medical centers in Boston pilot robotic suturing platforms that compress manual needle holder demand in high-complexity settings.
Germany
EU MDR vigilance reporting obligations intensify documentation burdens for reusable instrument manufacturers based in Solingen and Tuttlingen. CE marking under the EU Medical Device Regulation accelerates procurement standardization across hospital purchasing groups in Bavaria and North Rhine-Westphalia. Precision forges in the Tuttlingen cluster expand capacity for laparoscopic tool production.
Japan
Academic medical centers in Tokyo and Osaka prioritize titanium alloy instruments for surgeon ergonomics during prolonged minimally invasive procedures. METI industrial standards govern biocompatibility testing for imported surgical instruments. The Nagoya manufacturing corridor hosts specialized producers of extended-shaft laparoscopic needle holders.
India
Ambulatory surgical centers in Maharashtra and Karnataka favor disposable plastic variants where reprocessing economics prove unfavorable. CDSCO medical device registration requirements create compliance barriers for imported reusable instruments. Specialty stainless steel mills in Gujarat supply surgical-grade austenitic alloys to domestic instrument fabricators.
China
NMPA Class II medical device approvals govern market access for imported needle holders in Shanghai and Beijing hospital systems. Yangtze River Delta manufacturers scale production of standard stainless steel instruments for domestic mid-tier hospitals. The Pearl River Delta cluster concentrates disposable plastic variant output for export markets.
Needle Holders Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and integrated surgical workflow offerings. The vendor base stratifies into three tiers: diversified medtech conglomerates with hospital system contracts, specialized surgical instrument manufacturers with precision-forging heritage, and emerging disposable-focused suppliers serving ambulatory settings. Dominant competitive moves include portfolio consolidation around comprehensive grasping instrument sets and backward integration into captive tungsten carbide insert production.
Among German precision-forging specialists, Karl Storz and B. Braun Melsungen AG exemplify the heritage-driven archetype with vertically controlled supply chains. Stryker Corporation represents the diversified conglomerate tier with North American hospital system integration. These three entities anchor competitive positioning across premium tungsten carbide and standard stainless steel segments.
| Leading Market Players |
|---|
| Karl Storz |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Medtronic plc |
| Smith & Nephew plc |
| Olympus Corporation |
| Integra LifeSciences Holdings Corporation |
| Stille AB |
| Teleflex Incorporated |
| Others |
Supply & Pricing Matrix
Family-owned precision-forging specialists in Solingen and Tuttlingen anchor tungsten carbide insert supply, translating heritage metallurgical expertise into pricing discipline that resists commoditization pressure from Asian stainless steel producers.
Pricing Analysis
Warranty and reprocessing validation bundling separates premium tungsten carbide holders from unbundled standard stainless steel alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects jaw insert technology and ISO 13485 certification status. Cost compression in mid-tier stainless steel instruments is intensifying because nickel and chromium input volatility squeezes forge margins. Ambulatory surgical centers exhibit highest price sensitivity, while tertiary hospital systems prioritize grip longevity over unit cost.
Supply Chain Analysis
Tungsten carbide insert supply rests on German specialty forges in Solingen and Tuttlingen, with surgical-grade stainless steel feedstock drawing from Chinese mills and Indian austenitic alloy producers. Raw material dependencies span nickel-chromium alloys, titanium sponge, and medical-grade polymers for disposable variants. Single-source vulnerability concentrates in carbide insert forging capacity. Distribution runs through hospital purchasing groups and specialized surgical instrument distributors serving ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive tungsten carbide insert production to secure margin control against forge capacity bottlenecks.
For Market Incumbents: Deepen backward integration into carbide insert forging to defend against Solingen supply concentration risk. Consolidate vendor relationships with tertiary hospital systems around comprehensive grasping instrument portfolios. Lock in long-term austenitic alloy supply contracts before nickel price volatility escalates. For New Entrants and Emerging Players: Capture disposable plastic variant volume in United States ambulatory surgical centers where reprocessing economics favor single-use instruments. Target ISO 13485 certification gaps among Indian manufacturers seeking contract eligibility at major hospital purchasing groups. Lead with low-temperature sterilization compatibility as a differentiated procurement pitch. For Investors and Strategic Acquirers: FDA 510(k) clearance timeline extensions for novel locking ratchet designs are the leading indicator that regulatory documentation automation capabilities will separate viable acquisition targets from stranded assets. Focus on mid-tier European suppliers facing EU MDR vigilance cost pressures. Watch for portfolio consolidation announcements among Class IIa instrument manufacturers as a signal of distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance opens standardized procurement channels across German hospital purchasing groups. |
| Backward Integration | Captive tungsten carbide insert production insulates margin structures from Solingen forge capacity constraints. |
| Hospital System Partnership | Integrated surgical instrument set contracts concentrate purchasing power with three-vendor-per-facility limits. |
| Software Companion Development | Reprocessing validation documentation automation reduces FDA 510(k) approval cycle burdens. |
| Reimbursement Strategy | Outpatient procedure coding alignment accelerates disposable variant adoption in ambulatory surgical centers. |
Research Methodology
Multi-period observation of laparoscopic procedure volumes, sterilization cycle adoption patterns, and hospital vendor consolidation trends anchored the trend analysis, supplemented by interviews with instrument sterilization technicians, GPO contracts managers, biomedical engineers, and regulatory affairs leads at precision-forging specialists. Secondary validation drew from FDA 510(k) filings, EU MDR vigilance databases, hospital procurement records, and SEC disclosures by diversified medtech conglomerates. Bottom-up instrument shipment estimates triangulated against top-down surgical procedure demand models.
Input-output matrices mapped tungsten carbide insert supply from German forges through finished instrument assembly to end-user procurement channels across the analysis window. Segmentation dimensions modeled included product type, material grade, procedural application, and institutional purchasing tier. CAGRs derived from regression analysis against surgical volume projections and instrument replacement cycle assumptions. Forecast inputs incorporated METI biocompatibility standard revisions and CDSCO registration pathway changes for imported reusable instruments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to robotic suturing platform adoption rates and EU MDR documentation burden escalations. Forecasts reflect documented assumptions regarding sterilization cycle compatibility and hospital value analysis committee behavioral shifts. A small set of triggers warrants ongoing watch: FDA guidance on reusable device reprocessing validation, nickel commodity price spikes, and tertiary hospital robotic surgery pilot expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Dental Surgical Microscopes Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Thoracic Surgery Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Cryosurgery Market