
 Robotic Surgery Market | 2026-2036
Robotic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Surgery Market Outlook
Aftermarket service revenue is rewriting profit architecture across the robotic surgery landscape. Intuitive Surgical dominates installed base maintenance through long-term service contracts that lock in recurring income. Medtronic leverages its diversified medtech portfolio to bundle robotic platforms with complementary surgical instruments. Stryker Corporation anchors orthopedic robotics through its Mako platform, sustaining premium positioning in knee and hip replacement workflows.
Robotic surgery encompasses computer-assisted surgical platforms that integrate electromechanical arms, stereoscopic visualization, and real-time instrument control to perform minimally invasive procedures with submillimeter precision. These systems typically operate through 8-15 mm port incisions, reducing blood loss and hospitalization duration compared with open surgery. Surgical instruments represent the most mature revenue category, while software solutions are capturing expanding margin pools as AI-driven preoperative planning and intraoperative analytics gain clinical traction. The urology application segment retains the deepest installed base, though general surgery is accelerating as platforms broaden instrument compatibility for colorectal and thoracic procedures.
FDA 510(k) and de novo pathways govern US market entry, while the EU MDR and CE marking framework impose strengthened clinical evidence requirements for European commercialization. Japan's PMDA operates a distinct shonin approval track that extends timelines but rewards demonstrated safety profiles with favorable reimbursement. Stakeholders must monitor how regulatory divergence between FDA streamlined pathways and EU MDR conformity assessments reshapes geographic launch sequencing and capital allocation priorities.
Market Dynamics
Long-term service contracts are locking hospital systems into single-vendor ecosystems, creating defensive moats that reshape competitive entry strategies and capital allocation across the robotic surgery value chain.
Growth Catalysts
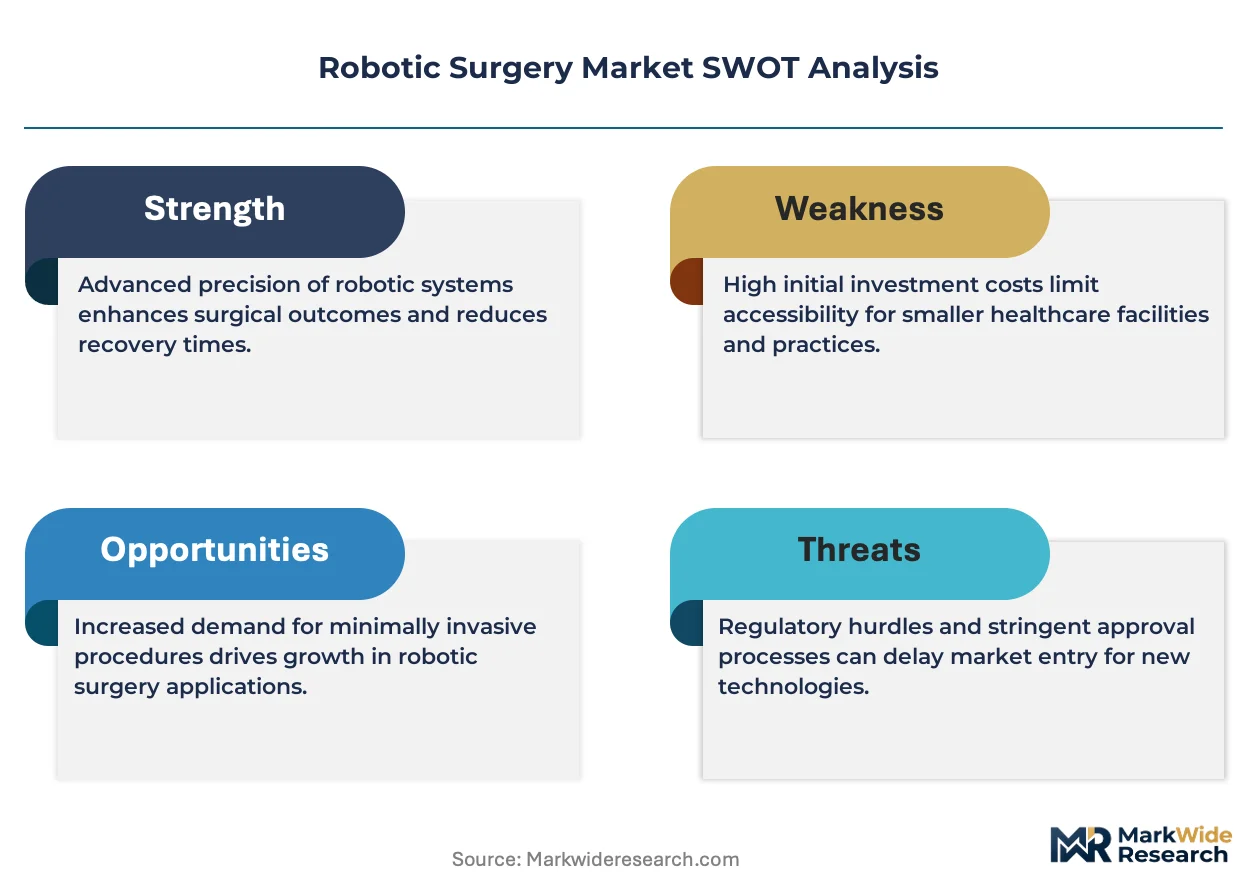
- FDA 510(k) Streamlining:Expedited premarket review for predicate-based robotic platforms accelerates commercialization timelines for iterative system upgrades.
- Minimally Invasive Procedure Demand:Hospital systems prioritize reduced length-of-stay metrics to optimize bed utilization and reimbursement outcomes.
- Japan PMDA Shonin Pathway:Favorable reimbursement rates for demonstrated safety profiles incentivize manufacturers to prioritize clinical evidence generation.
Market Restraints
- Capital Equipment Intensity:Single robotic platform installations require substantial upfront expenditure that constrains community hospital participation.
- Instrument Supply Concentration:Proprietary instrument ecosystems limit third-party alternatives and lock buyers into recurring consumable purchases.
- EU MDR Clinical Evidence Burden:Strengthened conformity assessment requirements extend European commercialization timelines and documentation costs.
Strategic Opportunities
- General Surgery Expansion:Broader instrument compatibility for colorectal and thoracic procedures opens addressable procedure volumes beyond established urology bases.
- AI-Integrated Preoperative Planning:Machine learning analytics for surgical pathway optimization capture expanding software margin pools.
- Germany Hospital Consolidation:Centralized purchasing by large hospital networks creates volume aggregation points for platform negotiations.
Industry Challenges
- Surgeon Training Pipeline:Proctoring requirements and credentialing protocols constrain qualified operator availability.
- Interoperability Friction:Integration with existing hospital information systems and imaging archives demands customized implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Surgery Market |
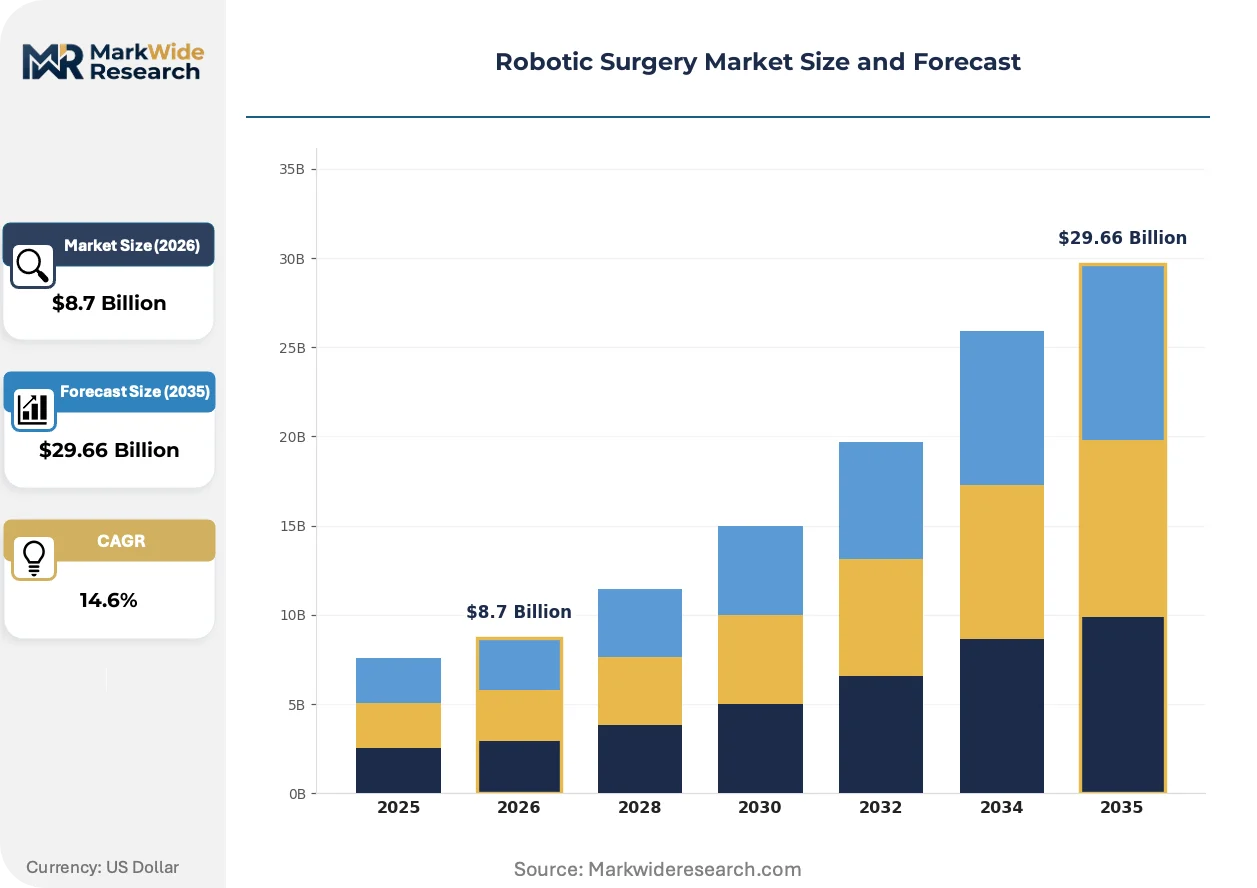
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgical Systems, Surgical Instruments, Imaging Systems, Software Solutions Application: Urology, Gynecology, General Surgery, Neurosurgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Technology: Telemanipulation, Haptic Feedback, Autonomous Systems, Navigation Systems |
| Companies Covered | Intuitive Surgical, Medtronic, Stryker Corporation, Zimmer Biomet, Smith+Nephew, Johnson & Johnson, Asensus Surgical, CMR Surgical, THINK Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Surgery Market Strategic Shifts
Software-enabled functionality is capturing margin from hardware-centric business models. Artificial intelligence, cloud analytics, and augmented visualization are compressing the boundary between intraoperative execution and preoperative intelligence.
Haptic feedback systems are migrating from research prototypes into commercial platforms. Academic medical centers in the United States and Germany are piloting force-sensing instruments that restore tactile information lost in conventional robotic interfaces. This sensory restoration is enabling more complex tissue manipulation and reducing inadvertent injury rates in delicate dissection workflows.
EU MDR post-market surveillance requirements are tightening real-world evidence collection obligations. Manufacturers must now maintain systematic clinical follow-up registries that track long-term device performance across diverse hospital settings. Orthopedic robotics faces the steepest compliance burden given the extended follow-up horizons for joint replacement outcomes.
Hospital procurement committees are consolidating vendor relationships around integrated service bundles. Large health systems in Japan and Germany are negotiating multi-year enterprise agreements that span capital equipment, disposable instruments, and training infrastructure. This consolidation favors suppliers with comprehensive platform ecosystems over point-solution specialists.
Robotic Surgery Market Segmentation
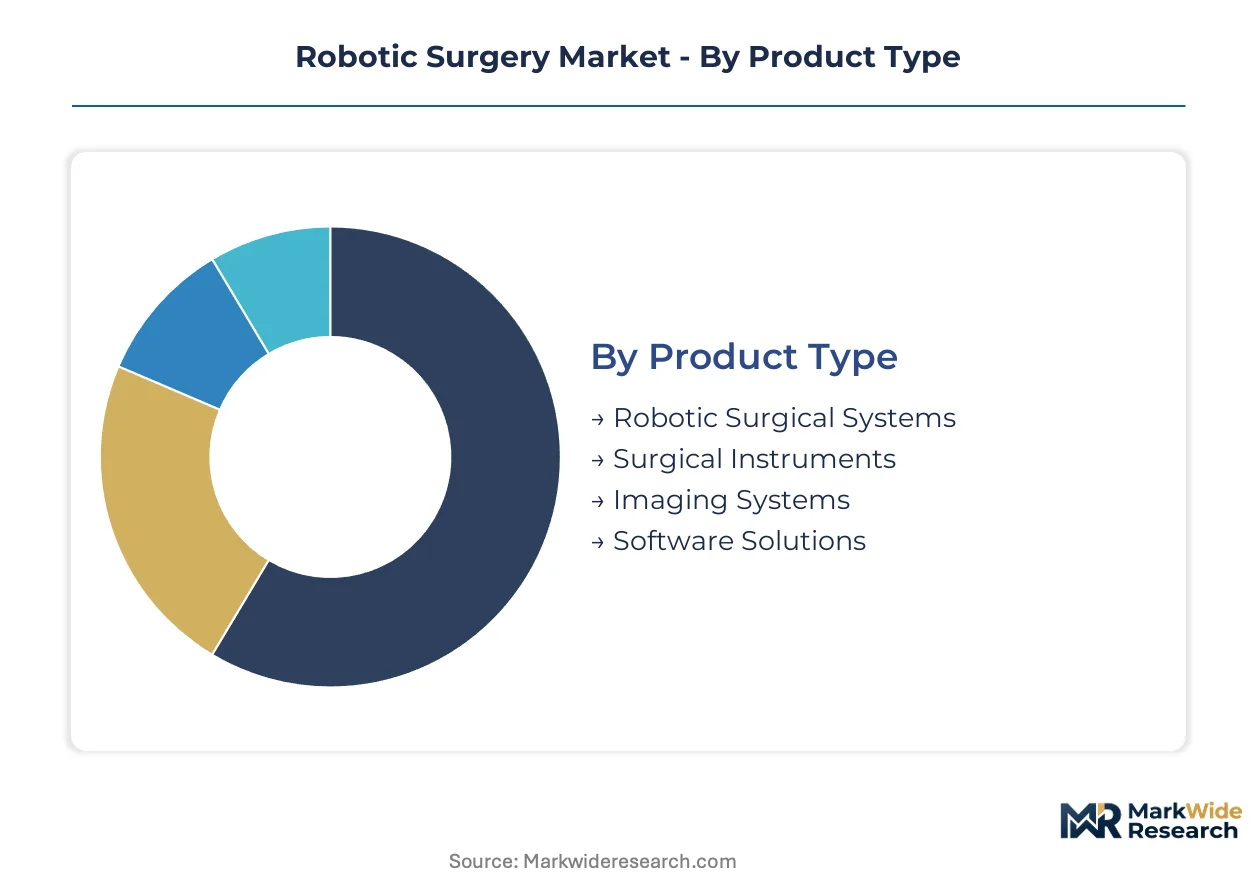
Segmentation in robotic surgery reveals how capital intensity, procedure volumes, and reimbursement structures fragment purchasing behavior across health systems. Each dimension exposes different decision-making hierarchies and vendor lock-in dynamics that reshape competitive entry strategies.
Product Type:
Cycle times diverge sharply across product categories, with consumable instruments turning over in weeks while capital systems lock revenue across decade-long depreciation schedules.
- Robotic Surgical Systems:Electromechanical platforms integrating articulated arms, surgeon consoles, and vision towers that anchor hospital capital budgets. United States health systems concentrate procurement authority at the IDN level, with da Vinci installations requiring dedicated OR infrastructure and biomed support contracts.
- Surgical Instruments:Single-use and limited-reuse end effectors, graspers, and energy devices that generate recurring revenue through procedure volume. German hospital networks prioritize instrument standardization across multiple robotic platforms to reduce supply chain complexity.
- Imaging Systems:Integrated fluorescence and 3D visualization modules that enhance intraoperative navigation. These attach as upgrades to base platforms rather than standalone purchases.
- Software Solutions:Preoperative planning analytics and intraoperative guidance algorithms delivered via cloud or embedded architecture. Japan's PMDA shonin pathway incentivizes manufacturers to bundle AI modules with hardware for favorable reimbursement coding.
Surgical Instruments anchors the volume base while Software Solutions gains share at the steepest rate.
Application:
Procedure reimbursement rates and clinical evidence depth stratify adoption maturity across surgical specialties.
- Urology:Radical prostatectomy and partial nephrectomy procedures that established the first commercial robotic installed bases. United States academic medical centers retain the deepest case volumes, though community hospital adoption is plateauing as prostate cancer screening rates shift.
- Gynecology:Hysterectomy and myomectomy procedures where robotic approaches compete with conventional laparoscopy on cost-effectiveness metrics. Hospital systems in Germany evaluate robotic gynecology against established MIS pathways with shorter learning curves.
- General Surgery:Colorectal resection, hernia repair, and bariatric procedures that represent the largest untapped procedure volume. Platform manufacturers are expanding instrument compatibility to capture this expansion.
- Neurosurgery:Stereotactic biopsy and tumor resection applications where navigation precision outweighs capital cost concerns. Research institutions in Japan pilot these systems for functional neurosurgery applications.
Urology retains the deepest installed base while General Surgery is expanding most quickly as platforms broaden instrument compatibility.
End User:
Purchasing authority and capital access stratify across facility types, with reimbursement environment determining viable business models.
- Hospitals:Integrated delivery networks and academic medical centers that control the majority of robotic surgery volume. These entities negotiate multi-year enterprise agreements spanning equipment, consumables, and training infrastructure.
- Ambulatory Surgical Centers:Freestanding facilities where CMS reimbursement for outpatient robotic procedures determines investment viability. United States ASC chains evaluate robotic platforms against case volume thresholds and payer mix.
- Clinics:Specialty urology and gynecology practices with limited procedure volume that rely on hospital partnerships for robotic access rather than direct capital investment.
- Research Institutions:Academic centers where clinical trial participation and training proctoring generate revenue offsetting equipment costs. These sites pilot haptic feedback and autonomous functionality before commercial rollout.
Hospitals anchor the revenue base while Ambulatory Surgical Centers are climbing the fastest as outpatient reimbursement frameworks mature.
Technology:
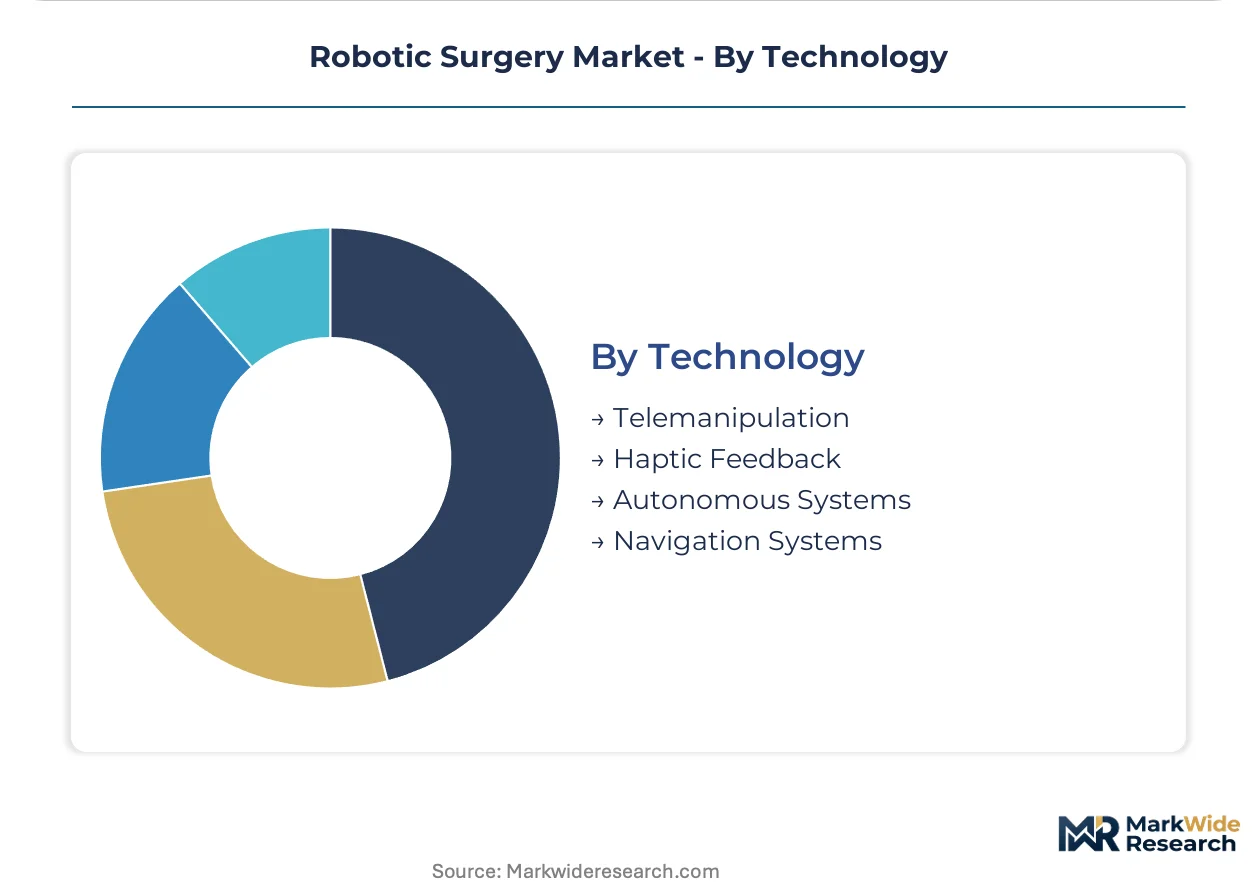
Technical maturity and regulatory pathway complexity fragment R&D investment across capability layers.
- Telemanipulation:Master-slave architectures where surgeon hand movements translate to instrument motion with motion scaling and tremor filtration. This dominates current commercial installations.
- Haptic Feedback:Force-sensing instruments that restore tactile information lost in conventional robotic interfaces. Academic medical centers in the United States and Germany pilot these systems for delicate tissue dissection.
- Autonomous Systems:AI-directed suturing and tissue manipulation with limited human oversight. Regulatory frameworks for autonomous surgical action remain underdeveloped across FDA and EU MDR pathways.
- Navigation Systems:Preoperative imaging registration and real-time instrument tracking that overlays anatomical guidance. These integrate with existing imaging archives but demand customized hospital IT implementation.
Telemanipulation anchors the installed base while Haptic Feedback is gaining share fastest as sensory restoration enables more complex procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health systems in the United States deploy robotic platforms across the broadest procedure spectrum, while German hospitals concentrate investment in orthopedic and general surgery applications. Japanese institutions prioritize neurosurgical navigation systems with extended regulatory follow-up. Emerging adoption in India and Brazil follows distinct capital-constrained pathways favoring shared-access models over direct hospital ownership.
United States
Integrated delivery networks in Texas and California anchor the deepest installed bases for urologic and gynecologic robotics. FDA 510(k) streamlining enables rapid predicate-based upgrades, compressing commercialization timelines for iterative system enhancements. Academic medical centers in Boston and the Research Triangle pilot haptic feedback integration before broader rollout.
Germany
Hospital consolidation in North Rhine-Westphalia and Bavaria creates centralized procurement authority favoring multi-year enterprise agreements. EU MDR conformity assessments impose strengthened clinical evidence requirements that extend documentation timelines for European market entry. The Munich and Berlin clusters concentrate orthopedic robotics adoption within large university hospital networks.
Japan
PMDA shonin approval pathways reward demonstrated safety profiles with favorable reimbursement rates that incentivize clinical evidence generation. Kanto and Kansai regions concentrate neurosurgical robotics pilot programs at academic institutions. Tokyo Medical University and Osaka University hospitals generate proctoring revenue through training infrastructure that offsets equipment acquisition costs.
India
Metropolitan hospital chains in Maharashtra and Karnataka deploy robotic platforms through leasing arrangements that circumvent capital intensity constraints. The country's national pharmaceutical regulator maintains distinct import licensing requirements for electromechanical surgical devices. Apollo and Fortis hospital networks in Chennai and Hyderabad aggregate procedure volumes across multiple cities to justify platform investment.
Brazil
São Paulo and Rio de Janeiro concentrate robotic surgery adoption within premium private hospital networks serving insured populations. ANVISA operates parallel registration tracks that extend timelines for imported capital equipment relative to domestic assembly alternatives. Hospital Israelita Albert Einstein and Sírio-Libanês anchor training proctoring capacity that spreads qualified operator availability across the Southeast region.
Robotic Surgery Market Competitive Environment
Capability concentration sits with established platform developers holding decade-long service contract portfolios; scale advantage sits with diversified medtech conglomerates bundling robotics within broader surgical portfolios. The vendor base stratifies across three tiers: integrated platform ecosystems, orthopedic specialization houses, and emerging soft-tissue challengers. Dominant competitive moves include long-term hospital lock-in through training infrastructure and instrument supply concentration, plus geographic expansion via regulatory pathway arbitrage between FDA streamlined tracks and EU MDR extended timelines.
Within the integrated platform tier, Intuitive Surgical and Medtronic occupy positions that exemplify divergent strategic postures toward ecosystem control. Intuitive Surgical anchors recurring revenue architecture through installed base maintenance contracts that span system depreciation cycles. Medtronic represents the diversified conglomerate archetype, leveraging cross-divisional instrument portfolios to bundle robotic capital expenditure within broader surgical workflow negotiations. Stryker Corporation sits within the orthopedic specialization vector, where premium positioning in joint replacement workflows sustains defensive margins against soft-tissue platform migration.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Medtronic |
| Stryker Corporation |
| Zimmer Biomet |
| Smith+Nephew |
| Johnson & Johnson |
| Asensus Surgical |
| CMR Surgical |
| THINK Surgical |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-to-Rotterdam maritime corridor's container rate volatility compresses margin buffers for electromechanical platform manufacturers while amplifying price differentiation between integrated service bundles and bare-metal capital sales. German hospital networks leverage this logistics cost pressure to negotiate multi-year enterprise agreements that lock in consumable pricing, whereas Indian metropolitan chains absorb freight volatility through leasing structures that transfer ownership risk to third-party lessors.
Pricing Analysis
Long-term service contracts dominate robotic surgery commercial architecture, with pricing stratifying across premium, standard, and economy tiers based on instrument bundle comprehensiveness and training infrastructure inclusion. FDA 510(k) predicate pathways accelerate iterative system upgrades that sustain premium positioning for early movers, while CE marking under EU MDR imposes documentation costs that compress margins for European market entrants. Ambulatory surgical centers exhibit acute price sensitivity due to CMS reimbursement thresholds, whereas academic medical centers prioritize ecosystem breadth over per-procedure economics.
Supply Chain Analysis
High-precision servo motors and optical encoders draw from specialized manufacturing clusters in Japan, Germany, and Switzerland that anchor electromechanical arm production. Single-source dependencies on rare-earth magnet suppliers concentrate vulnerability in neodymium procurement chains, while semiconductor content for vision processing modules rests on Taiwan and South Korea foundry capacity. Distribution runs through authorized distributor networks that bundle installation, biomed training, and maintenance contracting rather than discrete equipment transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic surgery demand cycles correlate with hospital capital expenditure recovery phases following reimbursement rate adjustments, positioning the market for expansion as health systems prioritize length-of-stay reduction metrics.
For Market Incumbents: Insulate installed base revenue through proprietary instrument ecosystems that raise switching costs for hospital procurement committees facing surgeon retraining expenses. Extend service contract durations to match system depreciation schedules, countering emerging soft-tissue challengers by embedding AI-driven analytics modules that demonstrate measurable outcome improvements in colorectal and thoracic workflows. For New Entrants and Emerging Players: Mid-tier hospital networks in India and Brazil represent the most penetrable entry point where capital constraints favor leasing partnerships over direct platform sales. Target neurosurgical navigation applications in Japanese academic institutions where PMDA shonin pathways reward clinical evidence generation with favorable reimbursement coding, deploying training-proctoring revenue models that offset equipment acquisition barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates seeking to divest non-core robotics divisions amid portfolio rationalization pressures. Monitor EU MDR post-market surveillance compliance costs as an inflection indicator for distressed asset availability, particularly among orthopedic specialization houses facing extended joint replacement follow-up obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year enterprise agreements with IDNs lock in recurring consumable revenue across urology and general surgery applications. |
| Software Companion Development | AI-integrated preoperative planning modules capture expanding margin pools as FDA 510(k) pathways accommodate algorithmic enhancements. |
| CE Marking Pathway | EU MDR conformity assessment investment accelerates European commercialization timelines relative to competitors burdened by documentation gaps. |
| Reimbursement Strategy | PMDA shonin alignment in Japan secures favorable procedure coding that drives hospital procurement committee prioritization. |
| Backward Integration | In-house production of force-sensing instruments reduces haptic feedback platform cost structures and accelerates regulatory submission timelines. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and robotic surgery proctors, then refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, CMS Medicare procedure databases, and hospital procurement contract registries. Bottom-up procedure volume estimates triangulated with top-down capital expenditure forecasts across the analysis window.
Demand-supply balance modeling segmented projections across product type, application specialty, end-user facility tier, and technology maturity level throughout the forecast period. CAGRs derived from installed base growth trajectories, instrument utilization rates, and service contract renewal patterns, with cross-reference to PMDA approval timelines and ANVISA registration tracks for geographic expansion scenarios.
Practitioners should monitor reimbursement rate adjustments, EU MDR post-market surveillance enforcement intensity, and haptic feedback regulatory pathway developments for early signals of forecast revision triggers. Cross-checking against hospital capital budget disclosure filings and GPO contract award announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Thoracic Surgery Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market