
 Equine Surgical Equipment Market | 2026-2036
Equine Surgical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Equine Surgical Equipment Market Analytics
Specialized veterinary surgical training is reorganizing how equipment manufacturers align product development with clinical workflows. Ethicon leverages its suture and wound closure heritage to sustain dominance in soft tissue applications. Jørgen Kruuse A/S anchors its position through deep specialization in equine-specific instrument design across Scandinavian and Central European markets.
Equine surgical equipment encompasses purpose-built instruments, anesthesia delivery systems, imaging platforms, and operative tables engineered for 450-550 kg patients, typically constructed from surgical-grade stainless steel or titanium alloys to withstand repeated sterilization cycles. The equipment serves orthopedic intervention, emergency colic surgery, and diagnostic arthroscopy in performance horses and breeding stock. Surgical instruments command the most entrenched margin pool due to replacement frequency and custom kit configurations, while robotic-assisted technology represents the fastest-expanding segment as university veterinary hospitals adopt precision platforms for minimally invasive procedures. Imaging systems compete primarily on detector resolution and portability between clinic and field settings.
FDA Center for Veterinary Medicine oversight governs device safety claims in the United States, while ISO 13485 certification functions as a baseline market access requirement across all major supply destinations. The EU Medical Device Regulation's veterinary spillover effects and Japan's PMDA alignment with JIS quality standards further stratify compliance burdens for multinational suppliers. Stakeholders must weigh regulatory capital requirements against the defensive value of multi-jurisdiction certification when prioritizing geographic expansion sequences.
Market Dynamics
Robotic-assisted surgical platforms are compressing the adoption curve for minimally invasive procedures in university veterinary hospitals, forcing traditional instrument manufacturers to recalibrate their R&D roadmaps and service architectures around precision-guided intervention workflows.
Growth Catalysts
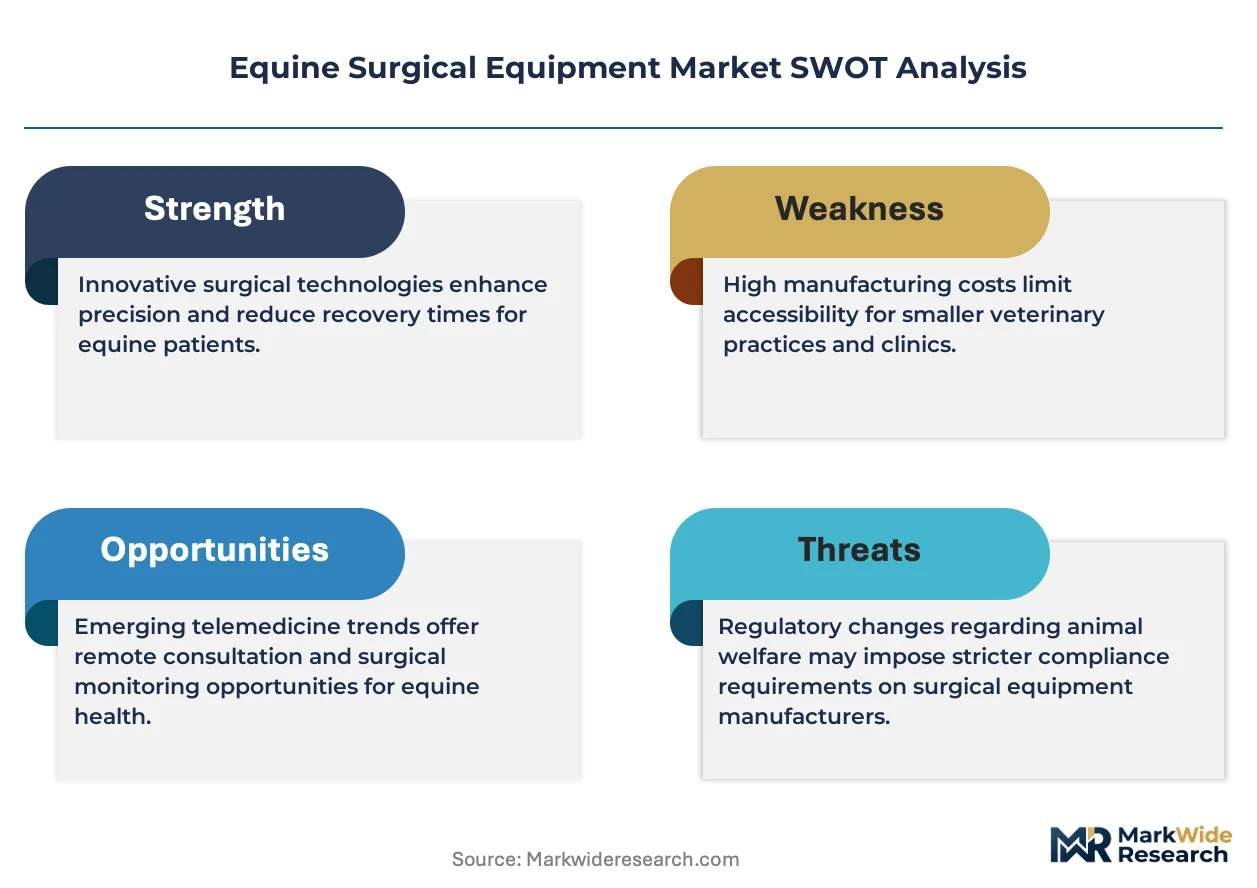
- ISO 13485 certification mandates:Quality system requirements across the EU Medical Device Regulation's veterinary spillover effects and Japan's PMDA alignment with JIS standards are elevating entry barriers that favor established suppliers with compliance infrastructure.
- Equine sports medicine expansion:Racing stables and performance horse facilities in the United States are procuring advanced arthroscopy suites and anesthesia delivery systems for injury management and career longevity protocols.
- Titanium alloy instrumentation:Material science advances enabling 40% weight reduction in handheld surgical kits are reducing surgeon fatigue during extended colic procedures and driving replacement cycles.
Market Restraints
- Surgical-grade stainless steel price volatility:Raw material input costs for instrument-grade alloys fluctuate with nickel and chromium commodity markets, compressing margin predictability for mid-tier manufacturers.
- FDA Center for Veterinary Medicine oversight complexity:Device safety claim substantiation requirements create multi-year approval timelines that deter smaller innovators from entering the United States market.
- Field-portable imaging substitution:High-resolution smartphone-connected ultrasound probes are capturing diagnostic cases previously requiring capital-intensive radiography suites in ambulatory practice settings.
Strategic Opportunities
- Brazilian equine breeding sector:ANVISA regulatory harmonization efforts and expanding thoroughbred operations in São Paulo state create whitespace for anesthesia systems and foal surgery instrumentation.
- Tele-surgery training networks:Convergence of haptic feedback interfaces with low-latency connectivity enables remote proctoring of arthroscopic techniques, opening subscription revenue streams for equipment vendors.
- Modular table design:Configurable operative platforms accommodating both standing sedation procedures and full general anesthesia are penetrating German university hospitals seeking throughput flexibility.
Industry Challenges
- Veterinary surgical residency capacity:Accredited training programs produce insufficient numbers of board-certified equine surgeons to absorb advanced technology deployment, creating adoption bottlenecks for complex capital equipment.
- Multi-jurisdiction certification timelines:Parallel FDA 510(k) veterinary pathways, EU MDR technical documentation, and PMDA quality management reviews extend product launch schedules by 18-24 months for multinational suppliers.
- Legacy instrument refurbishment economics:Third-party reconditioning services compete with OEM replacement sales, complicating aftermarket revenue modeling and warranty boundary enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equine Surgical Equipment Market |
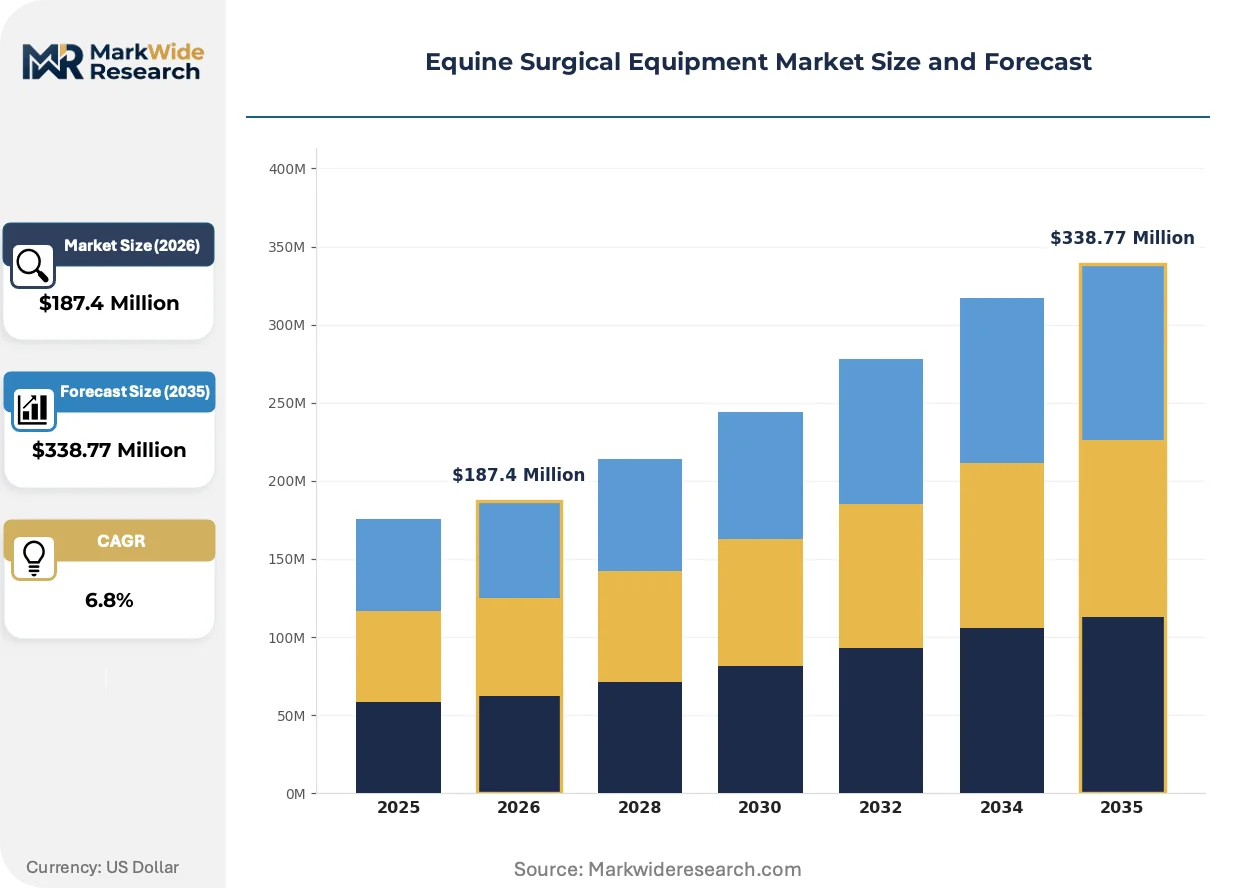
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Tables, Anesthesia Equipment, Surgical Instruments, Imaging Systems End User: Veterinary Clinics, Research Institutions, Animal Hospitals, Rehabilitation Centers Application: Orthopedic Surgery, Soft Tissue Surgery, Diagnostics, Emergency Surgeries Technology: Minimally Invasive, Robotic-Assisted, Laser Surgery, Traditional Surgery |
| Companies Covered | DePuy Synthes Vet, Eickemeyer Veterinary Equipment, Ethicon, Jorgensen Laboratories, Medtronic, IDEXX Laboratories, Integra LifeSciences, Jørgen Kruuse A/S, Haico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equine Surgical Equipment Market Evolving Landscape
Digital integration and material science advances are restructuring how surgical workflows are executed, monitored, and reimbursed across equine veterinary practice settings, with implications for equipment specification, training delivery, and capital allocation priorities.
Fluoroscopy-guided navigation systems are supplanting traditional blind needle placement in stifle arthroscopy procedures. University veterinary hospitals in Germany and Japan are deploying these platforms for meniscal repair and osteochondral fragment extraction. The technology is supplanting conventional instrument sets by enabling sub-millimeter accuracy that reduces iatrogenic cartilage damage and shortens rehabilitation protocols.
REACH substance restrictions on chromium(VI) compounds in surface treatment processes are compelling European instrument manufacturers to migrate toward citric acid passivation and electropolishing alternatives. The industrial consequence extends production cycle times by 15-20% while eliminating hexavalent chromium waste streams. German and Danish suppliers are responding by vertically integrating their finishing operations to control process consistency and documentation trails for notified body audits.
Leasing arrangements with bundled maintenance and training services are displacing outright capital purchases among independent equine practitioners. Distributors in the United States are consolidating their field service organizations to support this shift, replacing traditional equipment sales representatives with clinical application specialists. This transition is most visible in Texas and Kentucky where ambulatory surgical units require predictable cost structures aligned with seasonal cash flow patterns in breeding operations.
Equine Surgical Equipment Market Segmentation
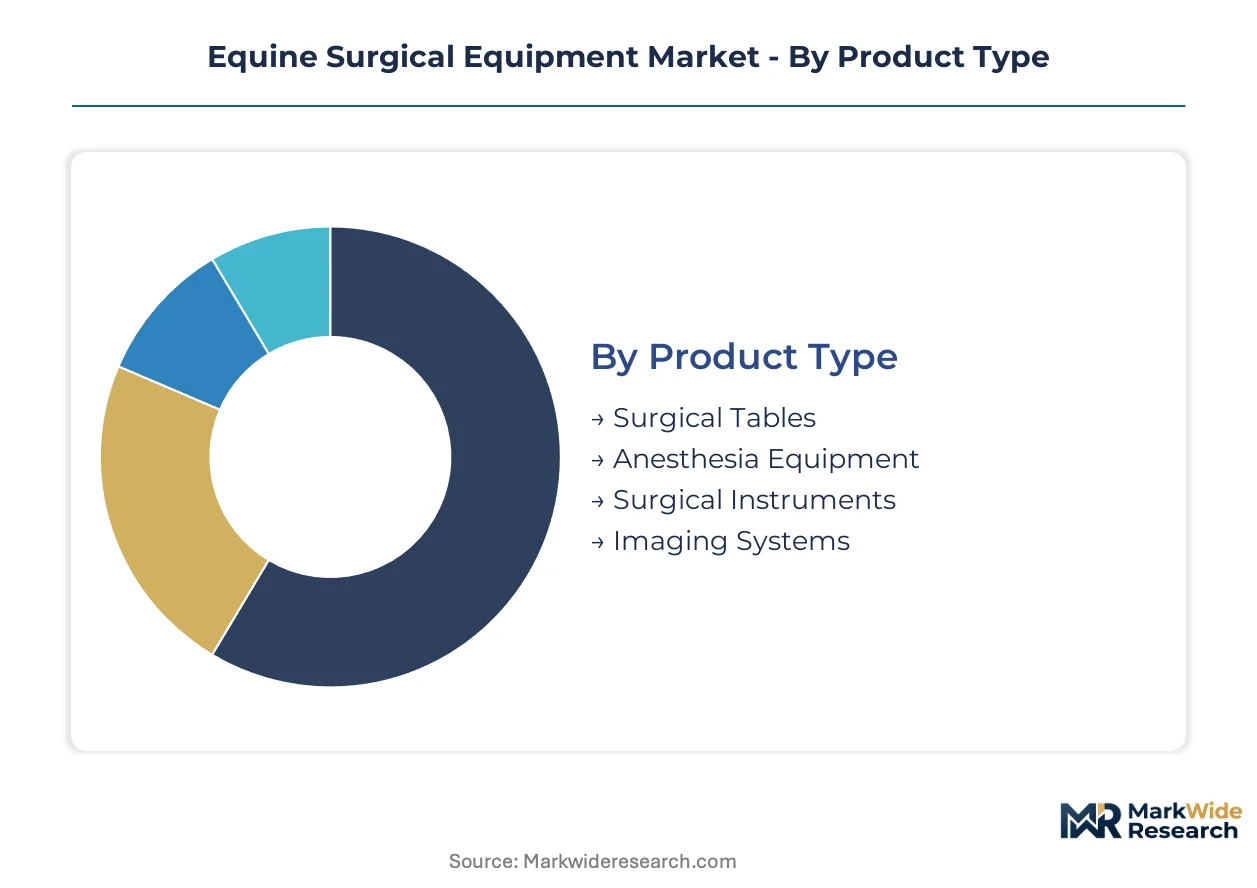
Segmentation in equine surgical equipment reveals how procurement priorities diverge between high-volume ambulatory practices and capital-intensive university hospitals. Understanding these splits enables suppliers to align R&D investment with the specific workflow constraints of each customer archetype.
Product Type:
Margin pools concentrate in instrument kits and anesthesia systems where replacement cycles and consumable attachments generate recurring revenue streams.
- Surgical Instruments:Handheld retractors, forceps, and needle holders fabricated from surgical-grade stainless steel or titanium alloys dominate procurement volumes. Racing stables in Kentucky and Texas prioritize lightweight titanium configurations to reduce surgeon fatigue during extended colic procedures.
- Anesthesia Equipment:Precision vaporizers and ventilator systems calibrated for 450-550 kg patients command premium positioning. German university hospitals are expanding procurement of multi-agent delivery platforms compatible with both inhalant and total intravenous protocols.
- Surgical Tables:Hydraulic and electric lift systems with Trendelenburg positioning support both standing sedation and general anesthesia workflows.
- Imaging Systems:Portable radiography and fluoroscopy units enable intraoperative guidance in field settings.
Surgical instruments hold installed capacity. Anesthesia equipment is rotating up the share rankings.
End User:
Volume concentration sits with multi-specialty facilities performing both elective and emergency procedures.
- Veterinary Clinics:Independent and group practices performing ambulatory surgery constitute the foundational demand layer. Clinics in São Paulo state are expanding surgical capabilities as Brazilian thoroughbred breeding operations professionalize.
- Animal Hospitals:Referral centers with 24-hour emergency capacity absorb the most complex capital equipment. Japanese animal hospitals are deploying robotic-assisted platforms for arthroscopic intervention in performance horses.
- Research Institutions:University veterinary hospitals drive technology validation and resident training.
- Rehabilitation Centers:Post-surgical recovery facilities require monitoring equipment and therapeutic modalities.
Animal hospitals dominate capital deployment. Veterinary clinics are expanding fastest as ambulatory surgery models proliferate.
Application:
Technology adoption intensity varies sharply between scheduled elective procedures and emergency interventions.
- Orthopedic Surgery:Arthroscopy and fracture repair procedures demand precision visualization and fixation systems. German and Japanese university hospitals are adopting fluoroscopy-guided navigation for stifle meniscal repair.
- Emergency Surgeries:Colic intervention and laceration repair require rapid instrument accessibility and mobile anesthesia delivery. Field-portable kits are penetrating Texas and Kentucky where ambulatory response times determine survival rates.
- Soft Tissue Surgery:Respiratory and gastrointestinal procedures utilize specialized retractor sets and stapling devices.
- Diagnostics:Arthroscopic exploration and biopsy sampling support pre-surgical planning.
Emergency surgeries anchor replacement instrument demand. Orthopedic surgery is climbing the fastest as sports medicine protocols expand.
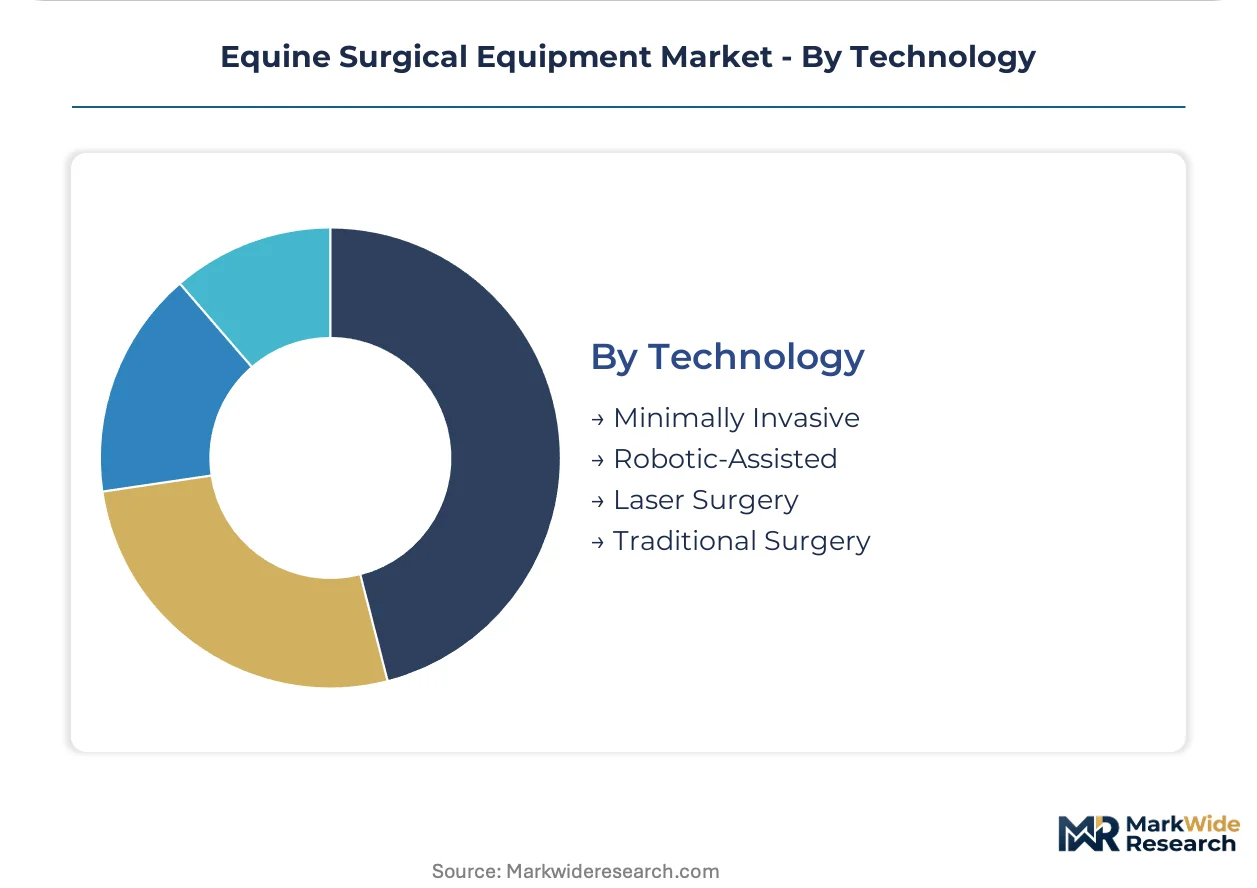
Technology:
Capital allocation patterns separate established workflow technologies from emerging platform investments.
- Robotic-Assisted:Haptic-enabled precision platforms are compressing the adoption curve for minimally invasive procedures. University veterinary hospitals in Germany and Japan are deploying these systems for sub-millimeter accuracy in fragment extraction.
- Minimally Invasive:Arthroscopy and laparoscopy equipment reduces tissue trauma and shortens rehabilitation. Racing stables are procuring video arthroscopy suites for career longevity protocols.
- Laser Surgery:Tissue ablation and cauterization systems serve specific soft tissue applications.
- Traditional Surgery:Open procedures with conventional instrument sets retain dominance in field settings and cost-constrained practices.
Traditional surgery maintains procedure volume leadership. Robotic-assisted technology is gaining share fastest as training infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equine surgical equipment procurement patterns diverge sharply between mature veterinary infrastructure markets and emerging breeding economies. The United States and Germany concentrate capital deployment in university hospital precision platforms, while Brazil and Japan represent contrasting adoption trajectories shaped by regulatory maturity and sports medicine investment cycles.
United States
Kentucky and Texas racing stables drive titanium instrument kit demand for colic intervention protocols. FDA Center for Veterinary Medicine oversight shapes device safety claim substantiation timelines for manufacturers seeking market entry. University veterinary hospitals in Lexington and Louisville deploy robotic-assisted arthroscopy platforms for performance horse orthopedic protocols.
Germany
German university hospitals prioritize fluoroscopy-guided navigation systems for stifle meniscal repair procedures. EU Medical Device Regulation veterinary spillover effects extend compliance documentation requirements across supply chains. The Hanover region concentrates equine surgical training infrastructure and instrument manufacturing finishing operations.
Japan
Japanese animal hospitals absorb capital-intensive robotic platforms for minimally invasive arthroscopic intervention in racehorses. PMDA alignment with JIS quality standards elevates certification burdens for imported equipment suppliers. The Hidaka district in Hokkaido anchors thoroughbred breeding operations driving surgical infrastructure investment.
Brazil
São Paulo state thoroughbred breeding professionalization expands demand for anesthesia systems and foal surgery instrumentation. ANVISA regulatory harmonization efforts reduce import pathway friction for multinational suppliers. The Campinas cluster concentrates veterinary distribution networks serving southeastern breeding operations.
United Kingdom
Newmarket racing industry investment sustains demand for portable imaging and emergency surgical kits. REACH substance restrictions on chromium(VI) compounds reshape instrument surface treatment supply chains for European manufacturers. The Cambridgeshire corridor hosts specialized veterinary equipment distributors serving national racing infrastructure.
Equine Surgical Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure in equine surgical equipment. The upper tier commands anesthesia system and imaging platform categories through bundled service architectures, while mid-cap specialists dominate handheld instrument customization for regional veterinary preferences. Three archetypes define positioning: diversified medical device conglomerates with veterinary divisions, pure-play equine instrument fabricators, and regional distributors with captive service organizations. Competitive moves concentrate on backward integration into titanium alloy finishing operations and tele-surgery training subscription models.
Within the pure-play specialist tier, Jørgen Kruuse A/S and Eickemeyer Veterinary Equipment occupy positions anchored in Scandinavian and Central European market knowledge. Ethicon represents the diversified conglomerate archetype, leveraging suture and wound closure heritage across soft tissue applications. These three companies exemplify how geographic origin and corporate structure shape competitive positioning without requiring scale-driven capital deployment.
| Leading Market Players |
|---|
| DePuy Synthes Vet |
| Eickemeyer Veterinary Equipment |
| Ethicon |
| Jorgensen Laboratories |
| Medtronic |
| IDEXX Laboratories |
| Integra LifeSciences |
| Jørgen Kruuse A/S |
| Haico |
| Others |
Value Network & Pricing Analysis
Titanium alloy substitution for surgical-grade stainless steel in handheld instrument fabrication is simultaneously relocating finishing operations toward German and Danish suppliers while compressing margin structures for mid-tier manufacturers dependent on nickel-chromium commodity exposure.
Pricing Analysis
Long-term offtake contracts with bundled maintenance and training services dominate capital equipment procurement, particularly among Kentucky and Texas racing stables seeking predictable cost structures aligned with seasonal breeding cash flows. Three-tier pricing structure across premium titanium configurations, standard stainless steel kits, and economy refurbished instruments separates university hospitals from ambulatory practitioners from cost-constrained field veterinarians. Cost compression in mid-tier stainless steel instruments is intensifying because REACH substance restrictions on chromium(VI) compounds have extended European production cycle times. Independent equine practitioners in São Paulo state exhibit highest price sensitivity, while Japanese animal hospitals deploying robotic-assisted platforms demonstrate lowest sensitivity due to performance horse revenue premiums.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors shape delivery economics for titanium alloy raw material shipments originating from Chinese and Russian smelters. Manufacturing concentration clusters in Germany, Denmark, and the United States, with finishing operations drawing from Scandinavian titanium sponge and German surgical steel forging capacity. Supply chain risk centers on single-source vulnerability for ISO 13485-certified precision vaporizer components sourced from specialized German suppliers. Distribution runs through veterinary equipment distributors with captive field service organizations, replacing traditional sales representative models with clinical application specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equine surgical equipment constitutes a defensive-moat market where regulatory entrenchment through multi-jurisdiction certification creates prohibitive switching costs for established suppliers.
For Market Incumbents: Compound defensive positioning through backward integration into titanium alloy finishing operations and captive tele-surgery training subscription platforms. Threats from smartphone-connected ultrasound substitution in diagnostic imaging demand preemptive bundling of fluoroscopy-guided navigation with instrument kit sales. Priority lever rests on expanding ISO 13485 compliance infrastructure to capture ANVISA harmonization benefits in Brazilian thoroughbred markets. For New Entrants and Emerging Players: Aftermarket refurbishment services for legacy instrument sets represent the most penetrable white-space where OEM warranty boundaries remain contested. Target São Paulo state veterinary clinics professionalizing surgical capabilities alongside expanding breeding operations. Go-to-market angle emphasizes modular table design accommodating both standing sedation and general anesthesia workflows, addressing throughput flexibility gaps in German university hospital procurement. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play equine instrument fabricators with deep regional market knowledge and established notified body audit trails. Long-term viability hinges on regulatory compliance infrastructure rather than scale-driven capital deployment. Signal to watch: PMDA-JIS alignment completion in Japan as inflection indicator for import pathway friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality system infrastructure captures EU MDR veterinary spillover effects and Japanese PMDA market access. |
| Tele-Surgery Training Platform Development | Haptic feedback subscription models create recurring revenue streams alongside capital equipment sales. |
| Titanium Alloy Backward Integration | In-house finishing operations control citric acid passivation consistency for REACH compliance documentation. |
| ANVISA Regulatory Harmonization | Brazilian import pathway alignment reduces launch timeline friction for anesthesia system suppliers. |
| Modular Table Design Launch | Configurable platforms penetrate German university hospitals seeking standing sedation and general anesthesia flexibility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equine veterinary surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) veterinary filings, EU MDR technical documentation databases, PMDA quality management registration records, and hospital procurement contract repositories. Bottom-up instrument kit demand modeling triangulated against top-down anesthesia system capital deployment tracking across university veterinary hospitals.
Across the analysis window, forecasts incorporate product type segmentation by instrument material grade, anesthesia delivery protocol compatibility, and imaging portability requirements; end-user segmentation by clinic, hospital, and research institution archetypes; and technology segmentation spanning traditional, minimally invasive, and robotic-assisted platforms. CAGRs were derived from replacement cycle analysis for handheld instruments and adoption curve modeling for capital-intensive platforms, incorporating veterinary surgical residency capacity constraints as a demand ceiling factor.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine oversight, EU Medical Device Regulation veterinary spillover effects, and Japanese PMDA-JIS alignment regimes; material policy shifts would require re-modeling. Specific risk factors include REACH substance restriction expansion, nickel-chromium commodity volatility, and field-portable imaging substitution acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Robotic Surgery Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Global Biopsy Needles Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market