
 Middle East and Africa Lancet and Pen Needles Market | 2026-2036
Middle East and Africa Lancet and Pen Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Lancet and Pen Needles Market Analytics
Pre-loaded pen needle cartridges and bundled lancet-plus-meter kits is pivoting how hospitals and homecare buyers evaluate total cost of ownership. Becton Dickinson and Company leverages its manufacturing scale to supply safety-engineered lancets across Gulf Cooperation Council tenders. Novo Nordisk A/S anchors insulin delivery ecosystems with proprietary pen needle compatibility that locks in recurring demand. Julphar competes on regional production proximity, reducing import lead times for North African health ministries.
Lancets and pen needles are sterile, single-use or limited-reuse piercing instruments manufactured from stainless steel or polymer substrates, typically 28–32 gauge in diameter, designed to extract capillary blood or deliver injectable drugs through subcutaneous tissue. Safety lancets dominate hospital procurement due to needlestick prevention mandates, while pen needles capture the fastest expansion as insulin pen adoption rises in diabetes management. Homecare channels now represent a concentrated margin pool as patients self-source higher-gauge, finer needles that reduce injection pain.
South Africa's Health Products Regulatory Authority, Saudi Food and Drug Authority, and Egypt's Drug Authority each enforce sterilization and biocompatibility standards that shape product registration timelines and manufacturing compliance costs. The EU Medical Device Regulation's extraterritorial influence on CE-marked imports further filters which suppliers gain market access across the region. Stakeholders must monitor harmonization between national regulators and Gulf Standardization Organization benchmarks to anticipate which product configurations will clear multi-country tenders.
Market Dynamics
The Middle East and Africa lancet and pen needles market is being fundamentally restructured by the migration of diabetes management from hospital settings to homecare environments, a shift that alters volume concentration, margin pools, and procurement authority across the value chain.
Growth Catalysts
- Saudi Arabia's Ministry of Health tender centralization:Consolidated public hospital procurement creates predictable demand blocks that incentivize suppliers to establish regional distribution hubs.
- South Africa's sterility enforcement:The Health Products Regulatory Authority's pre-sterilization mandates accelerate displacement of reusable lancets with single-use safety formats.
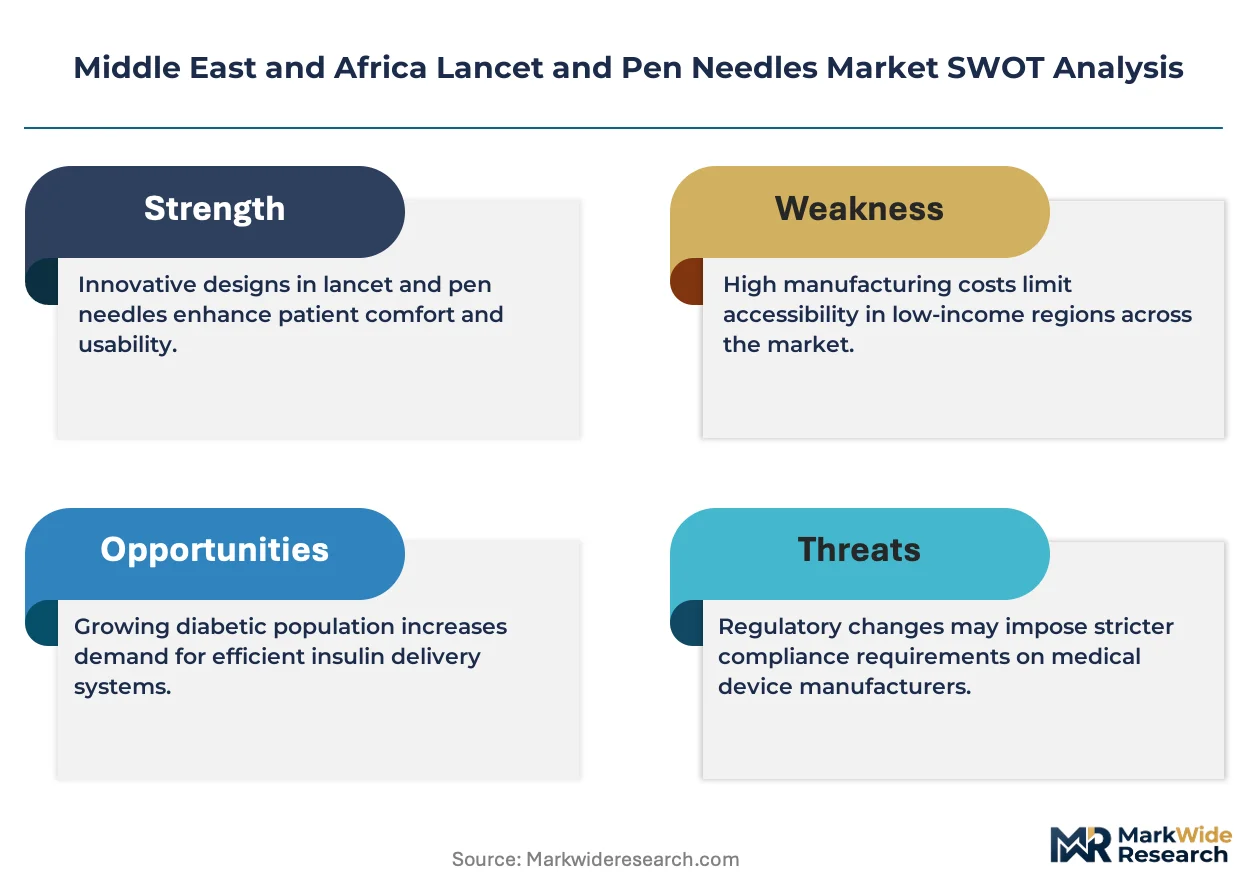
- Insulin pen ecosystem lock-in:Proprietary needle-to-pen compatibility creates recurring revenue streams as patient adherence programs expand across Gulf Cooperation Council states.
Market Restraints
- Import dependency concentration:Local manufacturing capacity for precision-gauge stainless steel remains concentrated in European and Asian supply bases, exposing buyers to currency volatility and shipping disruptions.
- Biocompatibility testing costs:Egypt's Drug Authority requires extended cytotoxicity validation timelines that extend product registration cycles by eight to fourteen months.
- Substitution pressure from insulin pumps:Continuous subcutaneous infusion systems reduce per-patient pen needle consumption among Type 1 diabetes cohorts in high-income Gulf markets.
Strategic Opportunities
- North African local production incentives:Julphar's manufacturing proximity to Egyptian and Moroccan health ministries creates template for regional supply base expansion.
- Bundled diagnostic kits:Lancet-plus-meter combinations capture pharmacy channel shelf space and reduce patient acquisition friction in South African retail networks.
- EU MDR extraterritorial alignment:CE-marked suppliers can leverage harmonized technical documentation to accelerate multi-country registration across Gulf Standardization Organization member states.
Industry Challenges
- Specialized polymer extrusion expertise:Thin-wall needle hub manufacturing requires precision molding capabilities scarce across the Middle East and Africa region.
- Multi-jurisdiction registration synchronization:Divergent sterilization validation requirements between Saudi Food and Drug Authority and South Africa's Health Products Regulatory Authority force redundant testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Lancet and Pen Needles Market |
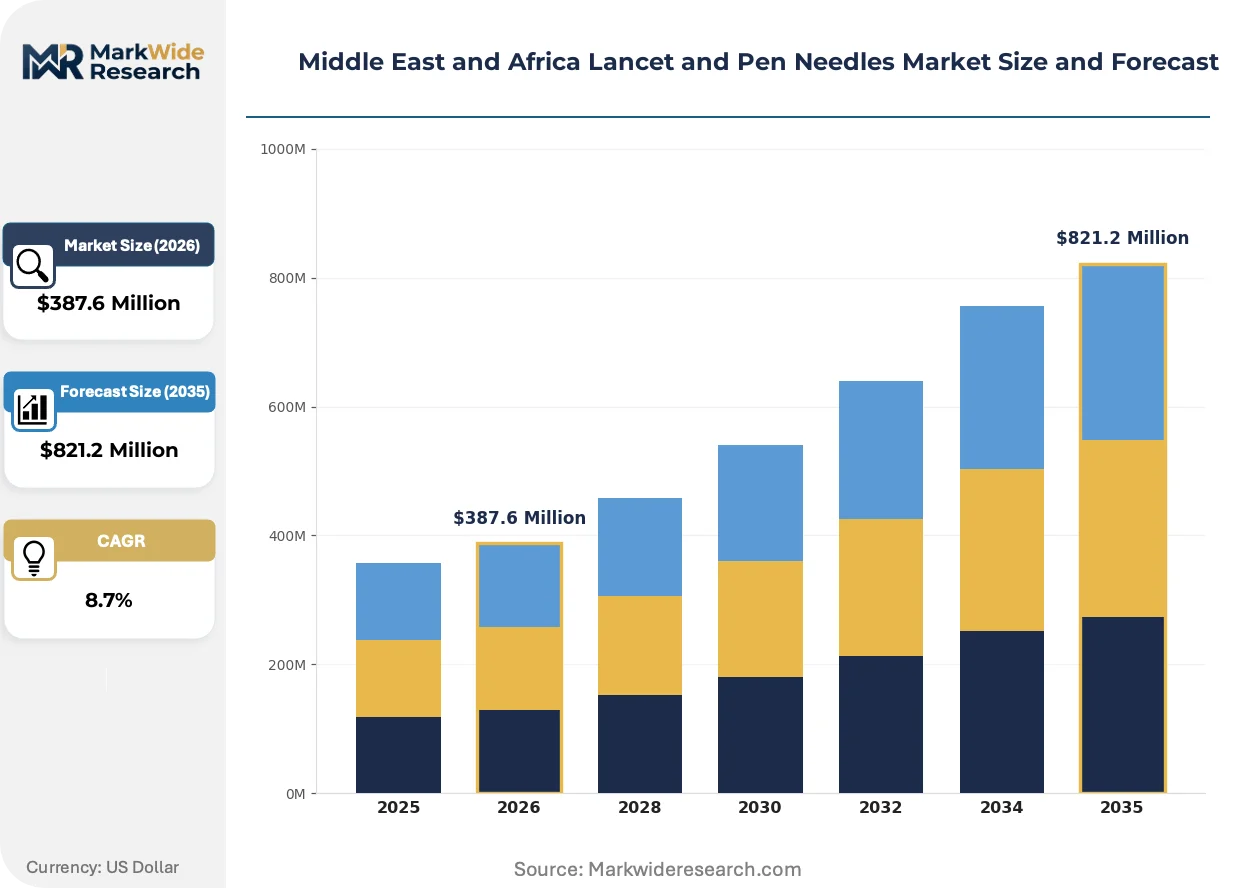
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Lancets, Safety Lancets, Pen Needles, Reusable Lancets End User: Hospitals, Diabetes Clinics, Homecare, Pharmacies Delivery Mode: Subcutaneous, Intramuscular, Intravenous, Transdermal Material: Stainless Steel, Polymer, Glass, Others |
| Companies Covered | Novo Nordisk A/S, Becton Dickinson and Company, Sanofi, Julphar, Ypsomed Holding AG, Terumo Corporation, B. Braun Melsungen, HTL-STREFA S.A., Owen Mumford, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Lancet and Pen Needles Market Evolving Landscape
Active materials science advancement and regulatory harmonization pressures are compressing product development cycles while elevating performance thresholds for penetration force and patient comfort metrics across the region.
Silicone-coated needle surfaces are converging with higher-gauge thinner-wall designs to reduce injection pain perception. Homecare patients in Saudi Arabia and the UAE are self-selecting 32-gauge needles despite premium pricing. This convergence is compressing the addressable market for standard 29-gauge hospital-contract SKUs.
Gulf Standardization Organization benchmarks for single-use safety-engineered sharps are reshaping tender specifications across GCC public health systems. Manufacturers must now demonstrate integrated needlestick prevention mechanisms to qualify for Ministry of Health contracts. Egyptian and Jordanian suppliers are retrofitting production lines to meet these mechanical safety requirements.
Patient self-sourcing through retail pharmacies is displacing institutional procurement as the dominant volume channel for pen needles. Hospital discharge protocols in South Africa now include take-home prescriptions that route demand to retail rather than clinical replenishment. This behavioral shift concentrates margin capture with pharmacy chains in Johannesburg and Cape Town metropolitan clusters.
Middle East and Africa Lancet and Pen Needles Market Segmentation
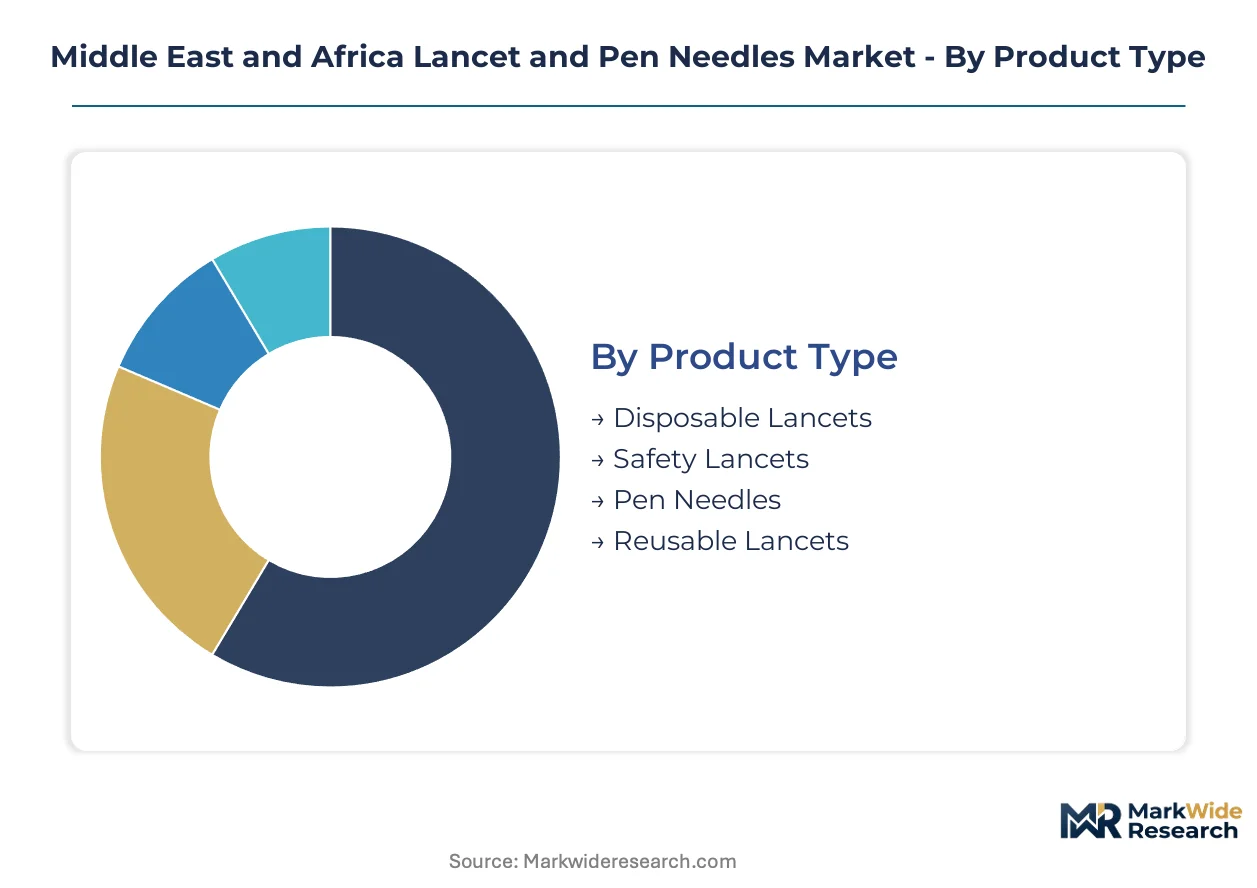
Segmentation in the Middle East and Africa lancet and pen needles market reveals how procurement authority, sterility requirements, and patient self-management behaviors split volume across divergent channels and product formats. Understanding these divisions exposes where margin pools concentrate and which specifications determine tender eligibility.
Product Type:
Supply concentration for precision-manufactured piercing instruments varies sharply across sterilization requirements and safety engineering complexity.
- Safety Lancets:These single-use devices integrate spring-loaded retraction mechanisms and needlestick prevention guards. South Africa's Health Products Regulatory Authority mandates their use in public hospitals, creating predictable demand blocks that favor suppliers with regional distribution hubs.
- Pen Needles:Thin-wall stainless steel cannulas paired with polymer hubs, typically 28–32 gauge, designed for insulin pen compatibility. Saudi Arabia's Ministry of Health tenders concentrate procurement of these units as diabetes prevalence rises and insulin pen ecosystems expand across Gulf Cooperation Council states.
- Disposable Lancets:Simple twist-top or pressure-activated designs without integrated safety mechanisms. Retail pharmacy chains in Johannesburg and Cape Town metropolitan clusters stock these for price-sensitive homecare patients.
- Reusable Lancets:Metal-bodied devices with replaceable lancet cartridges. Egypt's Drug Authority registration requirements and sterilization validation timelines have compressed their addressable market to specialized diabetes clinics with in-house sterilization capacity.
Safety lancets absorb the bulk of installed capacity; pen needles are expanding most quickly.
End User:
Cost tier differentiation separates institutional procurement with volume discounts from retail channels where patients self-source premium specifications.
- Homecare:Individual patients purchasing through retail pharmacies, increasingly selecting 32-gauge pen needles and bundled lancet-plus-meter kits despite premium pricing. Hospital discharge protocols in South Africa now route replenishment demand to this channel rather than clinical procurement.
- Hospitals:Consolidated public health system tenders across Saudi Arabia and South Africa specify safety-engineered formats and pre-sterilized disposable units. Gulf Standardization Organization benchmarks for needlestick prevention mechanisms determine contract eligibility.
- Diabetes Clinics:Specialized outpatient facilities in Cairo, Casablanca, and Nairobi requiring consistent supply of standard-gauge lancets for capillary blood extraction. Julphar's regional manufacturing proximity reduces import lead times for North African clinic networks.
- Pharmacies:Retail distribution points capturing concentrated margin pools as patient self-sourcing displaces institutional procurement. Metropolitan pharmacy chains in Gulf Cooperation Council states stock higher-gauge SKUs that reduce injection pain perception.
Hospitals dominate current procurement volume; homecare is climbing the fastest as diabetes management migrates from clinical settings.
Delivery Mode:
Application requirements dictate gauge selection, needle length, and hub design specifications across therapeutic categories.
- Subcutaneous:Primary delivery mode for insulin administration, using 4–6mm pen needle lengths. This segment captures the majority of pen needle consumption as basal and bolus insulin regimens expand across the region.
- Intramuscular:Longer needle lengths with 90-degree insertion angles for certain GLP-1 receptor agonist formulations. Demand concentrates in hospital settings with trained clinical administration.
- Intravenous:Specialized applications requiring precise penetration depth control. Limited penetration in lancet and pen needle markets due to alternative vascular access device availability.
- Transdermal:Emerging microneedle and micro-puncture applications for vaccine delivery and biosensing. Regulatory frameworks remain under development across Middle East and Africa pharmaceutical authorities.
Subcutaneous delivery absorbs the bulk of installed capacity; transdermal applications are gaining share fastest among next-generation delivery research programs.
Material:
Volume concentration and margin structure diverge between precision metal forming and polymer extrusion capabilities.
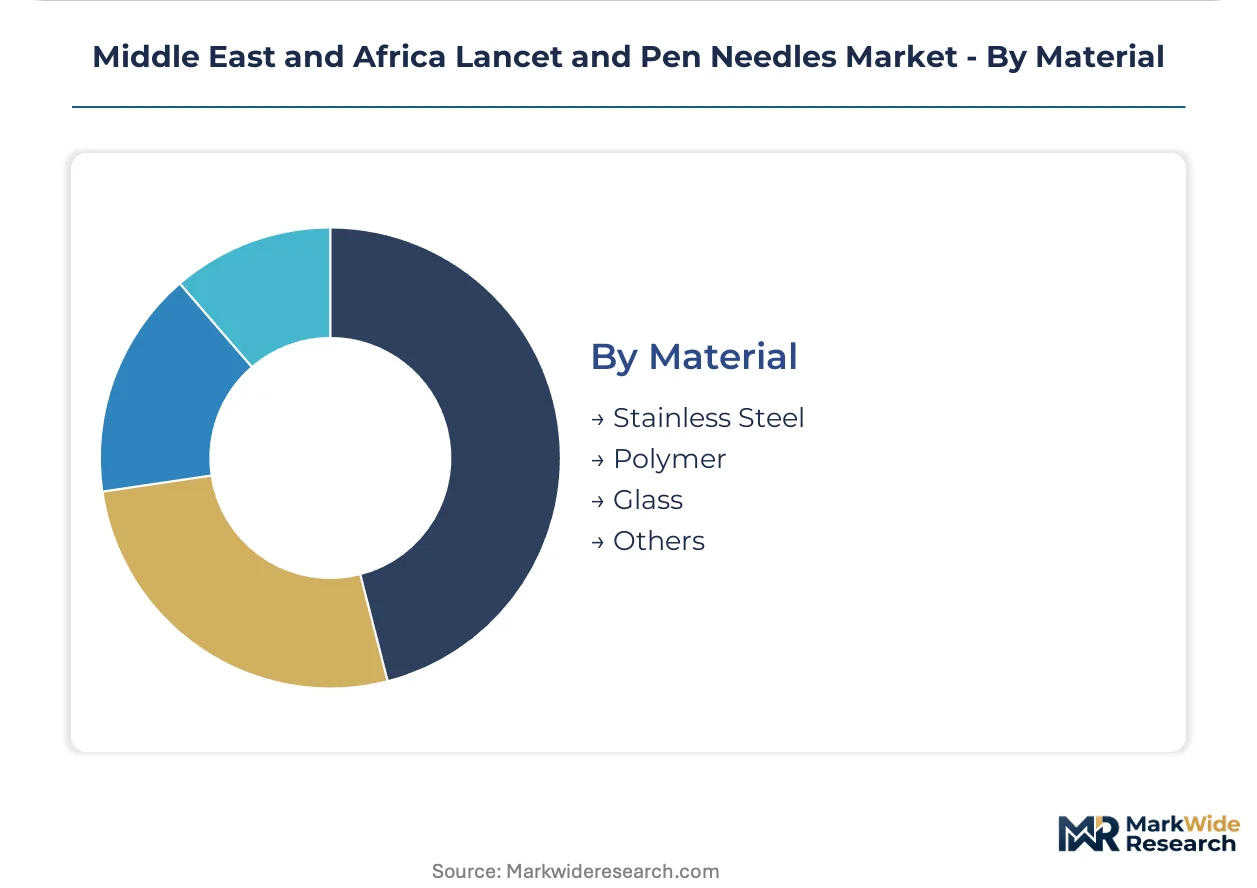
- Stainless Steel:Medical-grade 304 and 316L alloys for cannula fabrication, requiring specialized grinding and electropolishing equipment. Import dependency from European and Asian supply bases exposes regional buyers to currency volatility.
- Polymer:Polypropylene and polycarbonate hub materials with silicone lubricant coatings to reduce penetration force. Thin-wall precision molding capabilities remain scarce across the Middle East and Africa region.
- Glass:Limited to specialized capillary tube applications in laboratory settings. Fragility constraints prevent adoption in patient-facing lancet or pen needle formats.
- Others:Composite materials and experimental biodegradable substrates under evaluation for sustainability-aligned procurement criteria in select Gulf Cooperation Council pilot programs.
Stainless steel absorbs the bulk of installed capacity; polymer formulations are expanding most quickly as silicone-coated higher-gauge designs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City's healthcare logistics zone concentrates import distribution for pen needles serving Saudi Arabia's western provinces. This tax-advantaged hub reduces customs clearance cycles for medical device shipments entering Red Sea ports.
Saudi Arabia
Ministry of Health tender centralization creates predictable demand blocks exceeding regional peers. The Saudi Food and Drug Authority enforces Gulf Standardization Organization needlestick prevention benchmarks that filter supplier eligibility. Riyadh's hospital procurement consortiums aggregate volume for safety-engineered lancets across public health networks.
South Africa
Health Products Regulatory Authority sterility mandates accelerate displacement of reusable formats with single-use safety lancets. The national tender system consolidates public hospital procurement through centralized adjudication. Johannesburg and Cape Town metropolitan pharmacy chains capture concentrated margin pools as hospital discharge protocols route replenishment demand to retail channels.
United Arab Emirates
MOHAP registration requirements align with EU Medical Device Regulation technical documentation standards, accelerating multi-country clearance for CE-marked suppliers. Dubai's healthcare free zones host regional distribution hubs serving Gulf Cooperation Council states. Abu Dhabi's diabetes management programs expand insulin pen ecosystem adoption among Emirati patient cohorts.
Egypt
Egypt's Drug Authority imposes extended cytotoxicity validation timelines that compress competitive windows for new entrants. Cairo's specialized diabetes clinics require consistent supply of standard-gauge lancets for capillary blood extraction. Regional manufacturing proximity from UAE-based producers reduces import lead times for North African health ministries.
Morocco
Ministry of Health procurement reforms favor pre-sterilized disposable formats in public hospital tenders. Casablanca's clinic networks source lancets through regional distributors with Maghreb-wide logistics coverage. The national pharmaceutical regulator harmonizes biocompatibility standards with Gulf Standardization Organization benchmarks to facilitate cross-border supplier qualification.
Middle East and Africa Lancet and Pen Needles Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels and product specifications. The market structure concentrates around multinational medical device manufacturers with established Gulf Cooperation Council distribution infrastructure and regional pharmaceutical producers leveraging manufacturing proximity. Three archetypes dominate: global diversified medical technology conglomerates with safety-engineered portfolios, European diabetes care specialists with proprietary pen needle ecosystems, and regional pharmaceutical manufacturers with North African production bases. Competitive moves center on tender qualification through regulatory harmonization and regional hub establishment to reduce import lead times.
Within the diversified medical technology tier, Becton Dickinson and Company and Terumo Corporation exemplify scale-driven supply positions across Gulf public health tenders. Novo Nordisk A/S anchors the proprietary ecosystem archetype through insulin delivery compatibility that locks in recurring demand. Julphar occupies the regional production position, leveraging UAE manufacturing proximity to serve Egyptian and Moroccan health ministry procurement cycles with reduced shipping disruption exposure.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Becton Dickinson and Company |
| Sanofi |
| Julphar |
| Ypsomed Holding AG |
| Terumo Corporation |
| B. Braun Melsungen |
| HTL-STREFA S.A. |
| Owen Mumford |
| Others |
Value Network & Pricing Analysis
Silicone-coated 32-gauge needle surfaces are compressing cost economics across manufacturing tiers while simultaneously redistributing supply concentration toward European and Asian precision-extrusion specialists capable of thin-wall polymer hub fabrication. This technological convergence forces Middle East and African buyers to absorb currency-adjusted premiums for higher-gauge SKUs or accept longer lead times from regional distributors with limited molding capabilities.
Pricing Analysis
Short lead time premiums of fifteen to twenty percent above spot inventory pricing dominate tender negotiations for Ministry of Health contracts across Gulf Cooperation Council states. Three-tier pricing structure across premium, standard, and economy levels separates silicone-coated 32-gauge hospital discharge prescriptions from uncoated 29-gauge institutional SKUs and twist-top disposable lancets in Johannesburg pharmacy chains. Cost compression in standard-gauge pen needles is intensifying because Egyptian and Moroccan health ministries are consolidating volume through centralized adjudication. Retail homecare patients selecting bundled lancet-plus-meter kits exhibit lowest price sensitivity; public hospital procurement committees in South Africa demonstrate highest sensitivity due to national tender budget caps.
Supply Chain Analysis
CE marking and Gulf Standardization Organization needlestick prevention qualification gates filter supplier eligibility for Saudi Arabia's Ministry of Health tenders, compressing qualified vendor pools to established multinationals with harmonized technical documentation. Precision stainless steel cannula fabrication concentrates in Germany, Japan, and South Korea; polymer hub extrusion and silicone coating capabilities center on Switzerland and the United States. Raw material dependencies span medical-grade 316L alloy feedstock, polypropylene resin, and pharmaceutical-grade silicone lubricants. Single-source vulnerability in thin-wall molding equipment exposes regional distributors to twelve-to-eighteen month capacity expansion delays. Distribution runs through King Abdullah Economic City's healthcare logistics zone for Red Sea port entry, then fragments to national tender administrators and metropolitan pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Medical Device Regulation extraterritorial influence and Gulf Standardization Organization safety-engineering benchmarks erect barrier-to-entry moats favoring incumbents with pre-existing CE-marked documentation and regional distribution infrastructure.
For Market Incumbents: To counter insulin pump substitution pressure in high-income Gulf diabetes cohorts, deepen proprietary pen needle ecosystem lock-in through expanded patient adherence program sponsorship across Ministry of Health hospital discharge protocols. Anchor backward integration into silicone coating application capabilities to capture margin compression from European specialty chemical suppliers. For New Entrants and Emerging Players: Capture white-space in North African local production incentives by establishing precision molding partnerships with Julphar's existing UAE manufacturing footprint to serve Egyptian and Moroccan health ministry procurement cycles with reduced shipping disruption exposure. Penetrate South Africa's retail pharmacy channel through bundled diagnostic kit offerings that reduce patient acquisition friction in Johannesburg and Cape Town metropolitan clusters. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking Gulf Cooperation Council tender qualification through regulatory harmonization assets. Five-to-ten year viability favors suppliers with demonstrated CE-marked portfolio breadth and established King Abdullah Economic City distribution presence. Monitor insulin pump penetration rates in Saudi Arabia and UAE as inflection indicator for pen needle consumption trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Gulf Standardization Organization Compliance Investment | Qualification for Saudi Ministry of Health tender blocks exceeds regional peer access. |
| Regional Distribution Hub Establishment | King Abdullah Economic City logistics zones reduce customs clearance cycles for Red Sea entry. |
| Silicone Coating Capability Integration | Captures margin from European specialty chemical suppliers while improving patient comfort metrics. |
| Patient Adherence Program Expansion | Locks in recurring pen needle demand through proprietary ecosystem compatibility. |
| CE Marking Pathway Acceleration | Leverages EU MDR technical documentation for multi-country registration across GCC states. |
Research Methodology
Multi-period observation of tender award patterns, product registration timelines, and patient self-sourcing channel migration anchored the trend analysis, supplemented by interviews with hospital procurement managers, biomedical engineers at diabetes clinics, pharmacy chain category buyers, and regulatory affairs specialists at national pharmaceutical authorities. Secondary validation drew from Saudi Food and Drug Authority filings, South Africa's Health Products Regulatory Authority registration databases, Gulf Standardization Organization benchmark publications, and EU Medical Device Regulation technical documentation repositories. Bottom-up volume triangulation across end-user segments reconciled with top-down market sizing from import trade data and distributor shipment records.
Input-output matrices modeled penetration rates across safety lancet, pen needle, and disposable lancet product types by homecare, hospital, diabetes clinic, and pharmacy channels throughout the forecast period. Segmentation dimensions included gauge specification, sterilization format, delivery mode, and material substrate alongside geographic regulatory cluster alignment. CAGRs were derived from fitted growth curves calibrated to tender volume aggregation patterns and patient cohort expansion trajectories. Forecast inputs incorporated insulin pen ecosystem adoption rates, needlestick prevention mandate implementation timelines, and retail pharmacy channel share displacement from institutional procurement.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to insulin pump substitution acceleration, currency volatility in Egyptian and South African import markets, and harmonization gaps between national regulators and Gulf Standardization Organization benchmarks. A model refresh is warranted upon material change in Saudi Arabia's Ministry of Health tender centralization pace or EU Medical Device Regulation extraterritorial enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Special Purpose Needles Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Global Veterinary Surgical Instruments Market