
 Endoscopic Spinal Surgery Market | 2026-2036
Endoscopic Spinal Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Spinal Surgery Market Analysis
High-definition visualization standards is redrawing competitive boundaries in endoscopic spinal surgery. Stryker Corporation leverages its integrated imaging portfolio to anchor premium system placements across North American hospital networks. Karl Storz competes through rigid endoscope specialization, while Joimax GmbH dominates the full-endoscopic access segment with dedicated spinal instrumentation.
Endoscopic spinal surgery employs tubular retractor systems, fiber-optic cameras, and specialized shavers to access the spinal canal through sub-centimeter portals, reducing paraspinal muscle disruption and enabling same-day discharge protocols. The procedure serves herniated disc decompression, stenosis relief, and targeted tumor resection where tissue preservation determines recovery velocity. Visualization systems command the highest margin pools as 4K and 3D imaging modalities displace standard-definition platforms in tertiary hospitals. Ambulatory surgery centers represent the fastest-growing end-user channel as payors shift elective spine procedures away from inpatient settings. Minimally invasive technology leads procedure volume, though robotic-assisted navigation is gaining traction in complex revision cases.
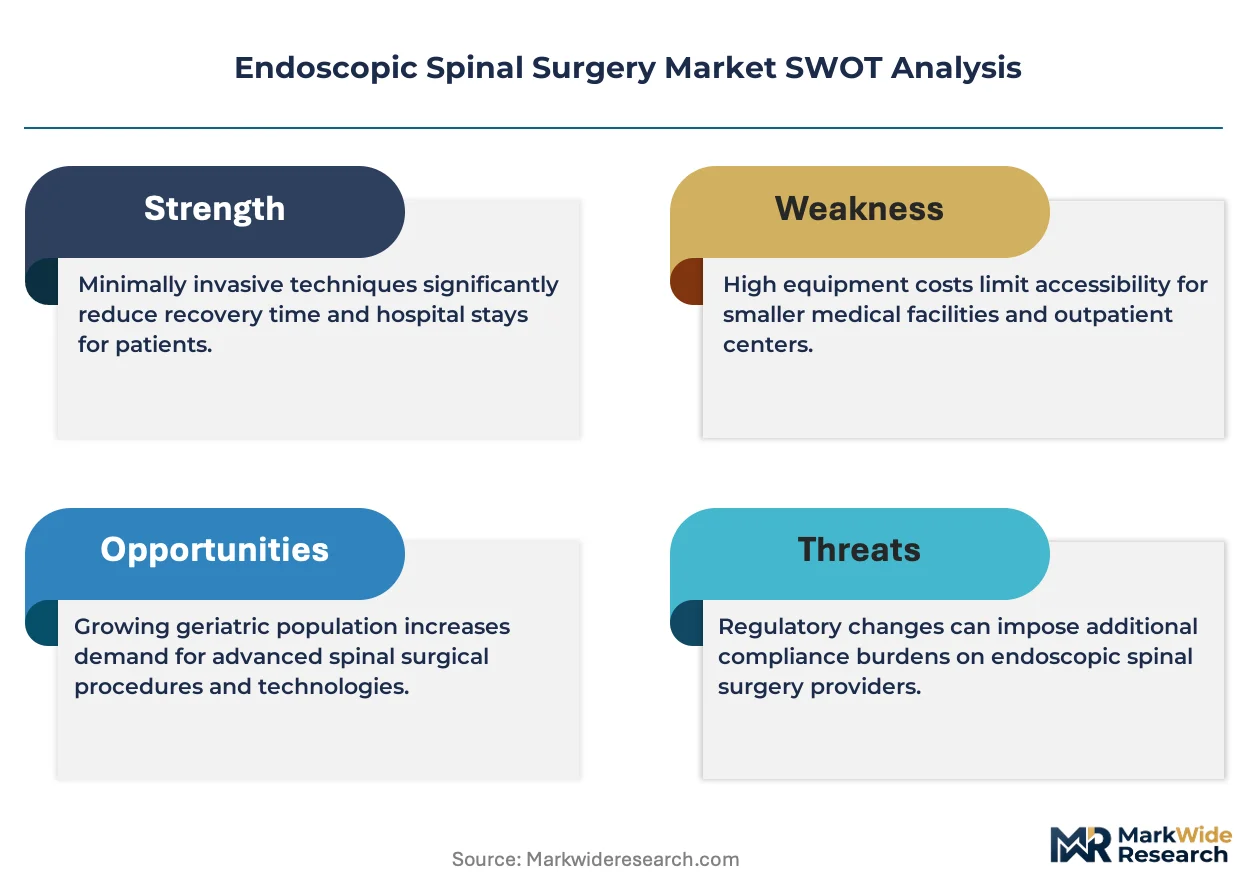
FDA 510(k) clearance pathways govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for spinal implant systems in Europe. Japan's PMDA maintains distinct technical documentation standards that delay market entry for foreign visualization platforms. Stakeholders must monitor reimbursement coding decisions for outpatient endoscopic discectomy, as coverage determinations will dictate capital deployment across ambulatory and hospital-based delivery models.
Market Dynamics
Reimbursement migration from inpatient to ambulatory settings is compressing procedure economics and forcing capital deployment toward outpatient-compatible visualization platforms. This structural shift privileges equipment footprints that integrate with same-day discharge protocols.
Growth Catalysts
- CMS outpatient reimbursement expansion:The Centers for Medicare and Medicaid Services has elevated ambulatory surgery center payment rates for endoscopic discectomy, redirecting case volume from hospital operating rooms.
- 4K imaging modality penetration:German hospital networks are standardizing ultra-high-definition visualization systems to reduce revision rates and accelerate surgeon training curves.
- Paraspinal muscle preservation protocols:Same-day discharge requirements are concentrating demand for tubular retractor systems that minimize tissue disruption and postoperative opioid dependence.
Market Restraints
- Capital equipment intensity:High-definition camera consoles and dedicated spinal endoscopes require seven-figure capital commitments that strain ambulatory surgery center balance sheets.
- Surgeon training pipeline constraints:Fellowship programs produce fewer than two hundred spine-focused endoscopists annually in the United States, creating procedural capacity ceilings.
- EU MDR clinical evidence requirements:The European Union Medical Device Regulation mandates extended follow-up data for spinal implant systems, delaying product launches by eighteen to thirty-six months.
Strategic Opportunities
- Japanese tertiary hospital networks:PMDA technical documentation standardization has created first-mover advantages for visualization platforms that complete local compliance early.
- Robotic navigation convergence:Integration of optical tracking with endoscopic access is opening complex revision cases previously excluded from minimally invasive approaches.
- Subscription-based equipment financing:Per-procedure leasing models are unlocking ambulatory surgery center adoption without upfront capital expenditure.
Industry Challenges
- Biocompatibility certification timelines:FDA 510(k) pathway documentation for novel polymer retractor materials extends clearance cycles and compresses commercialization windows.
- Legacy EMR integration friction:Visualization system data outputs require custom interface development to populate hospital electronic medical record fields, delaying deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopic Spinal Surgery Market |
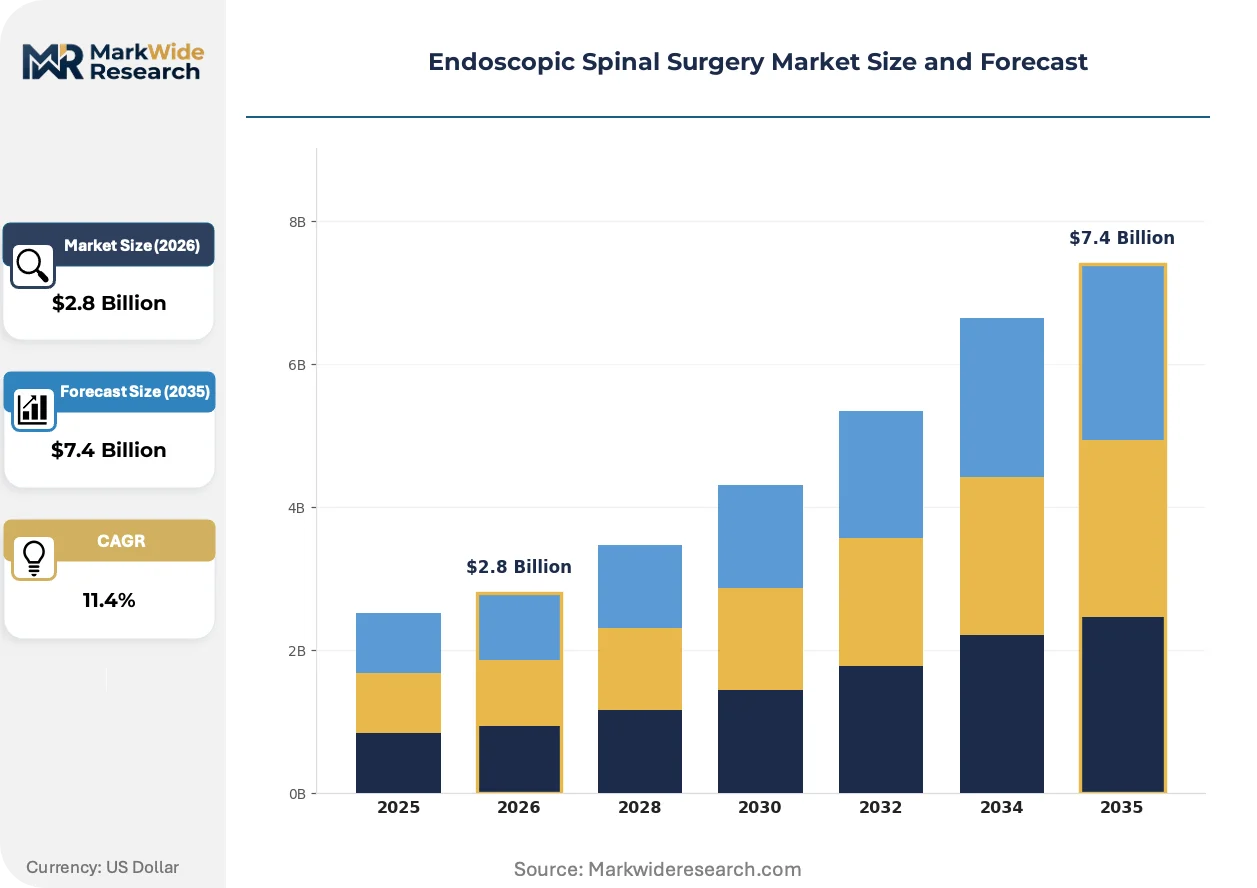
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Surgical Instruments, Visualization Systems, Accessories Application: Discectomy, Foraminotomy, Spinal Fusion, Tumor Removal End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Institutions Technology: Minimally Invasive, Robotic Surgery, 3D Imaging, Imaging Modalities |
| Companies Covered | Stryker Corporation, Karl Storz, Medtronic, Zimmer Biomet, NuVasive, Johnson & Johnson (DePuy Synthes), Joimax GmbH, B. Braun Melsungen AG, Globus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Spinal Surgery Market Emerging Trajectories
Visualization fidelity and procedural setting economics are the dual axes of technical competition. Equipment manufacturers are racing to compress system footprints while expanding imaging resolution, anticipating ambulatory surgery center procurement criteria.
Single-use endoscope sheaths are decomposing capital-intensive sterilization infrastructure requirements. Ambulatory surgery centers in Florida and Texas are adopting disposable optical channels to eliminate reprocessing bottlenecks and reduce infection liability exposure. This technology is decomposing the traditional hospital-centric supply relationship by enabling standalone facility independence from centralized sterile processing.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing serialization investments across spinal instrumentation portfolios. Manufacturers must now embed traceable identifiers into every tubular retractor and specialized shaver, raising production costs but enabling post-market surveillance granularity. German distributors are responding by consolidating supplier relationships to reduce compliance administration burden.
Surgeon preference for integrated visualization-plus-instrumentation systems is consolidating procurement decisions. Hospital materials management departments are bundling camera consoles with dedicated spinal access kits, displacing standalone component purchasing. This concentration is most visible in North Carolina and Ohio health systems, where standardization committees are mandating single-vendor endoscopy platforms to reduce training variability and spare parts inventory complexity.
Endoscopic Spinal Surgery Market Segmentation
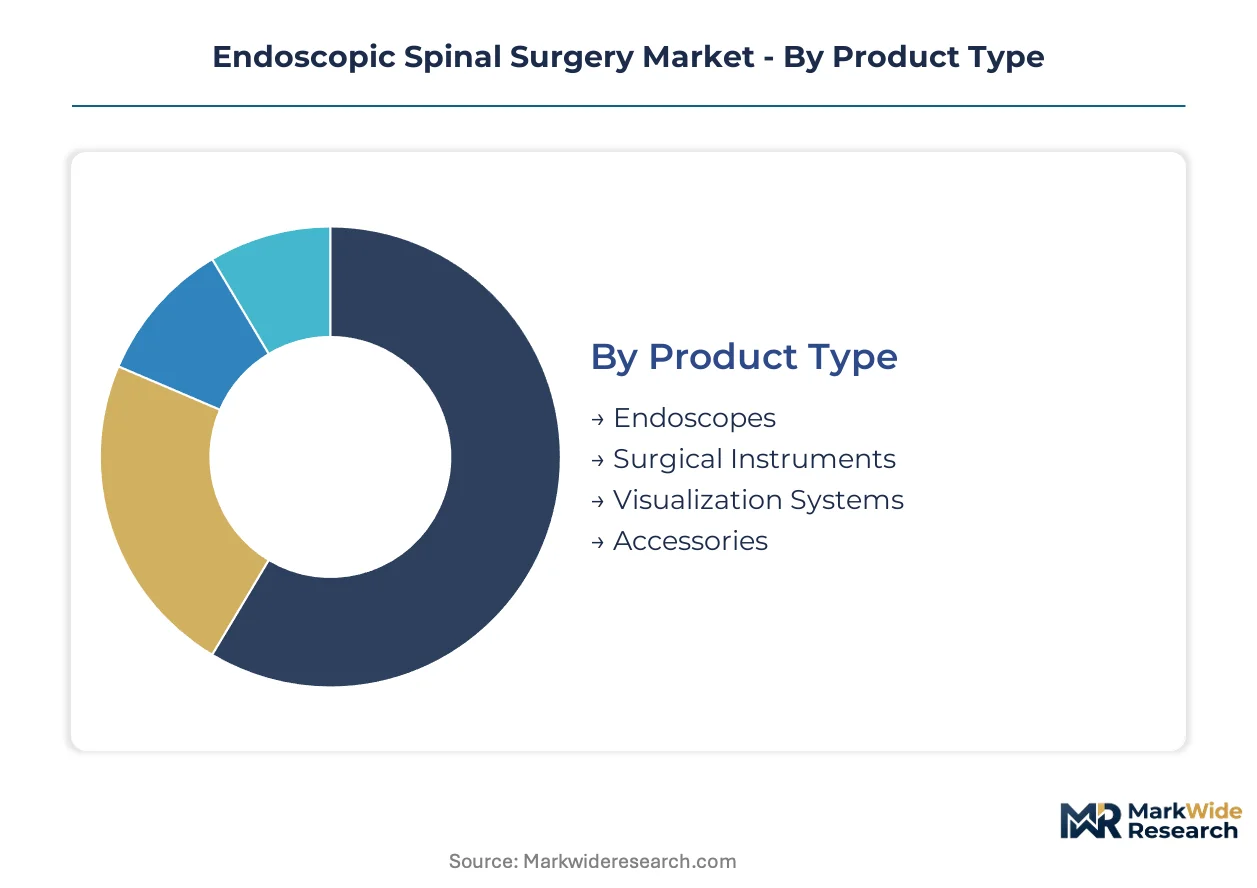
Endoscopic spinal surgery equipment flows through distinct procurement channels shaped by capital intensity, procedure volume, and reimbursement economics. Understanding how product types, applications, and technologies concentrate across delivery settings reveals where margin pools and growth trajectories diverge.
Product Type:
Visualization systems and endoscopes move through hospital networks with centralized sterile processing, while accessories and disposable instruments penetrate ambulatory surgery centers seeking to eliminate reprocessing infrastructure.
- Endoscopes:Rigid fiber-optic and rod-lens systems deliver sub-millimeter resolution through tubular retractor channels. German hospital networks are standardizing 4K-compatible platforms to reduce revision rates and accelerate fellowship training curves.
- Surgical Instruments:Specialized shavers, punches, and graspers designed for sub-centimeter portal access. Ambulatory surgery centers in Florida and Texas are adopting single-use instrument kits to bypass centralized sterilization dependencies and compress case turnaround times.
- Visualization Systems:Camera consoles and image processing units commanding premium pricing in tertiary hospitals.
- Accessories:Disposable sheaths, irrigation tubing, and electrocautery probes enabling standalone facility independence.
Visualization systems dominate installed base. Accessories are where expansion concentrates.
Application:
Procedure complexity determines reimbursement tier and capital equipment requirements, with simple decompression cases migrating fastest to outpatient settings while fusion and revision surgeries remain hospital-anchored.
- Discectomy:Herniated nucleus pulposus removal through transforminal or interlaminar approaches. CMS outpatient reimbursement expansion is redirecting case volume from hospital operating rooms to ambulatory surgery centers in the United States.
- Foraminotomy:Lateral recess and neural foraminal decompression preserving segmental stability. Japanese tertiary hospitals are integrating optical tracking to expand minimally invasive candidacy for stenotic elderly patients.
- Spinal Fusion:Instrumented stabilization requiring biologics and interbody cages. EU MDR clinical evidence mandates are delaying implant system launches by eighteen to thirty-six months.
- Tumor Removal:Intradural and extradural lesion resection demanding intraoperative neuromonitoring.
Discectomy commands procedure volume. Foraminotomy is climbing the fastest as aging demographics expand stenosis prevalence.
End User:
Capital deployment constraints and reimbursement coding decisions are fragmenting procurement authority between health system standardization committees and independent ambulatory facility operators.
- Hospitals:Tertiary and community institutions with fellowship training programs and complex revision capabilities. North Carolina and Ohio health systems are mandating single-vendor endoscopy platforms to reduce spare parts inventory complexity.
- Ambulatory Surgery Centers:Standalone facilities capturing CMS outpatient payment rate elevations for endoscopic discectomy. Subscription-based equipment financing is unlocking adoption without seven-figure upfront capital commitments.
- Specialty Clinics:Spine-focused practices with in-office procedure suites.
- Research Institutions:Academic medical centers generating clinical evidence for regulatory submissions.
Hospitals retain complex case concentration. Ambulatory surgery centers are gaining share fastest in elective decompression procedures.
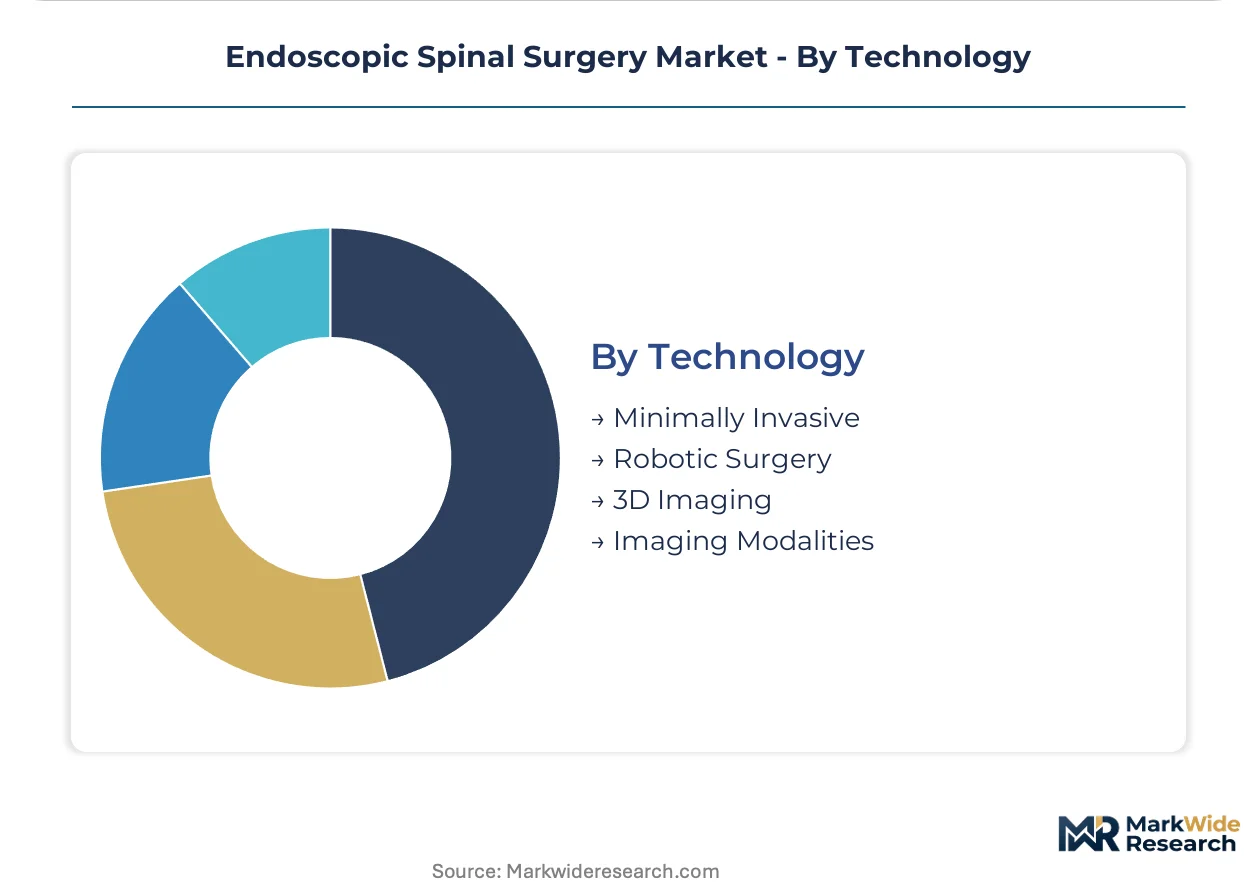
Technology:
Imaging fidelity and navigational precision are the dual axes of competitive differentiation, with manufacturers racing to compress system footprints while expanding resolution and optical tracking integration.
- Minimally Invasive:Tubular retractor systems and sub-centimeter portal access preserving paraspinal musculature. Same-day discharge protocols are concentrating demand for tissue-preserving approaches that minimize postoperative opioid dependence.
- Robotic Surgery:Optical tracking and navigation platforms enabling complex revision cases. Integration with endoscopic access is opening surgical candidacy previously excluded from minimally invasive approaches.
- 3D Imaging:Stereoscopic visualization accelerating surgeon training curves.
- Imaging Modalities:4K and ultra-high-definition standards displacing standard-definition platforms.
Minimally invasive technology anchors procedure volume. Robotic surgery represents the steepest expansion trajectory as navigation converges with endoscopic access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endoscopic spinal surgery equipment flows from German and Japanese manufacturing clusters toward import-dependent markets. The United States runs a persistent trade deficit in visualization systems while maintaining export strength in disposable instrumentation.
United States
Ambulatory surgery centers in Florida and Texas are absorbing CMS outpatient reimbursement expansion for endoscopic discectomy. FDA 510(k) clearance pathways govern device commercialization timelines. The Research Triangle in North Carolina anchors health system standardization committees mandating single-vendor endoscopy platforms.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are standardizing 4K-compatible visualization systems to reduce revision rates. EU MDR clinical evidence requirements impose extended follow-up data mandates for spinal implant systems. The Stuttgart medical technology cluster concentrates rigid endoscope manufacturing and sterilization equipment production.
Japan
Tertiary hospitals in Tokyo and Osaka are integrating optical tracking to expand minimally invasive candidacy for elderly stenotic patients. PMDA technical documentation standards delay market entry for foreign visualization platforms. The Kobe medical device corridor hosts domestic manufacturers specializing in fiber-optic camera systems.
China
Provincial hospital networks in Jiangsu and Guangdong are adopting subscription-based equipment financing to bypass upfront capital constraints. NMPA registration requirements for Class III medical devices extend approval cycles for imported visualization platforms. The Suzhou industrial park hosts contract manufacturers producing tubular retractor systems for regional distribution.
Switzerland
Swissmedic certification requirements for spinal implant biocompatibility create premium positioning for precision instrumentation. The Basel-Zurich corridor concentrates robotic navigation convergence research with academic medical centers. Geneva-based distributors are consolidating supplier relationships to reduce EU MDR compliance administration burden.
Endoscopic Spinal Surgery Market Vendor Landscape
Listed leaders compete with private specialists across imaging fidelity and access instrumentation dimensions. The vendor base concentrates around integrated visualization-plus-instrumentation bundling and standalone component specialization. Three archetypes dominate: diversified orthopedic conglomerates with spinal divisions, pure-play endoscopy manufacturers, and dedicated spinal access specialists. M&A activity targets optical tracking capabilities while portfolio diversification pushes into single-use disposable channels.
Among diversified orthopedic conglomerates, Stryker Corporation and Medtronic exemplify scale-driven platform bundling strategies. Joimax GmbH occupies a specialist position within the full-endoscopic access segment. Karl Storz represents the pure-play endoscopy manufacturing archetype with rigid scope specialization. These three anchors illustrate how competitive positioning splits between comprehensive system integration and targeted instrumentation depth.
| Leading Market Players |
|---|
| Stryker Corporation |
| Karl Storz |
| Medtronic |
| Zimmer Biomet |
| NuVasive |
| Johnson & Johnson (DePuy Synthes) |
| Joimax GmbH |
| B. Braun Melsungen AG |
| Globus Medical |
| Others |
Supply Flow & Price Mechanics
Ninety-day lead times for 4K camera consoles from German manufacturers concentrate pricing power among hospital networks with centralized procurement committees, while ambulatory surgery centers face compressed margins from subscription financing obligations. This inventory-to-pricing dynamic privileges integrated system vendors over standalone component suppliers.
Pricing Analysis
Hospital purchasing committees anchor three-tier pricing structure across premium, standard, and economy levels, with 4K visualization systems commanding premiums based on FDA 510(k) clearance tier and after-sales service bundling. Price differentiation stems from certification grade and volume scale, with multi-hospital health systems extracting steeper discounts than independent ambulatory facilities. Cost compression in the standard tier is intensifying because EU MDR compliance investments are raising production overheads. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while tertiary hospital networks prioritize performance specifications over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate among German and Japanese manufacturers serving North American hospital networks, while ambulatory surgery centers in Florida and Texas prefer strategic stockpiles of single-use disposable sheaths to eliminate sterilization bottlenecks. Supply concentrates in Germany for rigid endoscope production, Japan for fiber-optic camera systems, and China for tubular retractor contract manufacturing. Raw material dependencies include optical-grade glass, medical-grade polymers, and precision-machined stainless steel. Single-source vulnerability in 4K image sensor supply creates structural risk. Distribution runs through specialized medical device distributors with GPO contracts and direct hospital sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward health system standardization committees as North Carolina and Ohio networks consolidate procurement authority under single-vendor mandates, fragmenting leverage for standalone component suppliers.
For Market Incumbents: Shield installed base positions through backward integration into fiber-optic component manufacturing and exclusive GPO contract extensions with multi-hospital networks. The threat of subscription-based financing models from emerging entrants demands countermeasures through captive leasing subsidiaries. Priority levers include sterilization service bundling and fellowship training program sponsorships that lock in surgeon preference. For New Entrants and Emerging Players: Anchor in ambulatory surgery center channels in Texas and Florida where capital constraints exclude incumbent premium systems. The most penetrable segment is single-use disposable instrument kits bypassing centralized sterile processing. A direct-to-facility sales model with per-procedure financing terms unlocks adoption without seven-igure capital commitments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic conglomerates spinning non-core spinal divisions under portfolio rationalization pressures. Long-term viability hinges on robotic navigation convergence capabilities and ambulatory-compatible system footprints. The signal to watch is CMS reimbursement coding decisions for outpatient endoscopic fusion procedures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercialization timelines for visualization platforms in US hospital networks. |
| CE Marking Pathway | Enables access to German hospital networks standardizing 4K-compatible systems. |
| Hospital System Partnership | Locks in procurement decisions through integrated training and service bundling. |
| Software Companion Development | Enables EMR integration reducing deployment friction in health system rollouts. |
| Reimbursement Strategy | Aligns product positioning with CMS outpatient payment rate elevations. |
Methodological Framework
Operator-level perspectives from spine surgeons, hospital purchasing committee directors, ambulatory surgery center administrators, GPO contracts managers, and biomedical engineers anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation submissions. Bottom-up equipment shipment data and top-down healthcare expenditure patterns underwent cross-triangulation to reconcile volume estimates.
Sensitivity analysis across procedure volume assumptions, reimbursement rate scenarios, and capital expenditure cycles shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application complexity, end-user channel, and technology tier alongside surgeon training pipeline constraints. CAGRs derived from equipment replacement cycles, ambulatory migration rates, and imaging modality upgrade patterns. Forecast inputs incorporated PMDA approval timelines for Japanese market entry and EU MDR clinical evidence requirements.
Decision-makers should treat outputs as directional under stable reimbursement coding and surgeon training throughput assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions without anticipating regulatory shocks or technology discontinuities. Revision becomes warranted when ambulatory surgery center case volume crosses thresholds triggering inpatient capacity reallocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Global Gauze Swabs Market
Surgical Instruments
Surgical Tubing Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
United States General Surgical Devices Market