
 Japan General Surgical Devices Market | 2026-2036
Japan General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan General Surgical Devices Market Foresight
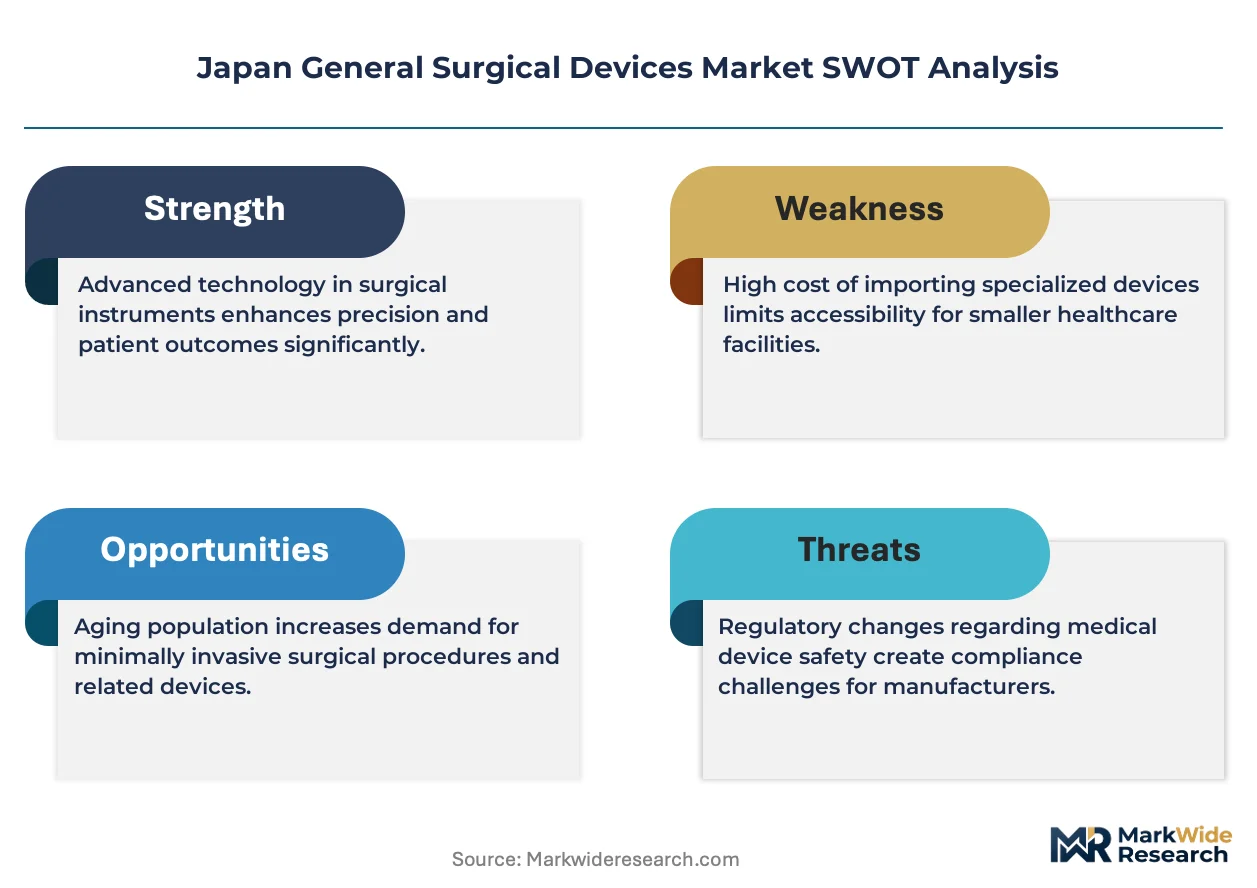
JIS T 0301 quality management certification is rotating vendor eligibility, effectively filtering which manufacturers qualify for public hospital tenders. Olympus Corporation leverages its endoscopic heritage to sustain dominance in laparoscopic device supply chains. Terumo Corporation anchors domestic production through vertically integrated needle and suture manufacturing. Johnson & Johnson competes across electrosurgical and wound closure portfolios, while Medtronic plc extends its robotic-assisted surgery platforms into select Japanese teaching hospitals.
General surgical devices comprise hand-held instruments, energy-based systems, closure materials, and visualization platforms engineered from medical-grade stainless steel, titanium alloys, and polymer composites, sterilized for repeated or single-use deployment in operating theaters. These tools enable tissue manipulation, hemostasis, and access creation across abdominal, thoracic, and pelvic procedures. Electrosurgical devices and laparoscopic platforms command premium positioning as hospitals convert open procedures to minimally invasive alternatives. Sutures retain volume leadership but face margin compression from commoditization, while robotic surgery systems represent the fastest-growing technology tier despite capital intensity barriers.
PMDA's Pharmaceutical and Medical Device Act enforcement shapes clinical evidence requirements and post-market surveillance obligations for all commercialized devices. METI's industrial policy promotes domestic robotic surgery ecosystem development through R&D tax incentives and hospital reimbursement alignment. JIS standards govern material biocompatibility and electrical safety specifications, creating compliance cost differentials between established players and new entrants. Stakeholders must monitor reimbursement rate revisions for robotic-assisted procedures and PMDA's evolving real-world evidence acceptance criteria to calibrate portfolio and partnership investments.
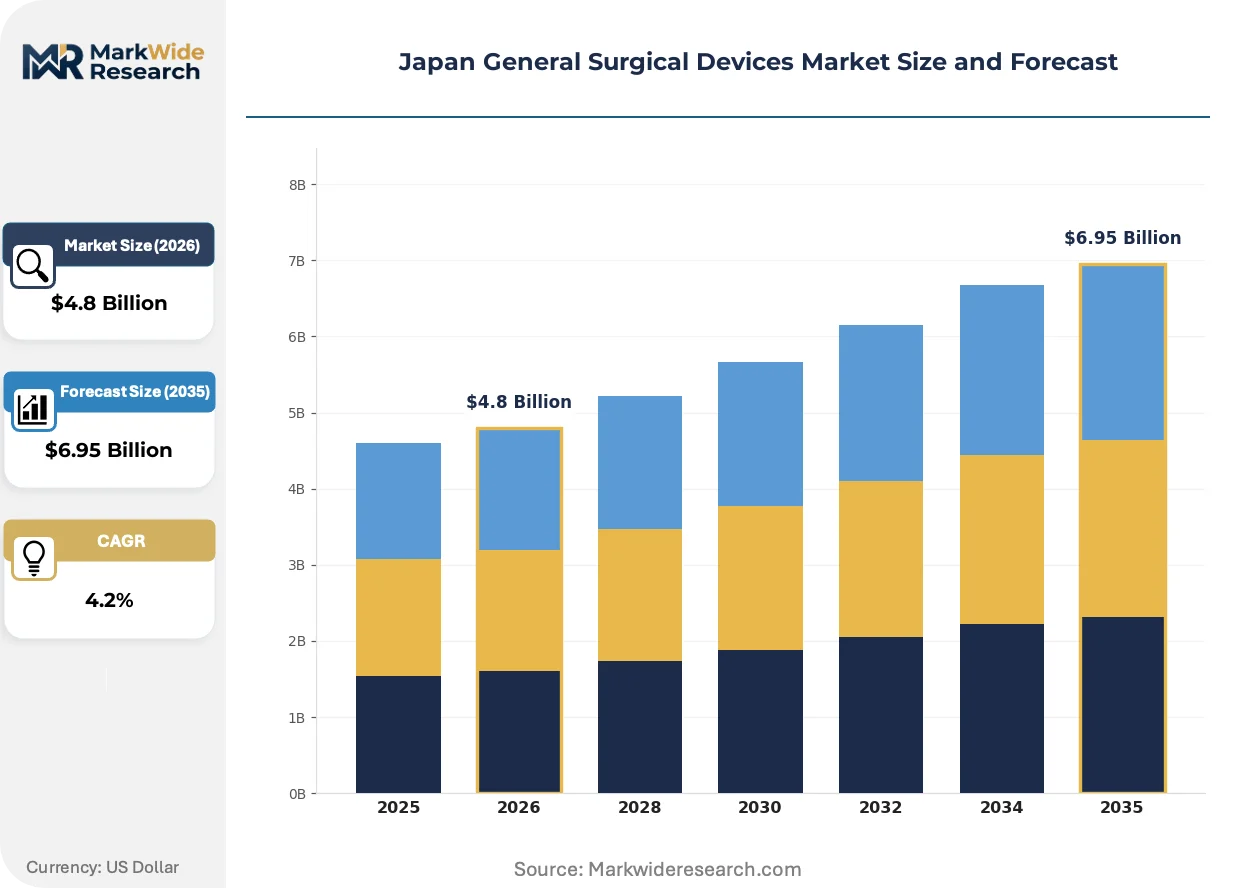
Market Dynamics
Japan's surgical device landscape is compressing around METI's industrial policy for robotic surgery ecosystems, which ties hospital reimbursement rates to minimally invasive procedure adoption and reshapes capital allocation across public and private healthcare networks.
Growth Catalysts
- Robotic surgery reimbursement alignment:METI's policy framework links procedure codes to robotic-assisted surgery platforms, accelerating hospital procurement cycles for capital-intensive systems in tertiary centers.
- Ambulatory surgical center expansion:Japan's aging demographics are driving procedural volumes into outpatient settings, creating concentrated demand for single-use laparoscopic instruments and compact electrosurgical units.
- PMDA streamlined approval pathways:The Pharmaceutical and Medical Device Act's accelerated review tracks for minimally invasive devices are shortening time-to-market for novel visualization platforms and energy-based systems.
Market Restraints
- Titanium alloy supply concentration:Medical-grade titanium feedstock for instrument manufacturing concentrates among a limited supplier base, exposing device makers to input cost volatility and allocation risk.
- JIS T 0301 certification barriers:The quality management certification's rotation of vendor eligibility creates structural friction for new entrants seeking public hospital tender participation.
- Open procedure residual preference:Established surgical training pathways and reimbursement inertia sustain demand for conventional instruments, constraining premium platform penetration in regional hospitals.
Strategic Opportunities
- Hokkaido and Kyushu regional hospital networks:Underpenetrated prefectures outside Tokyo-Osaka corridors present whitespace for robotic surgery platform deployment and localized service infrastructure.
- AI-integrated surgical navigation:Convergence of machine vision algorithms with laparoscopic imaging systems is enabling real-time tissue characterization and procedure optimization.
- R&D tax incentive capture:METI's industrial policy offers substantial credits for domestic robotic surgery ecosystem development, rewarding localized manufacturing and clinical trial investment.
Industry Challenges
- Robotic surgery specialist training pipelines:Certified surgeon availability lags platform installation rates, constraining utilization and return on capital for hospital buyers.
- Legacy instrument sterilization infrastructure:Integration of single-use polymer composites with existing autoclave and central sterile supply workflows requires facility-level reconfiguration.
- PMDA real-world evidence submission requirements:Post-market surveillance obligations for novel devices demand extended clinical data collection, extending commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan General Surgical Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Sutures, Electrosurgical Devices, Laparoscopic Devices End User: Hospitals, Ambulatory Surgical Centers, Clinics, Outpatient Facilities Technology: Robotic Surgery, Minimally Invasive Surgery, Conventional Surgery, Digital Tools Application: General Surgery, Gynecology, Orthopedics, Urology |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Medtronic plc, Smith & Nephew plc, Terumo Corporation, Johnson & Johnson, B. Braun Melsungen AG, Conmed Corporation, Stryker Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan General Surgical Devices Market Shifts & Advancements
Device architectures are pivoting toward disposable-electronic hybrids that merge single-use polymer construction with embedded sensor arrays, fundamentally altering procurement economics and sterilization workflows across Japanese operating theaters.
Polymer composite single-use instruments with integrated force-feedback sensors are supplanting reusable stainless steel hand tools in high-volume laparoscopic procedures. Ambulatory surgical centers in Osaka's manufacturing corridor are adopting these platforms at accelerated rates. The shift is compressing maintenance and sterilization overhead while elevating per-procedure supply costs.
PMDA's evolving acceptance of real-world evidence for post-market surveillance is restructuring clinical trial design for novel electrosurgical devices. Manufacturers now prioritize registry data and post-approval studies over traditional randomized controlled trials. This regulatory flexibility most benefits energy-based system developers targeting teaching hospital networks in Tokyo.
Hospital buying committees are consolidating vendor relationships around full-procedure portfolios rather than discrete instrument categories. Integrated supply contracts spanning visualization, energy, and closure platforms are displacing single-product tenders. This concentration pattern is most visible in prefectural hospital networks seeking procurement simplification and volume-based pricing leverage.
Japan General Surgical Devices Market Segmentation
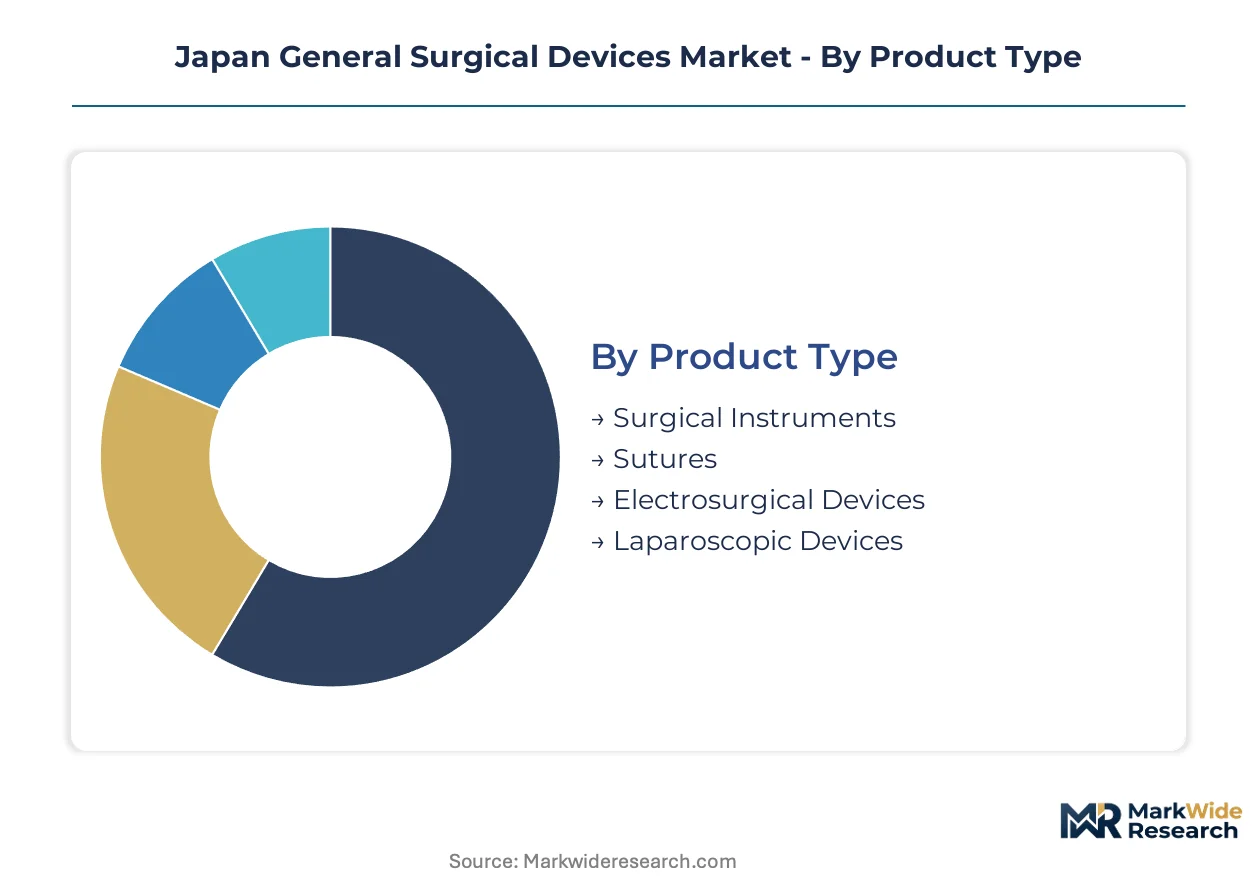
Segmentation in Japan's surgical device market reveals how METI's reimbursement policies and PMDA's regulatory pathways concentrate procurement decisions across specific technology tiers and care settings. Understanding these divisions exposes where capital flows and where substitution pressures reshape competitive dynamics.
Product Type:
Substitution pressure intensifies most acutely in mechanical instrument categories, where polymer single-use alternatives displace reusable metal platforms and compress traditional supplier margins.
- Electrosurgical Devices:Energy-based systems combining radiofrequency generators with specialized electrodes enable precise tissue cutting and coagulation. Tertiary hospitals in Tokyo prioritize these platforms as METI ties reimbursement premiums to minimally invasive procedure volumes.
- Laparoscopic Devices:Visualization platforms, trocars, and articulating instruments facilitate abdominal access without open incision. Osaka's ambulatory surgical centers drive concentrated demand for compact, single-use configurations that eliminate sterilization overhead.
- Surgical Instruments:Hand-held graspers, retractors, and scalpels fabricated from medical-grade stainless steel and titanium alloys.
- Sutures:Absorbable and non-absorbable closure materials including synthetic polymers and natural collagen threads.
Sutures retain volume leadership; laparoscopic devices hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive tertiary centers from outpatient facilities operating under constrained procurement budgets and accelerated patient throughput requirements.
- Hospitals:Tertiary and secondary acute care institutions with centralized surgical departments and dedicated robotic surgery programs. Tokyo's university-affiliated hospitals anchor demand for integrated platform ecosystems spanning visualization, energy, and closure technologies.
- Ambulatory Surgical Centers:Dedicated outpatient facilities performing same-day procedures under streamlined anesthesia protocols. Japan's aging demographics push procedural volumes into these settings, creating concentrated demand for disposable instrument kits and compact electrosurgical units.
- Clinics:Smaller physician practices performing limited-scope procedures with basic instrument inventories.
- Outpatient Facilities:Hospital-affiliated day surgery units and specialized procedure centers.
Hospitals dominate capital expenditure; ambulatory surgical centers are expanding most quickly.
Technology:
Application focus determines technology adoption velocity, with procedure-specific reimbursement codes accelerating migration from open to minimally invasive platforms in high-volume specialties.
- Robotic Surgery:Computer-assisted platforms with articulated instrument arms and 3D visualization enabling remote manipulation. METI's industrial policy links procedure reimbursement to robotic-assisted surgery adoption, accelerating procurement cycles in teaching hospitals.
- Minimally Invasive Surgery:Laparoscopic and endoscopic techniques reducing tissue trauma through small-incision access. PMDA's streamlined approval pathways for visualization platforms shorten time-to-market for novel energy-based systems targeting this segment.
- Conventional Surgery:Open procedures with direct tissue access via standard incision.
- Digital Tools:AI-integrated navigation systems and augmented reality overlays for surgical planning.
Minimally invasive surgery commands procedure volume; robotic surgery is gaining share fastest.
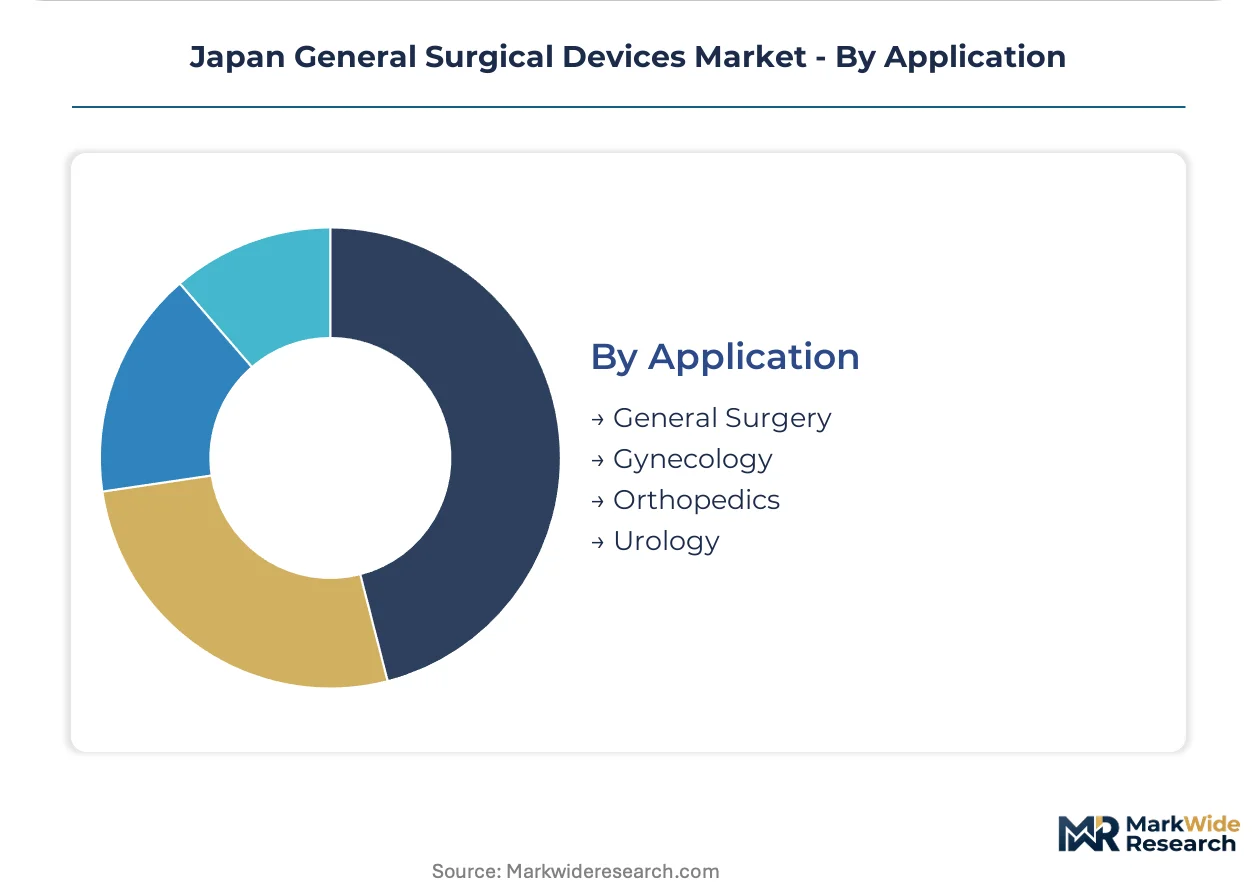
Application:
Volume concentration in abdominal and pelvic procedures creates procurement scale effects that favor integrated supply contracts over discrete instrument purchasing.
- General Surgery:Abdominal procedures including cholecystectomy, appendectomy, and hernia repair. Prefectural hospital networks consolidate vendor relationships around full-procedure portfolios spanning visualization, energy, and closure platforms.
- Gynecology:Hysterectomy, ovarian procedures, and fertility interventions. Underpenetrated prefectures outside Tokyo-Osaka corridors present whitespace for robotic surgery platform deployment.
- Orthopedics:Joint replacement, fracture fixation, and sports medicine interventions.
- Urology:Prostate, kidney, and bladder procedures including robotic-assisted prostatectomy.
General surgery anchors procurement scale; gynecology shows the strongest platform conversion momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shinkansen high-speed rail network and Tokyo Bay port infrastructure anchor Japan's surgical device distribution, enabling just-in-time delivery of sterile instruments to tertiary hospitals across the archipelago.
Kanto/Tokyo
Tokyo's university-affiliated hospitals drive demand for robotic surgery platforms and integrated visualization systems. METI's reimbursement alignment for minimally invasive procedures accelerates capital procurement cycles in this cluster. The Tokyo Bay medical technology corridor concentrates headquarters operations for domestic device manufacturers and teaching hospital networks.
Kansai/Osaka
Osaka's manufacturing corridor hosts concentrated production of single-use laparoscopic instruments and compact electrosurgical units. PMDA's streamlined approval pathways benefit local manufacturers targeting ambulatory surgical center expansion. The region's device fabrication ecosystem supplies both domestic demand and export markets across Asia-Pacific.
Chubu/Nagoya
Nagoya's industrial base supports precision machining of medical-grade titanium alloys and stainless steel surgical instruments. JIS T 0301 certification requirements filter vendor eligibility for public hospital tenders originating from this manufacturing hub. The region's metalworking heritage feeds instrument supply chains serving central Japan's secondary hospitals.
Kyushu
Underpenetrated prefectures in Kyushu present whitespace for robotic surgery platform deployment and localized service infrastructure. METI's industrial policy incentives reward manufacturers establishing clinical trial sites and training centers outside Tokyo-Osaka corridors. Fukuoka's emerging medical device cluster attracts investment in minimally invasive surgery ecosystem development.
Hokkaido
Hokkaido's regional hospital networks operate under constrained procurement budgets with residual preference for conventional open surgery instruments. PMDA's real-world evidence requirements extend commercialization timelines for novel devices targeting this remote market. Sapporo's tertiary centers anchor demand while rural facilities lag in minimally invasive platform adoption.
Japan General Surgical Devices Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, creating a bifurcated structure where scale-driven multinationals dominate premium robotic platforms while domestic specialists capture single-use instrument volumes. The market consolidates around three strategic archetypes: vertically integrated domestic manufacturers, diversified global health conglomerates, and focused visualization platform developers. Competitive moves center on hospital buying committee consolidation around full-procedure portfolios and R&D tax incentive capture through localized manufacturing investment.
Among diversified global health conglomerates, Johnson & Johnson and Medtronic plc occupy positions spanning electrosurgical, wound closure, and robotic-assisted surgery portfolios. Domestic specialists Olympus Corporation and Terumo Corporation exemplify the vertically integrated archetype, with the former leveraging endoscopic heritage and the latter anchoring needle and suture manufacturing. Boston Scientific Corporation represents the focused platform developer position, competing across cardiovascular and surgical intervention segments.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Medtronic plc |
| Smith & Nephew plc |
| Terumo Corporation |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Conmed Corporation |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
Capacity utilization at Osaka's polymer composite manufacturing plants creates scale thresholds that filter supplier participation in public hospital tenders. METI's R&D tax incentives reward domestic production volume, concentrating cost advantages among vertically integrated device makers while elevating price floors for imported alternatives.
Pricing Analysis
Volume-discount tiering structures separate procurement contracts for tertiary hospital networks from ambulatory surgical center spot purchases. Three-tier pricing stratification across premium robotic platforms, standard laparoscopic systems, and economy-grade mechanical instruments reflects JIS T 0301 certification grade and bundled service coverage. Cost compression in single-use polymer instruments intensifies as Osaka manufacturers expand capacity. Ambulatory surgical centers exhibit highest price sensitivity; Tokyo teaching hospitals prioritize performance metrics over unit cost.
Supply Chain Analysis
Japan and Germany anchor precision machining of medical-grade titanium alloys and stainless steel surgical instruments. Domestic feedstock draws from Chubu's metalworking corridor, while polymer resin supplies hinge on South Korean petrochemical output. Single-source vulnerability concentrates in medical-grade titanium sponge refining. Distribution runs through Tokyo Bay port infrastructure and Shinkansen-connected regional logistics hubs serving prefectural hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital buying committee consolidation around full-procedure portfolios has shifted negotiating leverage toward multi-year integrated supply contracts. Prefectural network procurement centralization fragments vendor access for discrete instrument specialists.
For Market Incumbents: Secure JIS T 0301 certification renewals ahead of eligibility rotation cycles to maintain public tender participation. Deepen backward integration into medical-grade titanium alloy sourcing to offset feedstock allocation risk from concentrated suppliers. Olympus and Terumo should expand service infrastructure in Kyushu and Hokkaido before robotic platform competitors establish localized training pipelines. For New Entrants and Emerging Players: Post-market surveillance data aggregation services present a service-layer gap where PMDA's real-world evidence requirements exceed incumbent analytical capabilities. Underpenetrated gynecology robotic surgery in prefectures outside Tokyo-Osaka corridors offers the most penetrable whitespace. Target hospital system partnerships emphasizing AI-integrated surgical navigation as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among disposable-electronic hybrid instrument developers serving ambulatory surgical center expansion. Five-to-ten year viability favors manufacturers capturing METI's R&D tax incentives through localized clinical trial investment. Monitor PMDA reimbursement rate revisions for robotic-assisted procedures as the critical inflection signal for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| JIS T 0301 Certification Investment | Quality management certification rotation filters vendor eligibility for public hospital tenders. |
| Hospital System Partnership | Integrated supply contracts spanning visualization, energy, and closure platforms displace single-product purchasing. |
| Reimbursement Strategy Alignment | METI's procedure code linkages to robotic-assisted surgery accelerate capital procurement cycles. |
| Software Companion Development | AI-integrated surgical navigation enables real-time tissue characterization for procedure optimization. |
| Regional Service Infrastructure | Kyushu and Hokkaido training centers address certified surgeon availability lagging platform installation. |
Research Methodology
Operator-level perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and PMDA regulatory consultants anchored the qualitative base. Primary interview findings triangulated against secondary sources including hospital procurement databases, GPO contract filings, METI industrial policy documents, and PMDA approval registry data. Bottom-up procedure volume estimates and top-down device spend analysis converged through cross-validation across Tokyo and Osaka hospital networks.
Sensitivity analysis tested forecast outputs against alternative scenarios for robotic surgery reimbursement rate revisions and titanium alloy supply disruptions. Segmentation modeling spanned product type, end user facility tier, technology platform, and application specialty across the projection horizon. CAGRs derived from historical procedural volume trajectories, capital equipment replacement cycles, and ambulatory surgical center expansion rates. Forecast inputs incorporated METI R&D tax incentive utilization patterns and PMDA accelerated approval pathway throughput.
Underlying assumptions cover sustained reimbursement alignment for minimally invasive procedures, with deviation risk concentrated in PMDA real-world evidence acceptance criteria shifts and titanium feedstock allocation constraints. Recalibration cycles align with material shifts in METI industrial policy revisions and prefectural hospital network procurement centralization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Disposable Surgical Devices Market
Surgical Instruments
Surgical Hand-Access Port Market