
 Surgical Lamps Market | 2026-2036
Surgical Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Lamps Market Outlook
Ambulatory surgical centers is reorganizing procurement patterns as outpatient volumes shift from traditional hospital settings. Stryker Corporation leverages its integrated surgical suite portfolio to anchor premium ceiling-mounted installations across North American health systems. Trumpf Medical Systems sustains engineering leadership in shadow-free illumination architectures for complex orthopedic procedures.
Surgical lamps are high-intensity, adjustable lighting fixtures engineered to deliver color temperatures between 3,000K and 6,700K with color-rendering indices exceeding 90, enabling tissue differentiation during invasive procedures. LED technology dominates new installations due to thermal efficiency and extended operational lifespan, while halogen retains replacement demand in budget-constrained clinics. Ceiling-mounted configurations occupy the largest revenue share, though mobile units are expanding fastest in field surgical and temporary facility deployments.
FDA 510(k) clearance pathways and IEC 60601-2-41 safety standards govern electrical and photobiological performance, compelling manufacturers to maintain dual compliance documentation for US and European market access. The EU Medical Device Regulation requires updated technical files for surgical lamp classifications, extending certification timelines for non-EU producers. Stakeholders must monitor evolving energy-efficiency mandates from the EU Green Deal as these will reshape capital equipment specifications ahead of replacement cycles.
Market Dynamics
LED thermal management advances are compressing replacement cycles while IEC 60601-2-41 compliance costs are restructuring vendor economics toward consolidated technical documentation.
Growth Catalysts
- EU Medical Device Regulation:Extended certification timelines for non-EU producers are favoring incumbents with established technical files, accelerating hospital procurement from verified suppliers.
- Ambulatory surgical centers:Outpatient volume migration from traditional hospital settings is creating dedicated procurement streams for compact, ceiling-mounted LED systems.
- Shadow-free illumination architectures:Complex orthopedic procedure requirements are driving specification upgrades in German university hospitals modernizing operating theater infrastructure.
Market Restraints
- Dual compliance documentation:FDA 510(k) clearance pathways and IEC 60601-2-41 standards impose parallel certification costs that disproportionately burden mid-tier manufacturers.
- Halogen replacement demand:Budget-constrained clinics in emerging markets sustain legacy technology procurement, fragmenting product roadmaps and diluting R&D focus.
- EU Green Deal energy mandates:Anticipated capital equipment specifications are freezing procurement decisions ahead of replacement cycles, compressing near-term order flow.
Strategic Opportunities
- Field surgical deployments:Mobile surgical lamp units are capturing temporary facility and military medical applications where ceiling infrastructure is unavailable.
- Photobiological performance integration:Convergence of surgical illumination with circadian lighting protocols is opening wellness-oriented hospital construction specifications.
- After-sales service unbundling:Independent maintenance contracts for LED driver replacement and optical calibration are creating recurring revenue streams separate from capital sales.
Industry Challenges
- Optical engineering talent scarcity:Specialized expertise in color-rendering index optimization above 90 and thermal lens design concentrates among aging specialist cohorts.
- Legacy halogen infrastructure integration:Hybrid operating theaters require backward-compatible mounting systems and electrical specifications, complicating product architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Lamps Market |
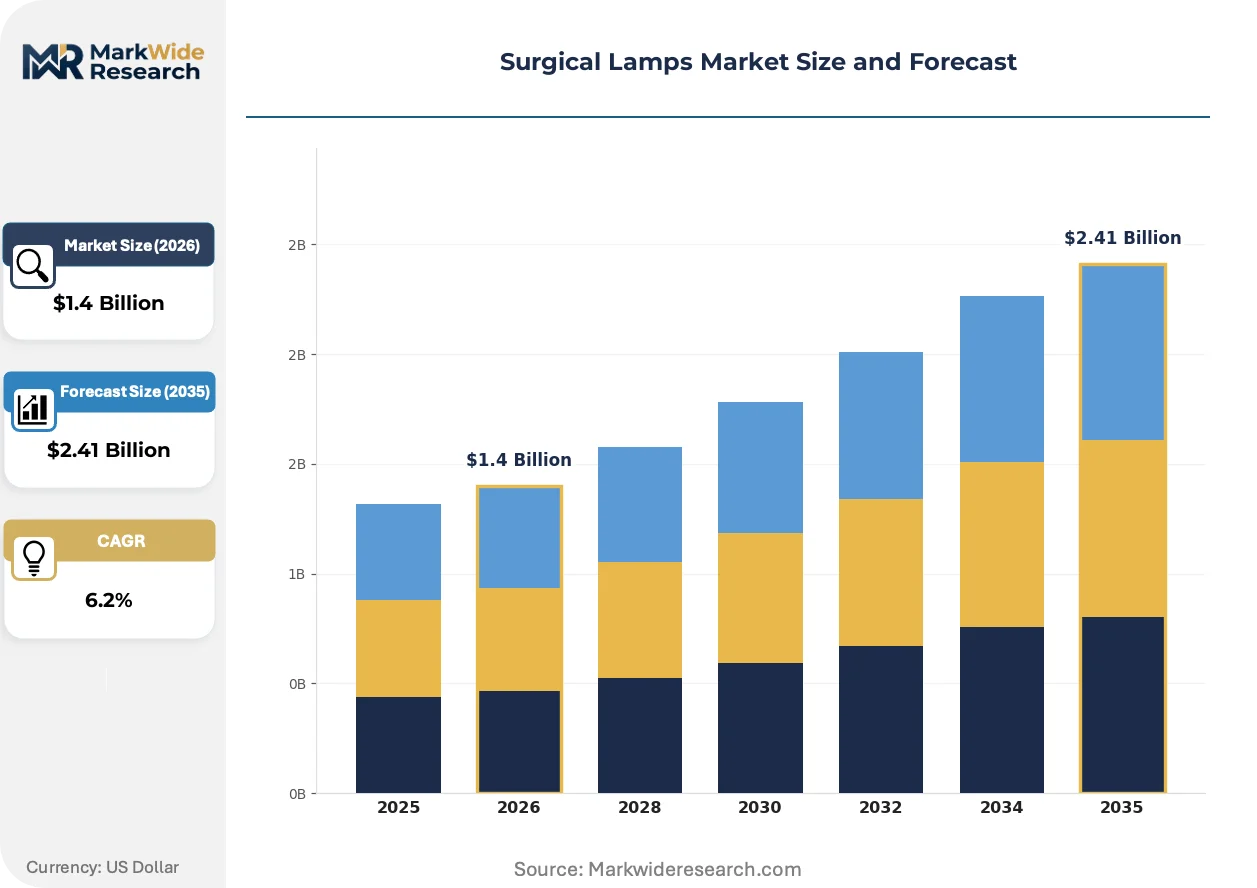
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Fluorescent Technology: Mobile, Ceiling-Mounted, Wall-Mounted, Integrated End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Facilities Application: General Surgery, Dental Surgery, Orthopedic Surgery, Urology |
| Companies Covered | Maquet Holding B.V. & Co. KG, Trumpf Medical Systems, Stryker Corporation, Shanghai Huifeng Medical Instrument Co., Ltd., Heine Optotechnik GmbH & Co. KG, Getinge AB, Koninklijke Philips N.V., Aesculap AG, STERIS plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Lamps Market Strategic Shifts
Photobiological safety engineering and modular optical architectures are restructuring how surgical lighting systems are specified, procured, and maintained across acute care environments.
Adaptive color-temperature LED engines are fragmenting the traditional single-fixture model. These systems enable real-time adjustment between 3,000K and 6,700K during procedures. German university hospitals are specifying them for neurosurgical suites where tissue differentiation requirements shift across operative phases. The technology is fragmenting vendor portfolios into modular upgrade paths rather than monolithic replacement cycles.
FDA updated medical device illumination standards are elevating color-rendering index minimums for 510(k) clearance eligibility. Manufacturers must resubmit technical documentation for existing product lines. Ceiling-mounted configurations face the steepest compliance burden due to their dominant installed base and longer replacement intervals.
Hospital procurement departments are consolidating vendor relationships around integrated surgical suite portfolios. Single-source contracting for lighting, booms, and integration systems is displacing discrete equipment purchasing. This concentration is most visible in North American health systems where capital budget centralization and GPO alignment favor full-suite suppliers over specialized lamp manufacturers.
Surgical Lamps Market Segmentation
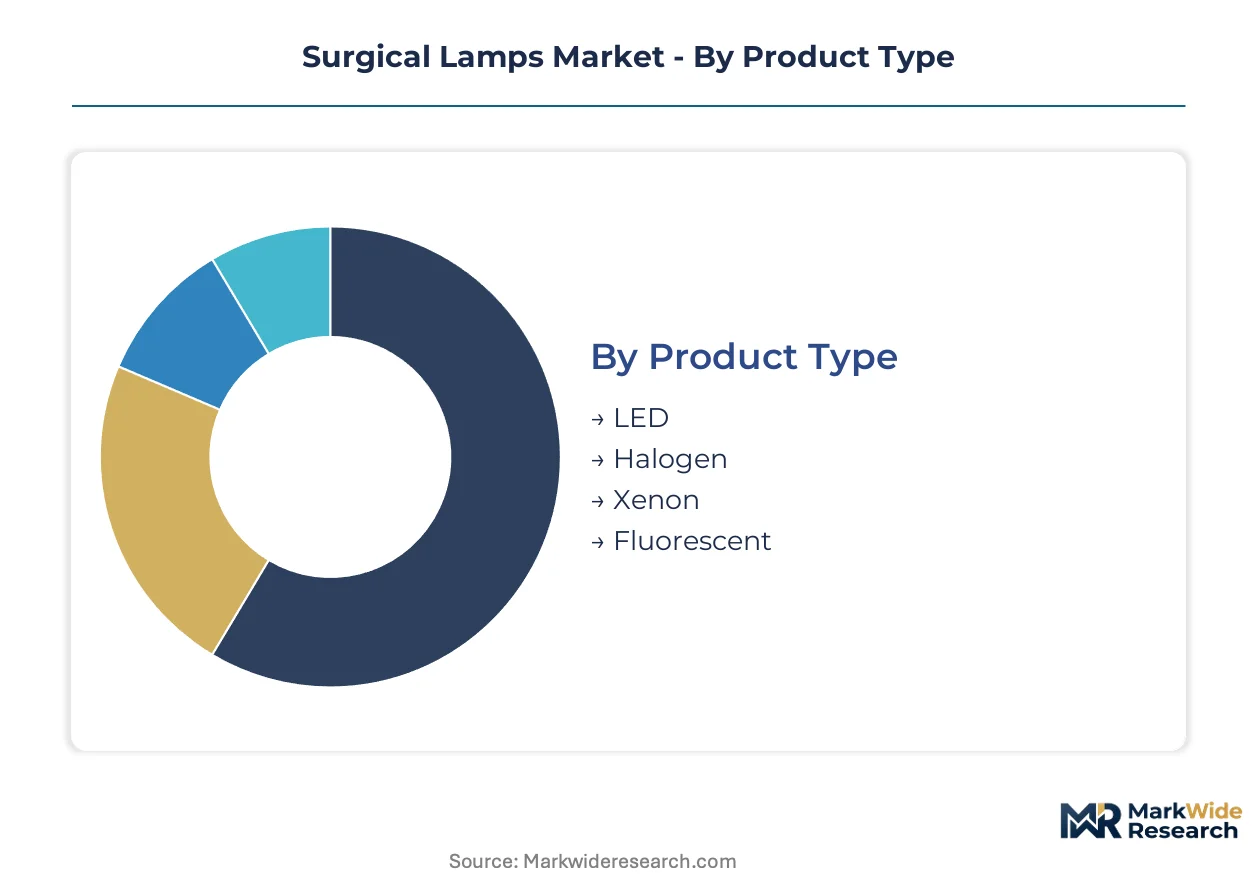
Surgical lamp procurement patterns fragment sharply across installation environments and procedural requirements. LED thermal architectures and mounting configurations create distinct margin pools that reward specialized engineering capabilities over commodity assembly.
Product Type:
Margin concentration sits with solid-state illumination platforms that command premium positioning through energy efficiency and spectral precision.
- LED:Solid-state semiconductor arrays deliver color temperatures tunable between 3,000K and 6,700K with color-rendering indices above 90. German university hospitals are specifying these systems for neurosurgical suites where tissue differentiation requirements shift across operative phases. FDA updated medical device illumination standards are elevating minimum color-rendering thresholds, compressing replacement cycles for legacy installations.
- Halogen:Tungsten-halogen filaments produce continuous-spectrum output through quartz-envelope thermal cycling. Budget-constrained clinics in emerging markets sustain procurement demand, fragmenting product roadmaps and diluting manufacturer R&D focus toward dual-platform maintenance.
- Xenon:High-intensity discharge arcs generate daylight-matched spectra through noble gas excitation. Specialized ophthalmic microsurgical suites specify these systems for retinal procedure visualization.
- Fluorescent:Mercury vapor excitation of phosphor coatings produces diffuse, lower-intensity output. Limited to ancillary examination lighting in cost-sensitive outpatient settings.
The dominant share belongs to LED, while Halogen is closing the gap fastest through replacement demand in budget-constrained installations.
Technology:
Installation architecture determines capital intensity and service contract attach rates across acute care construction cycles.
- Ceiling-Mounted:Suspended boom-integrated fixtures dominate revenue concentration through permanent operating theater infrastructure. North American health systems are consolidating vendor relationships around integrated surgical suite portfolios that bundle lighting with booms and integration systems.
- Mobile:Castor-mounted units with battery backup enable repositioning across procedural areas. Field surgical deployments and temporary military medical facilities are capturing this configuration where ceiling infrastructure is unavailable.
- Wall-Mounted:Articulating arm fixtures attach to vertical surfaces in space-constrained procedure rooms. Ambulatory surgical centers specify these for minor procedure suites with lower capital budgets.
- Integrated:Lighting modules embedded within ceiling supply units combine illumination with gas, power, and data services. New hospital construction specifications favor this consolidation to reduce ceiling clutter.
Ceiling-Mounted retains the largest installed base, though Mobile is expanding most quickly in non-traditional deployment environments.
End User:
Procurement authority and replacement cycle timing vary substantially across facility ownership structures.
- Hospitals:Centralized capital committees govern multi-year replacement programs for operating theater infrastructure. EU Medical Device Regulation extended certification timelines are favoring incumbents with established technical files, accelerating procurement from verified suppliers.
- Ambulatory Surgical Centers:Outpatient volume migration from traditional hospital settings is creating dedicated procurement streams for compact, ceiling-mounted LED systems with faster installation timelines.
- Clinics:Independent physician ownership drives price-sensitive purchasing through group purchasing organization contracts. Halogen retention is highest in this segment due to constrained capital access.
- Research Facilities:Academic medical centers require spectral calibration documentation for reproducible imaging protocols. Photobiological performance integration with circadian lighting protocols is opening wellness-oriented construction specifications.
Hospitals command the dominant procurement volume, while Ambulatory Surgical Centers are gaining share fastest through outpatient volume migration.
Application:
Procedure complexity dictates shadow-free illumination specifications and color-temperature adaptability requirements.
- General Surgery:Abdominal and soft-tissue procedures require broad-field illumination with minimal shadowing. Standard LED configurations satisfy most specifications without premium adaptive engines.
- Orthopedic Surgery:Deep cavity visualization through blood-perfused tissue demands high-intensity output with superior red-rendering indices. German university hospitals are modernizing operating theater infrastructure with shadow-free illumination architectures from Trumpf Medical Systems.
- Dental Surgery:Oral cavity procedures require compact head-mounted or ceiling fixtures with color-matching for restorative material selection. Smaller field diameter specifications reduce fixture cost.
- Urology:Endoscopic-assisted procedures combine external illumination with integrated camera light sources. Hybrid requirements split procurement between surgical lamp and endoscopy system vendors.
General Surgery maintains the broadest installed base, though Orthopedic Surgery is climbing the fastest through university hospital modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Rhine-Main medical technology corridor anchors European surgical lamp engineering, while US health system consolidation reshapes procurement corridors across the Great Lakes and Northeast.
Germany
University hospital modernization in Baden-Württemberg and Bavaria drives specification upgrades for shadow-free illumination architectures. The EU Medical Device Regulation extends certification timelines, favoring incumbents with established technical files in Tübingen and Munich clusters. Trumpf Medical Systems sustains engineering leadership from its Ditzingen headquarters for complex orthopedic procedures.
United States
Ambulatory surgical center expansion across Texas and Florida creates dedicated procurement streams for compact LED systems. FDA updated medical device illumination standards elevate color-rendering index minimums for 510(k) clearance eligibility. Stryker Corporation leverages its integrated surgical suite portfolio across Michigan and Ohio health systems.
China
Tier-three hospital construction in the Yangtze River Delta and Pearl River Delta sustains volume demand for ceiling-mounted configurations. NMPA medical device registration requirements tighten photobiological safety documentation for imported systems. Shanghai Huifeng Medical Instrument Co., Ltd. anchors domestic supply from its Pudong manufacturing base.
Japan
Aging surgical infrastructure in the Kansai region accelerates replacement cycles for LED thermal management platforms. METI energy-efficiency guidelines for medical equipment reshape capital equipment specifications ahead of hospital renovation programs. Osaka-based distributors concentrate procurement authority for integrated surgical suite portfolios.
India
Budget-constrained clinics in Maharashtra and Gujarat sustain halogen replacement demand alongside LED adoption in corporate hospital chains. CDSCO medical device rules require updated import licenses for surgical lamp classifications, extending lead times for European suppliers. Mumbai and Ahmedabad clusters split procurement between cost-sensitive clinics and premium hospital construction.
Surgical Lamps Market Competitive Environment
Listed leaders compete with private specialists across integrated surgical suite portfolios and component-level illumination engineering. The vendor base stratifies between full-suite health system contractors and dedicated optical engineering houses. Three archetypes dominate: diversified medical technology conglomerates with GPO-aligned distribution, mid-cap specialists in shadow-free architectures, and regional fabricators serving price-sensitive procurement. Competitive moves concentrate on hospital procurement consolidation and modular optical platform development.
Among diversified health technology conglomerates, Stryker Corporation and Koninklijke Philips N.V. exemplify the integrated-suite archetype with bundled lighting, booms, and integration systems. Trumpf Medical Systems occupies a specialist position in shadow-free illumination architectures from its German engineering base. Shanghai Huifeng Medical Instrument Co., Ltd. represents the regional fabricator tier serving domestic procurement in China with cost-optimized configurations.
| Leading Market Players |
|---|
| Maquet Holding B.V. & Co. KG |
| Trumpf Medical Systems |
| Stryker Corporation |
| Shanghai Huifeng Medical Instrument Co., Ltd. |
| Heine Optotechnik GmbH & Co. KG |
| Getinge AB |
| Koninklijke Philips N.V. |
| Aesculap AG |
| STERIS plc |
| Others |
Value Chain & Pricing Dynamics
Ninety-to-one-hundred-twenty-day certification lead times for EU Medical Device Regulation technical files concentrate pricing power among German and US incumbents with established documentation, while compressing margins for mid-tier manufacturers lacking pre-validated product architectures. This inventory discipline cascades through procurement decisions at hospital systems and ambulatory surgical centers, favoring suppliers with compliant stock over price-competitive challengers facing extended approval cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with premium tiers anchored by FDA 510(k) cleared systems with color-rendering indices above 95 and integrated surgical suite bundling. Price differentiation stems from certification grade and after-sales service attach rates, with maintenance contracts for LED driver replacement commanding recurring premiums. Cost compression in the economy tier intensifies as Chinese regional fabricators expand domestic production capacity. Ambulatory surgical centers exhibit highest price sensitivity due to capital budget constraints, while university hospital systems in Germany demonstrate lowest sensitivity when specifying shadow-free illumination architectures for complex orthopedic procedures.
Supply Chain Analysis
Inventory buffers for optical-grade aluminum heat sinks and precision LED driver assemblies extend to sixty-to-ninety days across German, Chinese, and US manufacturing nodes, reflecting semiconductor component lead time volatility. Raw material dependencies center on rare-earth phosphors for spectral tuning, high-purity aluminum for thermal management, and ceramic substrates for LED array mounting. Single-source vulnerability concentrates in specialized optical lens grinding equipment controlled by Japanese and German precision engineering houses. Distribution runs through hospital group purchasing organizations in North America, direct tender contracts with public health systems in Europe, and regional distributor networks serving tier-three hospital construction in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Independent maintenance contracts for LED calibration and driver replacement represent a service-attach opportunity expanding faster than hardware sales, as hospital procurement departments unbundle after-sales support from capital equipment purchases to manage operational expenditure budgets.
For Market Incumbents: Shield installed base relationships by embedding optical calibration services into multi-year service agreements, countering emerging specialist firms offering unbundled maintenance at lower price points. Deepen backward integration into precision LED driver manufacturing to reduce semiconductor supply exposure and capture margin from component replacement cycles. Prioritize certification investment for adaptive color-temperature engines ahead of anticipated FDA minimum threshold increases. For New Entrants and Emerging Players: Differentiate on mobile surgical lamp configurations for field deployment and temporary military medical facilities, where ceiling infrastructure constraints exclude established ceiling-mounted specialists. Target ambulatory surgical center procurement streams in Texas and Florida, where outpatient volume migration creates demand for compact LED systems with faster installation timelines than integrated suite offerings. Pursue direct-to-facility sales models bypassing GPO consolidation to capture price-sensitive independent clinic segments. For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle consolidation play because LED thermal management advances compress hardware refresh intervals while service contract attach rates deepen recurring revenue visibility. Acquisition targets should display established EU MDR technical files and hospital system reference contracts rather than raw market share. Watch German university hospital modernization program announcements as inflection indicators for premium specification upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Investment | Extended certification timelines favor incumbents with pre-validated documentation for hospital procurement. |
| Adaptive Color-Temperature Engine Development | German neurosurgical suites specify real-time spectral adjustment between 3,000K and 6,700K. |
| After-Sales Service Unbundling | Independent LED driver replacement contracts create recurring revenue separate from capital sales. |
| Mobile Configuration Expansion | Field surgical deployments capture temporary facility applications lacking ceiling infrastructure. |
| Integrated Surgical Suite Partnership | North American health systems consolidate vendor relationships around bundled lighting and boom systems. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and ambulatory surgical center administrators; and secondary validation against FDA 510(k) clearance databases, EU MDR technical file registries, hospital capital expenditure disclosures, and medical device trade flow records. Bottom-up triangulation across installation volume estimates by mounting configuration and technology type converged with top-down market sizing derived from disclosed revenue segments of listed manufacturers.
Across the analysis window, the forecasting framework modeled volume and value trajectories across product type, technology architecture, end-user facility category, and application complexity dimensions. CAGRs were derived from replacement cycle timing analysis, regulatory compliance cost impacts on pricing elasticity, and penetration rate assumptions for mobile configurations in non-traditional deployment environments. Procedure volume migration from inpatient to outpatient settings and photobiological safety standard evolution served as primary demand-side inputs.
The analysis sits within stated boundaries; outcomes outside sustained hospital capital expenditure levels or accelerated EU Green Deal energy mandate implementation would require recalibration. Forecasts reflect documented assumptions regarding LED thermal management improvement rates and certification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Pneumoperitoneum Market