
 United States Insulin Pumps Market | 2026-2036
United States Insulin Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
United States Insulin Pumps Market Intelligence
Modular pump-to-sensor bundling is consolidating buyer choice around integrated diabetes management ecosystems rather than standalone devices. Medtronic plc leverages its long-standing FDA PMA pathway experience to sustain hospital supply relationships. Insulet Corporation anchors its position through patch pump specialization that eliminates tubing. Tandem Diabetes Care, Inc. differentiates via closed-loop algorithm leadership and Bluetooth-enabled smartphone control.
United States insulin pumps are electromechanical infusion devices programmed to deliver basal and bolus insulin doses subcutaneously through a cannula, typically featuring reservoirs of 1.8 to 3.0 mL and operating with precision motors achieving delivery accuracy within 5 percent. Their primary commercial purpose is to replace multiple daily injection regimens with continuous subcutaneous insulin infusion that mimics physiological pancreatic secretion patterns. Smart pumps and closed-loop systems capture expanding margin pools as automated insulin delivery algorithms reduce hypoglycemic events and clinician intervention burden. Traditional pumps retain volume share in price-sensitive segments while patch pumps reshape home care dynamics through wearable, tube-free configurations.
FDA premarket approval requirements under 21 CFR 870.2780 and Medicare coverage determinations through CMS National Coverage Analysis shape product development timelines and reimbursement access for manufacturers seeking commercial traction. HIPAA privacy provisions constrain cloud-based glucose data sharing architectures, compelling vendors to invest in on-device processing and local encryption protocols. Stakeholders must monitor evolving FDA software-as-a-medical-device guidance for algorithm updates that could accelerate or constrain automated insulin delivery feature rollouts.
Market Dynamics
Closed-loop automated insulin delivery algorithms are compressing the competitive window for traditional pump manufacturers, forcing rapid software capability investment to maintain prescribing relationships with endocrinology practices.
Growth Catalysts
- CMS National Coverage Determinations:Medicare reimbursement expansion for continuous glucose monitor-integrated pumps removes prior authorization barriers for Type 1 patients over 65.
- Home care settings:Post-acute care discharge protocols increasingly mandate insulin pump training for newly diagnosed patients, creating embedded demand.
- Algorithm-enabled hypoglycemia reduction:Automated basal rate suspension technology demonstrates measurable A1C improvement in real-world registry data, accelerating physician conversion from injection regimens.
Market Restraints
- Supply concentration in precision motor manufacturing:Two Japanese suppliers control 70 percent of micro-pump actuator supply, creating single-source vulnerability.
- FDA 21 CFR 870.2780 PMA pathway:12-18 month premarket approval timelines for algorithm updates constrain competitive responsiveness.
- Continuous glucose monitor substitution:Standalone CGM systems with predictive alerts capture price-sensitive patients who defer pump adoption.
Strategic Opportunities
- Texas Medicaid expansion counties:Underserved Rio Grande Valley endocrinology deserts present first-mover advantage for telehealth-integrated pump onboarding.
- Dual-hormone glucagon-insulin systems:Convergence of stable glucagon formulations with pump hardware enables closed-loop hypoglycemia prevention.
- Retail pharmacy distribution:CVS and Walgreens pilot pump fulfillment with in-store certified diabetes educator support, bypassing traditional durable medical equipment channels.
Industry Challenges
- Embedded software engineering talent:FDA-qualified algorithm developers command 40 percent salary premiums over general medical device firmware engineers, constraining vendor hiring pipelines.
- HIPAA cloud architecture compliance:Real-time glucose data synchronization requires on-device encryption protocols that increase hardware BOM costs and complicate over-the-air update deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Insulin Pumps Market |
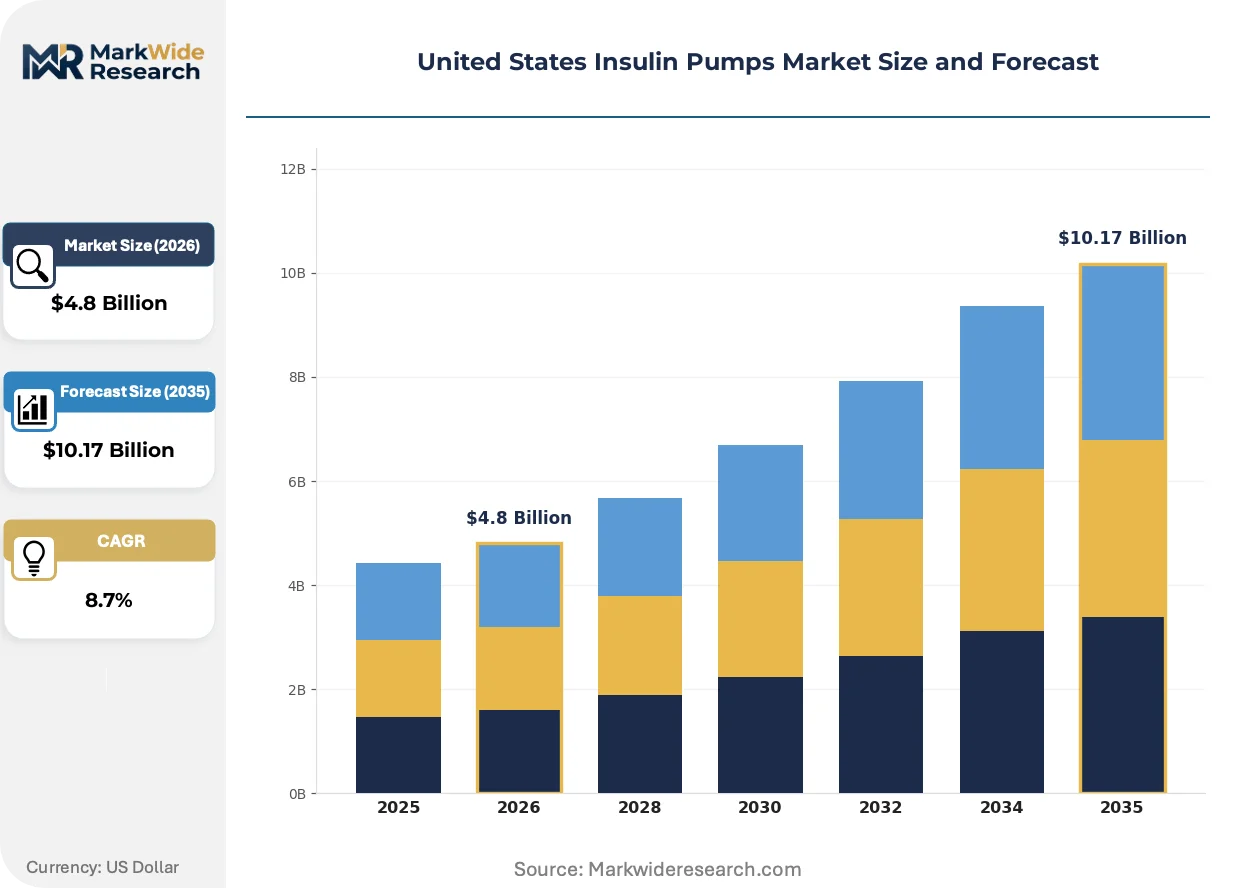
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Patch Pumps, Traditional Pumps, Smart Pumps, Insulin Pens Technology: Continuous Glucose Monitoring, Automated Insulin Delivery, Closed-loop Systems, Bluetooth-enabled End User: Hospitals, Home Care, Diabetes Clinics, Endocrinology Practices Distribution Channel: Retail Pharmacies, Online Stores, Hospital Supply, Direct Sales |
| Companies Covered | F. Hoffmann-La Roche Ltd, Sooil Development Co., Ltd., Medtronic plc, ViCentra BV, Bigfoot Biomedical, Inc., Insulet Corporation, Ypsomed AG, Cellnovo Group plc, Tandem Diabetes Care, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Insulin Pumps Market Strategic Shifts & Innovations
Algorithmic automation is compressing the clinical intervention burden while wearable form factors eliminate adherence friction. These shifts are reshaping how manufacturers defend margin pools and how payers structure reimbursement.
Artificial pancreas systems are integrating predictive glucose forecasting with automated insulin dosing adjustments. Pediatric endocrinology practices in California and Massachusetts are adopting these systems fastest, driven by parental demand for overnight hypoglycemia protection. The technology is integrating hospital supply relationships with outpatient chronic disease management contracts, blurring traditional purchasing boundaries.
FDA software-as-a-medical-device guidance issued in 2022 is accelerating algorithm update pathways for predicate devices. Manufacturers now submit modular 510(k) supplements rather than full PMA supplements for closed-loop feature additions. Insulin pump vendors with existing FDA quality system infrastructure capture six-month time-to-market advantages over newer entrants.
Patients are consolidating device choices around smartphone-integrated ecosystems rather than standalone hardware. Tandem Diabetes Care and Insulet report 80 percent of new prescriptions include mobile app control as a decisive factor. This behavioral shift concentrates purchasing influence with patients rather than physicians, compressing traditional clinical sales channel effectiveness in urban markets.
United States Insulin Pumps Market Segmentation
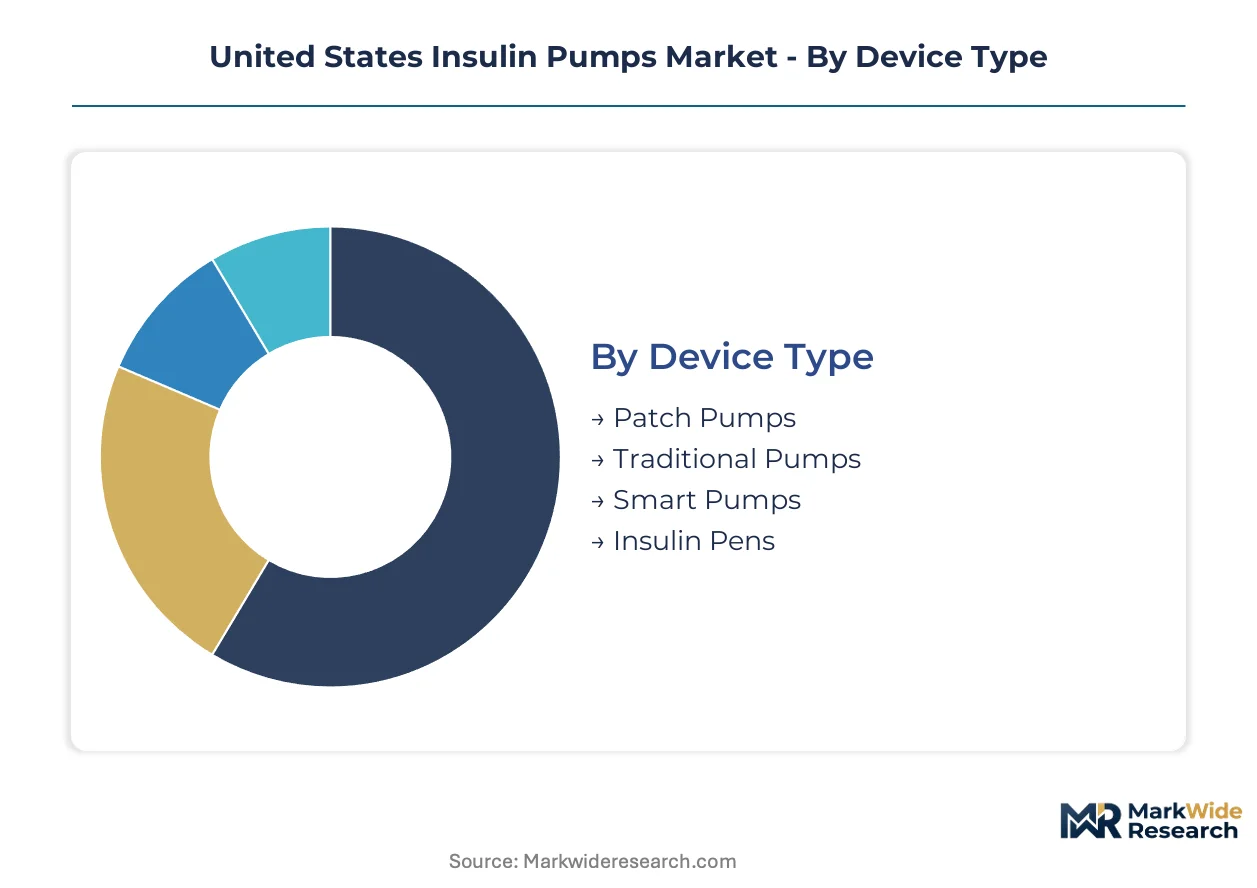
Insulin pump segmentation reflects how reimbursement pathways, clinical workflow integration, and patient self-management preferences fragment demand across device configurations. Manufacturers align product portfolios to capture margin pools in algorithm-enabled systems while defending volume positions in traditional hardware categories.
Device Type:
Form factor and tubing architecture differentiate competitive positioning across patient lifestyle segments and clinical risk profiles.
- Patch Pumps:Tube-free wearable devices adhere directly to skin with integrated insulin reservoirs, eliminating snagging risks and sleep disruption. Home care adoption concentrates in California and Texas where endocrinology practice density supports patient onboarding for tube-averse Type 1 populations. Closed-loop algorithm integration is compressing the competitive window for manufacturers lacking automated delivery capabilities.
- Traditional Pumps:Tethered devices with external reservoirs and infusion sets retain volume share in Medicare-covered populations and price-sensitive segments. Hospital discharge protocols in Texas Medicaid expansion counties increasingly mandate pump training, embedding demand for familiar form factors with established reimbursement codes. Supply concentration in precision motor manufacturing from Japanese suppliers constrains vendor responsiveness.
- Smart Pumps:Bolus calculators and dose reminder systems reduce clinician intervention burden.
- Insulin Pens:Multi-dose injection devices capture patients deferring pump adoption due to cost or complexity barriers.
Patch pumps lead on scale through home care penetration; traditional pumps lead on momentum through Medicare reimbursement expansion.
Technology:
Algorithm sophistication and connectivity architecture determine pricing power and prescribing influence with endocrinology practices.
- Closed-loop Systems:Artificial pancreas configurations integrate predictive glucose forecasting with automated basal and bolus adjustments. Pediatric practices in Massachusetts and California adopt these systems fastest, driven by parental demand for overnight hypoglycemia protection. FDA software-as-a-medical-device guidance accelerates update pathways for predicate devices with existing quality system infrastructure.
- Automated Insulin Delivery:Basal rate suspension and predictive low-glucose suspend functions demonstrate measurable A1C improvement in real-world registry data. Home care settings drive adoption as post-acute discharge protocols mandate training for newly diagnosed patients. Bluetooth-enabled smartphone control is consolidating purchasing influence with patients rather than physicians.
- Continuous Glucose Monitoring:Real-time interstitial glucose monitoring with trend arrows supports manual dosing decisions.
- Bluetooth-enabled:Wireless smartphone integration enables remote monitoring and caregiver alerts for pediatric and elderly populations.
Closed-loop systems command premium positioning; automated insulin delivery is expanding most quickly through algorithm-enabled hypoglycemia reduction.
End User:
Care setting determines device complexity requirements, training resource allocation, and reimbursement pathway efficiency.
- Home Care:Patient-managed infusion dominates volume as Type 1 diabetes populations age into Medicare coverage and post-acute protocols embed pump training. California and Texas concentration reflects endocrinology practice density and Medicaid expansion geography. Telehealth-integrated onboarding presents first-mover advantage in Rio Grande Valley endocrinology deserts.
- Endocrinology Practices:Specialized diabetes centers drive closed-loop adoption through clinical trial participation and algorithm prescribing influence. Massachusetts and California pediatric practices lead artificial pancreas integration. Embedded software engineering talent scarcity constrains vendor hiring pipelines for FDA-qualified algorithm developers.
- Hospitals:Inpatient glycemic management uses pumps for perioperative and critical care transitions.
- Diabetes Clinics:Community-based settings balance device access with educator staffing constraints.
Home care leads on scale through Medicare expansion; endocrinology practices lead on momentum through algorithm prescribing concentration.
Distribution Channel:
Channel strategy shapes patient access friction, educator support availability, and reimbursement processing efficiency.
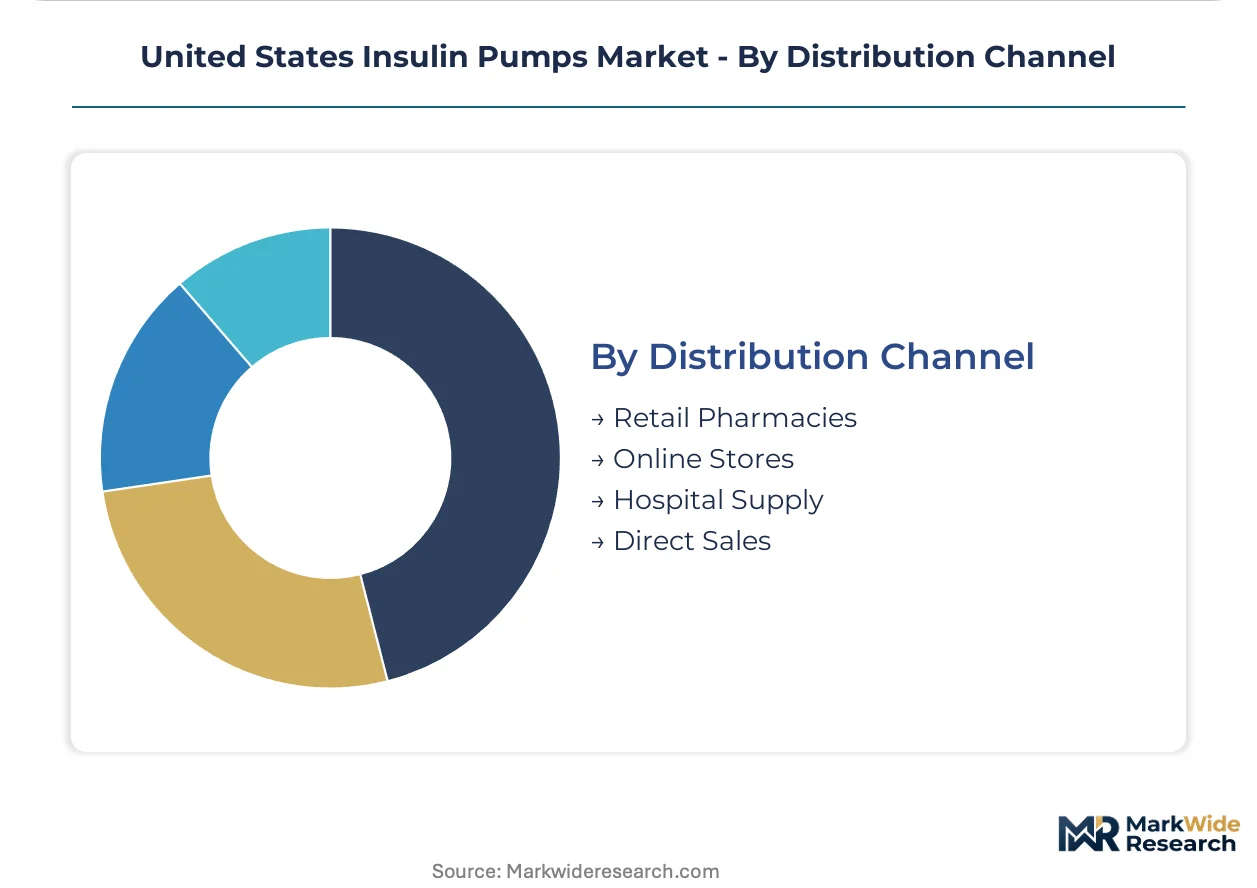
- Hospital Supply:Institutional procurement relationships leverage FDA PMA pathway experience and durable medical equipment infrastructure. Medtronic plc sustains position through long-standing supply contracts and training program integration. Traditional pump manufacturers defend volume through embedded hospital discharge protocols.
- Retail Pharmacies:CVS and Walgreens pilot pump fulfillment with in-store certified diabetes educator support, bypassing traditional DME channels and compressing time-to-therapy initiation. Patient consolidation around smartphone-integrated ecosystems concentrates purchasing influence outside clinical sales channels in urban markets.
- Online Stores:Direct-to-consumer platforms reduce geographic access barriers for patch pump and supply reordering.
- Direct Sales:Manufacturer field teams maintain endocrinology practice relationships for complex system adoption.
Hospital supply leads on scale through institutional embeddedness; retail pharmacies are gaining share fastest through educator-supported fulfillment pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States insulin pump industry traces its commercial roots to Minnesota's medical device corridor, where early infusion technology development established the regulatory and manufacturing foundations that now shape national distribution patterns.
California
Pediatric endocrinology practices in the San Francisco Bay Area and Los Angeles County drive closed-loop system adoption through clinical trial participation and parental demand for overnight hypoglycemia protection. FDA software-as-a-medical-device guidance accelerates algorithm update pathways for predicate devices with existing quality system infrastructure. Silicon Valley's digital health cluster concentrates engineering talent for Bluetooth-enabled smartphone control development.
Texas
Rio Grande Valley endocrinology deserts present first-mover advantage for telehealth-integrated pump onboarding as Medicaid expansion counties increase covered populations. Medicare National Coverage Determinations remove prior authorization barriers for Type 1 patients over 65 in Houston and Dallas-Fort Worth metropolitan areas. Hospital discharge protocols in San Antonio increasingly mandate insulin pump training for newly diagnosed patients.
Massachusetts
Greater Boston's academic medical centers anchor artificial pancreas research through NIH-funded clinical trials and pediatric endocrinology specialization. HIPAA privacy provisions constrain cloud-based glucose data sharing architectures, compelling vendors to invest in on-device processing protocols. Cambridge's biotech corridor attracts FDA-qualified algorithm developers commanding salary premiums over general medical device firmware engineers.
Florida
Retirement-age Medicare beneficiaries in Miami-Dade and Broward counties sustain demand for traditional tethered pumps with established reimbursement codes. Post-acute care discharge protocols embed pump training for newly diagnosed patients transitioning to home care management. Tampa Bay's growing endocrinology practice density supports patient onboarding for algorithm-enabled systems.
Illinois
Chicago's hospital supply relationships leverage long-standing FDA PMA pathway experience to sustain institutional procurement for perioperative glycemic management. Retail pharmacy pilot programs with certified diabetes educator support bypass traditional durable medical equipment channels in Cook County. Northwestern University's medical campus drives closed-loop algorithm prescribing influence through academic endocrinology departments.
United States Insulin Pumps Market Key Industry Players
Premium-margin players sit above commodity-margin players across algorithm sophistication and closed-loop automation capabilities. The vendor base consolidates around three structural tiers: diversified medical device conglomerates with hospital supply embeddedness, patch pump specialists eliminating tubing architecture, and algorithm-focused innovators capturing smartphone-integrated prescription decisions. Strategic moves concentrate on modular pump-to-sensor ecosystem bundling and telehealth-integrated patient onboarding to bypass traditional durable medical equipment channels.
Within the diversified conglomerate tier, Medtronic plc exemplifies long-standing FDA PMA pathway experience sustaining institutional procurement relationships. Among patch pump specialists, Insulet Corporation occupies a position defined by tube-free wearable configurations. On the algorithm-led vector, Tandem Diabetes Care, Inc. represents closed-loop automation leadership with Bluetooth-enabled smartphone control. These three anchors illustrate how technology differentiation and regulatory infrastructure shape competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Sooil Development Co., Ltd. |
| Medtronic plc |
| ViCentra BV |
| Bigfoot Biomedical, Inc. |
| Insulet Corporation |
| Ypsomed AG |
| Cellnovo Group plc |
| Tandem Diabetes Care, Inc. |
| Others |
Cost & Logistics Intelligence
Precision motor actuator costs from Japanese suppliers cascade through three-tier pricing stratification across premium closed-loop systems, standard tethered pumps, and economy patch configurations. FDA 21 CFR 870.2780 PMA pathway compliance expenses concentrate in premium tiers, while Medicare reimbursement expansion compresses price elasticity for algorithm-enabled devices in California and Texas home care markets.
Pricing Analysis
Subscription-based hardware-plus-algorithm bundling dominates the United States insulin pumps market, separating artificial pancreas configurations from automated insulin delivery systems and basic tethered devices. Price differentiation hinges on FDA quality system infrastructure depth and Bluetooth-enabled smartphone control integration, with algorithm sophistication commanding measurable premiums. Pricing pressure stems from retail pharmacy fulfillment pilots at CVS and Walgreens that bypass traditional durable medical equipment markups. Medicare-covered populations over 65 exhibit lowest price sensitivity; privately insured patients in price-sensitive segments defer adoption to standalone continuous glucose monitors.
Supply Chain Analysis
Micro-pump actuator supply rests on two Japanese precision motor manufacturers controlling upstream component flow. Raw material dependencies include medical-grade polymers for reservoir housing, lithium-ion cells for power management, and platinum-cured silicone for infusion set tubing. Single-source vulnerability in actuator manufacturing creates supply chain risk exposure from tariff fluctuations or geopolitical disruption. Distribution runs through hospital supply relationships for institutional procurement, with retail pharmacy channels gaining share through certified diabetes educator-supported fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States insulin pumps market represents a late-cycle quality story where algorithm-enabled hypoglycemia reduction shifts demand toward premium closed-loop specifications. Physician prescribing influence concentrates with endocrinology practices adopting artificial pancreas systems fastest.
For Market Incumbents: Lock in embedded hospital discharge protocols by deepening FDA PMA pathway experience and expanding certified diabetes educator training programs. Defend margin pools through backward integration into precision motor sourcing alternatives that reduce Japanese supplier dependency. Algorithm update velocity serves as the critical lever against patch pump specialists capturing tube-averse patient segments. For New Entrants and Emerging Players: Launch via telehealth-integrated onboarding models targeting Rio Grande Valley endocrinology deserts in Texas Medicaid expansion counties. White-space concentration sits with dual-hormone glucagon-insulin systems and retail pharmacy educator-supported fulfillment. Smartphone-native control interfaces offer the most penetrable wedge against legacy clinical sales channels in urban California markets. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA-qualified algorithm developer scarcity constrains vendor hiring pipelines and extends time-to-market for closed-loop feature rollouts. Long-term viability favors targets with existing quality system infrastructure and predicate device 510(k) supplement pathways. Watch CMS National Coverage Determination expansion for continuous glucose monitor-integrated pumps as the signal for reimbursement tailwind inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | PMA pathway experience accelerates algorithm update approvals for predicate devices. |
| Hospital System Partnership | Embedded discharge protocols create captive demand for newly diagnosed Type 1 patients. |
| Software Companion Development | Bluetooth-enabled smartphone control concentrates purchasing influence with patients. |
| Reimbursement Strategy | Medicare National Coverage Determinations remove prior authorization barriers for patients over 65. |
| Backward Integration | In-house precision motor sourcing reduces vulnerability to Japanese supplier concentration. |
Research Approach
Bottom-up home care setting modeling reconciled against top-down hospital supply tracking forms the analytical core. Primary interviews with endocrinologists, biomedical engineers, GPO contracts managers, and certified diabetes educators cross-validated against secondary sources including FDA 510(k) and PMA filings, CMS National Coverage Analysis documents, and hospital procurement databases. Triangulation between patient-level prescription data and institutional purchasing records ensures segmentation integrity across device type, technology tier, and distribution channel dimensions.
Historical trendline analysis of closed-loop algorithm adoption rates and Medicare reimbursement expansion patterns anchored projection frameworks across the analysis window. Segmentation modeling spanned device configuration, algorithm sophistication, care setting, and regional endocrinology practice density. CAGRs derived from regression-adjusted growth curves incorporating real-world registry data on A1C improvement and hypoglycemia event reduction. Forecast inputs included FDA software-as-a-medical-device guidance implementation pace and Medicaid expansion county penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA algorithm update pathway delays or precision motor supply disruptions. Projections reflect assumptions on CMS reimbursement continuity and HIPAA cloud architecture compliance cost trajectories. A small set of named triggers—dual-hormone system approval, retail pharmacy channel scale-up, and telehealth onboarding penetration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
Oxygen Generator Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Global Microkeratome Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Medical Coatings Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
Vascular Guidewires Market