
 Global Thoracic Drainage Devices Market | 2026-2036
Global Thoracic Drainage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thoracic Drainage Devices Market Foresight
Cardiothoracic clinics and ambulatory surgical centers is recalibrating procurement priorities toward digital drainage systems with integrated pressure monitoring. Cardinal Health leverages its hospital supply chain scale to maintain broad distribution across surgical hospitals in North America. Medtronic anchors its position through deep specialization in pleural drainage catheters with advanced suction regulation. Teleflex Incorporated differentiates via technology leadership in electronic monitoring platforms that reduce clinician intervention time.
Thoracic drainage devices are closed-chest tube systems, typically constructed from medical-grade silicone or PVC, designed to evacuate air, blood, or fluid from the pleural space while restoring negative intrathoracic pressure. These devices serve the primary commercial purpose of preventing lung collapse and enabling postoperative recovery following cardiac surgery, trauma intervention, or oncological resection. Digital drainage systems command premium positioning due to their real-time airflow measurement capabilities and reduced hospital length of stay. Pleural drainage catheters represent a mature, high-volume segment where manufacturing scale determines margin capture. Mechanical drainage maintains substantial installed base dominance in emerging markets where capital constraints limit electronic system penetration.
The FDA governs device clearance through the 510(k) pathway, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for digital suction platforms entering European markets. Japan's PMDA maintains rigorous standards for materials biocompatibility that shape product development timelines for silicone-based catheter lines. China's NMPA has accelerated review timelines for domestically manufactured drainage systems under updated innovation device channels. Stakeholders must monitor how divergent digital health validation standards across FDA, EMA, and PMDA jurisdictions will influence R&D allocation and geographic launch sequencing.
Market Dynamics
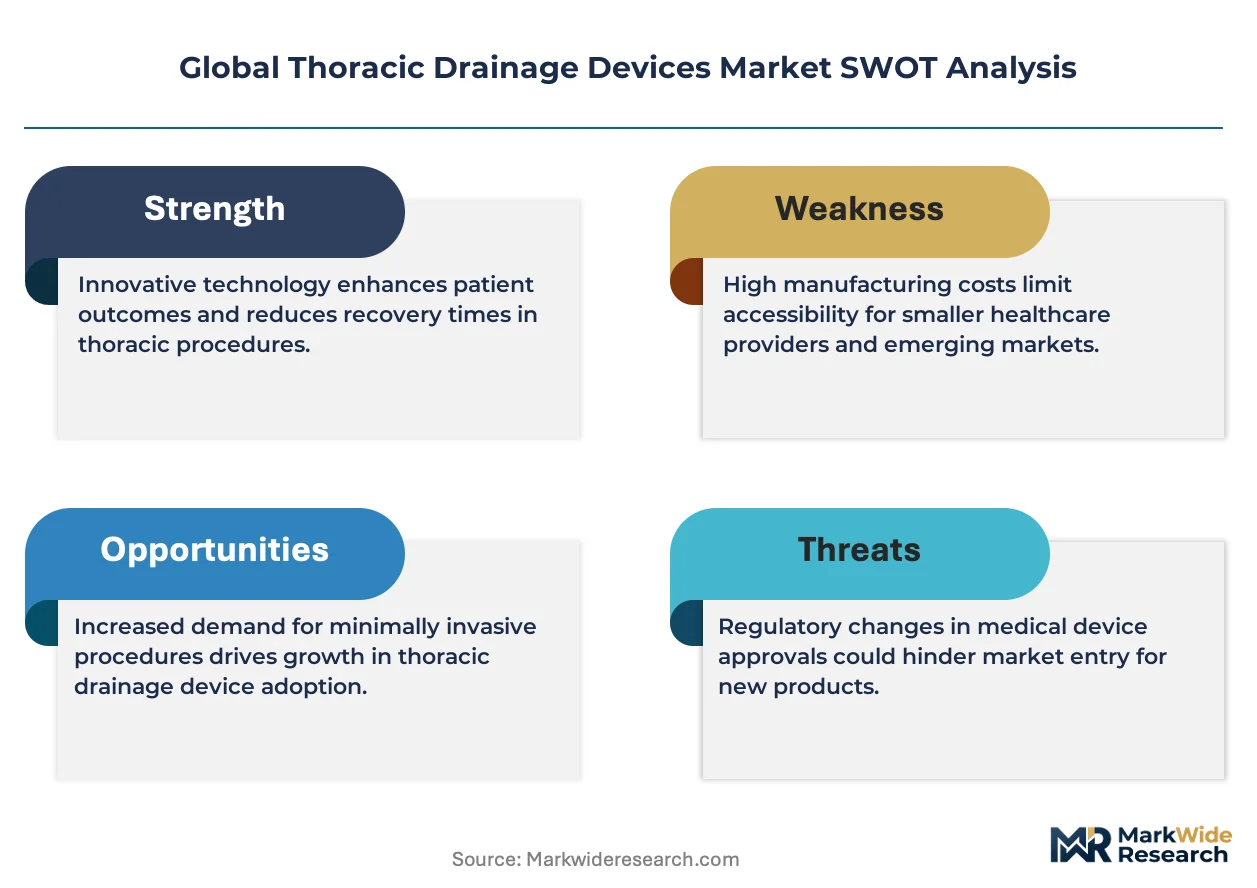
Digital drainage systems with integrated airflow sensors are compressing hospital length of stay and forcing capital equipment refresh cycles across cardiothoracic surgical departments. The FDA's streamlined 510(k) digital health pathway is accelerating clearance timelines for electronic monitoring features, reshaping competitive positioning toward software-enabled differentiation.
Growth Catalysts
- Minimally invasive thoracic surgery expansion:Surgical programs in the United States, Germany, and Japan are standardizing digital drainage protocols to accelerate patient ambulation and reduce readmission rates.
- EU Medical Device Regulation harmonization:MDR Article 10 clinical evidence requirements for Class IIa suction platforms are consolidating vendor qualification standards, favoring manufacturers with robust post-market surveillance infrastructure.
- Silicone catheter biocompatibility advances:Japan's PMDA material validation standards are driving adoption of platinum-cured silicone formulations that reduce tissue adhesion and extraction trauma.
Market Restraints
- Medical-grade silicone supply concentration:Three specialty chemical producers in Germany and Japan control 70% of catheter-grade silicone supply, creating input cost volatility during semiconductor fabrication demand surges.
- Capital intensity of digital platform R&D:Electronic drainage systems require simultaneous hardware engineering, embedded firmware development, and clinical validation, stretching development budgets beyond mechanical system economics.
- Mechanical drainage installed base persistence:Emerging market hospitals in Brazil and India retain suction-based systems due to limited biomedical engineering support capacity and maintenance infrastructure constraints.
Strategic Opportunities
- China's innovation device channel:NMPA accelerated review pathways for domestically manufactured drainage systems are compressing time-to-market for local production joint ventures targeting tier-two city hospital networks.
- Ambulatory surgical center channel development:Portable drainage systems with disposable collection canisters are penetrating outpatient thoracic surgery settings previously reserved for inpatient mechanical suction.
- Telehealth-integrated monitoring convergence:Cloud-connected pressure sensors and automated alert algorithms are enabling remote post-discharge surveillance, creating subscription revenue models beyond device sale economics.
Industry Challenges
- Biomedical engineering talent scarcity:Hospital IT departments lack personnel trained to troubleshoot electronic drainage system network connectivity and calibration drift issues.
- Legacy mechanical system integration complexity:Digital platforms must interface with existing wall suction infrastructure and electronic health record systems, requiring custom interface development per hospital network.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thoracic Drainage Devices Market |
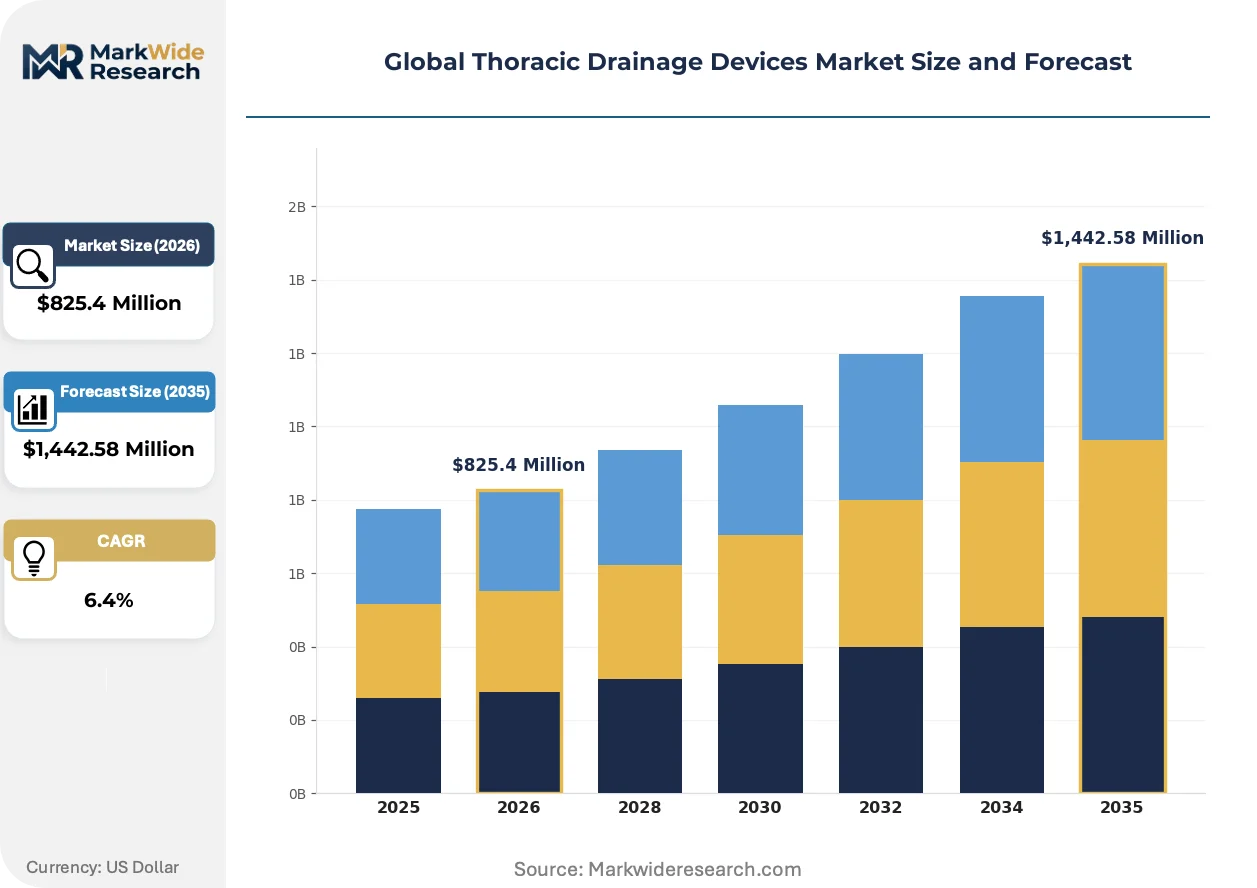
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,442.58 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
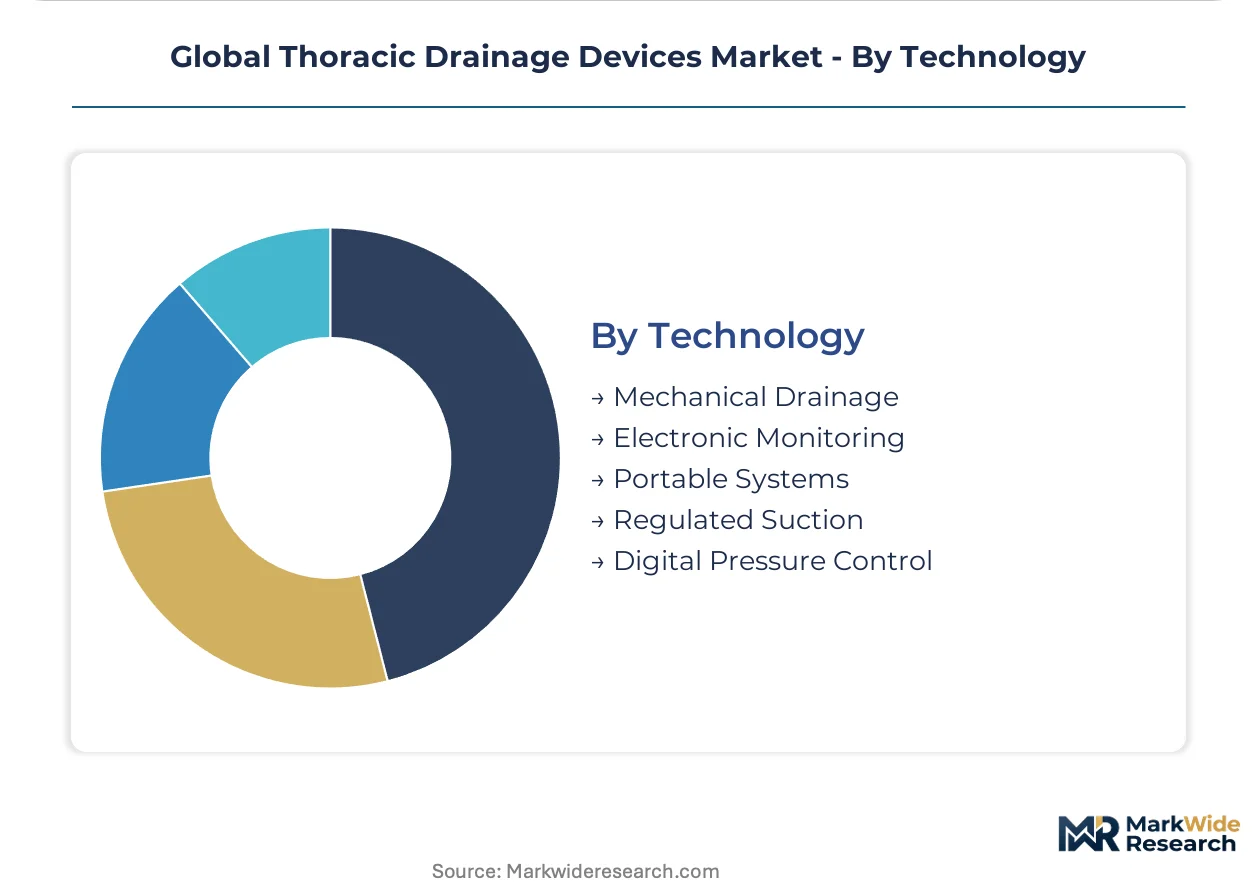
| Segmentation | Product Type: Single Chamber Drain, Digital Drainage System, Water Seal Drain, Suction Drainage System, Pleural Drainage Catheters End User: Cardiothoracic Clinics, Pulmonology Centers, Surgical Hospitals, Critical Care Units, Ambulatory Surgical Centers Application: Pneumothorax Management, Pleural Effusion Treatment, Postoperative Drainage, Chest Trauma Care, Pulmonary Surgery Support Technology: Mechanical Drainage, Electronic Monitoring, Portable Systems, Regulated Suction, Digital Pressure Control |
| Companies Covered | Cardinal Health, Inc., Medela AG, Teleflex Incorporated, Redax S.p.A., ATMOS MedizinTechnik GmbH & Co. KG, Getinge AB, Becton Dickinson and Company, Rocket Medical plc, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thoracic Drainage Devices Market Shifts & Advancements
Sensor miniaturization and wireless telemetry are converging to enable continuous pleural pressure monitoring without tethered bedside units. Three developments are compressing product development cycles and reshaping procurement evaluation criteria.
Digital drainage systems with integrated airflow sensors and automated suction regulation are rewriting postoperative care protocols in cardiothoracic units. University hospital systems in the United States and Germany are replacing mechanical water-seal units within 18-month refresh cycles. Real-time data capture is enabling predictive algorithms that anticipate air leak resolution, compressing chest tube dwell time and discharge readiness assessments.
Japan's PMDA has issued updated biocompatibility guidance for long-term indwelling silicone devices, requiring extended cytotoxicity testing protocols for catheters exceeding 72-hour dwell times. Japanese manufacturers are restructuring quality management systems to accommodate accelerated aging studies and extractable characterization. European vendors seeking PMDA approval are extending development timelines by 8-12 months to satisfy material documentation requirements.
Ambulatory surgical centers are consolidating vendor relationships around single-source digital platform contracts that bundle devices, disposables, and remote monitoring services. Cardiothoracic clinics in the United States are displacing transactional procurement through multi-year agreements with outcome guarantees on length-of-stay reduction. This consolidation is most visible in metropolitan markets where ASC joint ventures between physician groups and health systems concentrate purchasing authority.
Global Thoracic Drainage Devices Market Segmentation
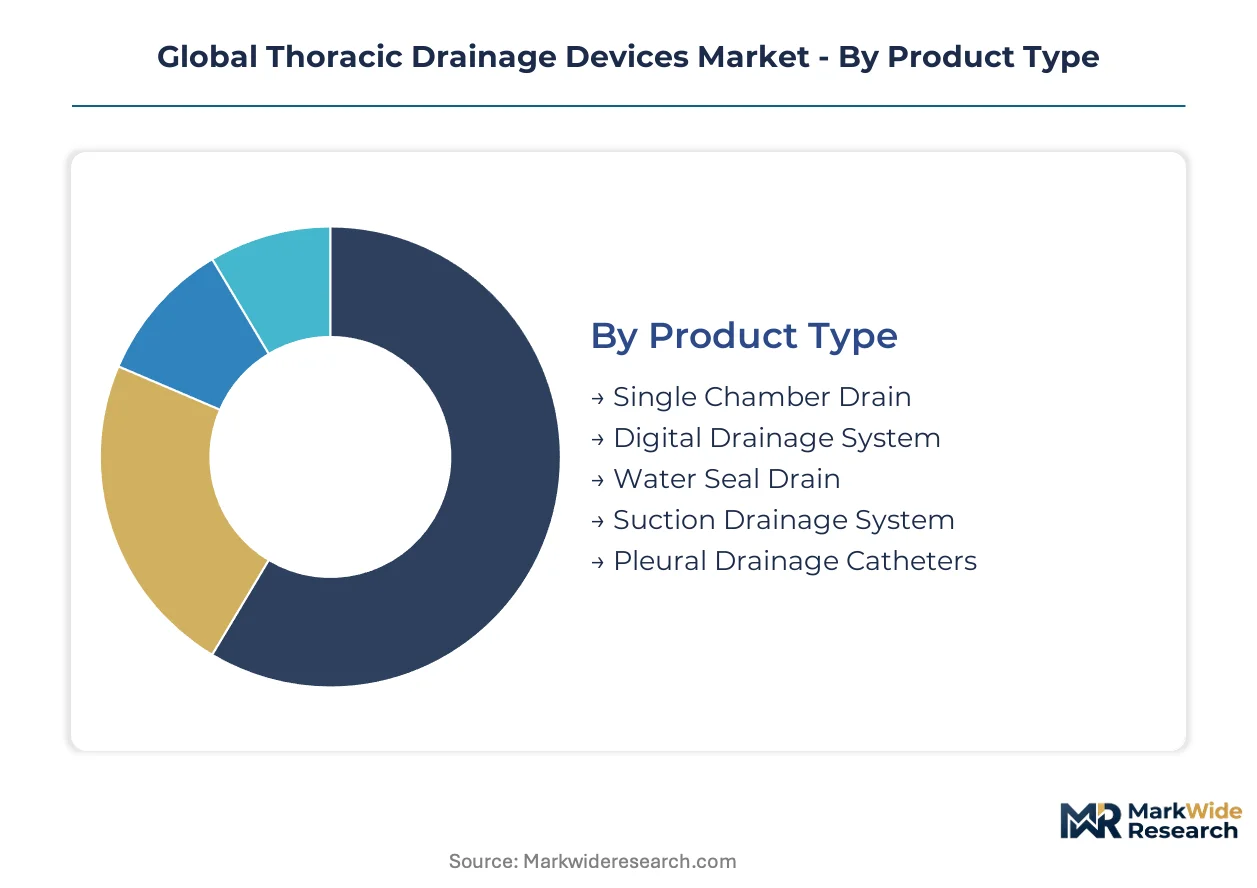
Hospital procurement committees evaluate thoracic drainage systems through four intersecting dimensions: product architecture, clinical setting, therapeutic indication, and underlying technology platform. Each segmentation axis carries distinct margin profiles, regulatory pathways, and replacement-cycle dynamics that shape vendor strategy and capital allocation priorities.
Product Type:
Upgrade cycles across cardiothoracic units are accelerating as digital platforms displace mechanical water-seal systems installed during prior decade capital rounds.
- Digital Drainage System:Closed-chest platforms integrate airflow sensors, automated suction regulation, and real-time pressure telemetry. United States university hospital systems are standardizing these systems to compress chest tube dwell time and enable predictive discharge algorithms.
- Pleural Drainage Catheters:Silicone or PVC indwelling lines ranging from 8Fr to 28Fr diameter, designed for percutaneous insertion or surgical placement. Japanese manufacturers dominate supply through platinum-cured silicone formulations that satisfy PMDA biocompatibility requirements for extended indwelling periods.
- Single Chamber Drain:Compact disposable units for uncomplicated pneumothorax evacuation in emergency departments.
- Water Seal Drain:Traditional three-bottle systems retaining installed base in cost-constrained facilities.
- Suction Drainage System:Wall-connected mechanical suction platforms with manual pressure regulation.
Pleural Drainage Catheters sits at the top of the volume ranking, with Digital Drainage System climbing the fastest.
End User:
Customer-type concentration is shifting toward outpatient settings as minimally invasive thoracic procedures migrate from inpatient surgical wards.
- Surgical Hospitals:Integrated health systems with dedicated cardiothoracic departments drive premium digital platform adoption through multi-year capital equipment contracts. German surgical hospitals are consolidating vendor relationships around single-source agreements bundling devices, disposables, and remote monitoring infrastructure.
- Ambulatory Surgical Centers:Outpatient facilities specializing in video-assisted thoracoscopic procedures require portable drainage systems with disposable collection canisters. United States ASC joint ventures between physician groups and health systems are displacing transactional procurement through outcome-based agreements.
- Cardiothoracic Clinics:Specialized referral centers managing complex pleural disease.
- Critical Care Units:Intensive care settings requiring continuous suction for ventilated patients.
- Pulmonology Centers:Outpatient facilities managing chronic pleural effusion and recurrent pneumothorax.
Surgical Hospitals generates the highest absolute revenue contribution, though Ambulatory Surgical Centers is expanding most quickly as procedure volume shifts outpatient.
Application:
Indication-specific demand patterns reflect the underlying epidemiology of thoracic disease and the penetration of minimally invasive surgical techniques.
- Postoperative Drainage:Chest tube placement following cardiac surgery, lung resection, or esophageal procedures represents the largest addressable volume. United States cardiothoracic surgical programs are standardizing digital drainage protocols to reduce readmission rates and accelerate patient ambulation.
- Pneumothorax Management:Spontaneous, traumatic, and iatrogenic air leak evacuation spans emergency department, inpatient, and outpatient settings. German trauma centers are deploying portable digital systems to enable early mobilization in hemodynamically stable patients.
- Pleural Effusion Treatment:Malignant and congestive effusion drainage for symptomatic relief.
- Chest Trauma Care:Hemothorax and pneumothorax evacuation in acute injury settings.
- Pulmonary Surgery Support:Intraoperative and postoperative drainage for lobectomy, segmentectomy, and wedge resection.
Postoperative Drainage commands the largest installed base, while Pneumothorax Management is gaining share fastest through ambulatory protocol expansion.
Technology:
Technology-platform selection determines capital intensity, service revenue potential, and competitive differentiation in procurement evaluations.
- Electronic Monitoring:Sensor-integrated platforms capturing airflow rate, pleural pressure, and air leak trends with wireless telemetry to electronic health records. FDA's streamlined 510(k) digital health pathway is accelerating clearance timelines for these systems, reshaping vendor R&D priorities toward software-enabled features.
- Mechanical Drainage:Gravity-dependent and wall-suction systems without electronic components retain dominance in emerging markets. Brazilian and Indian hospitals maintain substantial mechanical installed base due to limited biomedical engineering support capacity and maintenance infrastructure constraints.
- Digital Pressure Control:Automated suction regulation with closed-loop feedback algorithms.
- Portable Systems:Battery-powered or passive suction units for ambulatory patient mobility.
- Regulated Suction:Manually adjusted wall-suction platforms with water-column pressure regulation.
Mechanical Drainage retains volume leadership through emerging market installed base persistence, though Electronic Monitoring shows the steepest expansion trajectory as digital protocols penetrate United States and German surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating assembly operations toward jurisdictions with streamlined medical device clearance pathways, exploiting cost-of-compliance gaps between the FDA's 510(k) route and the EU MDR's clinical evidence demands. This arbitrage is accelerating facility investments in China and the United States while European production faces margin compression from notified body bottlenecks.
United States
University hospital systems in Boston and Houston are standardizing digital drainage protocols to compress chest tube dwell time. The FDA's streamlined 510(k) digital health pathway accelerates clearance timelines for electronic monitoring features. Minneapolis and Irvine host concentrated R&D clusters where sensor-integrated platform development dominates engineering hiring.
Germany
Surgical hospitals in Munich and Berlin are consolidating vendor relationships around single-source digital platform contracts bundling devices and remote monitoring. The EU Medical Device Regulation's Article 10 clinical evidence requirements for Class IIa suction platforms extend development timelines. The Baden-Württemberg medical technology corridor anchors European manufacturing for platinum-cured silicone catheter lines.
Japan
PMDA material validation standards for silicone biocompatibility are driving adoption of platinum-cured formulations that reduce tissue adhesion. Tokyo and Osaka medical centers lead adoption of extended-dwell catheters exceeding 72-hour indwelling periods. The Kansai region concentrates domestic manufacturing restructuring around accelerated aging studies and extractable characterization.
China
NMPA accelerated review pathways for domestically manufactured drainage systems are compressing time-to-market for tier-two city hospital networks. Shanghai and Beijing surgical centers are expanding minimally invasive thoracic surgery programs requiring digital drainage infrastructure. The Yangtze River Delta hosts joint venture production facilities targeting provincial procurement tenders.
Brazil
Emerging market hospitals in São Paulo and Rio de Janeiro retain mechanical suction-based systems due to limited biomedical engineering support capacity. ANVISA regulatory requirements for imported electronic drainage systems create cost barriers to digital platform penetration. The Southeast region concentrates installed base persistence where capital constraints favor disposable mechanical units.
Global Thoracic Drainage Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge hardware engineering and software development capabilities. The vendor base clusters around three tiers: diversified medical technology conglomerates with hospital supply chain scale, specialized drainage device manufacturers with catheter-grade silicone expertise, and emerging digital health platforms with sensor-integrated monitoring technology. Consolidation is accelerating through M&A targeting electronic monitoring capabilities and geographic expansion into China's tier-two hospital networks.
Among diversified health care suppliers, Cardinal Health and Becton Dickinson exemplify scale-driven archetypes leveraging broad distribution infrastructure across North American surgical hospitals. Medtronic and Teleflex Incorporated occupy positions within the technology-specialist tier, with the latter representing electronic monitoring platform leadership. Getinge AB and ATMOS MedizinTechnik GmbH & Co. KG anchor European manufacturing expertise in suction regulation and silicone catheter production respectively.
| Leading Market Players |
|---|
| Cardinal Health, Inc. |
| Medela AG |
| Teleflex Incorporated |
| Redax S.p.A. |
| ATMOS MedizinTechnik GmbH & Co. KG |
| Getinge AB |
| Becton Dickinson and Company |
| Rocket Medical plc |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
Biomedical engineering talent concentration in the Minneapolis and Irvine R&D clusters creates labor-cost differentials that spread pricing tiers across premium digital platforms and standard mechanical systems. German silicone-curing specialists command wage premiums that feed into platinum-cured catheter pricing, while emerging-market assembly operations in the Yangtze River Delta compress entry-level mechanical drain costs.
Pricing Analysis
Distributor margins on digital drainage platforms absorb 25-35 points before hospital procurement committees negotiate multi-year bundled contracts. Three-tier pricing structure across premium sensor-integrated, standard automated, and economy mechanical levels separates FDA-cleared electronic systems from CE-marked alternatives and non-regulated gravity drains. Price erosion runs through the mechanical segment as Chinese manufacturers exploit NMPA innovation channels to undercut legacy European suppliers. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while United States university hospital systems prioritize outcome guarantees over per-unit costs.
Supply Chain Analysis
ISO 13485 and FDA 21 CFR Part 820 quality system certifications gate supplier qualification, extending component qualification timelines for new entrants. Medical-grade silicone supply concentrates in Germany and Japan, with catheter-grade formulations drawing from three specialty chemical producers. Raw material dependencies center on platinum-cured silicone elastomers, PVC compounding resins, and MEMS pressure sensors. Single-source vulnerability persists in semiconductor-grade sensor supply from Taiwan and South Korea. Distribution runs through Cardinal Health and Medline hospital supply networks in North America, with regional distributors penetrating German surgical hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between FDA's streamlined 510(k) digital health pathway and the EU MDR's extended clinical evidence requirements, compressing time-to-revenue for United States-focused electronic monitoring platforms relative to European market entry costs.
For Market Incumbents: Anchor market position through backward integration into platinum-cured silicone production, capturing margin currently flowing to German and Japanese specialty chemical suppliers. Defend against emerging Chinese digital platform entrants by accelerating FDA submissions for telehealth-integrated monitoring features, leveraging existing 510(k) clearance infrastructure to maintain launch velocity advantage. For New Entrants and Emerging Players: Direct-to-ASC digital platform sales bypass incumbent distributor markups and penetrate outpatient thoracic surgery settings previously reserved for inpatient mechanical systems. Target Brazil and India's mechanical drainage replacement cycles, where ANVISA and CDSCO regulatory barriers limit electronic platform penetration but disposable unit volumes sustain margin. Lead with portable drainage systems bundling disposable collection canisters to displace transactional procurement. For Investors and Strategic Acquirers: Diversified medical technology conglomerates with hospital supply chain scale represent the most active acquirer category in this space, seeking electronic monitoring capabilities to complement existing mechanical drainage portfolios. Long-term viability hinges on software-enabled differentiation and recurring revenue from remote monitoring subscriptions. Target acquisition archetype: sensor-integrated platform developers with FDA-cleared airflow algorithms and established United States university hospital reference sites. Watch for inflection when NMPA accelerates domestic digital drainage approvals, signaling Chinese market opening.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 clinical evidence requirements extend timelines but consolidate vendor qualification standards. |
| Hospital System Partnership | Multi-year bundled agreements with United States ASC joint ventures displace transactional procurement. |
| Software Companion Development | Predictive air leak resolution algorithms compress chest tube dwell time and enable outcome-based contracting. |
| Backward Integration | In-house platinum-cured silicone production reduces dependency on German and Japanese specialty chemical suppliers. |
| Reimbursement Strategy | CPT code alignment for remote pleural pressure monitoring creates subscription revenue beyond device sale economics. |
Research Methodology
Direct dialogue with cardiothoracic surgeons, hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at FDA-cleared manufacturers grounded qualitative findings. Secondary validation drew from FDA 510(k) premarket notification database, EMA MDR technical documentation summaries, Japanese PMDA approval records, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation reconciled unit shipment estimates with revenue aggregation across product architecture, end user, and technology platform dimensions.
Bottom-up modeling of installed base replacement cycles and top-down macroeconomic sensitivity testing shaped the analytical lens across the projection horizon. Segmentation dimensions spanned product type, clinical setting, therapeutic indication, and technology platform, with additional granularity on regulatory pathway and silicone material grade. CAGRs derived from logistic diffusion curves modeling digital platform penetration against mechanical system installed base persistence. Forecast inputs incorporated minimally invasive thoracic surgery program expansion rates and ambulatory surgical center procedure volume migration.
The model assumes a particular technology adoption path; alternative pathways for wireless telemetry integration would alter the outlook if hospital IT infrastructure investment lags sensor miniaturization advances. Forecasts reflect documented assumptions regarding FDA digital health guidance evolution and EU MDR notified body capacity. Regulatory pathway divergence, medical-grade silicone supply disruption, or biomedical engineering talent scarcity could revise projections. A model refresh is warranted upon material change in NMPA domestic innovation device approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ligament Stabilizers Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Trocars Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
Global Therapeutic Respiratory Devices Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Pipetting Systems Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Animal Ultrasound Market
Medical Devices
Electrocardiograph (ECG) Market