
 PMS and Menstrual Health Supplements Market | 2026-2036
PMS and Menstrual Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
PMS and Menstrual Health Supplements Market Intelligence
DSHEA enforcement modernization is realigning the cost-of-entry calculus for new supplement entrants, forcing reformulation investments and third-party certification spending that favors scaled incumbents. Amway leverages its global direct-sales infrastructure to sustain physician-adjacent credibility in hormonal balance formulations. GNC Holdings anchors its retail footprint with in-store nutritional counselor staffing that competes against pure-play e-commerce brands. Pharmavite differentiates through USP-verified mineral sourcing that controls quality narrative at shelf.
PMS and menstrual health supplements comprise orally administered nutritional and botanical formulations containing standardized extracts of chasteberry, evening primrose oil, magnesium, vitamin B6, and L-tryptophan, manufactured through cold-press extraction, spray-drying, and tablet compression processes to deliver cyclical symptom modulation and micronutrient repletion. The product type dimension shows herbal segments occupying the deepest margin pools due to premium positioning of traceable botanical supply chains, while vitamins sustain volume leadership through pharmacy channel ubiquity. Application-focused segmentation reveals symptom relief leading current consumption patterns, with mood enhancement representing the fastest-growing structural pocket as psychodermatology and cycle-syncing wellness narratives reshape consumer self-identification.
FDA cGMP inspections, USP verification programs, and FTC substantiation standards collectively govern product claims, manufacturing fidelity, and advertising integrity across this market, with non-compliance triggering warning letters that freeze channel access. The EU's novel food authorization under EFSA guidance creates parallel compliance architecture for brands seeking cross-border expansion. Stakeholders must monitor emerging state-level labeling legislation and decide whether to front-run stricter purity thresholds or absorb reactive reformulation costs.
Market Dynamics
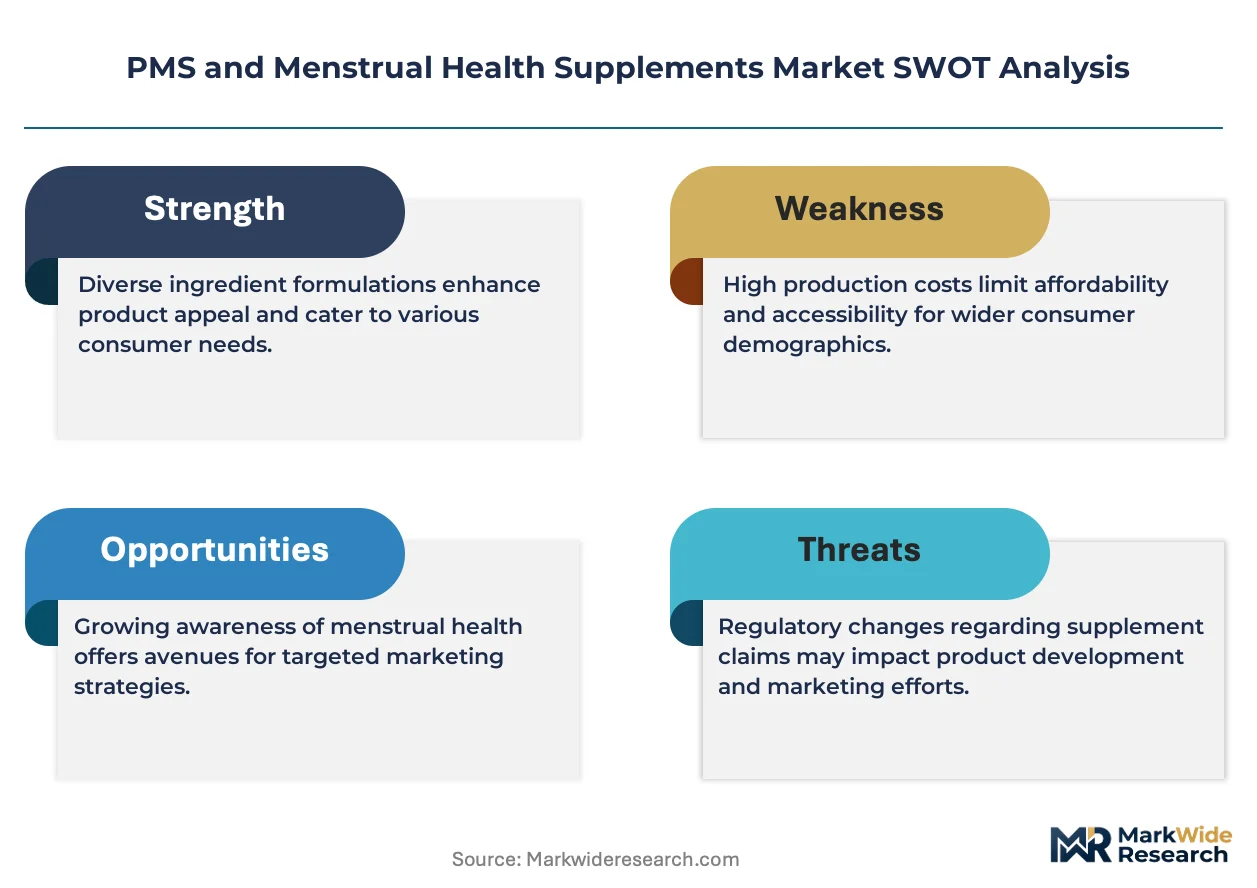
DSHEA enforcement modernization is tightening quality verification requirements, forcing reformulation investments and third-party certification spending that favors scaled incumbents over new entrants in the PMS and menstrual health supplements space.
Growth Catalysts
- Subscription replenishment models:Urban professional women in the United States are adopting auto-replenishment services that lock in recurring revenue streams and reduce customer acquisition costs for direct-to-consumer brands.
- FTC substantiation standards:Stricter advertising integrity requirements are professionalizing marketing claims and elevating consumer trust in clinically positioned formulations.
- Cycle-syncing wellness narratives:Psychodermatology and hormonal balance content on social platforms is converting symptom-aware consumers into supplement purchasers at earlier life stages.
Market Restraints
- Botanical supply concentration:Traceable chasteberry and evening primrose oil sourcing concentrates in Eastern European and South American growing regions, exposing margins to climate volatility and geopolitical disruption.
- USP verification bottlenecks:Limited third-party testing capacity creates months-long queue delays for brands seeking quality differentiation at retail.
- Pharmaceutical substitution:Low-dose hormonal contraceptives prescribed for PMS symptom management compete directly with supplement positioning in physician conversations.
Strategic Opportunities
- Functional gummy format expansion:Palatable delivery systems are capturing non-pill-averse consumers in pharmacy and mass retail channels previously dominated by tablets.
- EU novel food authorization:EFSA-compliant brands can access cross-border expansion into European markets where botanical supplement penetration lags US levels.
- Mood enhancement applications:L-tryptophan and vitamin B6 formulations targeting luteal-phase anxiety represent an underdeveloped structural pocket with premium pricing potential.
Industry Challenges
- Formulation science talent scarcity:Clinical nutritionists with hormonal health specialization command premium compensation, constraining mid-market brand R&D staffing.
- cGMP compliance capex:Cold-press extraction and spray-drying equipment upgrades require seven-figure facility investments that strain emerging manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PMS and Menstrual Health Supplements Market |
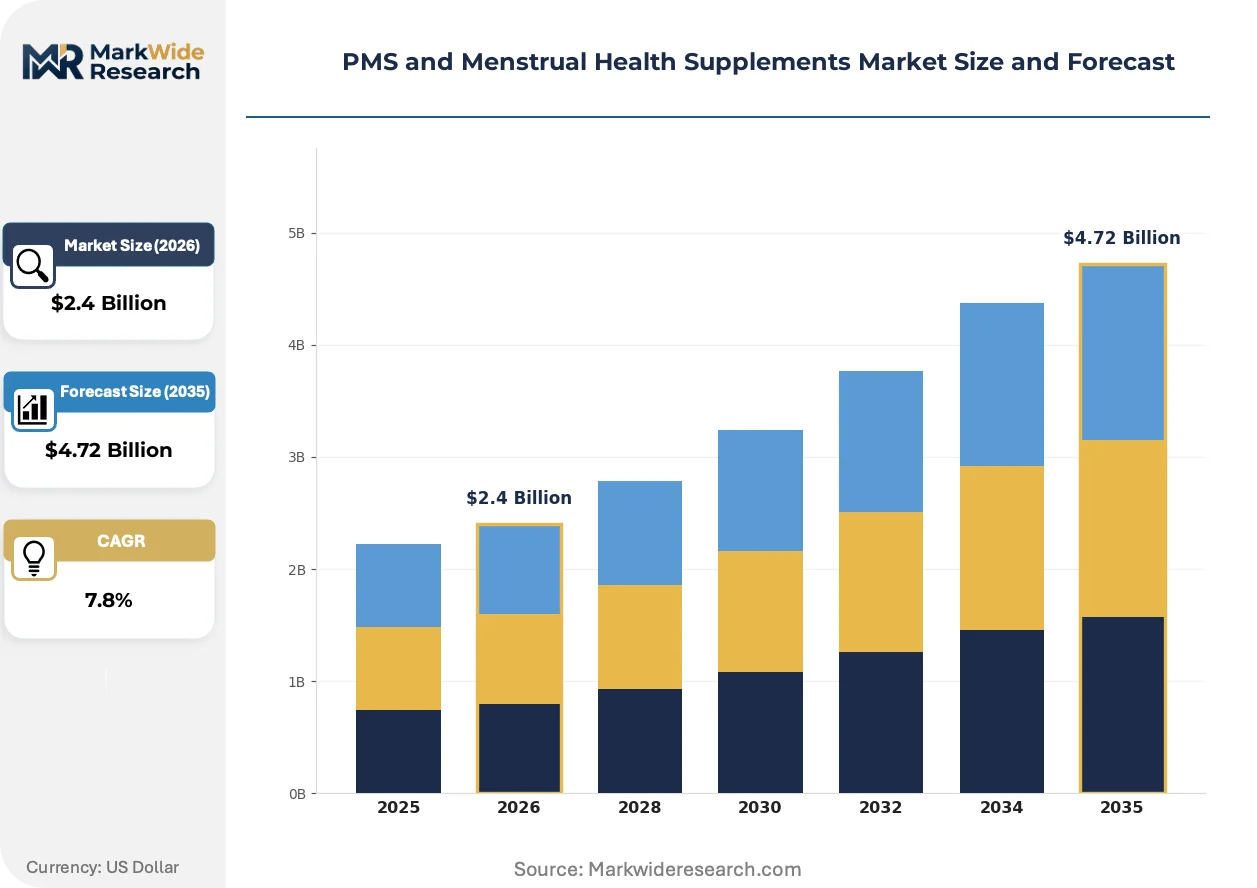
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal, Vitamins, Minerals, Amino Acids Application: Symptom Relief, Nutritional Support, Hormonal Balance, Mood Enhancement End User: Women, Healthcare Providers, Nutritional Counselors, Fitness Trainers Distribution Channel: Online Retail, Pharmacies, Health Stores, Direct Sales |
| Companies Covered | Amway, GNC Holdings, Inc., Herbalife International of America, Inc., Power Gummies, Pharmavite LLC, Nature's Bounty, USANA Health Sciences, Inc., Archer Daniels Midland, GlaxoSmithKline Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PMS and Menstrual Health Supplements Market Strategic Shifts & Innovations
Consumer self-identification around menstrual cycle awareness is reshaping how supplement brands formulate, position, and distribute products across pharmacy, direct-to-consumer, and wellness retail channels.
Functional gummy delivery systems is overtaking traditional tablet and capsule formats as the preferred consumption method among Millennial and Gen-Z buyers seeking palatable, portable dosing options. Subscription-based wellness platforms are accelerating gummy adoption through sample-inclusive onboarding flows that reduce trial friction. The shift is compressing shelf space allocation for legacy tablet SKUs in mass retail and forcing incumbent brands to retool manufacturing lines.
FDA cGMP inspection intensity has intensified post-DSHEA modernization, with warning letter volume rising for botanical identity testing failures and adulteration detection. Manufacturers are responding by investing in in-house chromatography capabilities and supplier audit programs that extend three tiers deep into raw material chains. Smaller brands lacking capital for vertical quality infrastructure face channel freeze-out as retailers demand documentation packages that only scaled players can assemble.
Cycle-tracking app integration is emerging as a decisive purchase trigger, with consumers expecting supplement recommendations synchronized to predicted symptom windows. Direct-to-consumer brands are embedding their SKUs within Flo, Clue, and Stardust platform ecosystems, displacing standalone e-commerce discovery. This behavior concentrates most visibly in the United States, where app penetration among reproductive-age women exceeds comparable markets by significant margins.
PMS and Menstrual Health Supplements Market Segmentation
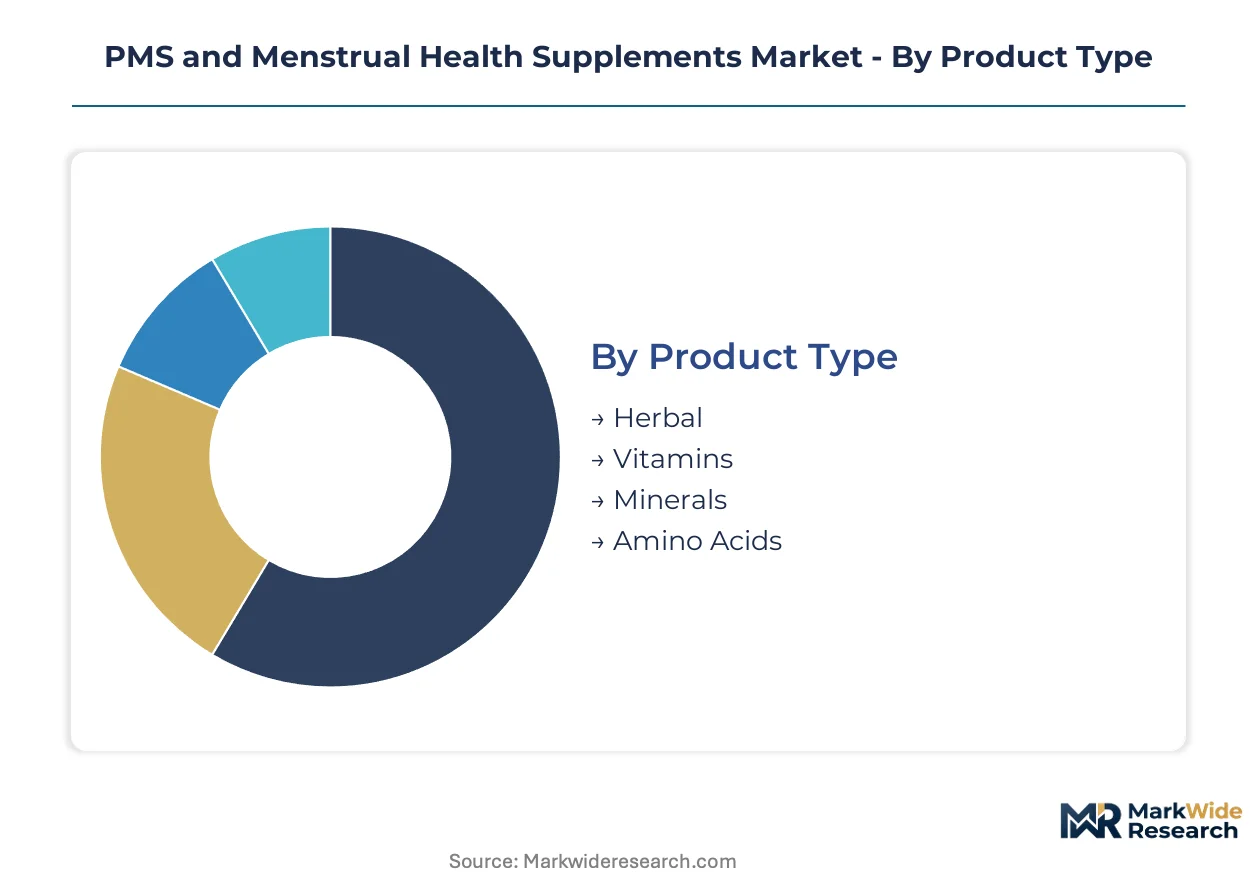
Segmentation in the PMS and menstrual health supplements market determines regulatory pathway complexity and margin architecture. Each dimension carries distinct certification burdens that reshape competitive positioning and channel access strategies.
Product Type:
FDA cGMP inspections and USP verification programs apply differentially across these categories, with botanical formulations facing the heaviest identity testing requirements.
- Herbal:Standardized extracts of chasteberry and evening primrose oil require cold-press extraction and chromatographic verification. Traceable supply chains from Eastern European growing regions command premium positioning in United States direct-to-consumer channels.
- Vitamins:Vitamin B6 formulations dominate pharmacy shelf presence through USP-verified sourcing. Mass retail ubiquity sustains volume leadership despite compressed margins relative to botanical segments.
- Minerals:Magnesium oxide and glycinate variants support cyclical micronutrient repletion protocols.
- Amino Acids:L-tryptophan positioning targets luteal-phase serotonin modulation with specialized manufacturing controls.
Vitamins sits at the top of the volume ranking, with Herbal climbing the fastest.
Application:
FTC substantiation standards and clinical claim requirements vary sharply across these use cases, forcing brands to calibrate marketing investment against evidentiary burden.
- Symptom Relief:Cramp and bloating formulations represent the largest current consumption cluster. United States urban professional women drive replenishment through subscription platforms.
- Mood Enhancement:L-tryptophan and vitamin B6 combinations targeting luteal-phase anxiety are gaining share fastest. Cycle-syncing wellness content on social platforms converts symptom-aware consumers at earlier life stages.
- Hormonal Balance:Chasteberry-based protocols compete against low-dose contraceptive prescriptions in physician-adjacent positioning.
- Nutritional Support:General micronutrient repletion appeals to preventive wellness seekers with lower symptom severity.
Symptom Relief captures the deepest revenue pool currently, though Mood Enhancement is expanding most quickly.
End User:
Prescription influence and professional recommendation patterns fragment demand across these stakeholder groups with divergent trust mechanisms.
- Women:Direct purchasers responding to cycle-tracking app recommendations and peer-validated social content. Self-directed discovery concentrates in Millennial and Gen-Z demographics.
- Healthcare Providers:Physicians and nurse practitioners evaluating supplement alternatives to hormonal contraceptives for PMS management.
- Nutritional Counselors:In-store advisors at GNC and specialty retailers steering formulation selection.
- Fitness Trainers:Cycle-syncing protocol advocates integrating supplements into training program design.
Women generate the dominant transaction volume, with Healthcare Providers representing the steepest expansion trajectory as clinical credibility professionalizes.
Distribution Channel:
Documentation requirements and quality verification intensity scale with channel format, freezing out undercapitalized entrants from premium retail placement.
- Online Retail:Direct-to-consumer brands embed SKUs within Flo and Clue app ecosystems. Subscription replenishment models lock in recurring revenue and reduce acquisition costs.
- Pharmacies:USP verification and third-party certification serve as table stakes for shelf placement. Functional gummy formats are displacing legacy tablet SKUs.
- Health Stores:Staffed nutritional counseling competes against pure-play e-commerce through personalized protocol design.
- Direct Sales:Amway leverages global physician-adjacent credibility through personalized hormonal balance consultations.
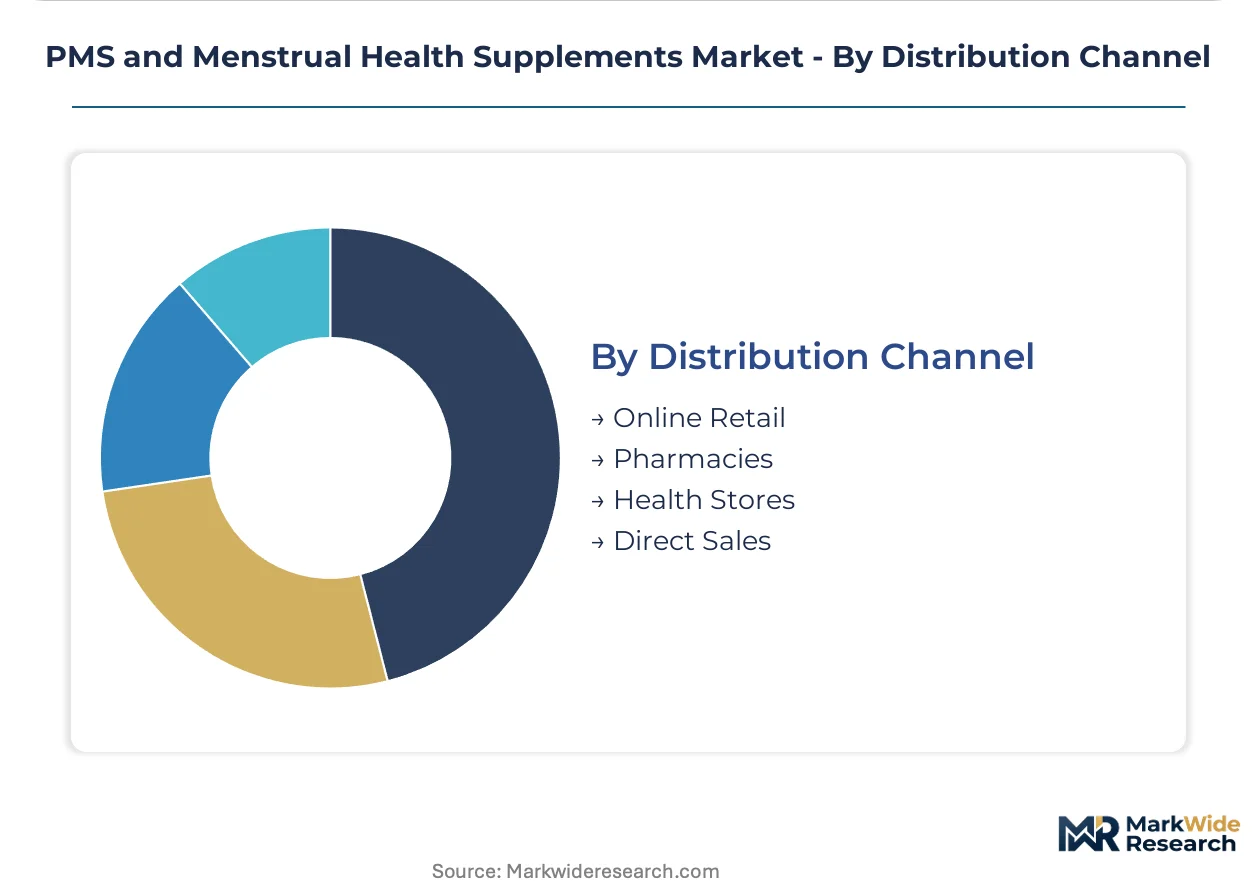
Online Retail leads transaction volume, with Pharmacies gaining share fastest as gummy adoption accelerates in mass retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban professional women in the United States anchor workforce-driven supplement adoption, with cycle-tracking app penetration creating concentrated demand clusters in coastal metropolitan areas.
United States
Subscription replenishment models lock in recurring revenue from Millennial and Gen-Z consumers in New York and Los Angeles. FDA cGMP inspection intensity has intensified post-DSHEA modernization, with warning letter volume rising for botanical identity testing failures. Functional gummy formats displace legacy tablet SKUs in mass retail channels across the Northeast Corridor.
Germany
Healthcare provider influence steers hormonal balance formulation selection in Berlin and Munich medical corridors. EFSA novel food authorization creates parallel compliance architecture for brands seeking cross-border expansion from German manufacturing bases. Traceable chasteberry supply chains from Eastern European growing regions concentrate quality verification investments in Bavaria.
United Kingdom
Direct-to-consumer wellness platforms accelerate adoption among London-based urban professionals seeking cycle-syncing protocols. The Medicines and Healthcare products Regulatory Agency enforces borderline product classifications that reshape marketing claim boundaries. Nutritional counselor staffing at health stores in Greater Manchester competes against pure-play e-commerce discovery.
India
Preventive wellness seekers in Maharashtra and Karnataka drive micronutrient repletion demand among lower symptom severity segments. FSSAI labeling requirements and Ayush ministry guidelines govern botanical formulation marketing. Manufacturing clusters in Gujarat process standardized herbal extracts for export-oriented production.
Australia
Fitness trainer protocol integration captures cycle-syncing consumers in Sydney and Melbourne wellness ecosystems. TGA complementary medicine regulations mandate evidence tiers that stratify permissible advertising claims. In-house chromatography capabilities at Queensland facilities respond to retailer documentation demands.
PMS and Menstrual Health Supplements Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where scaled incumbents absorb regulatory compliance costs that freeze out emerging entrants. Pharmaceutical-adjacent nutrition divisions leverage physician credibility networks, while direct-to-consumer brands embed SKUs within cycle-tracking app ecosystems. Three archetypes dominate: vertically integrated manufacturers controlling raw material sourcing, platform-native digital brands, and retail-anchored nutritional counseling operations. Competitive moves concentrate on third-party certification acquisition and functional format retooling.
Among direct-sales infrastructure operators, Amway leverages global physician-adjacent credibility. GNC Holdings, Inc. anchors retail-anchored positioning through staffed nutritional counselor networks. Pharmavite LLC occupies the quality-verification tier through USP-validated mineral sourcing protocols that control shelf-level narrative.
| Leading Market Players |
|---|
| Amway |
| GNC Holdings, Inc. |
| Herbalife International of America, Inc. |
| Power Gummies |
| Pharmavite LLC |
| Nature's Bounty |
| USANA Health Sciences, Inc. |
| Archer Daniels Midland |
| GlaxoSmithKline Plc |
| Others |
Cost & Logistics Intelligence
Evening primrose oil futures indexed to Argentine and Chinese spot markets cascade through three distinct pricing tiers as cold-press extraction costs concentrate margin pressure on mid-market brands lacking captive supply. Subscription bundling of gummy formats with cycle-tracking app integrations commands premium positioning against unbundled tablet SKUs in pharmacy channels.
Pricing Analysis
Subscription-versus-transactional bundling splits the market between auto-replenishment platforms and single-purchase pharmacy formats. Three-tier pricing structure across premium, standard, and economy levels reflects USP verification status and traceable botanical sourcing depth. Cost compression in economy-tier vitamin B6 tablets is intensifying because mass retail buyers negotiate volume rebates that squeeze contract manufacturers. Direct-to-consumer subscribers show least price sensitivity; pharmacy cash buyers exhibit highest elasticity.
Supply Chain Analysis
Direct-to-consumer channels handle Millennial and Gen-Z demand through Flo and Clue app ecosystem integrations. Raw material sourcing draws from Eastern European chasteberry cultivars, South American evening primrose estates, and Chinese magnesium processing facilities. Cold-press extraction equipment and chromatographic testing capacity constitute critical bottlenecks. Single-source vulnerability concentrates in traceable botanical supply chains where climate volatility disrupts harvest yields. Distribution runs through subscription platforms, pharmacy chains, and health store networks with divergent documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DSHEA enforcement modernization compounds regulatory compliance costs into sustainable competitive moats, with FDA warning letter volume acceleration driving demand for third-party verified formulations.
For Market Incumbents: Anchor shelf positioning through USP verification investment that freezes out undercapitalized entrants from pharmacy channel access. Defend against pure-play e-commerce disintermediation by embedding SKUs within Clue and Stardust cycle-tracking ecosystems. Prioritize in-house chromatography capabilities over outsourced testing to compress quality verification timelines.
For New Entrants and Emerging Players: Cycle-tracking API integration offers a technology-first wedge against established brands reliant on standalone e-commerce discovery. Target mood enhancement applications with L-tryptophan formulations where clinical claim substantiation requirements remain less stringent than hormonal balance positioning. Pursue sample-inclusive subscription onboarding flows that reduce trial friction among urban professional women.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated botanical processors controlling Eastern European and South American raw material access. Long-term viability hinges on regulatory compliance infrastructure that appreciates across tightening FDA and EFSA frameworks. Monitor EFSA novel food authorization queue velocity as inflection signal for European market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Acquisition | FDA cGMP compliance documentation unlocks pharmacy shelf placement against unverified competitors. |
| Cycle-Tracking App Integration | Flo and Clue platform embedding displaces standalone e-commerce discovery for Millennial buyers. |
| Cold-Press Extraction Scale-Up | In-house botanical processing captures margin pools from outsourced standardized extract suppliers. |
| Functional Gummy Format Launch | Palatable delivery systems convert non-pill-averse consumers in mass retail pharmacy channels. |
| EFSA Novel Food Authorization | Cross-border European expansion accesses underpenetrated botanical supplement demand in Germany and UK. |
Research Approach
Bottom-up subscription platform modeling reconciled against top-down raw material import tracking forms the analytical core of this study. Primary interviews with direct-to-consumer brand founders, pharmacy category buyers, contract manufacturing executives, and nutritional counselor staff at health stores combined with secondary validation against FDA warning letter databases, USP verification registries, and EFSA novel food submission logs. Triangulation across these sources yields volume estimates segmented by product type, application, and distribution channel.
Input-output matrices map chasteberry and evening primrose oil supply flows through cold-press extraction and spray-drying processing stages into finished gummy, tablet, and capsule formats. Segmentation dimensions span herbal, vitamin, mineral, and amino acid product types; symptom relief, mood enhancement, hormonal balance, and nutritional support applications; and online retail, pharmacy, health store, and direct sales channels. CAGRs derive from regression analysis of historical replenishment velocity and projected cycle-tracking app penetration curves across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA inspection intensity escalation and botanical supply climate disruption. Projections reflect assumptions around DSHEA enforcement modernization pace and EFSA authorization throughput capacity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
LAMEA Digestive Enzymes Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Eye Health Ingredients Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Pycnogenol Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
High Potency Apis Market