
 Spain Aesthetic Devices Market | 2026-2036
Spain Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Aesthetic Devices Market Analytics
The EU Medical Device Regulation (MDR) is shifting procurement criteria across Spanish aesthetic practices, forcing upgrades to CE-marked systems with enhanced clinical evidence. Hologic Inc. (Cynosure) anchors its position through Cynosure's established laser platform installed base across Iberian dermatology chains. Alma Lasers (Sisram Medical) competes on RF and ultrasound modalities tailored to clinic workflows. AbbVie (Allergan Aesthetics) dominates the injectables channel through Botox and Juvéderm brand strength in Spanish medical aesthetics.
Spain aesthetic devices encompass energy-based systems, injectable biologics, and mechanical apparatus designed for non-surgical cosmetic procedures, typically operating at wavelengths between 532 nm and 10,600 nm for laser platforms or utilizing 20-40 kHz ultrasound frequencies for adipose tissue disruption. These systems serve commercial purposes by enabling clinics to offer minimally invasive alternatives to plastic surgery with reduced recovery intervals. Laser devices occupy the largest revenue pool given their capital intensity and recurring consumable revenue, while injectables capture superior margins through repeat purchase cycles. RF technology leads growth velocity as Spanish clinics adopt combination platforms merging thermal energy with microneedling for collagen induction protocols.
Spain's national pharmaceutical regulator, the Spanish Agency for Medicines and Health Products (AEMPS), enforces MDR compliance timelines and post-market surveillance obligations that filter non-compliant vendors from the market. The EU AI Act introduces additional conformity requirements for algorithm-driven diagnostic and treatment planning modules embedded in next-generation devices. Stakeholders must monitor AEMPS guidance on software-as-a-medical-device classifications to preempt market access disruptions.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing vendor timelines and forcing Spanish aesthetic clinics to retire legacy laser platforms that lack updated clinical evidence packages. This regulatory pressure is reshaping procurement criteria across Madrid and Barcelona dermatology chains, creating a structural bottleneck for device manufacturers seeking market access.
Growth Catalysts
- MDR Compliance Mandate:The EU Medical Device Regulation requires enhanced post-market surveillance and clinical data, filtering out non-compliant vendors and creating upgrade cycles for CE-marked systems across Spanish aesthetic practices.
- RF-Microneedling Combination Protocols:Radiofrequency technology merged with fractional microneedling is expanding treatment menus in Spanish clinics, driving capital expenditure on multi-modality platforms for collagen induction therapies.
- Madrid-Barcelona Clinic Expansion:Dermatology chains concentrated in Spain's two largest metropolitan areas are broadening device portfolios to capture medical tourism flows from Latin America and North Africa.
Market Restraints
- MDR Certification Costs:The EU Medical Device Regulation imposes substantial documentation and notified body fees on manufacturers, compressing margins for mid-tier device vendors serving the Spanish market.
- Laser Platform Capital Intensity:High upfront investment requirements for picosecond and fractional laser systems restrict clinic adoption outside Madrid and Barcelona's premium aesthetic centers.
- Injectable Biologics Substitution:Botulinum toxin and hyaluronic acid fillers compete directly with energy-based devices for facial rejuvenation revenue, capturing repeat purchase loyalty through lower per-treatment capital requirements.
Strategic Opportunities
- Andalusia and Valencia Clinic Penetration:Aesthetic device density remains below Madrid-Barcelona levels in Spain's southern and eastern regions, offering first-mover positioning for RF and ultrasound platform vendors.
- EU AI Act Software Integration:Algorithm-driven treatment planning modules embedded in next-generation devices create differentiation pathways for vendors navigating AEMPS software-as-a-medical-device classifications.
- Combination Platform Convergence:Merging laser, RF, and ultrasound modalities into single systems reduces clinic footprint requirements and capital allocation friction for Spanish aesthetic practices.
Industry Challenges
- MDR Technical Documentation Gap:Spanish aesthetic device distributors face compressed timelines to assemble clinical evaluation reports and post-market surveillance systems for legacy platform portfolios.
- Specialized Technician Scarcity:Operating advanced laser and RF systems requires certified medical aestheticians, a credential pipeline that AEMPS and regional health authorities have not scaled to match device deployment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Aesthetic Devices Market |
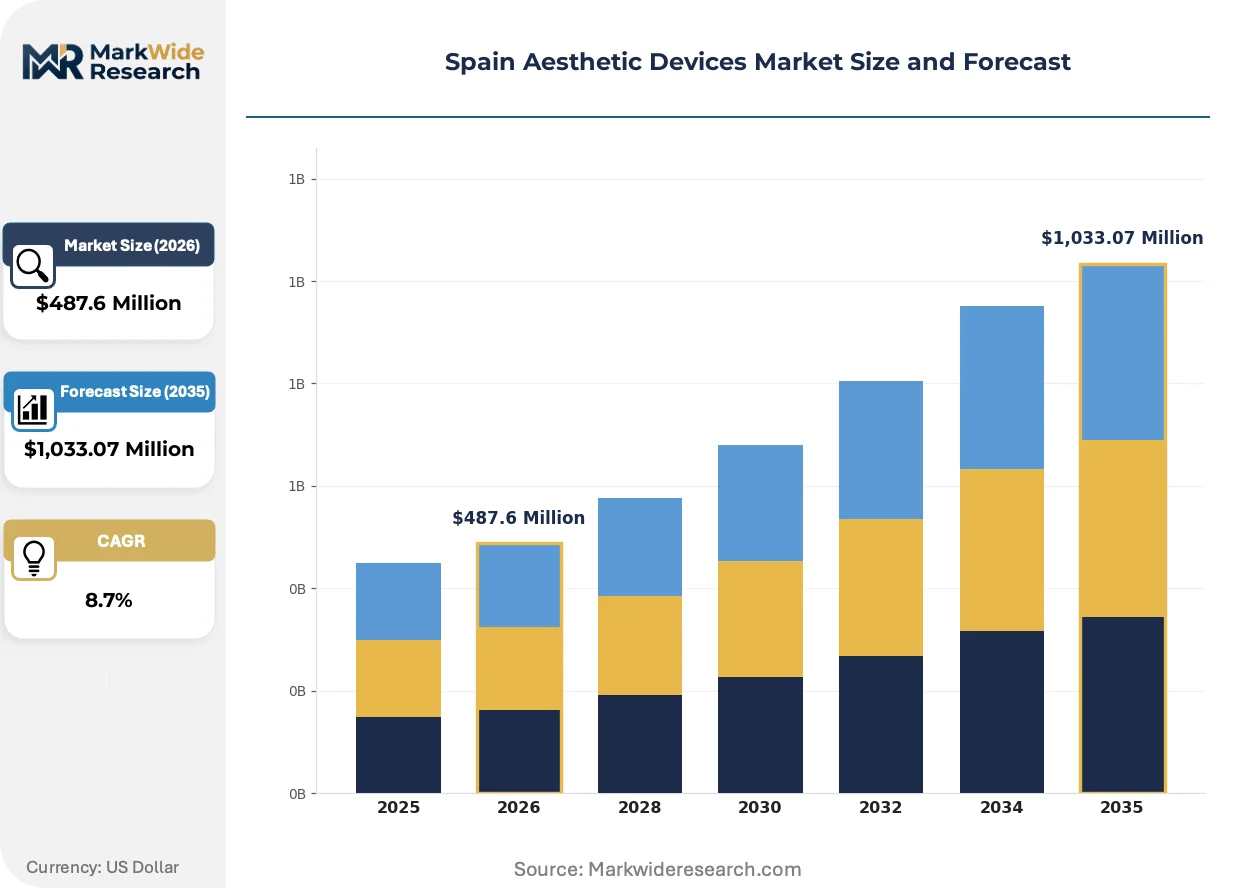
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Injectables, Skin Resurfacing, Body Contouring Technology: RF Technology, Ultrasound, LED Therapy, IPL End User: Clinics, Hospitals, Beauty Salons, Home Users Application: Facial Rejuvenation, Hair Removal, Acne Treatment, Scar Reduction |
| Companies Covered | Hologic Inc. (Cynosure), Alma Lasers (Sisram Medical), Cutera Inc., Lutronic Corporation, Galderma SA, AbbVie (Allergan Aesthetics), Lumenis, Venus Concept, Bausch + Lomb (Solta Medical), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Aesthetic Devices Market Evolving Landscape
Technology convergence is displacing single-modality platforms across Spanish aesthetic clinics, with combination systems capturing preference share through reduced treatment intervals and expanded indication ranges. Regulatory digitization and AI-driven diagnostic modules are embedding compliance deeper into device architecture.
Radiofrequency microneedling is converging with ultrasound adipose disruption in next-generation Spanish clinic platforms, enabling sequential collagen remodeling and non-surgical body contouring within single patient visits. Dermatology chains in Madrid are adopting these converged systems at twice the rate of standalone RF or ultrasound devices. This convergence is compressing capital deployment cycles by consolidating multiple revenue streams into single platform purchases.
The EU AI Act is imposing conformity requirements on algorithm-driven diagnostic modules embedded in aesthetic treatment planning software, forcing AEMPS to clarify software-as-a-medical-device classifications. Device manufacturers must now submit AI/ML documentation alongside traditional technical files for market authorization. Spanish clinics deploying next-generation platforms are prioritizing vendors with established EU AI Act compliance pathways over those with pending regulatory strategies.
Spanish aesthetic practices are unbundling after-sales service contracts from capital equipment purchases, negotiating standalone maintenance agreements with third-party biomedical engineering firms. This disintermediation of OEM service channels is most visible among Barcelona's independent dermatology clinics, which are aggregating device maintenance across multiple brands through regional service consortiums. The shift is compressing manufacturer service margins while extending equipment operational lifespans through competitive maintenance pricing.
Spain Aesthetic Devices Market Segmentation
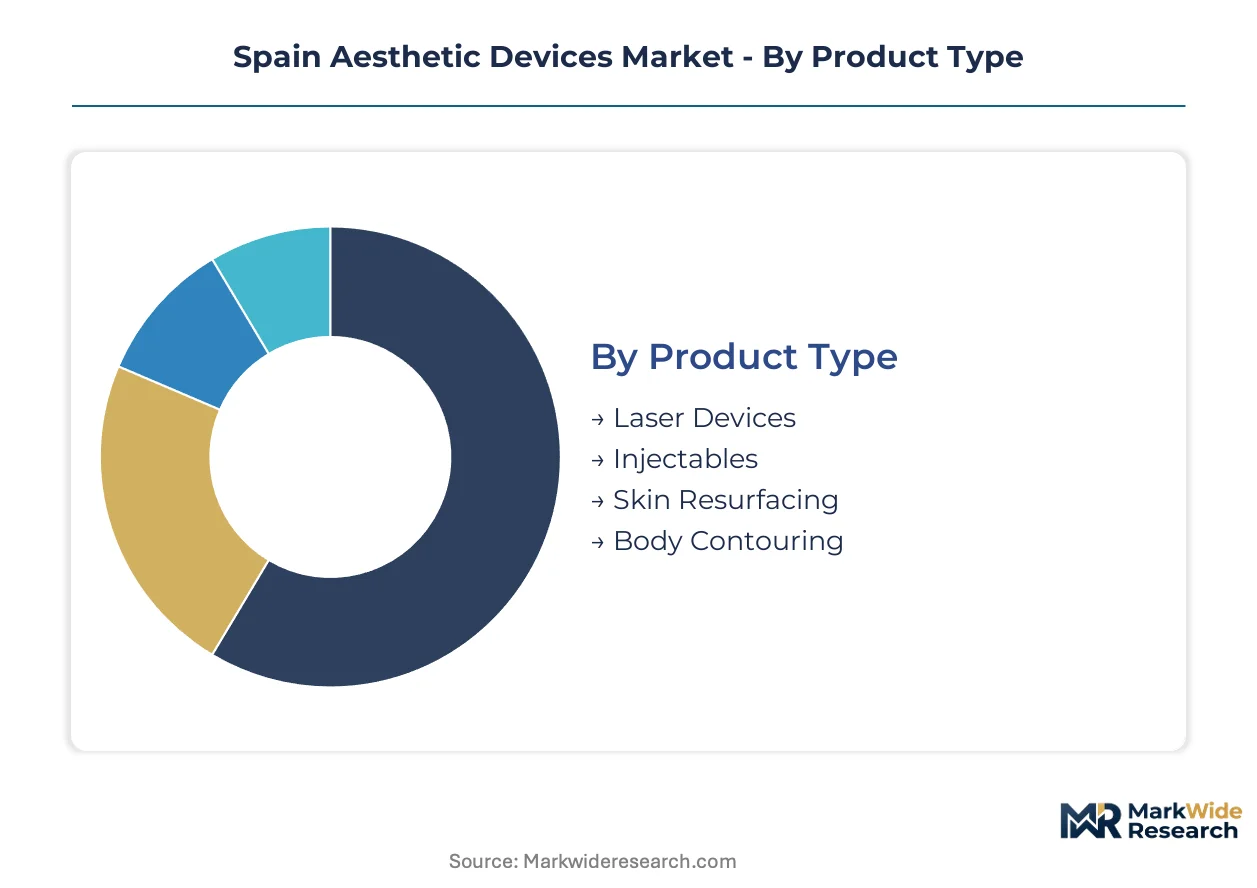
Segmentation in Spain's aesthetic devices market reveals distinct procurement patterns across Madrid and Barcelona's dermatology chains versus smaller regional clinics. Each dimension—product type, technology, end user, and application—carries specific regulatory and capital requirements under AEMPS oversight.
Product Type:
Supply concentration in laser platforms anchors procurement budgets across Spanish aesthetic practices, while injectables command recurring revenue streams through repeat purchase cycles.
- Laser Devices:Energy-based systems operating across 532 nm to 10,600 nm wavelengths deliver fractional resurfacing, vascular lesion treatment, and pigmentation correction. Madrid's premium dermatology chains concentrate demand here, driven by medical tourism flows from Latin America requiring advanced capital equipment visibility.
- Injectables:Botulinum toxin and hyaluronic acid formulations enable facial volume restoration and dynamic wrinkle reduction without capital infrastructure. Barcelona's independent clinics prioritize these for lower per-treatment overhead and faster patient turnover protocols.
- Skin Resurfacing:Mechanical and chemical modalities including microdermabrasion and fractional RF systems target epidermal renewal with reduced downtime.
- Body Contouring:Non-surgical adipose disruption technologies span cryolipolysis and ultrasound platforms for circumference reduction.
Laser devices absorb the bulk of installed capacity; injectables are expanding most quickly through subscription-style replenishment models.
Technology:
Cost tier differentiation separates premium combination platforms from standalone modalities, with RF-integrated systems commanding price premiums in Spanish clinic procurement.
- RF Technology:Radiofrequency energy delivers thermal collagen remodeling through monopolar, bipolar, and fractional delivery mechanisms. Andalusia and Valencia clinics are adopting RF-microneedling combinations fastest, capitalizing on lower capital barriers versus laser platforms.
- Ultrasound:High-intensity focused ultrasound and 20-40 kHz adipose disruption technologies enable non-invasive lifting and fat reduction. Madrid dermatology chains deploy these for body contouring revenue streams complementary to facial aesthetics.
- LED Therapy:Photobiomodulation systems utilizing specific wavelength arrays target inflammation reduction and post-procedure recovery acceleration.
- IPL:Intense pulsed light platforms deliver broadband energy for hair removal and photorejuvenation with lower device cost entry points.
RF technology absorbs the bulk of installed capacity; ultrasound platforms are gaining share fastest through combination system integration.
End User:
Customer type determines regulatory compliance depth, with clinical settings facing AEMPS MDR documentation requirements absent from home-use channels.
- Clinics:Specialized aesthetic and dermatology practices across Madrid, Barcelona, Valencia, and Seville constitute the primary procurement channel. These entities prioritize CE-marked systems with established post-market surveillance pathways to satisfy AEMPS inspection protocols.
- Hospitals:Plastic surgery departments within Spain's public and private hospital networks acquire capital-intensive laser platforms for reconstructive and cosmetic procedure integration.
- Beauty Salons:Non-medical aesthetic centers operate under lighter regulatory frameworks, concentrating demand in IPL and LED modalities below medical device thresholds.
- Home Users:Consumer-directed devices for hair removal and skin cleansing represent emerging distribution through pharmacy and e-commerce channels.
Clinics absorb the bulk of installed capacity; home users are climbing the fastest through direct-to-consumer device launches.
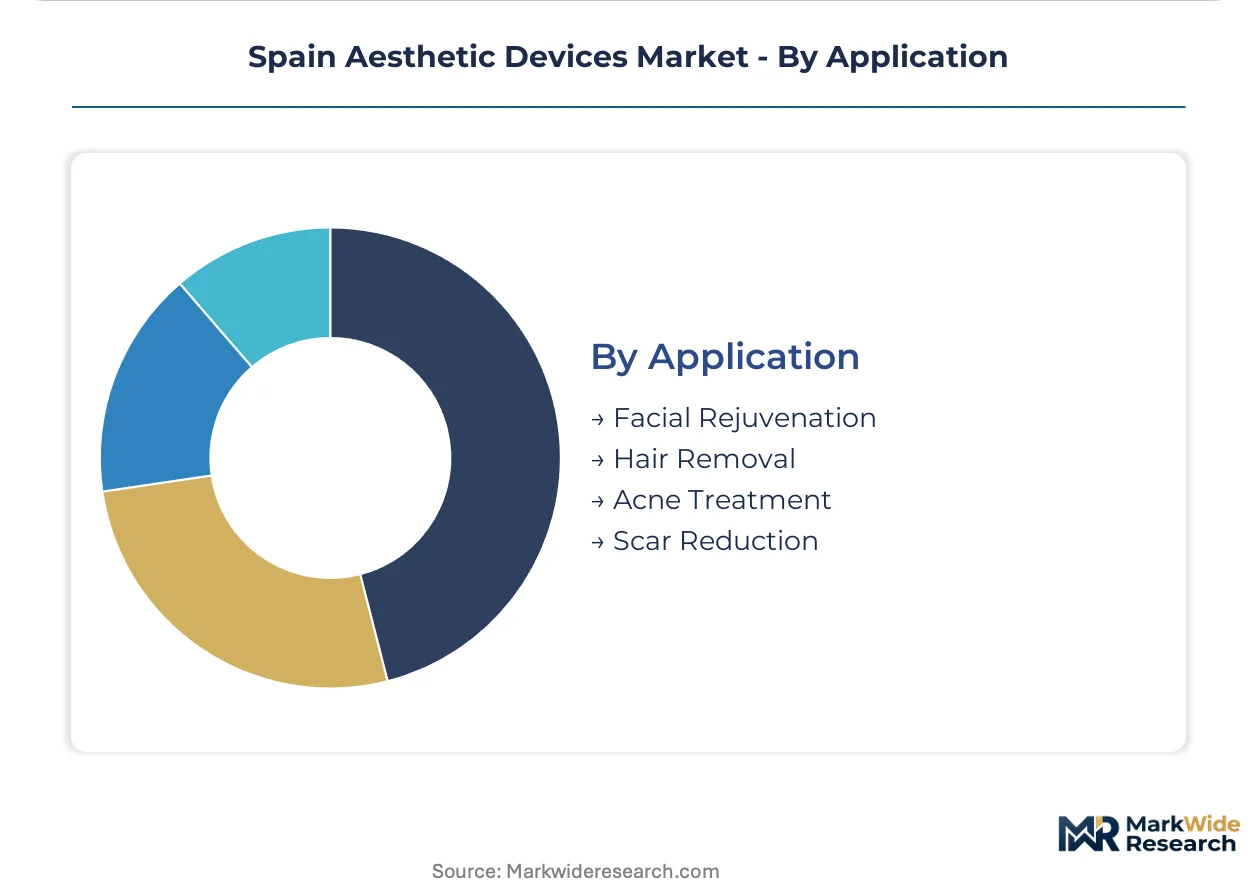
Application:
Volume concentration in facial rejuvenation reflects Spain's aging demographic profile and medical tourism positioning, while hair removal sustains steady replacement cycles.
- Facial Rejuvenation:Comprehensive treatment protocols combining neuromodulators, fillers, and energy-based skin tightening address photoaging and volume loss. Barcelona's clinic networks concentrate demand here, driven by competitive positioning for Mediterranean coastal medical tourism.
- Hair Removal:Laser and IPL platforms target permanent hair reduction across Fitzpatrick skin types prevalent in Spain's population. Replacement demand for legacy diode systems is accelerating under MDR compliance deadlines.
- Acne Treatment:Blue light, photodynamic therapy, and RF-based sebaceous gland modulation address inflammatory and cystic presentations.
- Scar Reduction:Fractional laser and microneedling protocols target traumatic, surgical, and acne-related textural irregularities.
Facial rejuvenation absorbs the bulk of installed capacity; scar reduction is gaining share fastest through expanded indication claims for combination platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's aesthetic devices market concentrates consumption in Madrid and Barcelona while manufacturing capacity remains concentrated among multinational suppliers. Production flows from Germany, the United States, and Israel into Spanish clinic networks. Regional disparities in device penetration create distinct procurement patterns across autonomous communities.
Madrid
Medical tourism from Latin America and North Africa drives premium laser platform demand in Madrid's dermatology chains. AEMPS inspection protocols enforce MDR compliance timelines for CE-marked systems. The capital's clinic networks deploy combination RF-ultrasound platforms at twice the rate of standalone modalities.
Catalonia
Barcelona's independent aesthetic clinics prioritize injectable biologics for lower per-treatment overhead and faster patient turnover. The region's health authority enforces post-market surveillance obligations under EU MDR frameworks. Coastal medical tourism positioning concentrates facial rejuvenation demand along the Costa Brava corridor.
Andalusia
Device density remains below Madrid-Barcelona levels, creating first-mover positioning for RF and ultrasound platform vendors. Spain's national pharmaceutical regulator filters non-compliant vendors through enhanced clinical evidence requirements. Seville's emerging clinic networks adopt capital equipment with reduced footprint requirements.
Valencia
Eastern Spain exhibits growing demand for LED therapy and IPL modalities below premium laser price tiers. Regional health authorities coordinate with AEMPS on software-as-a-medical-device classifications for AI-embedded platforms. Valencia's clinic expansion targets Mediterranean medical tourism flows with combination platform procurement.
Basque Country
Industrial purchasing power supports premium capital equipment acquisition in Bilbao and San Sebastián aesthetic centers. The region's strong healthcare infrastructure aligns with MDR technical documentation requirements for device distributors. Basque clinic networks concentrate on scar reduction and acne treatment applications.
Spain Aesthetic Devices Market Competitive Landscape
The competitive structure tilts toward multinational conglomerates with diversified aesthetic portfolios. Vendor concentration remains moderate, with five to eight firms capturing significant share across laser, RF, and injectable segments. Strategic archetypes include integrated medical technology conglomerates, specialized energy-based device manufacturers, and pharmaceutical-aesthetic hybrids. M&A activity and technology licensing agreements dominate competitive moves as firms seek combination platform capabilities.
Among diversified medical technology conglomerates, Hologic Inc. (Cynosure) and AbbVie (Allergan Aesthetics) occupy positions exemplifying scale-driven market presence. Alma Lasers (Sisram Medical) represents the specialized energy-based device archetype with focused RF and ultrasound expertise. These three firms anchor competitive dynamics through distinct strategic postures: conglomerate breadth versus specialized modality depth.
| Leading Market Players |
|---|
| Hologic Inc. (Cynosure) |
| Alma Lasers (Sisram Medical) |
| Cutera Inc. |
| Lutronic Corporation |
| Galderma SA |
| AbbVie (Allergan Aesthetics) |
| Lumenis |
| Venus Concept |
| Bausch + Lomb (Solta Medical) |
| Others |
Value Network & Pricing Analysis
Captive distribution networks through Madrid and Barcelona's dermatology chains anchor both procurement leverage and manufacturer pricing power across Spain's aesthetic device sector. OEMs retain margin control through bundled after-sales service contracts, though clinic consortiums are disintermediating these arrangements to compress lifetime ownership costs.
Pricing Analysis
Margin tightening in mid-tier laser platforms reflects MDR certification cost pass-throughs and notified body fee inflation. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked combination systems from standalone RF devices and non-certified legacy units. Pricing pressure intensifies in the injectables channel as AbbVie's Botox and Juvéderm franchises capture repeat purchase loyalty with lower per-treatment capital requirements. Independent clinics in Barcelona exhibit highest price sensitivity, while Madrid's medical tourism-facing chains absorb premium positioning for Latin American patient visibility.
Supply Chain Analysis
EU MDR local-content compliance timelines are reshaping sourcing patterns, with notified body proximity in Germany and the Netherlands becoming a procurement filter. Manufacturing concentrates in Israel, the United States, and Germany, with Alma Lasers' Israeli production and Hologic's US assembly feeding Iberian distribution. Supply chains rest on precision optical components, RF generators, and ultrasound transducers from specialized component vendors. Single-source vulnerability in semiconductor-based laser control modules creates bottleneck exposure. Distribution runs through AEMPS-authorized medical device distributors with regional service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's aesthetic device market operates as a supply-constrained environment where MDR certification capacity bottlenecks prop pricing power for compliant vendors. AEMPS inspection backlogs and notified body queue delays limit rapid competitive entry.
For Market Incumbents: To counter disintermediation of OEM service contracts by Barcelona clinic consortiums, Hologic and Alma Lasers should deepen captive service networks through regional biomedical engineering partnerships. Certification investment in EU AI Act compliance pathways for algorithm-driven treatment modules creates differentiation against mid-tier vendors lacking documentation resources. Channel control through exclusive distributor relationships in Andalusia and Valencia protects first-mover positioning where device density remains below Madrid-Barcelona levels. For New Entrants and Emerging Players: The price-point gap between premium combination platforms and economy IPL devices creates entry space for RF-microneedling specialists targeting Seville and Valencia clinic networks. Andalusia's underpenetrated aesthetic device market offers the most penetrable geography, with reduced footprint requirements and lower capital barriers than Madrid's premium segment. Direct-to-clinic technical training partnerships with AEMPS-accredited credentialing bodies provide a go-to-market angle that addresses specialized technician scarcity. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified medical technology conglomerates seeking combination platform capabilities. Long-term viability favors vendors with established MDR technical documentation and post-market surveillance infrastructure. Acquisition target archetypes include specialized RF-ultrasound platform manufacturers with EU AI Act compliance progress. The signal to watch is AEMPS guidance acceleration on software-as-a-medical-device classifications, which will filter non-compliant AI-embedded systems from reimbursement pathways.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR compliance timelines compress competitive windows for legacy platform vendors. |
| Combination Platform Development | Merging laser, RF, and ultrasound modalities reduces clinic capital allocation friction. |
| Hospital System Partnership | Public and private hospital plastic surgery departments anchor reconstructive device demand. |
| Software Companion Development | EU AI Act conformity requirements embed compliance into next-generation treatment planning modules. |
| Reimbursement Strategy | Medical tourism positioning for Latin American patients supports premium pricing in Madrid clinics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with dermatology clinic directors, biomedical equipment procurement managers, AEMPS regulatory affairs specialists, and GPO contracts administrators. AEMPS device registration databases, EU MDR notified body certification records, and Spanish customs import statistics for HS code 9018 medical device categories provided foundational secondary validation. Bottom-up clinic installation counts across Madrid, Barcelona, Valencia, and Seville were triangulated against top-down manufacturer shipment data.
Granularity-level modeling segmented the market by product type, technology modality, end-user setting, and application area, with additional dimensioning by autonomous community regulatory enforcement intensity. CAGRs were derived through regression analysis of historical installation trends and forward projection of MDR-driven replacement cycles. Forecast inputs incorporated AEMPS inspection capacity constraints, notified body queue dynamics, and medical tourism patient flow projections from Latin American source markets.
Inputs from AEMPS regulatory databases and notified body certification records were available through the study window; gaps in proprietary manufacturer pricing data introduce uncertainty bands around segment-level value estimates. Forecasts reflect documented assumptions regarding MDR compliance timeline adherence and clinic capital expenditure recovery post-pandemic. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Spinal Cord Stimulators Market
Medical Devices
Pericardial Patches Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Silastic Implant Market