
 Surgical AR Systems Market | 2026-2036
Surgical AR Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical AR Systems Market Analytics
Platform licensing revenue is reconfiguring margin pools away from one-time hardware sales toward recurring software subscriptions across surgical AR deployments. Philips Healthcare leverages its installed imaging base to bundle AR visualization modules, while Intuitive Surgical anchors its ecosystem through proprietary da Vinci AR integration protocols. Medtronic competes by extending surgical navigation software licenses into multi-year service agreements that lock in hospital purchasing cycles.
Surgical AR systems overlay computer-generated imagery onto the surgeon's field of view through optical see-through or video see-through displays, typically operating at sub-millimeter registration accuracy with latency below 20 milliseconds to maintain hand-eye coordination during open and minimally invasive procedures. Head-mounted displays capture the dominant share of product type revenue due to their direct integration with existing surgical microscopes and loupes, while markerless tracking technology is gaining fastest adoption as hospitals seek to eliminate sterile field contamination from physical fiducials. Application demand concentrates in navigation and visualization, where real-time anatomical overlay justifies premium pricing against conventional image-guided surgery systems.
FDA 510(k) clearance requirements govern Class II surgical AR devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for AR systems marketed under CE marking in Europe. Japan's PMDA evaluates surgical AR platforms through its Sakigake designation pathway, accelerating review for devices addressing unmet surgical needs. Stakeholders must monitor evolving software-as-a-medical-device classifications that could reclassify AR overlay algorithms from accessory components to standalone regulated products.
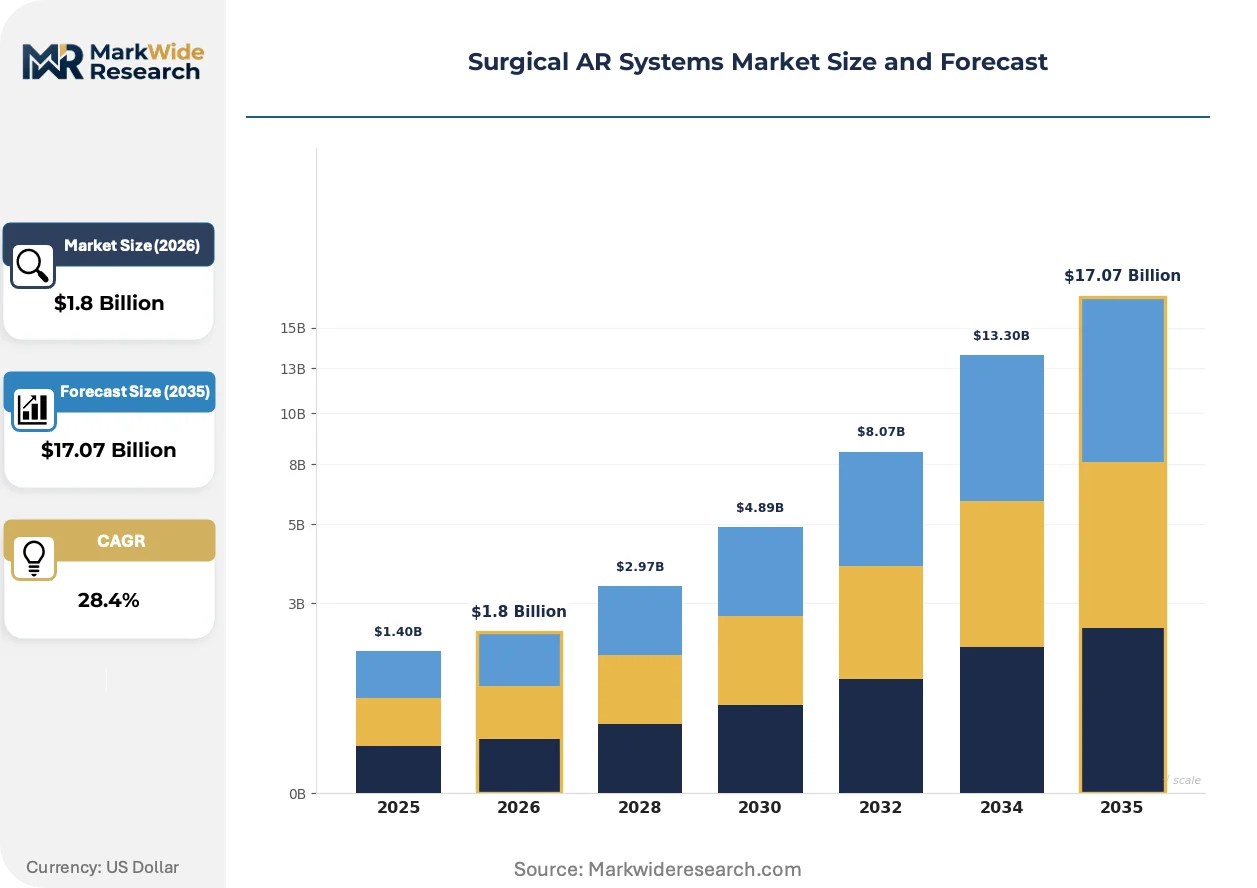
Market Dynamics
Platform licensing revenue is reconfiguring margin pools away from one-time hardware sales toward recurring software subscriptions across surgical AR deployments.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's premarket notification pathways for Class II surgical AR devices are accelerating commercial entry timelines for manufacturers targeting the United States market.
- Neurosurgical Navigation Demand:Academic medical centers are expanding procurement of AR visualization platforms for precision neurosurgical suites, driving capital equipment replacement cycles.
- Markerless Tracking Adoption:Hospitals are eliminating sterile field contamination risks by adopting markerless tracking technology in place of physical fiducials during open and minimally invasive procedures.
Market Restraints
- Sub-Millimeter Registration Costs:Achieving the sub-millimeter accuracy required for hand-eye coordination demands specialized optical components and calibration protocols that inflate unit economics.
- EU MDR Clinical Evidence Burden:The EU Medical Device Regulation imposes stricter clinical evidence standards for AR systems marketed under CE marking, extending time-to-market for European launches.
- Conventional IGS Substitution:Established image-guided surgery systems retain installed base loyalty where AR overlay premiums fail to demonstrate measurable outcome differentials.
Strategic Opportunities
- Japan Sakigake Acceleration:Japan's PMDA evaluates surgical AR platforms through its Sakigake designation pathway, creating regulatory fast-track potential for devices addressing unmet surgical needs.
- Software-as-Medical-Device Reclassification:Evolving SaMD classifications could elevate AR overlay algorithms from accessory components to standalone regulated products, opening new licensing revenue streams.
- Multi-Year Service Agreement Lock-In:Extending surgical navigation software licenses into multi-year service agreements captures hospital purchasing cycles and reduces competitive displacement risk.
Industry Challenges
- Latency Engineering Talent Scarcity:Maintaining sub-20 millisecond latency for hand-eye coordination requires specialized embedded systems expertise that remains concentrated among semiconductor and gaming industry veterans.
- Legacy Microscope Integration Complexity:Head-mounted displays must interface with heterogeneous surgical microscope and loupe ecosystems, creating technical validation burdens for each OEM partnership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical AR Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Mounted Displays, Smart Glasses, Projectors, Handheld Devices End User: Hospitals, Surgical Centers, Academic Institutions, Research Labs Technology: Marker-Based, Markerless, Projection-Based, Optical See-Through Application: Visualization, Navigation, Training, Remote Assistance |
| Companies Covered | Philips Healthcare, Siemens Healthineers, Intuitive Surgical, Medtronic, Stryker, BRAINLAB, Zimmer Biomet, CAE Healthcare, Vuzix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical AR Systems Market Evolving Landscape
Optical see-through displays are overtaking video see-through architectures as the dominant visualization paradigm, compressing hardware differentiation cycles and elevating software registration algorithms as the primary competitive battleground.
Markerless tracking technology is rendering obsolete the sterile field contamination protocols required for physical fiducial placement. Neurosurgical departments at academic medical centers are adopting camera-based spatial mapping systems at accelerated procurement cycles. This shift compresses the addressable market for fiducial manufacturers while expanding software licensing attach rates for tracking algorithm providers.
The EU Medical Device Regulation's clinical evidence requirements are reshaping product development roadmaps for CE-marked surgical AR systems. Manufacturers must now generate prospective clinical data rather than relying on predicate device equivalency. European launches face 12-18 month timeline extensions, prompting some firms to prioritize FDA 510(k) clearance sequences ahead of European commercialization.
Hospital procurement committees are unbundling after-sales service contracts from hardware purchases, forcing AR system vendors to compete on standalone software maintenance pricing. German university hospitals have pioneered this disaggregation, establishing benchmark terms that radiate through central European procurement networks. Vendors respond with tiered support offerings that segment training intensity from algorithm update access.
Surgical AR Systems Market Segmentation
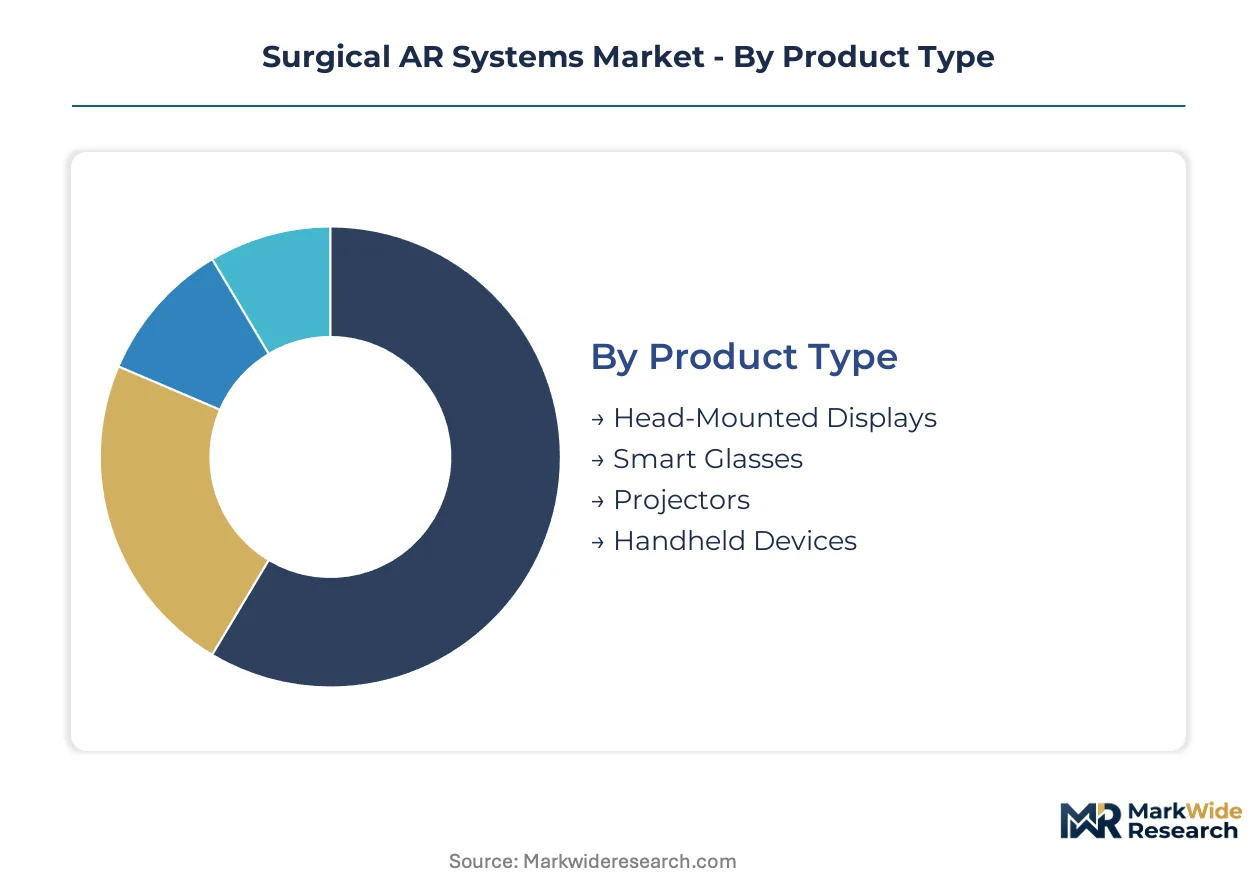
Surgical AR systems fragment across hardware form factors, institutional deployment settings, tracking methodologies, and clinical use cases. Each dimension carries distinct procurement cycles, service contract structures, and margin profiles that shape vendor go-to-market strategies.
Product Type:
After-sales-service intensity varies sharply across hardware categories, with head-mounted displays demanding specialized calibration protocols and smart glasses requiring frequent firmware refresh cycles.
- Head-Mounted Displays:Optical see-through architectures dominate neurosurgical suites at academic medical centers in the United States and Germany. These systems integrate with existing surgical microscopes and loupes, generating multi-year service agreements that lock in hospital purchasing cycles.
- Smart Glasses:Video see-through platforms are gaining fastest adoption in ambulatory surgical centers where capital budgets constrain full navigation suite investments. Japanese university hospitals have pioneered procurement frameworks that unbundle hardware from algorithm update subscriptions.
- Projectors:Projection-based visualization serves open-procedure environments where sterile field constraints prohibit wearable hardware.
- Handheld Devices:Portable AR tablets address training and remote assistance applications with lower registration accuracy requirements.
Head-Mounted Displays holds the largest share; momentum sits with Smart Glasses.
End User:
Cost tier stratification separates premium navigation suite deployments from budget-constrained training applications.
- Hospitals:Tertiary care centers in the United States and Japan concentrate demand for FDA 510(k)-cleared and PMDA-reviewed platforms with sub-millimeter registration accuracy. These institutions negotiate enterprise software licenses spanning multiple surgical departments.
- Surgical Centers:Freestanding facilities in Germany prioritize markerless tracking systems that eliminate sterile field contamination risks without capital-intensive infrastructure.
- Academic Institutions:Research hospitals generate clinical evidence for EU MDR compliance, extending European launch timelines.
- Research Labs:Preclinical development settings drive early-stage algorithm validation outside regulated pathways.
Hospitals command the dominant revenue pool; surgical centers are climbing the fastest as procurement disaggregation spreads.
Technology:
Volume concentration is shifting toward camera-based spatial mapping as hospitals eliminate physical fiducial protocols.
- Marker-Based:Physical fiducial systems retain installed base loyalty in legacy navigation suites where surgeons resist workflow disruption. German university hospitals have accelerated displacement of these systems through procurement mandates prioritizing sterile field integrity.
- Markerless:Camera-based tracking algorithms are expanding software licensing attach rates at academic medical centers in the United States and Japan. These systems demand specialized embedded systems expertise concentrated among semiconductor industry veterans.
- Projection-Based:Direct surface overlay technology addresses open-procedure environments without wearable hardware constraints.
- Optical See-Through:Transparent display architectures compress hardware differentiation cycles and elevate registration algorithm competition.
Marker-Based retains legacy installed base; Markerless gains share fastest through infection control mandates.
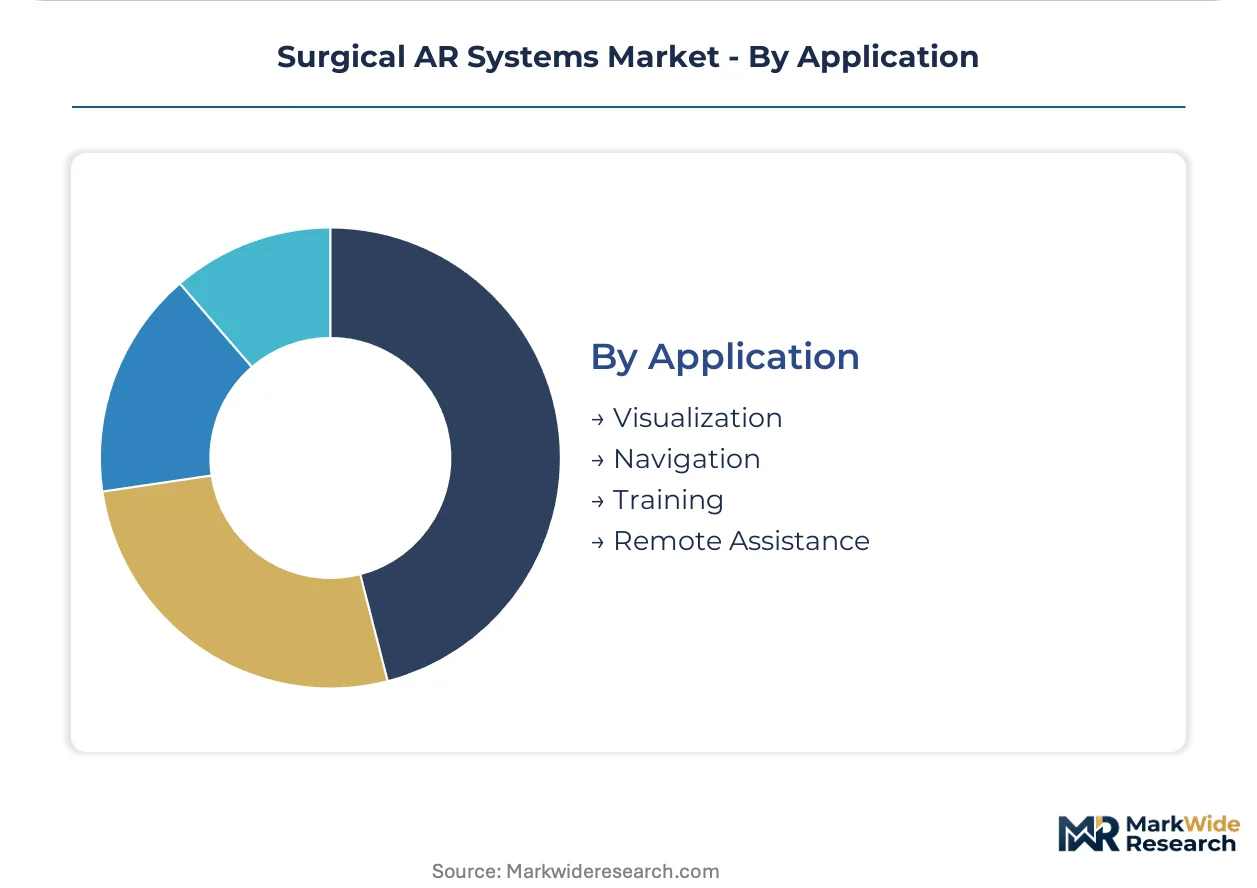
Application:
Customer type segmentation separates outcome-critical navigation deployments from cost-sensitive training modules.
- Visualization:Real-time anatomical overlay justifies premium pricing against conventional image-guided surgery systems in neurosurgical departments. United States academic medical centers drive replacement cycles as FDA 510(k) pathways streamline commercial entry.
- Navigation:Precision guidance applications demand sub-20 millisecond latency maintenance for hand-eye coordination. Japanese PMDA Sakigake designation accelerates review for platforms addressing unmet surgical navigation needs.
- Training:Simulation modules face pricing pressure as hospitals unbundle after-sales contracts from hardware purchases.
- Remote Assistance:Telesurgery support applications expand addressable market beyond capital equipment budgets into operational expenditure categories.
Visualization captures the largest revenue share; Navigation shows the steepest expansion trajectory as accuracy requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital capital budgets in Japan and Germany absorb premium pricing with minimal elasticity, while surgical centers in the United States and ambulatory facilities in emerging markets demand aggressive procurement terms that compress vendor margins.
United States
Academic medical centers in Boston and the San Francisco Bay Area drive replacement cycles for FDA 510(k)-cleared navigation suites with sub-millimeter accuracy requirements. The FDA's streamlined premarket notification pathways accelerate commercial entry timelines for Class II surgical AR devices. Tertiary care hospitals in the Texas Medical Center negotiate enterprise software licenses spanning multiple surgical departments.
Germany
University hospitals in Berlin and Munich pioneered procurement frameworks that unbundle after-sales service contracts from hardware purchases. The EU Medical Device Regulation imposes stricter clinical evidence standards for CE-marked systems, extending European launch timelines. Baden-Württemberg's surgical clusters concentrate demand for markerless tracking systems that eliminate sterile field contamination risks.
Japan
PMDA's Sakigake designation pathway accelerates regulatory review for platforms addressing unmet neurosurgical navigation needs. Tokyo and Osaka academic medical centers generate clinical evidence requirements that shape product development roadmaps. Japanese university hospitals have established benchmark procurement terms that radiate through Asia-Pacific commercialization strategies.
United Kingdom
NHS procurement frameworks prioritize cost-sensitive video see-through platforms in ambulatory settings over capital-intensive optical see-through suites. London teaching hospitals concentrate demand for training and remote assistance applications. The MHRA's post-Brexit regulatory autonomy creates divergence from EU MDR compliance timelines that vendors must navigate separately.
South Korea
Seoul's tertiary care centers demand sub-20 millisecond latency maintenance for hand-eye coordination in minimally invasive procedures. The MFDS evaluates surgical AR platforms through accelerated review pathways for devices demonstrating measurable outcome differentials. Korean semiconductor industry veterans supply specialized embedded systems expertise for camera-based spatial mapping algorithms.
Surgical AR Systems Market Competitive Landscape
Integrated healthcare conglomerates and specialized surgical navigation firms split the market between bundled ecosystem plays and standalone precision platforms. The vendor base concentrates around imaging equipment incumbents leveraging installed base advantages against pure-play AR specialists competing on registration algorithm performance. Two strategic archetypes dominate: conglomerates extending imaging modalities into AR visualization modules, and navigation specialists locking hospitals into multi-year software service agreements. Competitive moves center on proprietary integration protocols that anchor hospital purchasing cycles and markerless tracking technology licensing that displaces legacy fiducial systems.
Within the integrated healthcare tier, Philips Healthcare and Siemens Healthineers represent imaging equipment incumbents leveraging installed base breadth to bundle AR visualization modules with existing modalities. Intuitive Surgical occupies a position exemplifying ecosystem anchoring through proprietary surgical robot integration protocols that lock in hospital capital planning cycles. These three companies sit within distinct strategic positions: Philips and Siemens exemplify backward integration from imaging into overlay software, while Intuitive represents forward integration from robotic platforms into visualization layers.
| Leading Market Players |
|---|
| Philips Healthcare |
| Siemens Healthineers |
| Intuitive Surgical |
| Medtronic |
| Stryker |
| BRAINLAB |
| Zimmer Biomet |
| CAE Healthcare |
| Vuzix |
| Others |
Value Network & Pricing Analysis
Baden-Württemberg's surgical optics cluster in Germany concentrates specialized lens manufacturing capacity, creating asymmetric pricing power for head-mounted display suppliers serving United States academic medical centers. This geographic concentration of precision optical component production feeds directly into premium tier hardware pricing, while downstream software licensing margins remain insulated from component cost volatility through recurring subscription architectures.
Pricing Analysis
Multi-year service agreements and algorithm update subscriptions now drive lifetime value, displacing one-time hardware transactions as the dominant revenue architecture. Pricing stratifies across premium, standard, and economy tiers based on registration accuracy certification and after-sales training intensity. Cost compression in the smart glasses segment intensifies as ambulatory surgical centers demand unbundled procurement terms. Hospitals in Japan exhibit the lowest price sensitivity, prioritizing sub-millimeter accuracy and PMDA-reviewed platforms, while United States surgical centers show acute sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Extended payment terms from German university hospital procurement committees are reshaping supplier working capital requirements, with 90-day settlement windows now standard across central European deployments. Manufacturing draws from Taiwan for microdisplay panels, Germany for precision optics, and South Korea for embedded systems chipsets. Single-source vulnerability concentrates in specialized optical see-through waveguide components. Distribution runs through direct hospital system contracts in the United States and GPO-negotiated frameworks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical AR market rewards embedded systems engineering talent concentrated among semiconductor industry veterans, creating acquisition premiums for teams capable of sub-20 millisecond latency optimization. This capability scarcity favors incumbents with captive R&D pipelines and disadvantages capital-light entrants lacking hardware-software integration depth.
For Market Incumbents: Harden ecosystem lock-in by extending proprietary integration protocols from surgical robots into AR visualization layers, neutralizing modular competitors. Anchor hospital purchasing cycles through multi-year navigation software licenses that bundle markerless tracking algorithm updates. Defend against pure-play AR specialists by accelerating FDA 510(k) clearance sequences ahead of European MDR timelines.
For New Entrants and Emerging Players: Build out remote assistance applications as the most penetrable white-space segment, bypassing capital-intensive navigation suite competition. Target ambulatory surgical centers in the United States with video see-through platforms priced below optical see-through premiums. Establish go-to-market partnerships with GPO contracts managers rather than direct hospital sales forces.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors navigation specialists with validated clinical evidence libraries and installed base conversion momentum. Long-term viability hinges on software-as-medical-device reclassification readiness and regulatory pathway breadth across FDA, PMDA, and EU MDR frameworks. Monitor Japan's Sakigake designation awards as inflection indicators for platform differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlines commercial entry for Class II surgical AR devices targeting United States academic medical centers. |
| Markerless Tracking Algorithm Licensing | Displaces physical fiducial manufacturers while expanding software attach rates at infection-control-mandated hospitals. |
| Hospital System Partnership Expansion | Locks in enterprise software licenses spanning neurosurgical, orthopedic, and cardiovascular departments. |
| EU MDR Clinical Evidence Investment | Extends European launch timelines but creates predicate device barriers against non-compliant competitors. |
| Embedded Systems Talent Acquisition | Captures semiconductor industry veterans capable of latency engineering for hand-eye coordination maintenance. |
Research Methodology
The analysis maps head-mounted displays, smart glasses, and projection-based systems, each validated through hospital purchasing committee interviews, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at device manufacturers. Primary fieldwork combined with secondary validation against FDA 510(k) filings, PMDA Sakigake designations, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up unit economics triangulated against top-down market sizing across hardware, software, and service revenue pools.
Assumptions held regulatory pathway timelines and hospital capital budget elasticity fixed across the projection horizon, while varying markerless tracking adoption curves and software-as-medical-device reclassification scenarios. Segmentation dimensions modeled include product type, end user institution tier, tracking methodology, and clinical application intensity. CAGRs derived from surgical procedure volume growth, replacement cycle acceleration, and licensing revenue mix shifts. Forecast inputs incorporated neurosurgical navigation suite procurement data and ambulatory surgical center expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by imaging equipment conglomerates into standalone AR software would shift outcomes. Macroeconomic contraction in hospital capital expenditure, regulatory reclassification of overlay algorithms, or breakthroughs in non-invasive registration technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Global Gastrointestinal Devices Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Global Casting Devices Market
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Posture Correction Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Cranial Perforator Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market