
 Australia Contraceptive Devices Market | 2026-2036
Australia Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Contraceptive Devices Market Outlook
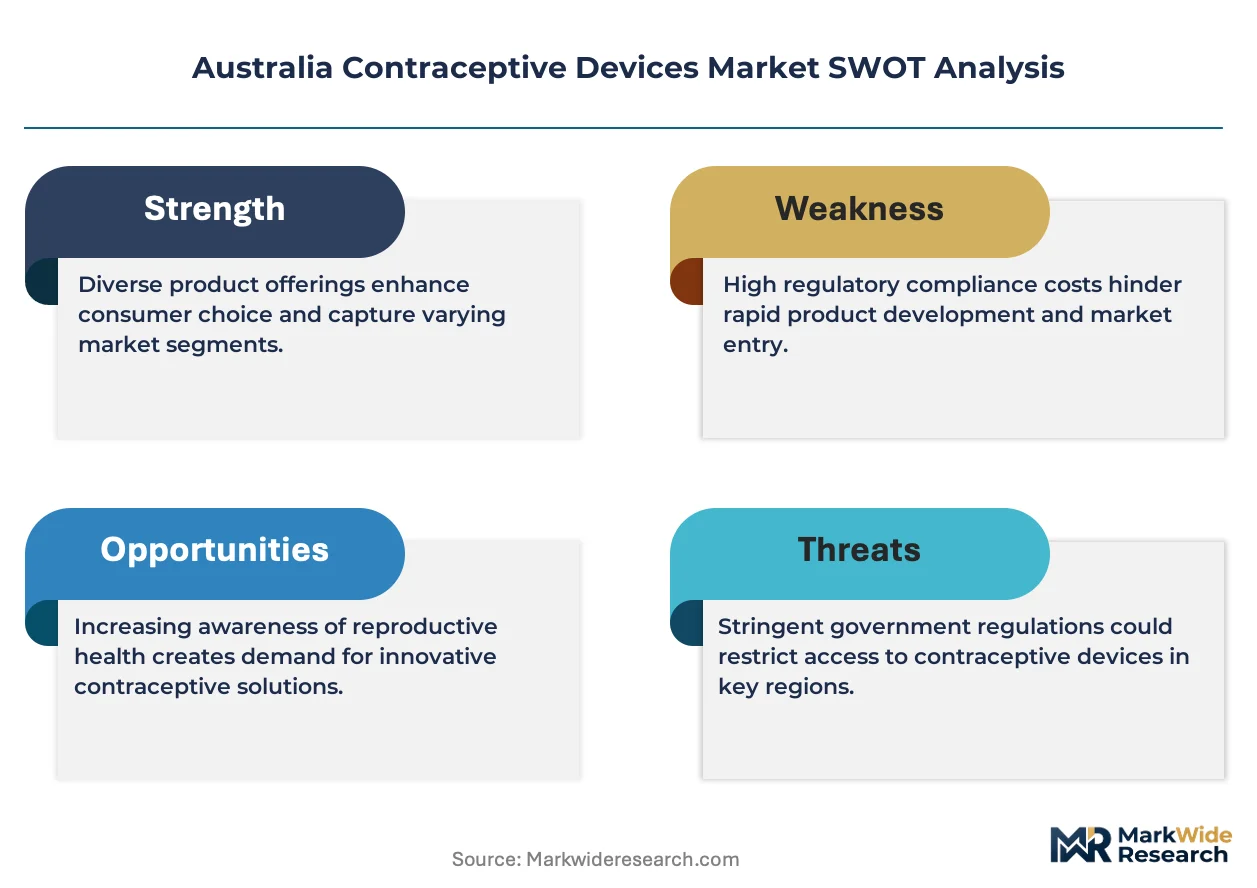
The TGA's updated medical device framework is recalibrating how manufacturers demonstrate clinical equivalence for contraceptive implants and intrauterine systems. Bayer AG leverages its hormonal IUD portfolio to sustain leadership in specialist clinic channels across Sydney and Melbourne. CooperSurgical anchors its position through focused distribution to Australian hospitals and family planning centers. Lifestyles Healthcare competes aggressively in the retail condom segment via pharmacy and supermarket placement.
Contraceptive devices encompass mechanically or hormonally active products designed to prevent pregnancy through barrier function, ovulation suppression, or sperm incapacitation, with specifications varying by active pharmaceutical ingredient load, device material biocompatibility, and duration of efficacy ranging from single-use to multi-year implantation. Their primary purpose spans family planning programs, individual reproductive health management, and public health cost containment through reduction of unintended pregnancy rates. Intrauterine devices command the largest product type share due to long-acting efficacy and declining insertion procedure costs in Australian primary care settings. Online retailers represent the fastest-growing end user channel, driven by discreet purchasing preferences and expanded telehealth prescribing authority under national pharmacy regulations.
The Therapeutic Goods Administration enforces ISO 13485-aligned quality management standards for all contraceptive device sponsors, while the Pharmaceutical Benefits Scheme determines reimbursement eligibility that directly shapes patient access and prescribing patterns across public and private settings. State-level health departments in Queensland and Western Australia operate parallel procurement frameworks for public clinic supply, creating fragmented tender environments. Stakeholders must monitor how TGA convergence with EU MDR requirements affects technical documentation burdens for existing product registrations.
Market Dynamics
The Therapeutic Goods Administration's convergence with EU MDR technical documentation requirements is compressing product registration timelines while elevating quality system burdens for contraceptive device sponsors seeking Australian market entry.
Growth Catalysts
- Pharmaceutical Benefits Scheme expansion:The PBS reimbursement eligibility for long-acting reversible contraceptives is reducing out-of-pocket costs for patients in public hospital networks across New South Wales and Victoria.
- Telehealth prescribing authority:National pharmacy regulations now permit remote consultation and prescription for hormonal implants, expanding access beyond traditional specialist clinic footprints.
- Biodegradable polymer advances:Next-generation implant materials with controlled release kinetics are extending efficacy duration while simplifying removal procedures in Australian primary care settings.
Market Restraints
- Specialist workforce concentration:Insertion-trained clinicians cluster disproportionately in metropolitan Sydney and Melbourne, limiting intrauterine device uptake in regional Queensland and Western Australia.
- Copper and hormone API cost volatility:Active pharmaceutical ingredient supply disruptions are compressing margins for intrauterine system manufacturers serving Australian public tenders.
- TGA-EU MDR documentation alignment:Convergence requirements are extending technical file preparation timelines for existing product registrations without grandfathering provisions.
Strategic Opportunities
- Western Australia public clinic procurement:State-level tender frameworks operate independently from eastern seaboard networks, creating entry points for sponsors with differentiated pricing or service models.
- Online pharmacy channel development:Discreet purchasing preferences among younger demographics are accelerating direct-to-patient distribution bypassing traditional retail pharmacy networks.
- Non-hormonal implant innovation:Copper-alloy and pH-modulating technologies address growing patient demand for hormone-free contraception in Australian family planning centers.
Industry Challenges
- Insertion procedure certification bottlenecks:Royal Australian College of General Practitioners training program capacity constraints are limiting the pace of clinician qualification for long-acting device placement.
- State procurement fragmentation:Queensland and Western Australia operate parallel tender environments with divergent technical specifications, forcing manufacturers to maintain multiple compliance documentation sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Contraceptive Devices Market |
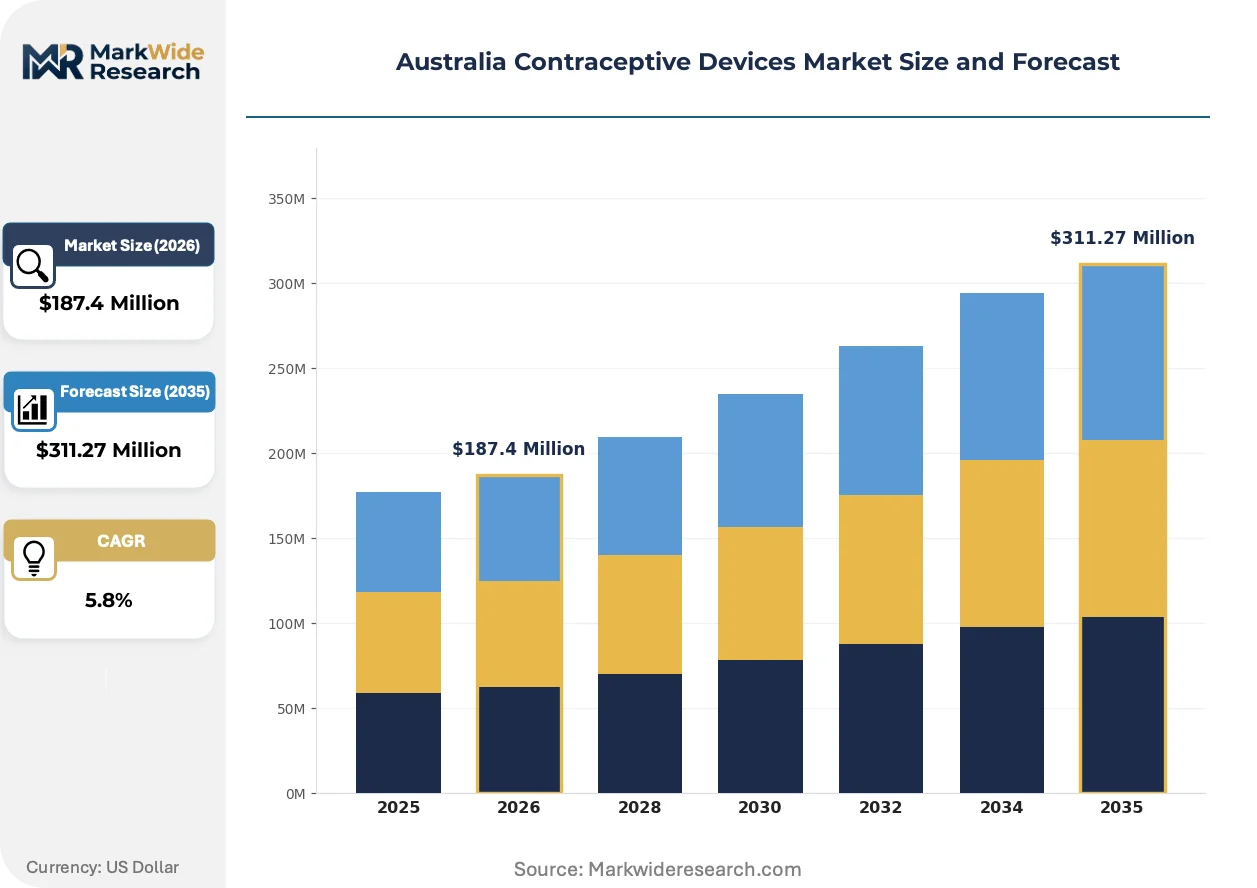
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrauterine Devices, Condoms, Implants, Patches End User: Hospitals, Clinics, Pharmacies, Online Retailers Application: Family Planning, Emergency Contraception, Regular Use, Health Education Distribution Channel: Direct Sales, Wholesalers, Online Platforms, Retail Outlets |
| Companies Covered | Reckitt Benckiser Group, Bayer AG, Merck & Co., Pfizer, Aspen Pharmacare, CooperSurgical, Lifestyles Healthcare, Church & Dwight, Organon & Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Contraceptive Devices Market Strategic Shifts
Digital health infrastructure and patient-directed care models are restructuring how contraceptive devices reach Australian consumers, with implications for manufacturer channel strategy and clinical support service design.
Bioresorbable implant technologies are consolidating the Australian long-acting contraceptive segment by eliminating removal procedure requirements entirely. Specialist clinics in Sydney and Melbourne are piloting these devices for patients seeking finite-duration fertility management. The technology is consolidating demand around single-insertion solutions and compressing aftermarket service revenue pools for removal-focused practices.
TGA alignment with EU MDR post-market surveillance obligations is intensifying real-world evidence collection requirements for hormonal intrauterine systems. Manufacturers must now maintain active implant registries and periodic safety update reporting that exceeds prior Australian standards. The implant segment bears the heaviest documentation burden as sponsors restructure quality management systems to satisfy dual-jurisdiction compliance.
Patient-initiated switching between contraceptive modalities is shortening product loyalty cycles and elevating the importance of seamless transition support. Retail pharmacy networks are capturing an expanding share of initial device consultations through pharmacist prescribing authority expansions in Victoria and New South Wales. This channel rotation is most pronounced among urban women aged 25-34 seeking convenience without specialist appointment delays.
Australia Contraceptive Devices Market Segmentation
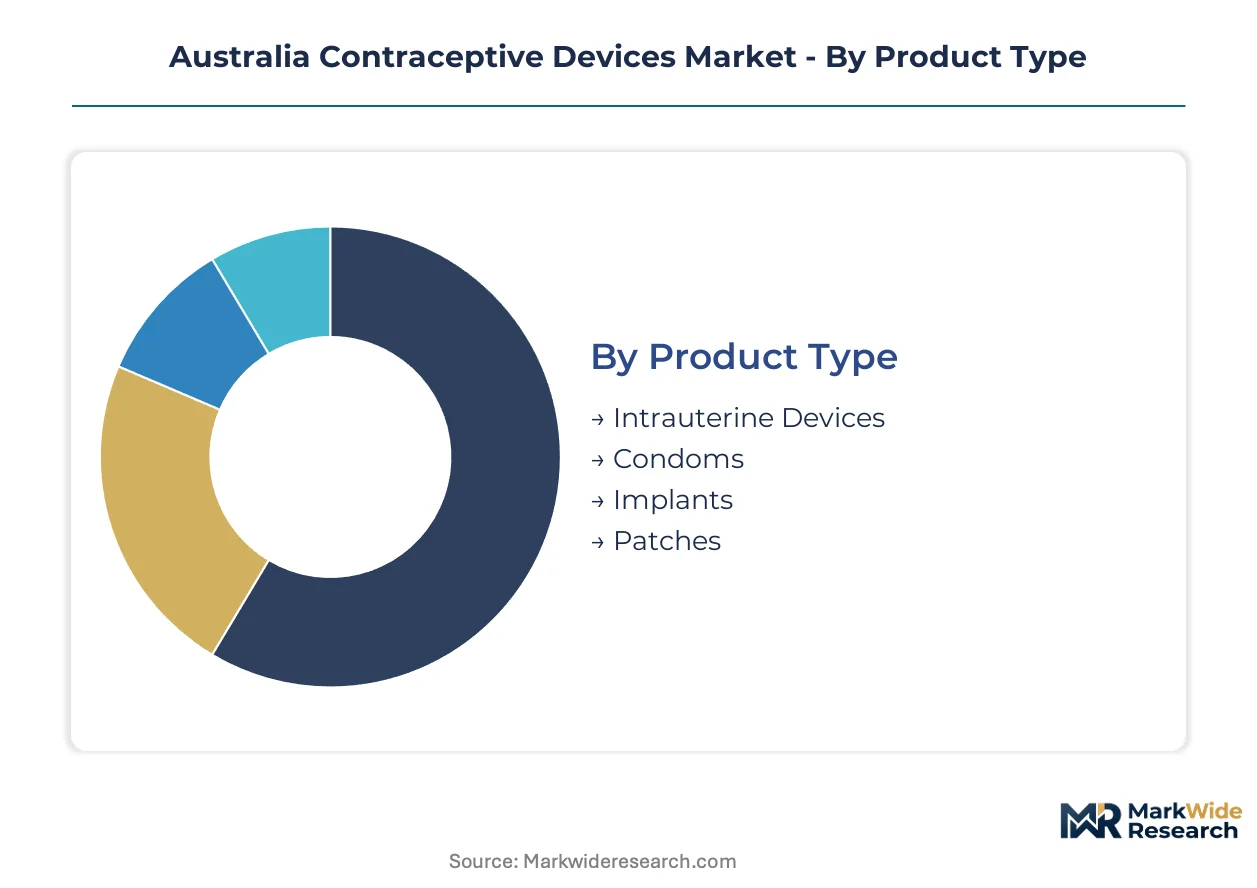
Segmentation of the Australia contraceptive devices market reveals how capital requirements, reimbursement pathways, and clinical infrastructure shape competitive positioning. Manufacturers must align product portfolios with specific channel economics and prescriber capabilities to capture value across distinct patient access points.
Product Type:
Intrauterine devices and implants demand the heaviest upfront investment in clinical training infrastructure and TGA registration documentation, while barrier methods require lighter capital deployment in manufacturing scale and retail distribution.
- Intrauterine Devices:Hormonal and copper-based systems with multi-year efficacy profiles. Demand concentrates in metropolitan specialist clinics across Sydney and Melbourne where insertion-trained clinicians cluster, though PBS reimbursement expansion is extending reach into Victorian primary care networks.
- Condoms:Latex and non-latex barrier products with single-use specifications. Volume concentrates in retail pharmacy and supermarket channels across New South Wales, driven by discreet purchasing preferences and over-the-counter accessibility without prescription requirements.
- Implants:Subdermal hormonal rods with multi-year release kinetics. Royal Australian College of General Practitioners certification requirements limit placement capacity to qualified clinicians in established training networks.
- Patches:Transdermal hormone delivery systems with weekly replacement schedules. Patient familiarity from other therapeutic categories supports uptake among younger demographics seeking non-invasive alternatives.
Intrauterine devices absorb the bulk of installed clinical capacity; online retailer distribution of barrier methods is expanding most quickly.
End User:
Channel selection reflects patient acuity, reimbursement eligibility, and convenience preferences, with hospital networks capturing complex cases and retail channels serving routine access needs.
- Hospitals:Public and private facilities managing complex contraceptive placements and post-procedural complications. Queensland Health procurement frameworks drive volume through tender-based supply arrangements.
- Clinics:Specialist family planning centers and general practice settings with trained clinicians. Western Australia's independent tender environment creates distinct entry requirements from eastern seaboard networks.
- Pharmacies:Community and retail settings with expanded prescribing authority under Victorian and New South Wales regulations. Pharmacist-led consultations are capturing initial device discussions for barrier and short-acting methods.
- Online Retailers:Direct-to-patient platforms leveraging telehealth prescribing authority and discreet fulfillment. Younger demographics in urban centers are driving channel growth fastest.
Hospitals and clinics retain the deepest clinical relationships; online retailers are climbing the fastest as telehealth infrastructure matures.
Application:
Use case segmentation determines product specification requirements, with long-acting methods demanding higher clinical support investment than episodic or educational applications.
- Family Planning:Structured reproductive health management spanning method selection through discontinuation. Australian primary care settings are expanding long-acting reversible contraceptive counseling capacity.
- Emergency Contraception:Post-coital intervention with time-sensitive access requirements. Retail pharmacy networks dominate distribution through over-the-counter availability.
- Regular Use:Ongoing contraceptive adherence with method-switching support. Patient-initiated modality changes are shortening product loyalty cycles across all channels.
- Health Education:Preventive counseling and method awareness programs. State health departments in Victoria and Queensland fund parallel public clinic initiatives.
Family planning absorbs the majority of clinical resource allocation; emergency contraception is gaining share fastest through retail channel expansion.
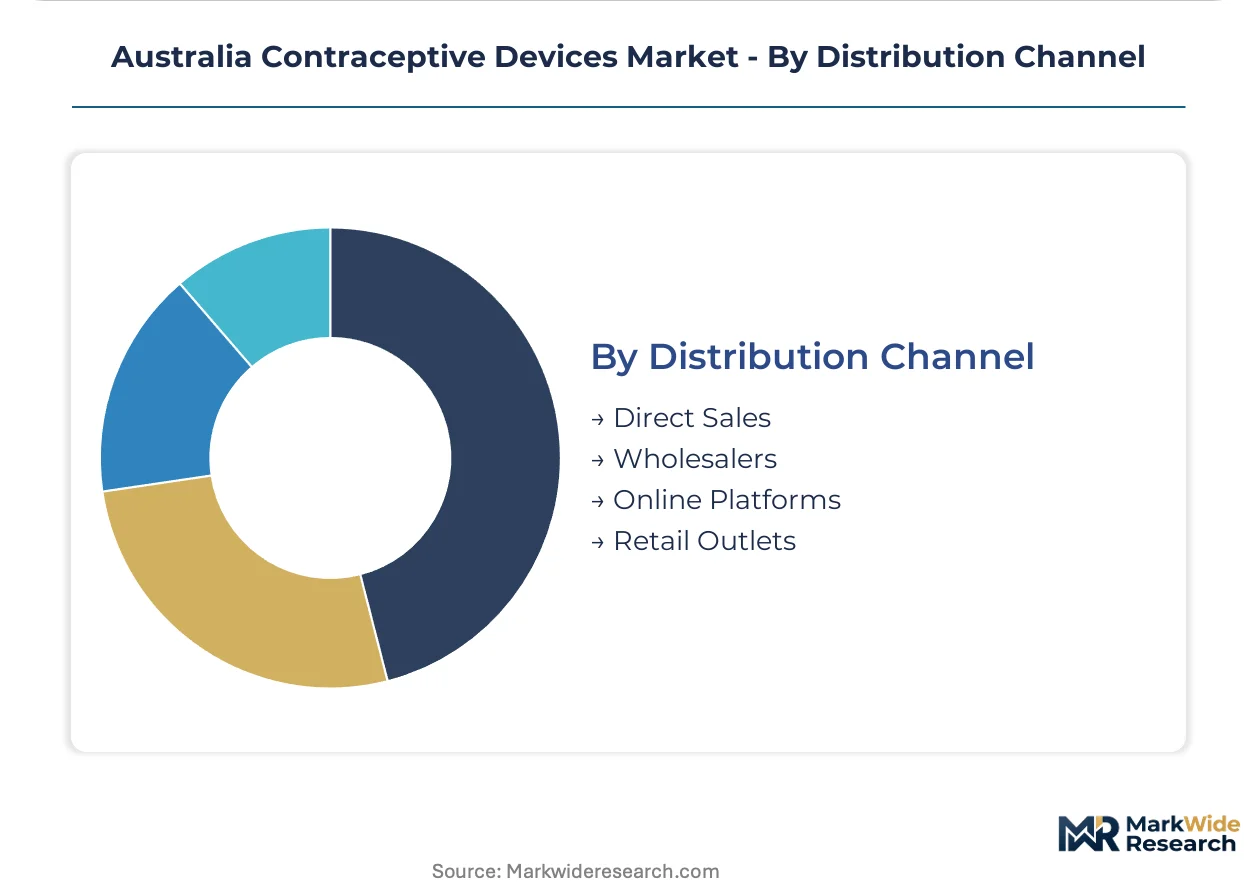
Distribution Channel:
Channel economics vary sharply by product complexity, with direct sales requiring specialized clinical support and online platforms demanding logistics investment in discreet fulfillment infrastructure.
- Direct Sales:Manufacturer-to-institution supply for hospitals and specialist clinics. Western Australia's separate tender frameworks require dedicated account management distinct from eastern networks.
- Wholesalers:Intermediary distribution to retail pharmacy and supermarket networks. National pharmacy chains in New South Wales and Victoria consolidate procurement volume.
- Online Platforms:Direct-to-patient fulfillment with telehealth integration. TGA-aligned quality management requirements extend to digital channel sponsors.
- Retail Outlets:Supermarket and convenience store placement for barrier methods. Shelf-space competition intensifies between domestic and imported condom brands.
Direct sales and wholesalers retain the largest volume throughput; online platforms are expanding most quickly as patient preference shifts toward remote access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne specialist clinic clusters anchor Australian contraceptive device demand, with metropolitan New South Wales and Victoria absorbing the bulk of intrauterine device and implant insertions through concentrated clinician networks and PBS reimbursement infrastructure.
New South Wales
Public hospital procurement expansion drives volume through Sydney's specialist clinic corridor, where the Therapeutic Goods Administration's streamlined registration pathways accelerate product entry for hormonal IUD sponsors. The Royal Australian College of General Practitioners training programs concentrate insertion-certified clinicians across Greater Sydney, limiting regional access gaps despite telehealth prescribing authority expansion.
Victoria
Pharmacist prescribing authority expansions in Melbourne retail networks capture initial device consultations for barrier and short-acting methods, diverting patients from specialist appointment queues. State health department funding for family planning centers supports long-acting reversible contraceptive counseling capacity in Victorian primary care settings, with PBS reimbursement reducing out-of-pocket costs for public hospital patients.
Queensland
Queensland Health's independent tender frameworks operate parallel to eastern seaboard procurement networks, creating distinct technical specification requirements for intrauterine system manufacturers. Specialist workforce concentration in Brisbane limits device uptake in regional centers, where Royal Flying Doctor Service partnerships attempt to bridge insertion procedure access gaps through mobile clinic rotations.
Western Australia
State-level procurement fragmentation generates entry points for sponsors with differentiated pricing models, as Western Australia's health department maintains separate compliance documentation sets from New South Wales and Victoria. Perth's family planning centers pilot non-hormonal implant technologies, addressing patient demand for copper-alloy and pH-modulating alternatives to hormonal contraception.
South Australia
Adelaide's hospital networks participate in national PBS reimbursement frameworks while maintaining localized specialist referral pathways for complex contraceptive placements. The Therapeutic Goods Administration's convergence with EU MDR requirements elevates technical documentation burdens for existing product registrations, compressing margins for sponsors serving South Australian public tenders.
Australia Contraceptive Devices Market Competitive Environment
Premium-margin players sit above commodity-margin players across reimbursement eligibility and clinical training infrastructure dimensions, with hormonal IUD and implant sponsors commanding higher returns through PBS-listed status while barrier method manufacturers compete on retail shelf-space velocity. The market structures around three tiers: multinational pharmaceutical sponsors with integrated specialist clinic distribution, regional healthcare conglomerates with hospital procurement relationships, and consumer health specialists with pharmacy and supermarket dominance. Consolidation pressures intensify through strategic partnerships between device sponsors and telehealth platforms, while portfolio diversification into bioresorbable implant technologies reshapes competitive positioning.
Within the multinational pharmaceutical tier, Bayer AG and Merck & Co. exemplify sponsors leveraging hormonal IUD portfolios to sustain leadership in specialist clinic channels, with CooperSurgical anchoring hospital and family planning center distribution through focused account management. Among consumer health specialists, Reckitt Benckiser Group and Church & Dwight occupy positions in retail pharmacy and supermarket condom segments, where discreet purchasing preferences and over-the-counter accessibility drive volume concentration. These archetypes represent divergent capital deployment strategies: heavy upfront investment in clinical training infrastructure and TGA registration documentation versus lighter manufacturing scale and retail distribution requirements.
| Leading Market Players |
|---|
| Reckitt Benckiser Group |
| Bayer AG |
| Merck & Co. |
| Pfizer |
| Aspen Pharmacare |
| CooperSurgical |
| Lifestyles Healthcare |
| Church & Dwight |
| Organon & Co. |
| Others |
Value Chain & Pricing Dynamics
Bioresorbable polymer manufacturing transitions are compressing production costs for implant sponsors while concentrating supply relationships among specialized polymer compounders in Germany and the United States. This dual effect simultaneously reduces per-unit material expenses and elevates switching costs for manufacturers locked into TGA-validated supplier networks.
Pricing Analysis
Value-based pricing anchors on clinical outcome equivalence to multi-year hormonal IUD performance. PBS reimbursement eligibility separates premium-tier hormonal intrauterine systems from economy-tier copper devices, with price differentiation driven by certification grade and volume scale in public tender environments. Cost compression in the copper IUD segment is intensifying because active pharmaceutical ingredient supply disruptions are forcing margin sacrifices to maintain Queensland Health contract positions. Retail pharmacy buyers exhibit highest price sensitivity for barrier methods, while hospital procurement committees prioritize total cost-of-ownership over unit pricing for long-acting reversible contraceptives.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific shipping corridors is elevating landed costs for latex condom manufacturers distributing through Australian supermarket networks. Raw material dependencies center on Malaysian rubber plantations, Chinese non-latex polymer facilities, and Indian copper wire drawing operations for intrauterine device components. Single-source vulnerability concentrates in hormone API synthesis, where European Union MDR-aligned suppliers face extended qualification timelines under TGA convergence requirements. Distribution runs through national pharmacy wholesalers for retail channels, while direct sales teams manage hospital and specialist clinic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TGA alignment with EU MDR technical documentation requirements constructs a cost-of-compliance barrier that rewards sponsors with existing quality management infrastructure while filtering undercapitalized entrants. This regulatory moat consolidates advantage around established players with dedicated regulatory affairs capacity.
For Market Incumbents: To counter telehealth platform disintermediation of specialist clinic channels, deepen clinical training partnerships with the Royal Australian College of General Practitioners to expand insertion-certified prescriber pools. Anchor hospital procurement positions through long-term service contracts bundling device supply with clinician education programs, insulating against price-only tender competition.
For New Entrants and Emerging Players: Begin with Western Australia's independent tender environment, where fragmented procurement creates entry points for sponsors with differentiated pricing or localized service models. Capture online pharmacy channel share through discreet fulfillment infrastructure investments targeting urban women aged 25-34. Prioritize non-hormonal implant innovation to address unmet demand in Perth family planning centers.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational pharmaceutical sponsors seeking Australian TGA registration assets as EU MDR convergence accelerates. Long-term viability favors sponsors with integrated specialist clinic distribution and PBS-listed product portfolios. Monitor Royal Australian College of General Practitioners training program expansion rates as the signal indicating addressable market growth for long-acting device placement capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| TGA Registration Pathway Investment | Accelerates market entry through streamlined device classification under EU MDR-aligned standards. |
| Specialist Clinic Partnership | Secures prescriber access in Sydney and Melbourne metropolitan corridors with concentrated insertion capacity. |
| Telehealth Platform Integration | Captures patient-initiated switching behavior through remote consultation and prescription fulfillment. |
| Bioresorbable Implant Development | Eliminates removal procedure requirements, compressing aftermarket service revenue for competitor practices. |
| State-Level Tender Diversification | Reduces dependence on New South Wales and Victoria procurement through Queensland and Western Australia entry. |
Study Parameters
Document review covered TGA medical device registration databases, PBS reimbursement schedules, and state health department procurement frameworks, complemented by interviews with specialist family planning clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from Therapeutic Goods Administration guidance documents, Pharmaceutical Benefits Scheme formulary listings, Queensland Health tender disclosures, and Australian Bureau of Statistics healthcare utilization data. Bottom-up demand modeling and top-down supply validation were triangulated to produce market estimates.
Segment-level projections across product type, end user, application, and distribution channel dimensions were generated through the analytical framework. CAGRs were derived from fitted growth curves calibrated against historical PBS expenditure patterns and clinician workforce expansion trajectories. Forecast inputs incorporated TGA registration timeline assumptions, state-level procurement fragmentation indices, and telehealth prescribing authority adoption rates.
Underlying measurement precision varies by segment; intrauterine device and implant categories carry tighter precision than barrier method estimates due to PBS claims data availability. Forecasts reflect assumptions about regulatory convergence timelines and clinician training program capacity constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Keratometers Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Ostomy Drainage Systems Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Radiotherapy Positioning Devices Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
US C-Arms Market
Medical Devices
Europe Smart Bed Market