
 Medical Coatings Market | 2026-2036
Medical Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Coatings Market Intelligence
ISO 10993 biocompatibility certification is collapsing the supplier base to firms with dedicated toxicology and clinical testing infrastructure. Surmodics leverages its surface modification platform to dominate hydrophilic coating supply for interventional devices. DSM-Firmenich anchors European demand through its biomedical materials division in the Netherlands. Hydromer competes on proprietary polymer chemistry for antimicrobial and lubricious applications.
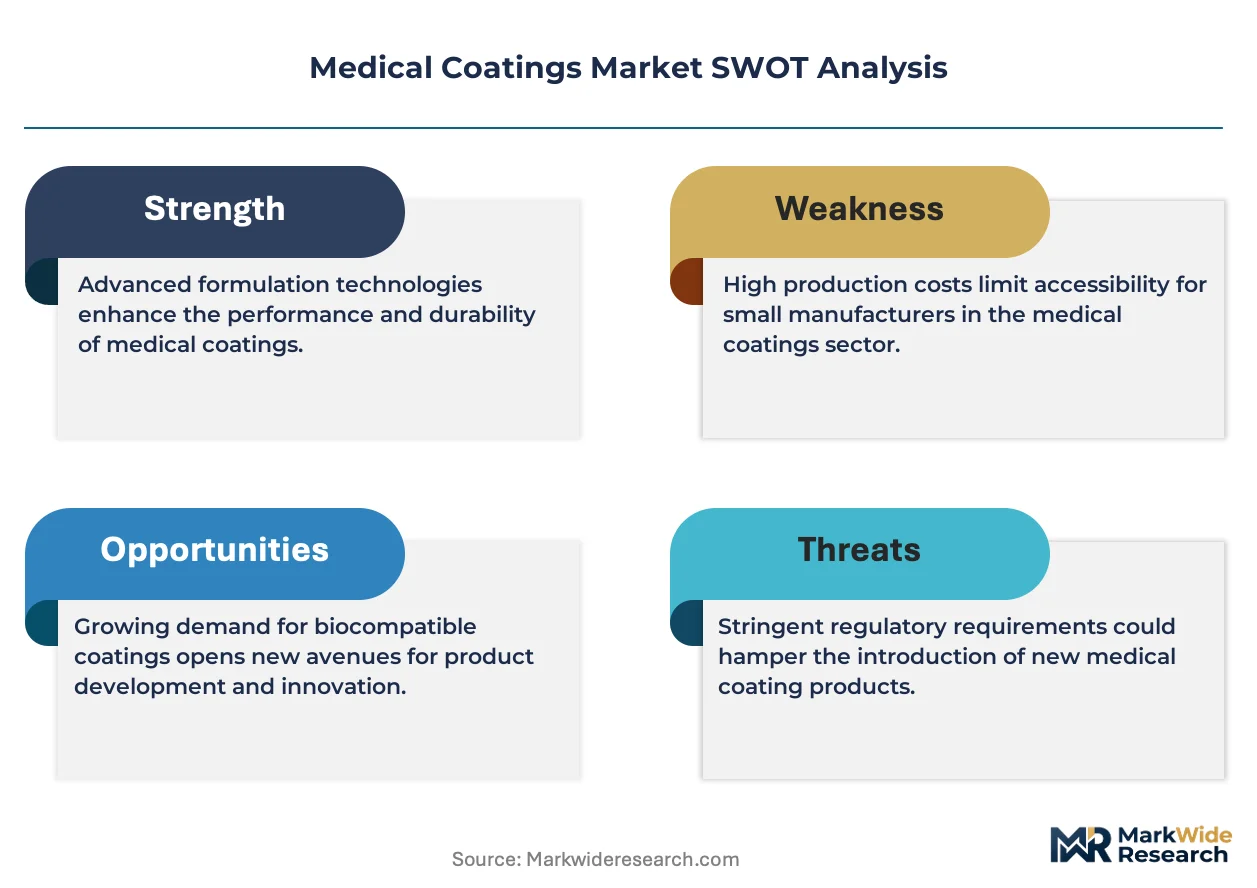
Medical coatings constitute thin functional layers applied to devices to modify surface properties such as wettability, thromboresistance, or drug release kinetics, typically ranging from nanometers to micrometers in thickness and formulated from polymers, ceramics, or biologics. Hydrophilic coatings reduce friction during catheter navigation through vasculature, while drug-eluting formulations enable localized therapeutic delivery from stents and balloons. Antimicrobial segments face margin pressure from commoditization, whereas drug-eluting and antithrombogenic categories command premium positioning due to clinical outcome differentiation and patent-protected formulations.
FDA enforces 510(k) and PMA pathways that mandate coating stability validation, while ISO 10993 and EU MDR biocompatibility standards determine market access in the United States and Europe. The EPA regulates antimicrobial coating claims and active ingredient registration, creating additional compliance layers for suppliers. Stakeholders must monitor evolving MDR clinical evidence requirements and EPA antimicrobial reclassification proposals to anticipate qualification cost shifts and supply chain restructuring.
Market Dynamics
ISO 10993 biocompatibility certification requirements are compressing the supplier base to firms with dedicated toxicology infrastructure, forcing mid-tier coating manufacturers to exit or consolidate while specialized players capture disproportionate margin in drug-eluting and antithrombogenic segments.
Growth Catalysts
- FDA PMA pathway expansion:Cardiovascular implant manufacturers face intensified scrutiny for coating stability validation, accelerating demand for pre-qualified coating platforms that de-risk regulatory timelines.
- Antimicrobial polymer chemistry:Proprietary formulations targeting device-associated infections are displacing conventional surface treatments in catheter and guidewire applications.
- China NMPA harmonization:Beijing's alignment with ISO 10993 standards is opening market access for foreign coating suppliers previously blocked by divergent testing protocols.
Market Restraints
- Platinum-group metal volatility:Electrode coating formulations depend on iridium and platinum feedstocks subject to South African supply concentration and price swings.
- EPA antimicrobial reclassification:Active ingredient registration reviews are extending commercialization timelines for silver-ion and copper-based coating claims.
- Silicone alternative limitations:Polydimethylsiloxane coatings face substitution pressure from hydrophilic polymers in neurovascular access devices due to thrombogenicity concerns.
Strategic Opportunities
- India CDSCO pathway acceleration:Medical device manufacturing incentives under PLI schemes are creating first-mover advantage for coating suppliers establishing local qualification labs.
- Orthopedic drug-eluting convergence:Antibiotic-loaded bone cement coatings represent untapped white space as joint replacement volumes rise in aging populations.
- EU MDR clinical evidence requirements:Stricter post-market surveillance mandates are favoring coating platforms with existing biocompatibility dossiers over novel formulations.
Industry Challenges
- Cross-functional toxicology expertise:ISO 10993-18 chemical characterization requirements demand rare combinations of polymer chemistry and analytical toxicology skills that resist standard training pipelines.
- Coating-to-substrate validation cycles:Each new device material pairing requires redundant adhesion, durability, and leachable studies that compress development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Coatings Market |
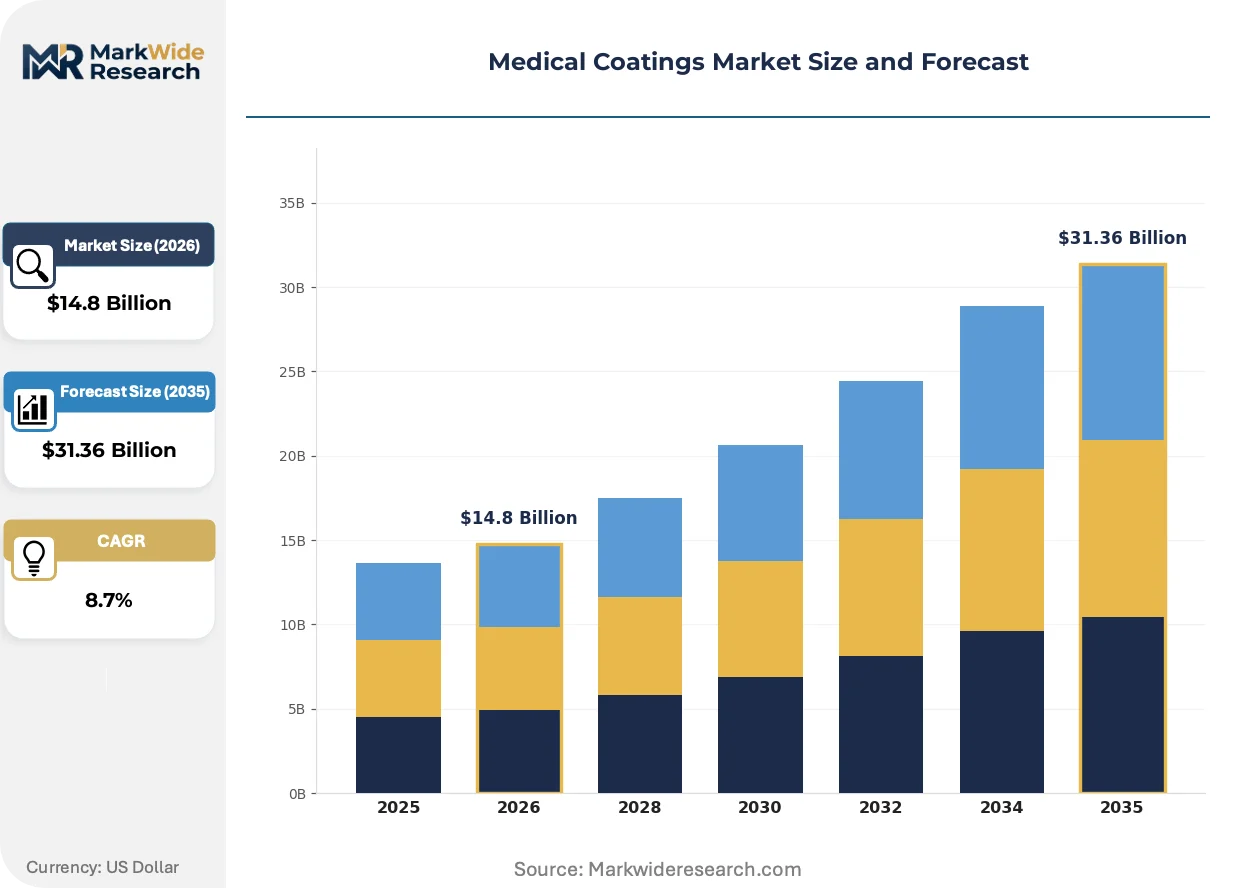
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Antimicrobial, Anti-fog, Hydrophilic, Antithrombogenic, Drug-Eluting, Biocompatible Application: Surgical Instruments, Implants, Diagnostic Devices, Catheters, Wound Care, Dental Devices End User: Hospitals, Outpatient Clinics, Diagnostic Laboratories, Specialty Care Centers, Surgical Centers, Research Institutes Technology: Plasma Spraying, Dip Coating, Vapor Deposition, Electrophoretic Deposition, Spray Coating, Chemical Vapor Deposition |
| Companies Covered | Surmodics, Hydromer, DSM-Firmenich, Biocoat Incorporated, Covalon Technologies, AST Products, Harland Medical Systems, Merit Medical Systems, Applied Medical Coatings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Coatings Market Strategic Shifts & Innovations
Surface engineering capabilities are bifurcating between commodity antimicrobial layers and precision drug-eluting architectures, with manufacturing scale and clinical evidence depth becoming the decisive competitive moats rather than formulation chemistry alone.
Ultrathin parylene conformal coatings are miniaturizing protective barriers for implantable electronics and sensor arrays. Neurostimulator manufacturers at Boston Scientific and Medtronic facilities are adopting sub-micron deposition processes for next-generation leads. This miniaturization is enabling device form factors previously incompatible with traditional encapsulation while compressing coating cost per unit area through batch processing advances.
EU MDR Article 10 technical documentation requirements are mandating coating stability data across accelerated aging protocols that exceed prior MEDDEV guidance. Manufacturers must now demonstrate performance retention through sterilization cycles and shelf-life claims. Drug-eluting coronary stents face the steepest compliance burden, with notified bodies demanding real-world evidence supplements to preclinical biocompatibility packages.
Hospital procurement consortiums are consolidating coating specification authority away from individual physicians toward value-analysis committees. Interventional cardiology device purchasing at US integrated delivery networks now routes through centralized supply chain functions that prioritize total cost of ownership over unit price. This concentration is most visible in the American Midwest and Southeast regions where Catholic health systems and for-profit chains dominate bed capacity.
Medical Coatings Market Segmentation
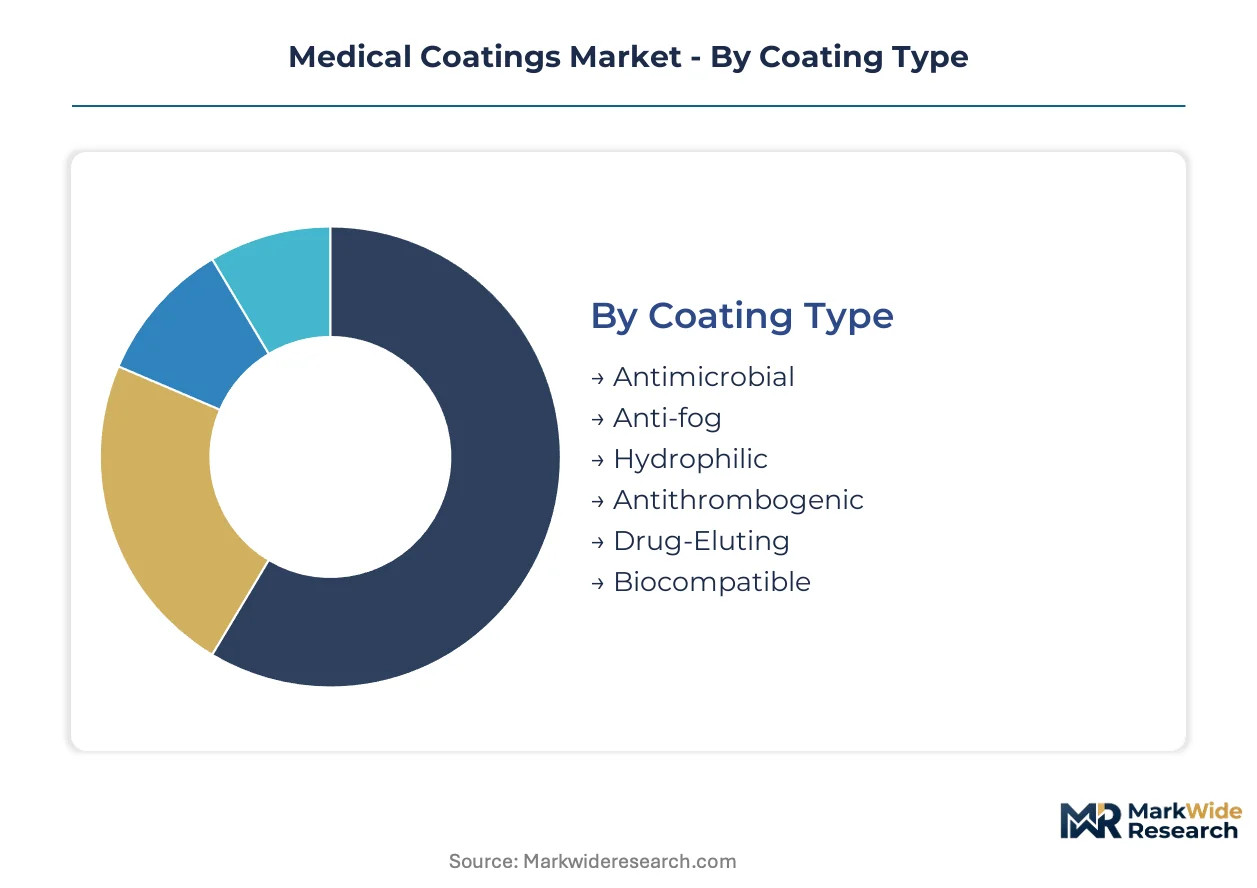
Coating specification authority in the medical device industry fragments across functional requirements, regulatory pathways, and manufacturing scale. Segmentation reveals where proprietary chemistry commands premium positioning versus where commodity formulations face margin compression from substitute technologies.
Coating Type:
Antimicrobial segments confront the most acute substitution pressure as silver-ion and copper-based formulations face EPA reclassification scrutiny and displacement by novel polymer alternatives.
- Antimicrobial:Silver-ion and copper-based formulations dominate catheter and guidewire applications. Demand concentrates in cardiovascular implant manufacturing clusters in the United States and Germany as device-associated infection protocols tighten.
- Drug-Eluting:Polymer matrices enable localized therapeutic release from coronary stents and balloon catheters. Manufacturers in China and the United States prioritize these coatings for regulatory differentiation under FDA PMA and NMPA pathways.
- Antithrombogenic:Heparin and synthetic polymer formulations reduce thrombosis risk in blood-contacting devices.
- Hydrophilic:Polyvinylpyrrolidone and polyethylene oxide chemistries reduce friction during vascular navigation.
- Biocompatible:Parylene and parylene-derivative barriers protect implantable electronics from body fluid ingress.
- Anti-fog:Hydrophilic surface treatments maintain optical clarity in endoscopic and laparoscopic instruments.
Antimicrobial coatings anchor the volume base while drug-eluting formulations gain share at the steepest rate.
Application:
Cost tier stratification separates premium implant coatings from commodity instrument treatments, with reimbursement intensity determining specification authority.
- Implants:Cardiovascular, orthopedic, and neurostimulator devices require multi-layer architectures combining antithrombogenic, drug-eluting, and encapsulation functions. German and Dutch manufacturers drive qualification demand under EU MDR Article 10 technical documentation requirements.
- Catheters:Interventional cardiology and neurovascular access devices integrate hydrophilic and antimicrobial layers. United States-based integrated delivery networks now route procurement through centralized value-analysis committees.
- Surgical Instruments:Anti-fog and antimicrobial surface treatments face commodity pricing pressure from low-cost Asian suppliers.
- Diagnostic Devices:Biosensor and imaging equipment coatings prioritize electrical insulation and biocompatibility.
- Wound Care:Antimicrobial and moisture-regulating films compete with advanced dressing materials.
- Dental Devices:Implant abutments and orthodontic instruments require biocompatible and antimicrobial surface modifications.
Surgical instruments generate the highest shipment volumes while implant coatings capture the most value per unit area.
End User:
Customer type determines validation burden, with hospital procurement consortiums imposing stricter coating qualification protocols than research or outpatient settings.
- Hospitals:Catholic health systems and for-profit chains in the American Midwest and Southeast dominate bed capacity and consolidate specification authority. These institutions prioritize total cost of ownership over unit price in interventional cardiology device purchasing.
- Surgical Centers:Ambulatory facilities favor pre-qualified coating platforms that accelerate regulatory timelines for high-volume procedures.
- Outpatient Clinics:Limited sterilization infrastructure drives preference for single-use devices with integrated coatings.
- Specialty Care Centers:Cardiac and orthopedic focused facilities demand evidence-backed coating performance for complex interventions.
- Diagnostic Laboratories:Biosensor and assay equipment manufacturers require precision deposition technologies.
- Research Institutes:Academic medical centers pilot novel surface chemistries before commercial scale-up.
Hospitals represent the largest addressable base while surgical centers expand most quickly as procedure migration accelerates.
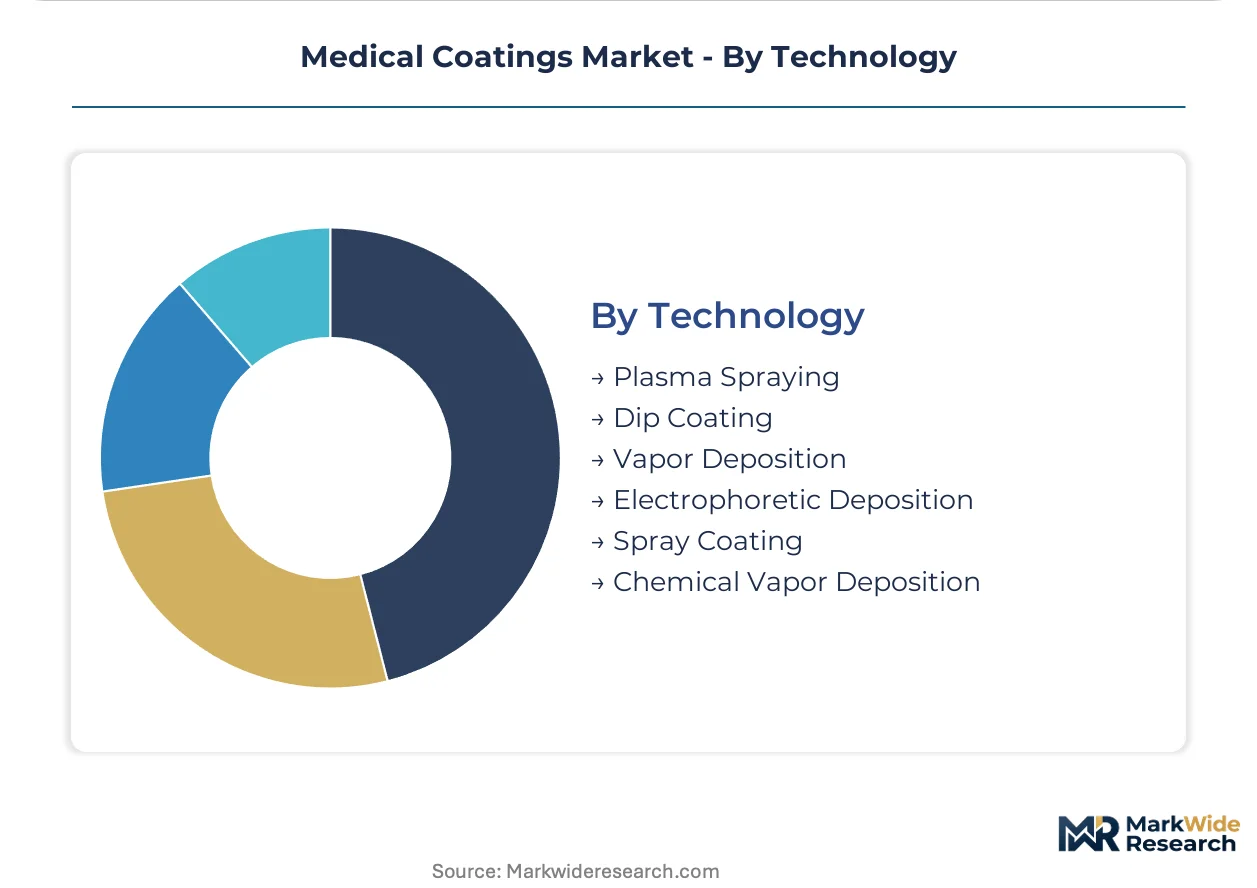
Technology:
Manufacturing scale and deposition precision separate high-throughput commodity methods from specialized platforms serving implantable electronics.
- Chemical Vapor Deposition:Parylene conformal coatings achieve sub-micron uniformity for neurostimulator leads and implantable sensors. Boston Scientific and Medtronic facilities adopt these processes for next-generation device miniaturization.
- Plasma Spraying:Hydroxyapatite and ceramic coatings bond to orthopedic implants for osseointegration. German and Swiss manufacturers leverage this technology for hip and knee replacement components under MDR clinical evidence requirements.
- Vapor Deposition:Physical and chemical variants deposit metal and ceramic thin films for electrode and barrier applications.
- Electrophoretic Deposition:Uniform polymer coating of complex geometries suits stent and guidewire manufacturing.
- Dip Coating:High-throughput immersion processes serve commodity antimicrobial and hydrophilic applications.
- Spray Coating:Robotic application systems enable gradient drug-eluting profiles on balloon catheters.
Dip coating dominates shipment volumes while chemical vapor deposition climbs the fastest as implantable electronics proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortiums and device manufacturing clusters concentrate coating demand across three dominant geographies. The United States, Germany, and China host the largest medical device manufacturing bases and regulatory approval pathways. Each market imposes distinct qualification burdens that reshape supplier competitive positioning.
United States
FDA PMA pathway expansion for cardiovascular implants intensifies coating stability validation requirements. EPA antimicrobial reclassification reviews extend commercialization timelines for silver-ion formulations. Boston Scientific and Medtronic facilities in Minnesota and Massachusetts drive demand for sub-micron parylene deposition processes in neurostimulator lead manufacturing.
Germany
EU MDR Article 10 technical documentation mandates accelerate coating qualification costs for orthopedic and cardiovascular device exporters. German notified bodies demand real-world evidence supplements to preclinical biocompatibility packages. Manufacturing clusters in Baden-Württemberg and Bavaria concentrate plasma spraying capacity for hydroxyapatite-coated hip and knee replacement components.
China
NMPA harmonization with ISO 10993 standards opens market access for foreign coating suppliers previously blocked by divergent testing protocols. Domestic cardiovascular stent manufacturers in Shanghai and Beijing prioritize drug-eluting coating platforms for regulatory differentiation. Local production incentives under medical device PLI schemes attract qualification lab investments from multinational suppliers.
Netherlands
DSM-Firmenich's biomedical materials division anchors European hydrophilic and antimicrobial coating supply. Dutch notified bodies enforce stricter post-market surveillance mandates under MDR clinical evidence requirements. Eindhoven-region manufacturing facilities specialize in polymer chemistry for catheter and guidewire surface modifications serving German and French device exporters.
India
CDSCO pathway acceleration under medical device manufacturing PLI schemes creates first-mover advantage for coating suppliers establishing local qualification infrastructure. Mumbai and Ahmedabad clusters concentrate catheter and surgical instrument manufacturing for domestic and export markets. Indian orthopedic implant manufacturers increasingly specify antibiotic-loaded bone cement coatings as joint replacement volumes rise.
Medical Coatings Market Key Industry Players
Player mix skews toward specialized surface modification firms with dedicated toxicology infrastructure and diversified chemical conglomerates with biomedical divisions. ISO 10993 biocompatibility certification requirements compress the mid-tier supplier base, forcing exits or consolidation while specialized players capture disproportionate margin. Two strategic archetypes dominate: integrated surface engineering platforms serving interventional device manufacturers, and polymer chemistry specialists competing on proprietary antimicrobial formulations. Dominant competitive moves include capacity expansion in Asia-Pacific qualification labs and technology licensing partnerships with cardiovascular implant manufacturers seeking pre-qualified coating platforms.
Within the specialized coating platform tier, Surmodics occupies a position exemplifying surface modification expertise for interventional devices, while Hydromer represents proprietary polymer chemistry capabilities for antimicrobial and lubricious applications. DSM-Firmenich anchors the diversified chemical conglomerate archetype through its Netherlands-based biomedical materials division. These three firms collectively illustrate how regulatory qualification depth and manufacturing scale separate premium-positioned suppliers from commodity antimicrobial coating competitors facing margin compression.
| Leading Market Players |
|---|
| Surmodics |
| Hydromer |
| DSM-Firmenich |
| Biocoat Incorporated |
| Covalon Technologies |
| AST Products |
| Harland Medical Systems |
| Merit Medical Systems |
| Applied Medical Coatings |
| Others |
Cost & Logistics Intelligence
ISO 10993 biocompatibility certification gates both supplier qualification and price differentiation, compressing the vendor base to firms with dedicated toxicology infrastructure while stratifying pricing across certification tiers. Buyers face steeper qualification costs for drug-eluting formulations that command premium positioning against commoditized antimicrobial alternatives.
Pricing Analysis
Cost-plus contracts with platinum-group metal indexation dominate electrode coating procurement, tying final pricing to South African iridium and platinum feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels separates FDA PMA-validated drug-eluting platforms from ISO 10993-certified antimicrobial layers and unqualified commodity formulations. Pricing pressure stems from EPA antimicrobial reclassification extending commercialization timelines for silver-ion claims. Hospital value-analysis committees in the American Midwest exhibit highest price sensitivity, while German orthopedic manufacturers prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg port congestion compress margins for European hydrophilic coating distributors serving German device manufacturers. Raw material supply concentrates in the United States, Germany, and China, with polymer chemistry feedstock anchored in Dutch DSM-Firmenich facilities and Chinese domestic stent manufacturers. Formulation depends on South African platinum-group metals and specialized polymer precursors from Japanese and South Korean suppliers. Single-source vulnerability around iridium feedstock concentration creates structural risk. Distribution runs through medical device OEM direct procurement channels and specialized coating applicator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating qualification laboratory services represent the fastest-expanding recurring-revenue layer, outpacing hardware sales as ISO 10993-18 chemical characterization demands outstrip internal toxicology capacity at mid-tier device manufacturers.
For Market Incumbents: Secure pre-qualified coating platform partnerships with cardiovascular implant manufacturers facing FDA PMA pathway expansion, while consolidating toxicology infrastructure to defend margin against emerging polymer chemistry specialists. Capacity addition in Chinese qualification labs under NMPA harmonization protocols captures first-mover positioning before domestic competitors achieve ISO 10993 certification parity. For New Entrants and Emerging Players: Anchor in antibiotic-loaded bone cement coatings for Indian orthopedic implant manufacturers under CDSCO pathway acceleration, where PLI manufacturing incentives outpace established supplier qualification timelines. White-space concentration in neurovascular hydrophilic coatings for Shanghai and Beijing catheter producers offers penetrable entry before Surmodics and Hydromer extend platform licensing dominance. For Investors and Strategic Acquirers: EU MDR Article 10 clinical evidence requirements reshape the acquisition landscape toward coating platforms with existing biocompatibility dossiers over novel formulations requiring redundant validation cycles. Long-term viability centers on specialized surface engineering firms with captive toxicology infrastructure and hospital system partnership channels. The signal to watch is notified body backlog duration for drug-eluting stent technical documentation reviews.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Qualification Lab Expansion | Captures margin compression from mid-tier manufacturer exits under tightening biocompatibility standards. |
| FDA PMA Pre-Submission Partnership | De-risks regulatory timelines for cardiovascular implant manufacturers seeking coating stability validation. |
| Antimicrobial Polymer Licensing | Displaces silver-ion formulations facing EPA reclassification scrutiny with proprietary chemistry platforms. |
| China NMPA Harmonization Investment | Opens market access previously blocked by divergent testing protocols for foreign coating suppliers. |
| Orthopedic Drug-Eluting Convergence | Targets antibiotic-loaded bone cement white space as Indian joint replacement volumes accelerate. |
Research Approach
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists provided ongoing calibration across primary interview rounds and secondary validation. Stakeholder input combined with FDA 510(k) and PMA filing databases, EU MDR notified body technical documentation, hospital procurement contract repositories, and ISO 10993 certification registries. Bottom-up coating demand modeling triangulated against top-down medical device production forecasts.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework segmented demand by coating type, application, end user, and deposition technology, with regional regulatory cluster as an additional dimension. CAGRs derived from implant procedure volume trajectories, device manufacturing capacity expansion, and coating penetration rate assumptions. Forecast inputs incorporated platinum-group metal price volatility indices and notified body review duration trends.
Material uncertainties — EPA antimicrobial reclassification timing, South African mining supply disruptions, EU MDR clinical evidence requirement evolution — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and certification cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gynecology Devices Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Knee Walkers Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Infant Incubator Market
Medical Devices
Incontinence Devices and Ostomy Market