
 Neuro Ablation Devices Market | 2026-2036
Neuro Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neuro Ablation Devices Market Analytics
The EU Medical Device Regulation is consolidating demand around manufacturers with established quality management systems and notified body relationships. Medtronic plc leverages its broad portfolio across radiofrequency and cryoablation platforms to sustain hospital contract loyalty. Abbott Laboratories anchors its position through electrophysiology integration, while Boston Scientific Corporation differentiates via specialized access tools for hard-to-reach neural targets.
Neuro ablation devices deliver targeted thermal, cryogenic, or electromagnetic energy to interrupt pain signaling pathways or destroy neural tissue, typically operating at frequencies between 460 and 500 kHz for radiofrequency systems with impedance-controlled delivery algorithms. Radiofrequency ablation occupies the largest installed base due to decades of clinical validation and straightforward capital requirements, whereas robotic assistance represents the fastest-expanding technology segment as hospitals seek to reduce operator variability and improve lesion placement accuracy in spinal procedures. Imaging guidance systems command premium pricing because real-time CT or MRI overlay reduces revision rates and supports outcome-based reimbursement contracts.
The FDA's 510(k) clearance pathway and the EU MDR's enhanced clinical evaluation requirements shape product development timelines and market access costs for neural intervention devices. Japan's PMDA maintains distinct pharmaceutical and medical device agency review standards that delay entry for companies lacking local regulatory partnerships. Stakeholders must monitor evolving evidence requirements for long-term neuromodulation outcomes as payers tighten prior authorization criteria across major markets.
Market Dynamics
Robotic assistance platforms are compressing operator variability in spinal ablation procedures, forcing traditional radiofrequency manufacturers to integrate navigation capabilities or cede high-value hospital contracts to surgical robotics specialists.
Growth Catalysts
- EU MDR clinical evidence mandates:Class III neural device requirements are filtering out undercapitalized competitors, concentrating procurement among manufacturers with established notified body relationships and quality management systems.
- Chronic pain intervention reimbursement:Germany, the United States, and Japan have matured prior authorization pathways that reduce economic friction for radiofrequency ablation in tertiary hospital pain management departments.
- Imaging guidance integration:Real-time CT and MRI overlay capabilities command premium pricing by reducing revision rates and supporting value-based care contracts with payers.
Market Restraints
- Capital intensity of robotic platforms:Spinal navigation systems require seven-figure hospital investments that limit penetration outside academic medical centers and large health systems.
- Supply concentration in radiofrequency generators:Core impedance-controlled delivery algorithms depend on specialized semiconductor fabrication concentrated in East Asian foundries.
- Substitution from neuromodulation:Spinal cord stimulation and peripheral nerve stimulation devices compete for overlapping chronic pain indications with reversible intervention profiles.
Strategic Opportunities
- Underpenetrated ambulatory surgical centers:United States outpatient facilities lack robotic ablation capabilities, creating white space for compact, cart-based navigation systems with simplified workflows.
- Technology convergence with electrophysiology:Integration of cardiac mapping algorithms into neural targeting is enabling cross-platform utilization and shared capital equipment across hospital departments.
- Japan PMDA regulatory partnerships:Local clinical trial collaborations accelerate market entry for foreign manufacturers navigating distinct pharmaceutical and medical device agency review standards.
Industry Challenges
- Interventional neuroradiology talent scarcity:Specialized training pipelines for CT- and MRI-guided ablation procedures lag behind equipment deployment, creating utilization bottlenecks in community hospitals.
- Legacy EMR integration complexity:Ablation procedure documentation and outcome tracking require custom interface development with hospital information systems, extending implementation timelines.
- Notified body capacity constraints:EU MDR transition has created eighteen-month backlog for class III device conformity assessments, delaying product launches and freezing R&D prioritization decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuro Ablation Devices Market |
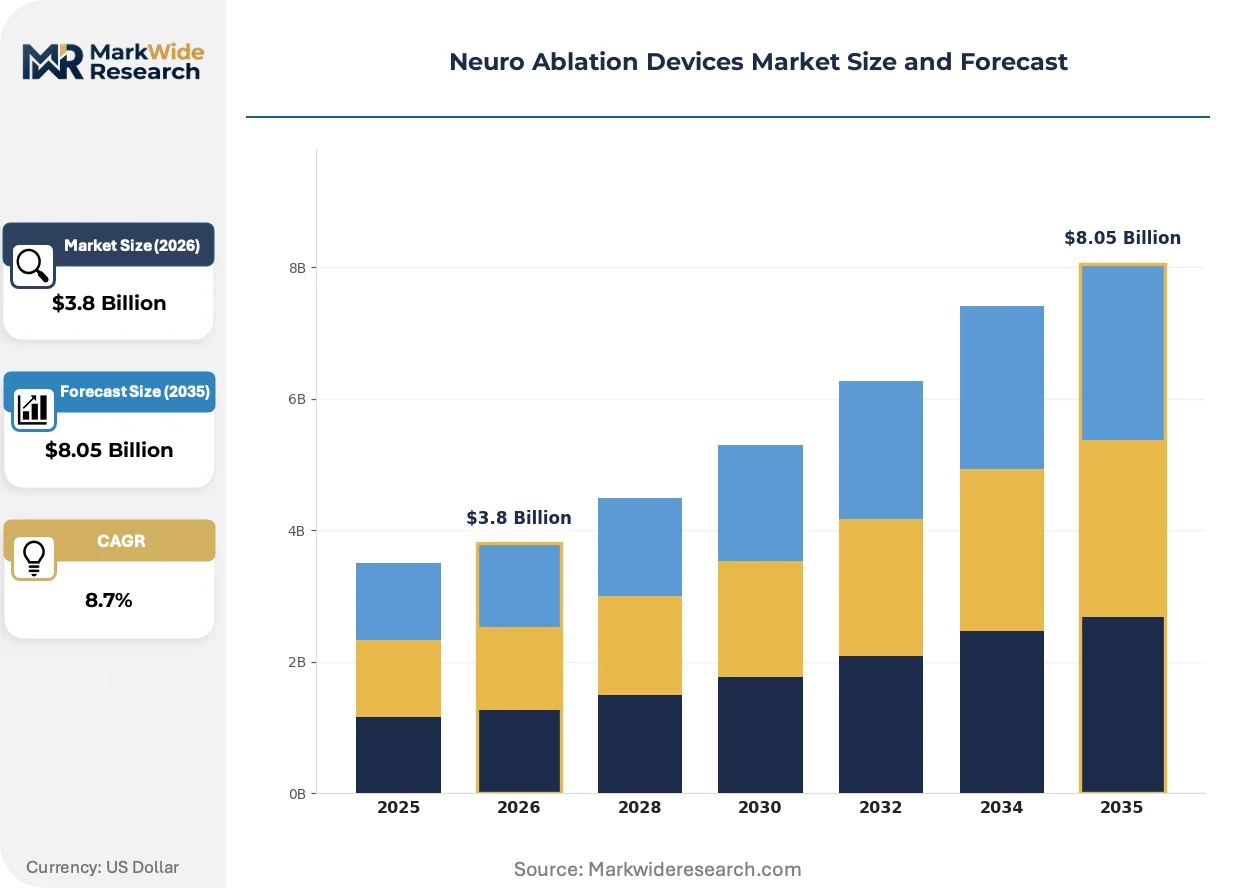
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation, Cryoablation, Microwave Ablation, Laser Ablation End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Technology: Electrophysiological Mapping, Imaging Guidance, Robotic Assistance, Thermal Monitoring Application: Pain Management, Tumor Ablation, Neuromodulation, Cardiac Arrhythmias |
| Companies Covered | Medtronic plc, Abbott Laboratories, Johnson & Johnson, Boston Scientific Corporation, AngioDynamics Inc., Biotronik SE & Co. KG, Stryker, AtriCure, Inc., Nevro Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuro Ablation Devices Market Evolving Landscape
Energy delivery precision and procedural workflow integration are the dominant vectors of competitive differentiation, with manufacturers racing to embed intelligence into ablation platforms before commoditization pressures erode hardware margins.
Pulsed radiofrequency technology is rewriting thermal lesion control by delivering energy in intermittent bursts that modulate neural signaling without destructive coagulation. Pain management specialists in German university hospitals are adopting these systems for neuropathic pain indications where traditional thermal ablation risks deafferentation complications. The technology is compressing the addressable market for cryoablation in facial neuralgia applications by offering comparable safety profiles with faster procedural times.
EU MDR Article 61 clinical evaluation requirements are restructuring product development economics by mandating systematic literature reviews and post-market clinical follow-up for class III neural devices. Manufacturers must now budget for multi-year evidence generation before CE marking, shifting competitive advantage toward incumbents with existing clinical data repositories. Small and mid-cap entrants are responding through predicate device strategies and notified body pre-submission consultations to de-risk regulatory timelines.
Hospital purchasing committees are consolidating vendor relationships around platforms that bundle capital equipment, disposables, and training into multi-year service agreements. Traditional capital sales models in the United States are yielding to risk-sharing arrangements where manufacturers guarantee outcome thresholds or procedure volume minimums. This restructuring is most visible in integrated delivery networks seeking to standardize ablation protocols across geographically dispersed facilities while capturing economies of scale in consumable procurement.
Neuro Ablation Devices Market Segmentation
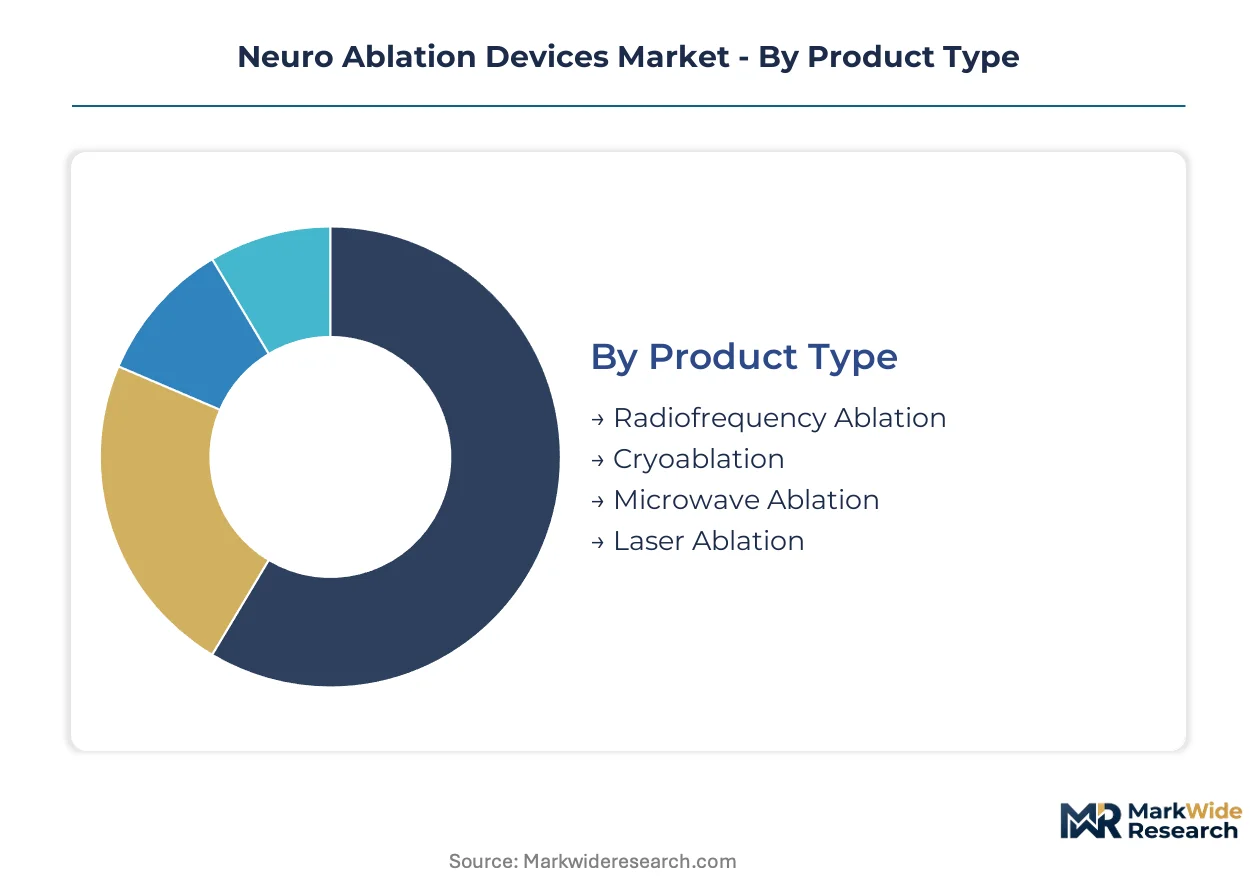
Neuro ablation devices fragment across energy modalities, procedural settings, and technological sophistication tiers. Procurement committees weight capital requirements against reimbursement pathways when segmenting vendor selection criteria.
Product Type:
Radiofrequency ablation systems demand the highest upfront capital commitment among thermal platforms, with impedance-controlled generators and proprietary electrode configurations locking hospitals into multi-year consumable contracts.
- Radiofrequency Ablation:Systems operate at 460-500 kHz with real-time impedance feedback algorithms. German university hospitals concentrate procurement for chronic pain protocols where decades of clinical validation support prior authorization pathways. Thermal lesion predictability drives preference over newer modalities despite higher disposable costs.
- Cryoablation:Pressurized gas delivery systems create reversible nerve blocks at -40°C to -60°C. Demand clusters in facial neuralgia applications within Japanese tertiary centers where PMDA pathways favor established cryogenic safety profiles. Slower procedural throughput limits penetration outside academic settings.
- Microwave Ablation:Electromagnetic field generators at 915 MHz or 2.45 GHz enable larger ablation zones with shorter treatment times. Adoption concentrates in tumor ablation protocols.
- Laser Ablation:Fiber-optic delivery of 980-1064 nm energy permits minimally invasive access to deep neural structures. Research laboratories in the United States pilot intraoperative MRI integration.
Most installed capacity flows through radiofrequency ablation. Expansion is steepest in cryoablation.
End User:
Facility reimbursement status and case-mix complexity determine technology deployment patterns across care settings.
- Hospitals:Tertiary centers with comprehensive pain management departments anchor demand for integrated imaging guidance and robotic navigation platforms. Outcome-based contracts with commercial payers in the United States favor capital-intensive systems that reduce revision rates.
- Ambulatory Surgical Centers:United States outpatient facilities lack robotic capabilities, creating demand for compact cart-based radiofrequency systems with simplified workflows and rapid turnover protocols.
- Specialty Clinics:Independent pain practices in Germany prioritize portable radiofrequency generators with lower throughput requirements.
- Research Laboratories:Academic medical centers in Japan pilot next-generation energy modalities under PMDA-supervised clinical trial frameworks.
Procedure volume concentrates in hospital settings. Steepest expansion trajectory belongs to ambulatory surgical centers.
Technology:
Integration depth with existing hospital infrastructure separates premium platforms from commoditized hardware tiers.
- Imaging Guidance:Real-time CT and MRI overlay systems command premium pricing by reducing revision rates. German procurement committees prioritize these capabilities for value-based care contracts.
- Robotic Assistance:Spinal navigation platforms compress operator variability in lesion placement accuracy. Academic medical centers in the United States drive adoption despite seven-figure capital requirements.
- Electrophysiological Mapping:Cardiac-derived algorithms enable cross-platform utilization across hospital departments.
- Thermal Monitoring:Integrated temperature feedback loops protect adjacent neural tissue during ablation procedures.
Imaging guidance captures the largest technology investment share. Robotic assistance gains share fastest.
Application:
Clinical indication breadth and reimbursement clarity determine addressable market sizing for each application segment.
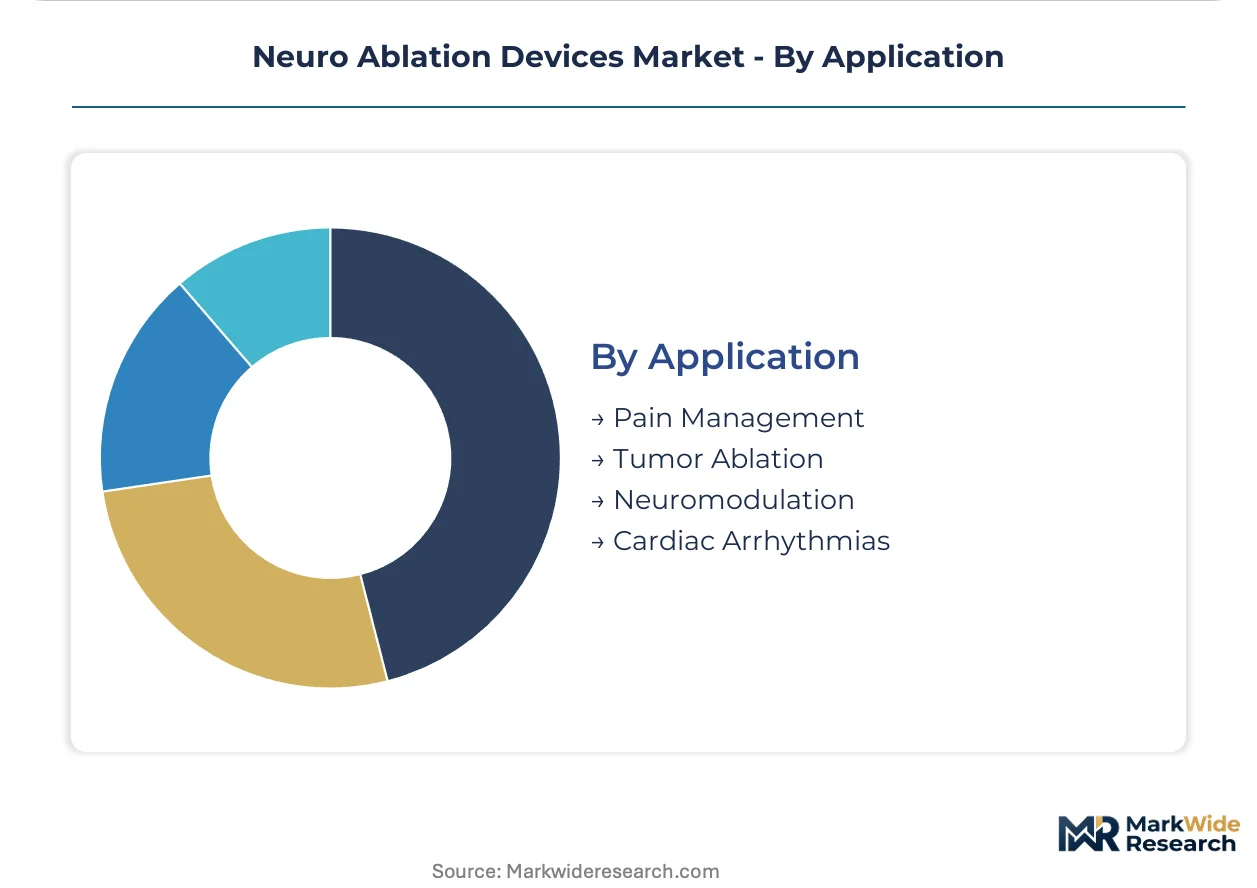
- Pain Management:Chronic back and neuropathic pain protocols generate the largest procedure volume. Mature prior authorization pathways in Germany, the United States, and Japan reduce economic friction for radiofrequency interventions.
- Tumor Ablation:Metastatic neural lesion treatment drives demand for microwave and laser platforms with larger ablation zones. Japanese oncology centers pilot combination therapies.
- Neuromodulation:Reversible intervention profiles compete with spinal cord stimulation devices for overlapping indications.
- Cardiac Arrhythmias:Electrophysiology crossover applications leverage shared mapping infrastructure with neural targeting systems.
Pain management absorbs the dominant share of installed devices. Tumor ablation climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiofrequency ablation technology originated in German university hospitals during the 1970s, establishing clinical protocols that now dominate chronic pain management worldwide. Germany's early investment in thermal lesion research created regulatory templates and reimbursement frameworks that subsequent markets adopted.
United States
Tertiary hospital pain management departments drive procurement of integrated imaging guidance systems. The FDA's 510(k) clearance pathway shapes product development timelines for neural intervention devices. Academic medical centers in Boston and Cleveland anchor adoption of robotic spinal navigation platforms despite seven-figure capital requirements.
Germany
University hospitals concentrate demand for pulsed radiofrequency systems treating neuropathic pain indications. The EU MDR's Article 61 clinical evaluation requirements filter device approvals toward manufacturers with established notified body relationships. Medical technology clusters in Baden-Württemberg and Bavaria host specialized training pipelines for CT-guided ablation procedures.
Japan
Tertiary oncology centers pilot combination therapies using microwave and laser platforms for metastatic neural lesions. The PMDA maintains distinct pharmaceutical and medical device agency review standards that delay market entry without local clinical trial partnerships. Tokyo and Osaka academic medical centers supervise next-generation energy modality trials under national regulatory frameworks.
United Kingdom
Integrated delivery networks seek standardized ablation protocols across geographically dispersed facilities. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment pathways alongside retained EU MDR requirements. London and Manchester hospital systems negotiate risk-sharing arrangements where manufacturers guarantee procedure volume minimums.
Switzerland
Swissmedic's streamlined class III device reviews attract manufacturers seeking faster European market access. Geneva and Zurich university hospitals emphasize outcome-based contracts with commercial payers favoring capital-intensive systems that reduce revision rates. The country's precision manufacturing heritage supports specialized semiconductor fabrication for impedance-controlled delivery algorithms.
Neuro Ablation Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and clinical evidence repositories. The vendor base stratifies into three tiers: diversified medtech conglomerates with broad ablation portfolios, specialized neural intervention firms with targeted access tools, and emerging robotics platforms compressing operator variability. Consolidation pressures intensify as hospital purchasing committees demand bundled capital-disposable-training agreements spanning multi-year service contracts.
Among diversified medtech conglomerates, Medtronic plc and Abbott Laboratories anchor the premium tier through established hospital contract loyalty and cross-platform electrophysiology integration. Boston Scientific Corporation occupies a specialized position with differentiated access tools for hard-to-reach neural targets. These three exemplify how incumbents leverage existing clinical data repositories and notified body relationships to navigate tightened EU MDR evidence requirements while smaller entrants face multi-year regulatory timelines.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Johnson & Johnson |
| Boston Scientific Corporation |
| AngioDynamics Inc. |
| Biotronik SE & Co. KG |
| Stryker |
| AtriCure, Inc. |
| Nevro Corp. |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in the United States and German hospital purchasing committees concentrate procurement volume, locking vendors into multi-year bundled contracts that blend capital equipment, disposables, and training services rather than transactional per-procedure pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the neuro ablation device market. Premium tiers attach to robotic navigation platforms with imaging guidance integration, while standard tiers cover radiofrequency generators with impedance-controlled algorithms, and economy tiers serve portable units for ambulatory settings. Price differentiation hinges on CE marking tier under EU MDR and FDA 510(k) clearance status, alongside after-sales service bundling. Cost compression in the economy tier is intensifying because ambulatory surgical centers demand simplified workflows at lower capital thresholds. Ambulatory surgical centers exhibit the highest price sensitivity, whereas academic medical centers prioritize outcome guarantees over unit economics.
Supply Chain Analysis
ISO 13485 certification and notified body relationships gate supplier access to tier-one medical device manufacturers, filtering component vendors toward established quality management systems. Semiconductor fabrication for impedance-controlled delivery algorithms centers on Taiwan, South Korea, and Japan, while precision manufacturing of radiofrequency electrodes concentrates in Germany and Switzerland. Raw material dependencies include specialized ceramics for thermal insulation, biocompatible alloys for electrode construction, and high-purity pressurized gases for cryoablation systems. Single-source vulnerability in East Asian foundry capacity for radiofrequency generator chips poses structural risk. Distribution runs through specialized medical device distributors with GPO contracts and direct hospital sales forces for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through software companion development and outcome-based contracting, as hospitals shift procurement criteria toward guaranteed revision-rate thresholds that premium-tier vendors can monetize.
For Market Incumbents: Deepen software integration into ablation platforms to capture recurring revenue streams and defend against surgical robotics specialists encroaching on spinal procedures. Invest in notified body pre-submission consultations to accelerate EU MDR Article 61 compliance timelines. Prioritize backward integration into specialized semiconductor sourcing to mitigate East Asian foundry concentration risk. For New Entrants and Emerging Players: Begin with compact cart-based navigation systems for United States ambulatory surgical centers, where robotic capabilities remain underpenetrated and capital constraints favor simplified workflows. Target independent pain practices in Germany with portable radiofrequency generators lacking imaging guidance. Pursue predicate device regulatory strategies to leverage existing clinical data repositories and compress time-to-market. For Investors and Strategic Acquirers: Surgical robotics platforms are the most active acquirer in this space, seeking neural ablation capabilities to complete spinal navigation portfolios. The five-to-ten year viability window favors manufacturers with established notified body relationships and post-market clinical follow-up infrastructure. Acquisition target archetypes include specialized access tool developers and pulsed radiofrequency technology holders. The signal to watch is EU MDR conformity assessment backlog resolution, which would unlock frozen R&D prioritization decisions and trigger consolidation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 61 compliance unlocks access to German university hospital procurement committees. |
| Hospital System Partnership | Multi-year service agreements with integrated delivery networks standardize protocols across dispersed facilities. |
| Software Companion Development | Real-time lesion monitoring algorithms command premium pricing and reduce operator variability. |
| Reimbursement Strategy | Prior authorization pathway navigation in Japan's PMDA framework accelerates commercial traction. |
| Strategic Partnership | Electrophysiology crossover agreements with cardiac mapping vendors enable shared capital utilization. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down radiofrequency generator shipment tracking forms the analytical core of this study. Primary interviews with pain management clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers were cross-validated against secondary sources including FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement data. This dual-layer approach ensures segmentation integrity across energy modalities, procedural settings, and technological sophistication tiers.
Historical trendline analysis of radiofrequency ablation procedure volumes and capital equipment replacement cycles established baseline growth patterns. The analytical framework projects expansion across the analysis window by modeling product type, end user facility class, technology integration depth, and clinical application indication. CAGRs were derived from weighted regression of installed base growth, reimbursement pathway maturation, and technology substitution elasticities. Industry-specific forecast inputs include EU MDR conformity assessment queue dynamics and PMDA clinical trial partnership formation rates.
Several conditions sit outside the modeled scope, including unannounced regulatory guidance revisions, abrupt reimbursement code changes, and supply chain disruptions from geopolitical events. Forecasts reflect assumptions about continued prior authorization pathway stability in Germany, the United States, and Japan. A model refresh is warranted upon material change in EU MDR notified body capacity or FDA 510(k) clearance timeline standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pedicle Screw Systems Market
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Global Ventilators Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Tubal Obstruction Devices Market