
 Pediatric HIV Infection Treatment Market | 2026-2036
Pediatric HIV Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric HIV Infection Treatment Market Analytics
Pediatric infectious disease specialists is reorganizing treatment access across high-burden regions. ViiV Healthcare dominates pediatric formulation development with its dispersible dolutegravir portfolio. Gilead Sciences sustains competitive positioning through its tenofovir alafenamide-based combinations with improved bone safety profiles for growing children.
Pediatric HIV infection treatment encompasses antiretroviral-based therapeutic interventions designed to suppress viral replication in patients from birth through adolescence, typically employing weight-band dosing algorithms and palatable formulations to overcome adherence barriers. These therapies functionally aim to restore CD4+ lymphocyte counts, prevent opportunistic infections, and enable normal immunological development. Combination antiretroviral therapy leads the product type landscape due to superior resistance profiles and simplified dosing schedules, while oral delivery mode anchors volume through its suitability for community-based administration programs. Pediatric clinics represent the fastest-growing end user segment as decentralized care models shift initiation and monitoring away from hospital settings.
FDA's pediatric study requirements under the Pediatric Research Equity Act shape formulation development timelines, while WHO prequalification standards determine procurement eligibility for low-income country programs. South Africa's Medicines Control Council and India's CDSCO enforce bioequivalence standards that filter substandard generics from national treatment pipelines. Stakeholders must monitor emerging long-acting injectable platforms and their compatibility with adolescent adherence patterns.
Market Dynamics
WHO prequalification standards are compressing formulation development timelines as manufacturers race to meet consolidated pediatric dosing guidelines before national procurement windows open.
Growth Catalysts
- Donor-funded procurement channels:PEPFAR and Global Fund commitments in sub-Saharan Africa lock in multi-year volume guarantees for dispersible antiretroviral formulations.
- WHO consolidated guidelines:Standardized weight-band dosing algorithms reduce clinical complexity and enable task-shifting to community health workers.
- Decentralized care models:Pediatric clinics in Kenya and Nigeria now initiate therapy outside hospital settings, expanding addressable patient pools.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for dolutegravir concentrates among Indian and Chinese suppliers, exposing programs to export restriction risk.
- Paediatric Investigation Plan requirements:EMA mandates extend development timelines by 18-24 months for European market access.
- Formulation stability barriers:Heat-stable alternatives to cold-chain-dependent liquid formulations remain technically limited for protease inhibitor classes.
Strategic Opportunities
- Long-acting injectable platforms:Cabotegravir-rilpivirine monthly formulations are displacing daily oral regimens for adolescent adherence support.
- Point-of-care viral load testing:Integration with community-based pediatric clinics enables same-day treatment optimization in South Africa.
- India's PLI scheme:Production-linked incentives for pharmaceutical manufacturing attract backward integration into pediatric formulation capacity.
Industry Challenges
- Paediatric pharmacokinetic expertise:Clinical trial networks lack sufficient investigators trained in neonatal and adolescent metabolism studies.
- Legacy supply contracts:Multi-year procurement agreements with originator manufacturers block rapid generic substitution even after patent expiry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric HIV Infection Treatment Market |
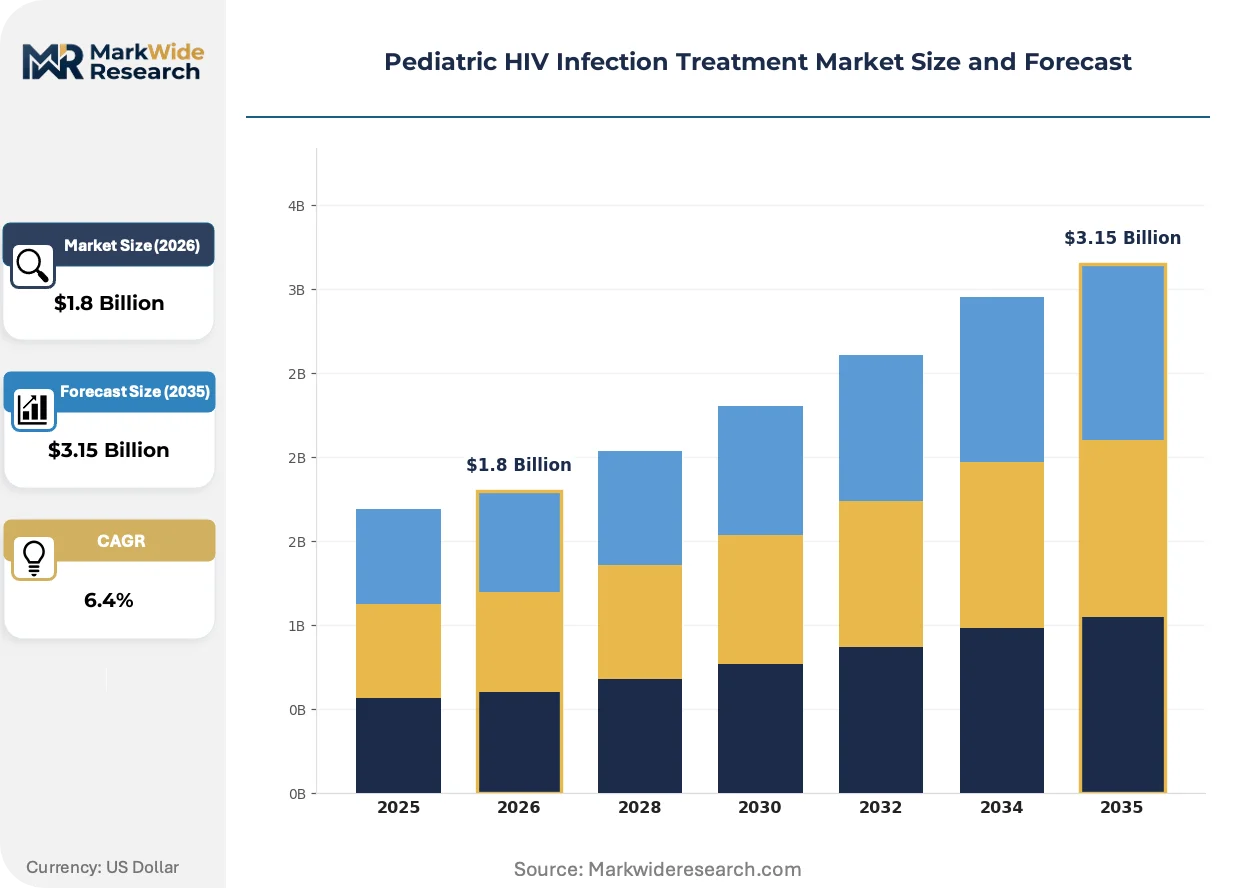
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiretroviral Drugs, Monotherapy, Combination Therapy, Vaccines Delivery Mode: Oral, Injectable, Infusion, Topical End User: Pediatric Clinics, Hospitals, Home Care, Research Institutions Therapy Area: Viral Suppression, Immune Restoration, Treatment Adherence, Prevention Strategies |
| Companies Covered | ViiV Healthcare, Gilead Sciences, Janssen Pharmaceuticals, Merck, AbbVie, Aurobindo Pharma, Bristol-Myers Squibb, Viatris, Genentech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric HIV Infection Treatment Market Evolving Landscape
Formulation science and service delivery models are converging to address adherence barriers that have historically suppressed treatment outcomes in pediatric populations.
Dispersible dolutegravir 10mg tablets are displacing liquid lopinavir-ritonavir as the first-line anchor in national programs. Ministries of health in Kenya and Uganda completed transitions during 2023 procurement cycles. The shift compresses cold chain requirements and reduces caregiver pill burden from twice-daily to once-daily administration.
FDA's Pediatric Research Equity Act amendments now mandate neonatal sub-studies for all new antiretroviral submissions. This regulatory friction extends development timelines but generates data gaps that generic manufacturers exploit for 505(b)(2) pathway entries. Indian firms with CDSCO-approved bioequivalence facilities capture accelerated review status.
Community health worker networks are absorbing tasks previously reserved for facility-based clinicians. In South Africa's Eastern Cape, accredited lay counselors now conduct adherence assessments and flag virological failure for physician review. This workforce extension is concentrating demand for simplified, pictogram-based dosing instructions that overcome literacy barriers.
Pediatric HIV Infection Treatment Market Segmentation
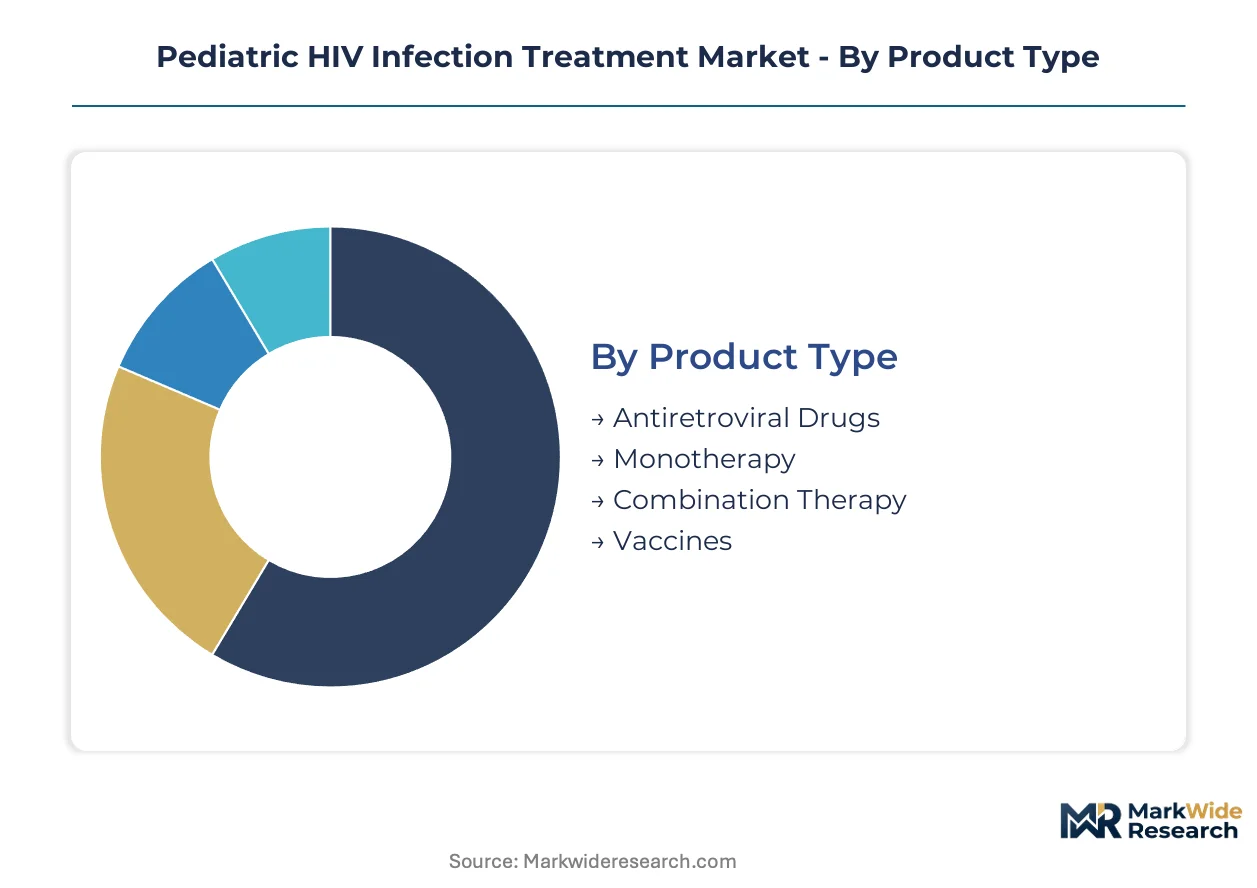
Pediatric HIV treatment pathways fragment across product formulations, administration routes, and care settings. Channel economics and patient age bands determine which segments capture procurement volume in donor-funded programs.
Product Type:
Channel flow splits between national tender programs for first-line regimens and hospital-based procurement for salvage therapy. Dispersible tablets dominate community channels while liquid formulations retain hospital share for neonates.
- Combination Therapy:Multi-drug fixed-dose combinations integrate dolutegravir with nucleoside reverse transcriptase inhibitors in weight-band scored tablets. Demand concentrates in Kenya's Mombasa County and Nigeria's Lagos State where community health workers dispense monthly supplies. WHO prequalification status determines eligibility for PEPFAR procurement windows.
- Antiretroviral Drugs:Broad category encompassing all drug classes targeting HIV replication. South Africa's national tender allocates 70% of volume to tenofovir alafenamide-based regimens for children over 25kg. Bone safety profiles drive preference over legacy tenofovir disoproxil fumarate.
- Monotherapy:Single-agent regimens reserved for neonatal prophylaxis and structured treatment interruptions. Zidovudine monotherapy retains niche use in PMTCT protocols where maternal viral load is undetectable.
- Vaccines:Investigational preventive and therapeutic candidates in Phase I/II trials. No approved products; research institutions in Uganda and Thailand host active cohort studies.
By volume, combination therapy leads. By growth pace, vaccines are climbing fastest through expanded trial networks.
Delivery Mode:
Patient age and caregiver literacy shape route selection more than clinical efficacy alone. Programs optimize for adherence support rather than pharmacokinetic perfection.
- Oral:Dispersible tablets and liquid syrups enable community-based administration without cold chain dependence. Kenya's differentiated care models deploy oral regimens through accredited drug dispensing outlets in rural Western Province.
- Injectable:Long-acting cabotegravir-rilpivirine monthly formulations target adolescents with demonstrated pill fatigue. South Africa's Western Cape pilots injectable transition at 15 years of age.
- Infusion:Intravenous zidovudine for neonates with suspected HIV infection pending PCR confirmation. Restricted to tertiary hospital neonatal units in Nigeria and Ethiopia.
- Topical:Microbicide gels and PrEP rings in development for adolescent girls. No commercialized products; demonstration projects in South Africa's KwaZulu-Natal evaluate acceptability.
Oral administration anchors procurement volume. Injectable platforms are expanding most quickly among adolescents.
End User:
Decentralization policies are redistributing patient volumes from centralized hospitals to community-based sites. Task-shifting regulations enable lower-cadre workers to initiate therapy.
- Pediatric Clinics:Dedicated sites with trained pediatric HIV nurses and point-of-care viral load capacity. Nigeria's Bayelsa State operates 34 such clinics with same-day result turnaround.
- Hospitals:Tertiary referral centers managing treatment failure, opportunistic infections, and complex comorbidities. South Africa's Groote Schuur Hospital in Cape Town serves as regional resistance testing hub.
- Home Care:Community health worker visits for stable patients with suppressed viral loads. Uganda's Family AIDS Care and Education Services model deploys counselors to patient homes.
- Research Institutions:Academic medical centers conducting pharmacokinetic studies and implementation science. Makerere University-Johns Hopkins collaboration in Kampala generates neonatal dosing data.
Pediatric clinics lead by patient enrollment. Home care is gaining share fastest through differentiated service delivery policies.
Therapy Area:
Programmatic targets cascade from viral suppression metrics to broader developmental outcomes. Donor indicators increasingly incorporate immunological recovery and retention in care.
- Viral Suppression:Primary endpoint driving procurement decisions and health worker performance metrics. South Africa's District Health Information System tracks suppression rates at 12 months post-initiation.
- Immune Restoration:CD4+ count recovery as secondary outcome predicting long-term survival. Kenyan guidelines prioritize immune restoration in children initiating therapy below 5 years of age.
- Treatment Adherence:Psychosocial support and pill burden reduction interventions. Nigeria's pediatric adherence clubs group stable adolescents for peer counseling.
- Prevention Strategies:PMTCT and pre-exposure prophylaxis for HIV-exposed infants. Uganda's Option B+ program integrates maternal and pediatric prevention services.
Viral suppression dominates outcome measurement. Prevention strategies are expanding most quickly through PMTCT platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sub-Saharan Africa consumes pediatric antiretroviral formulations through donor-funded procurement channels, while North American and European markets prioritize novel long-acting delivery platforms for adolescent adherence support.
South Africa
The Medicines Control Council enforces bioequivalence standards that filter substandard generics from national treatment pipelines. PEPFAR procurement windows lock in multi-year volume guarantees for dispersible dolutegravir formulations. The Western Cape pilots injectable cabotegravir-rilpivirine transitions at 15 years of age.
Nigeria
Federal Ministry of Health procurement concentrates demand in Lagos State and Bayelsa State where 34 dedicated pediatric clinics operate with same-day viral load turnaround. The country's national pharmaceutical regulator coordinates with WHO prequalification standards to accelerate generic formulation approvals. Community health worker networks in rural Western Province now initiate therapy outside hospital settings.
Kenya
Mombasa County anchors dispersible tablet distribution through community health workers dispensing monthly supplies. The Ministry of Health completed transitions from liquid lopinavir-ritonavir to dispersible dolutegravir during 2023 procurement cycles. Differentiated care models deploy oral regimens through accredited drug dispensing outlets.
Uganda
The Option B+ program integrates maternal and pediatric prevention services across Kampala and surrounding districts. Makerere University-Johns Hopkins collaboration generates neonatal dosing data that shapes regional guidelines. Family AIDS Care and Education Services deploys counselors to patient homes for stable patients with suppressed viral loads.
India
CDSCO-approved bioequivalence facilities capture accelerated review status for 505(b)(2) pathway entries. The Production-Linked Incentive scheme attracts backward integration into pediatric formulation capacity. Indian suppliers concentrate active pharmaceutical ingredient manufacturing for dolutegravir, exposing programs to export restriction risk.
Pediatric HIV Infection Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in pediatric HIV therapeutics. Originators with vertically integrated formulation pipelines control first-line dispersible tablet markets, while generic manufacturers compete on bioequivalence certification and WHO prequalification status. Two strategic archetypes dominate: vertically integrated originators with pediatric-specific portfolios, and CDSCO-approved generic houses with accelerated regulatory pathways. Competitive moves concentrate on portfolio diversification into long-acting injectable platforms and strategic partnerships with community health worker networks.
Within the originator tier, ViiV Healthcare and Gilead Sciences exemplify vertically integrated leaders. ViiV Healthcare occupies a position anchored in dispersible dolutegravir formulation development, while Gilead Sciences sits within the tenofovir alafenamide-based combination segment. Among generic manufacturers, Aurobindo Pharma represents CDSCO-approved bioequivalence facilities capturing accelerated review status.
| Leading Market Players |
|---|
| ViiV Healthcare |
| Gilead Sciences |
| Janssen Pharmaceuticals |
| Merck |
| AbbVie |
| Aurobindo Pharma |
| Bristol-Myers Squibb |
| Viatris |
| Genentech |
| Others |
Value Network & Pricing Analysis
Dispersible dolutegravir tablets replacing liquid lopinavir-ritonavir formulations are compressing cold chain costs while shifting procurement power toward Indian and Chinese API suppliers. This substitution simultaneously reduces per-patient treatment costs and concentrates upstream pricing leverage among active pharmaceutical ingredient manufacturers.
Pricing Analysis
Long-term offtake contracts with PEPFAR and Global Fund lock in volume guarantees that suppress spot market volatility for first-line regimens. Price differentiation rests on WHO prequalification status and bioequivalence certification tier, with CDSCO-approved facilities commanding modest premiums over standard generic entrants. Cost compression in dispersible tablet categories is intensifying because Kenyan and Nigerian ministries of health consolidate tenders around fewer suppliers. Donor-funded national programs exhibit highest price sensitivity, while hospital-based salvage therapy procurement shows lowest sensitivity due to clinical urgency.
Supply Chain Analysis
API manufacturing for dolutegravir concentrates among Indian and Chinese suppliers, exposing procurement programs to export restriction risk. Raw material dependencies span tenofovir alafenamide intermediates, dolutegravir sodium, and lamivudine bulk compounds. Single-source vulnerability in heat-stable protease inhibitor formulation technology remains unresolved. Distribution runs through WHO prequalified depot networks in Johannesburg, Nairobi, and Lagos before final-mile delivery to pediatric clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as donor funding commitments stabilize following pandemic-era disruptions. Procurement volume guarantees from PEPFAR and Global Fund renewal cycles provide the cyclical anchor.
For Market Incumbents: Consolidate formulation portfolios around dispersible dolutegravir to defend against emerging generic entrants with 505(b)(2) pathway approvals. Backward integration into API production reduces exposure to Indian and Chinese supply concentration. Lock in multi-year procurement contracts with Nigeria's Federal Ministry of Health before patent cliff effects accelerate.
For New Entrants and Emerging Players: WHO prequalification fast-track status offers the most penetrable entry point for CDSCO-approved bioequivalence facilities targeting Kenyan and Ugandan tender windows. Pediatric adherence support services represent underserved white space with limited incumbent specialization. Lead with point-of-care viral load testing integration to differentiate from commodity tablet suppliers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generic manufacturers holding Indian formulation capacity but lacking WHO prequalification depth. Long-term viability hinges on adolescent long-acting injectable platform transitions over the coming decade. Monitor cabotegravir-rilpivirine pediatric indication submissions as inflection indicators for portfolio obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Neonatal sub-studies under FDA Pediatric Research Equity Act amendments generate competitive data moats. |
| Regulatory Approval Pathway | CDSCO bioequivalence certification unlocks accelerated WHO prequalification for sub-Saharan tenders. |
| Manufacturing Scale-Up | India's PLI scheme attracts backward integration into dispersible tablet production capacity. |
| Licensing Agreement | Technology transfers from ViiV Healthcare enable generic dolutegravir formulation entry. |
| Pipeline Diversification | Long-acting injectable platforms address adolescent adherence barriers in South Africa's Western Cape pilots. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric infectious disease specialists, national procurement officers at Nigeria's Federal Ministry of Health, regulatory affairs leads at CDSCO and South Africa's Medicines Control Council, and community health worker program directors in Kenya's Mombasa County. Secondary validation drew from WHO prequalification databases, PEPFAR procurement disclosures, ClinicalTrials.gov pediatric HIV entries, and national tender documentation from Kenya, Nigeria, and Uganda. Bottom-up patient volume estimates were triangulated against top-down donor funding allocation models.
Across the analysis window, the forecasting framework modeled demand trajectories across product type segments, delivery mode categories, end user settings, and therapy area outcomes. CAGRs were derived from regression analysis of historical procurement volumes against pediatric patient enrollment trends. Key inputs included WHO consolidated guideline adoption timelines, national program decentralization policies, and dispersible formulation transition schedules.
Decision-makers should treat outputs as directional under assumptions of sustained donor funding commitments and stable API export policies from India and China; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as long-acting injectable regulatory approvals and adolescent indication expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric Dental Market
Pediatrics
Pediatric Growth Hormone Deficiency Market
Pediatrics
Pediatric Mattress Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Chronic Rhinosinusitis Market