
 Oxygen Generator Market | 2026-2036
Oxygen Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Generator Market Analysis
ISO 13485 certification for medical device quality management is redrawing competitive boundaries in oxygen generator supply. Air Products and Chemicals, Inc. leverages its cryogenic expertise to anchor high-purity industrial contracts across North America. INMATEC GaseTechnologie GmbH & Co. KG specializes in compact PSA systems for decentralized healthcare settings. Linde plc dominates merchant gas channels while extending into on-site generation through engineering partnerships.
An oxygen generator produces concentrated oxygen from ambient air through pressure swing adsorption, vacuum pressure swing adsorption, membrane separation, or cryogenic distillation, typically delivering 90-99.5% purity depending on the technology and application requirements. PSA systems lead unit shipments due to lower capital requirements and simpler maintenance profiles, while cryogenic installations command premium margins in steel and chemical processing. Medical oxygen supply applications are expanding fastest as hospitals replace bulk liquid tanks with on-site generation for resilience planning. Portable installations attract new entrants seeking to serve homecare and emergency response segments where mobility determines contract awards.
The U.S. FDA regulates medical oxygen concentrators under 21 CFR 868.5590, enforcing performance and safety standards that filter out uncertified suppliers. EPA emissions guidelines for wastewater treatment plants indirectly boost oxygen generator demand by mandating dissolved oxygen thresholds in activated sludge processes. Stakeholders must monitor how evolving FDA cybersecurity guidance for connected medical devices affects smart oxygen concentrator architectures and data handling protocols.
Market Dynamics
The oxygen generator market is restructuring around hospital resilience mandates that prioritize on-site production over liquid oxygen supply chains, with India's PLI scheme for medical devices accelerating domestic manufacturing capacity and permanently altering procurement patterns in emerging economies.
Growth Catalysts
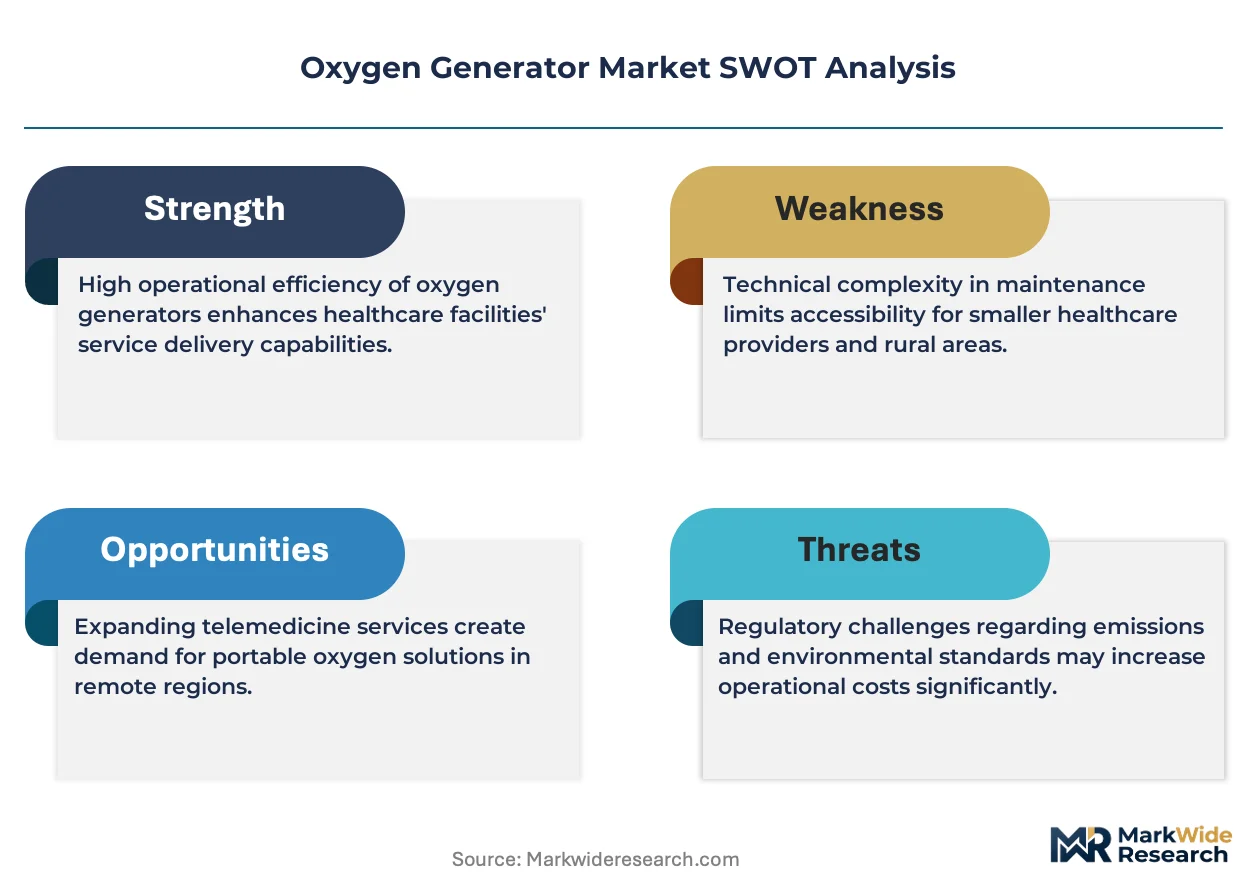
- Emerging economy hospital infrastructure:Healthcare facilities in India are scaling on-site oxygen production to reduce dependency on liquid oxygen deliveries, supported by post-pandemic capital investments and government-backed manufacturing incentives.
- ISO 13485 certification requirements:Medical device quality management standards are redrawing competitive boundaries, filtering out uncertified suppliers and consolidating procurement toward certified oxygen generator manufacturers.
- Pressure swing adsorption technology:PSA systems lead unit shipments due to lower capital requirements and simpler maintenance profiles, enabling decentralized healthcare deployment in resource-constrained settings.
Market Restraints
- Zeolite molecular sieve supply concentration:Critical PSA adsorbent production concentrates in China, creating input cost volatility and supply security risks for non-Chinese oxygen generator assemblers.
- Cryogenic distillation capex intensity:High-purity industrial oxygen generation requires substantial upfront capital that limits adoption among small-scale steel and chemical processors.
- US FDA 21 CFR 868.5590 compliance friction:Performance and safety certification timelines for medical oxygen concentrators extend market entry barriers for new suppliers.
Strategic Opportunities
- Homecare portable segment:Mobility-determined contract awards in emergency response and residential care create entry points for new competitors beyond established hospital supply relationships.
- EPA wastewater treatment mandates:Emissions guidelines mandating dissolved oxygen thresholds in activated sludge processes indirectly expand industrial oxygen generator demand.
- Smart concentrator cybersecurity frameworks:Evolving FDA guidance for connected medical devices enables differentiated architectures and recurring revenue service models.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise spanning gas separation physics, medical device regulation, and IoT integration remains concentrated among a limited supplier base.
- Legacy bulk tank infrastructure lock-in:Hospital capital planning cycles and existing liquid oxygen contracts create switching friction against on-site generation adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Generator Market |
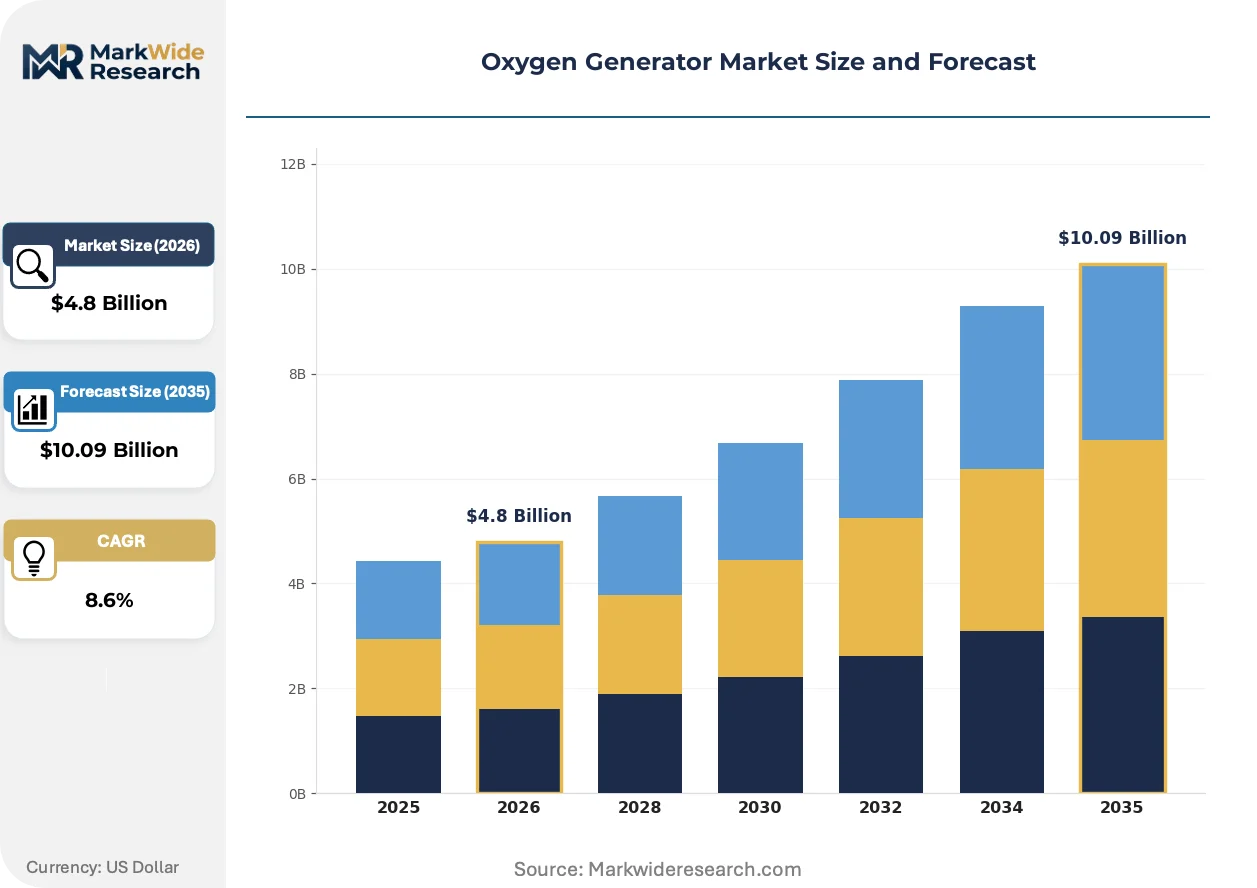
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
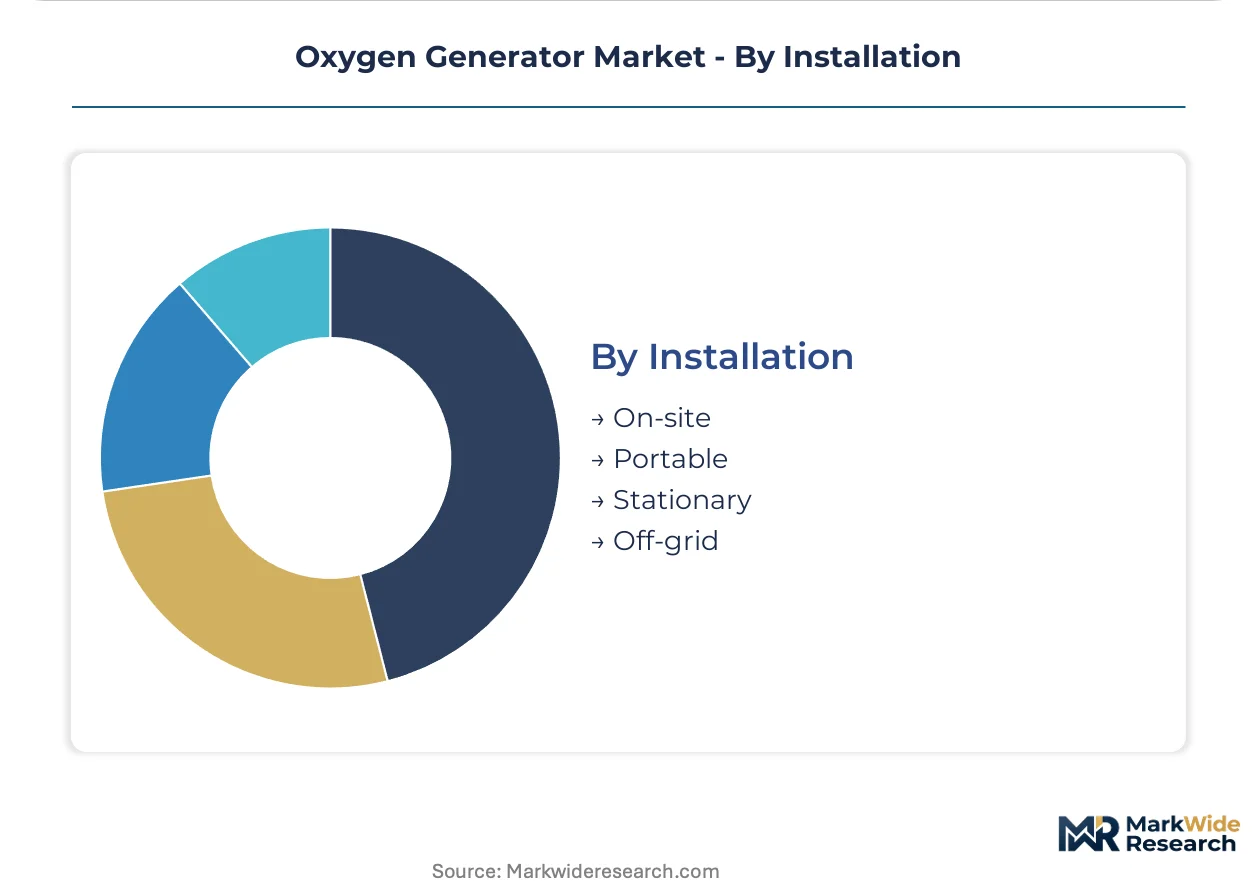
| Segmentation | Product Type: PSA, VPSA, Membrane, Cryogenic End User: Healthcare Facilities, Industrial Users, Aquaculture, Aerospace Application: Medical Oxygen Supply, Industrial Gas, Wastewater Treatment, Metal Fabrication Installation: On-site, Portable, Stationary, Off-grid |
| Companies Covered | Atlas Copco, Ingersoll Rand, Air Liquide, SIAD Macchine Impianti S.p.A., INMATEC GaseTechnologie GmbH & Co. KG, Air Products and Chemicals, Inc., OXYMAT, CAIRE Inc., Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Generator Market Emerging Trajectories
Modular PSA architectures and connected device platforms are actively restructuring competitive advantage in oxygen generation, compressing maintenance windows and enabling predictive service models that alter supplier-customer relationships.
Vacuum pressure swing adsorption is decomposing the traditional scale-purity tradeoff in medical oxygen supply. Mid-sized hospitals in Southeast Asia are adopting VPSA systems for 93-95% purity at throughput levels previously requiring cryogenic investment. This technology is decomposing the historical segmentation between portable concentrators and central supply systems, creating a middle tier of distributed generation nodes.
India's PLI scheme for medical devices is redirecting manufacturing investment toward domestic oxygen generator assembly. The incentive structure covers capital expenditure and component sourcing localization, with CDSCO medical device registration requirements tightening concurrently. Domestic producers are responding by establishing captive testing facilities to accelerate certification timelines.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts. Hospital procurement teams in Brazil are separating capital acquisition from aftermarket service, awarding multi-year performance contracts to independent technical service providers. This pattern is most visible in São Paulo's private hospital networks, where third-party PSA maintenance specialists now capture service revenue previously retained by original equipment suppliers.
Oxygen Generator Market Segmentation
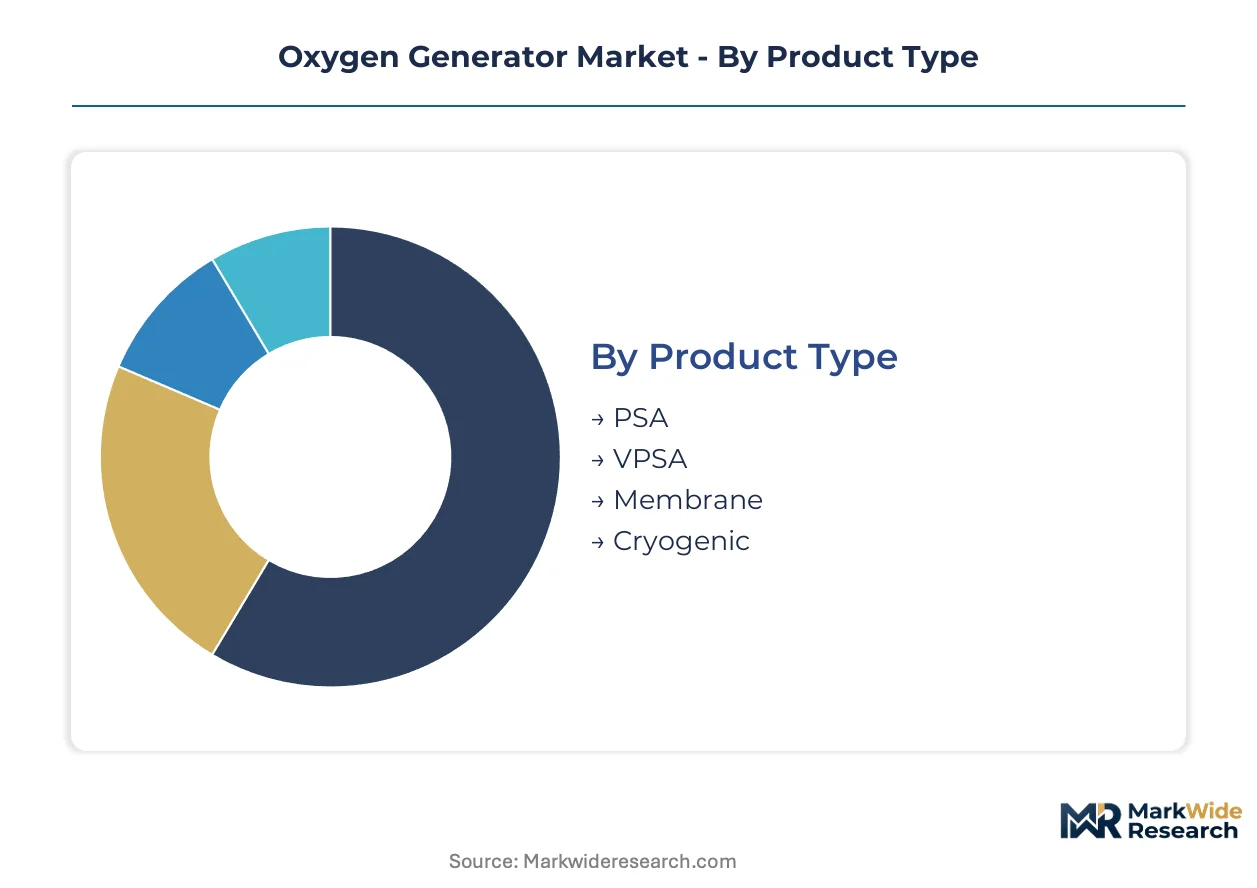
Oxygen generator procurement splits sharply across regulatory jurisdictions, with FDA 21 CFR 868.5590 governing medical devices while EPA wastewater mandates drive industrial specifications. Technology selection follows purity thresholds and capital availability rather than interchangeable substitution.
Product Type:
FDA 21 CFR 868.5590 compliance requirements and ISO 13485 certification standards create divergent competitive barriers across gas separation technologies.
- PSA:Pressure swing adsorption systems use zeolite molecular sieves to separate nitrogen from compressed air, achieving 90-96% oxygen purity. Indian hospital procurement under CDSCO registration requirements favors PSA for decentralized production, supported by PLI scheme capital subsidies for domestic assembly.
- VPSA:Vacuum pressure swing adsorption lowers operating pressure through vacuum regeneration, cutting energy consumption by 30-50% versus conventional PSA. Southeast Asian mid-sized hospitals in Thailand and Vietnam deploy VPSA for 93-95% purity at throughputs previously requiring cryogenic investment, decomposing the traditional scale-purity tradeoff.
- Membrane:Polymeric membrane separation delivers 30-40% oxygen enrichment for combustion enhancement and controlled atmosphere applications, dominating aquaculture aeration where purity requirements remain modest.
- Cryogenic:Air liquefaction and fractional distillation achieves 99.5%+ purity for steelmaking and chemical synthesis, with ASME pressure vessel certification and site-specific engineering limiting supplier participation to established industrial gas majors.
PSA handles the majority of throughput; VPSA is expanding most quickly on share as energy costs reshape operating economics.
End User:
Customer capital cycles and regulatory exposure determine technology-package bundling and service contract structures.
- Healthcare Facilities:Hospitals and clinics require FDA-cleared or CE-marked concentrators with 90%+ purity for patient ventilation and surgical support. Post-pandemic resilience planning in Brazil's São Paulo private networks drives replacement of bulk liquid tanks with on-site PSA generation.
- Industrial Users:Steel mills, chemical plants, and refineries consume high-purity oxygen for combustion enhancement and oxidation processes. Merchant gas contracts from Linde and Air Products dominate, though on-site cryogenic generation gains traction at integrated steel complexes in South Korea and Japan.
- Aquaculture:Fish farms and shrimp hatcheries use low-purity membrane systems for dissolved oxygen management in intensive recirculating systems.
- Aerospace:Aircraft onboard oxygen generation systems (OBOGS) employ pressure swing technology for crew breathing and fuel tank inerting, with FAA TSO-C89 certification governing airworthiness approvals.
Healthcare Facilities anchor equipment revenue; Industrial Users drive lifetime value through long-term gas supply agreements.
Application:
Purity specifications and flow rate requirements segment addressable markets into distinct procurement channels with limited cross-competition.
- Medical Oxygen Supply:Patient therapy, anesthesia, and critical care demand 90-99% purity with continuous flow reliability. India's Emergency Credit Line Guarantee Scheme financed hospital oxygen infrastructure expansion, accelerating PSA adoption in tier-2 and tier-3 cities.
- Industrial Gas:Steel cutting, welding, and chemical feedstock applications span 95-99.5% purity grades. EPA emissions guidelines for wastewater treatment plants indirectly boost demand through dissolved oxygen mandates in activated sludge processes.
- Wastewater Treatment:Municipal and industrial effluent facilities inject oxygen to maintain aerobic bacterial populations, with membrane systems capturing smaller plant installations below 50,000 population equivalent.
- Metal Fabrication:Oxy-fuel cutting and laser assist gas applications tolerate lower purity than chemical synthesis, opening entry points for VPSA suppliers.
Medical Oxygen Supply commands premium pricing; Wastewater Treatment is climbing the fastest on regulatory compliance deadlines.
Installation:
Mobility requirements and grid connectivity shape equipment packaging, power systems, and maintenance logistics.
- On-site:Permanent generation facilities integrated into hospital utilities or industrial plant infrastructure. Brazilian procurement teams increasingly separate capital acquisition from aftermarket service, awarding multi-year performance contracts to independent technical specialists.
- Portable:Battery and vehicle-mounted concentrators serve emergency response, military field hospitals, and homecare mobility. FDA emergency use authorizations during respiratory crises permanently shifted procurement standards toward decentralized supply.
- Stationary:Fixed-position PSA and VPSA systems dominate healthcare central supply installations, with modular architectures enabling capacity expansion without full replacement.
- Off-grid:Solar-hybrid and diesel-powered systems address remote mining camps, disaster relief, and rural clinics beyond reliable electrical infrastructure.
On-site installations absorb the bulk of capital expenditure; Portable configurations are gaining share fastest in homecare and emergency response segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical devices is redirecting manufacturing investment toward domestic oxygen generator assembly. Healthcare facilities across emerging economies are scaling on-site production to reduce dependency on liquid oxygen deliveries. The U.S. FDA's emergency use authorizations for portable oxygen concentrators have permanently shifted procurement standards toward decentralized supply.
United States
Hospital resilience mandates prioritize on-site generation over bulk liquid tanks. The FDA regulates medical oxygen concentrators under 21 CFR 868.5590, enforcing performance and safety standards that filter out uncertified suppliers. Houston's medical device corridor hosts engineering partnerships extending cryogenic expertise into decentralized healthcare settings.
India
Post-pandemic hospital infrastructure investments are accelerating domestic manufacturing capacity. The PLI scheme covers capital expenditure and component sourcing localization, with CDSCO medical device registration requirements tightening concurrently. Tier-2 and tier-3 cities in Maharashtra and Gujarat are establishing captive testing facilities to accelerate certification timelines.
Germany
Industrial gas demand from steel and chemical processing anchors cryogenic installation revenue. REACH compliance and CE marking requirements create divergent competitive barriers for medical versus industrial equipment. The Ruhr industrial cluster maintains merchant gas channels while extending into on-site generation through engineering partnerships.
Brazil
São Paulo's private hospital networks drive replacement of bulk liquid tanks with on-site PSA generation. ANVISA medical device registration governs concentrator imports and domestic assembly. Procurement teams are separating capital acquisition from aftermarket service, awarding multi-year performance contracts to independent technical specialists.
China
Zeolite molecular sieve production concentrates input supply for PSA adsorbent systems. GB standards and NMPA medical device regulations govern domestic certification and export quality. The Yangtze River Delta hosts component sourcing clusters serving non-Chinese oxygen generator assemblers facing supply security risks.
Oxygen Generator Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The vendor base splits between industrial gas majors with cryogenic expertise and compact system specialists serving decentralized healthcare. Three archetypes dominate: scale-driven merchant gas providers, technology-anchored engineering firms, and modular equipment fabricators. Consolidation proceeds through strategic partnerships rather than outright acquisition, while geographic expansion targets emerging economy hospital infrastructure.
Among European-based specialists, INMATEC GaseTechnologie GmbH & Co. KG and OXYMAT occupy positions within the compact PSA tier, exemplifying engineering-focused architectures for decentralized deployment. Air Products and Chemicals, Inc. represents the scale-driven archetype, anchoring high-purity industrial contracts through cryogenic distillation expertise. These three entities illustrate the competitive spectrum from modular healthcare systems to capital-intensive industrial installations.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Air Liquide |
| SIAD Macchine Impianti S.p.A. |
| INMATEC GaseTechnologie GmbH & Co. KG |
| Air Products and Chemicals, Inc. |
| OXYMAT |
| CAIRE Inc. |
| Linde plc |
| Others |
Supply Flow & Price Mechanics
Zeolite molecular sieve substitution for imported synthetic adsorbents is simultaneously redrawing supply geography toward Chinese production clusters and compressing pricing power for PSA system assemblers outside Asia. This input shift forces non-Chinese manufacturers to absorb freight premiums or surrender margin to domestic competitors with captive sieve supply.
Pricing Analysis
Certification level creates the primary spread between ISO 13485/FDA-grade medical concentrators and uncertified industrial units. Three-tier pricing structure across premium, standard, and economy levels bundles after-sales service with capital equipment in hospital contracts, while spot purchases for emergency response favor stripped-down configurations. Pricing pressure stems from India's PLI scheme subsidizing domestic assembly and compressing import parity. Municipal wastewater operators exhibit highest price sensitivity due to budget cycles, whereas integrated steel mills prioritize purity guarantees over unit economics.
Supply Chain Analysis
Inventory lead times for zeolite molecular sieves stretch 12-16 weeks due to concentrated production in China's Yangtze River Delta and Shandong province. PSA compressor modules draw from German and Japanese precision manufacturing, while membrane fibers source from US and South Korean polymer specialists. Single-source vulnerability concentrates in adsorbent supply, with tariff exposure rising on US-China medical device trade lanes. Distribution runs through regional gas equipment distributors with hospital GPO contracts and direct industrial sales teams for cryogenic installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oxygen generator market is recovering from pandemic-era demand spikes through normalized hospital capital cycles and sustained infrastructure investment in emerging economies.
For Market Incumbents: Fortify certification moats by accelerating ISO 13485 audits for Indian PLI scheme eligibility before CDSCO registration windows tighten. Deepen backward integration into zeolite sieve testing capabilities to offset Chinese supply concentration risk. Lock multi-year service contracts with São Paulo private hospital networks before third-party maintenance specialists capture aftermarket revenue.
For New Entrants and Emerging Players: Aftermarket service unbundling in Brazilian procurement creates white-space for independent PSA maintenance specialists without manufacturing scale. Target India's tier-2 and tier-3 cities where PLI-subsidized domestic assembly outcompetes import-dependent rivals. Lead with portable emergency response configurations where FDA emergency use authorization precedent lowers regulatory barriers versus hospital central supply systems.
For Investors and Strategic Acquirers: Capital is best deployed toward compact PSA engineering specialists with CE marking and modular architectures for Southeast Asian hospital decentralization. Long-term viability hinges on recurring revenue service models rather than equipment transaction cycles. Watch India's CDSCO enforcement intensity as the inflection signal for domestic manufacturing consolidation versus import competition.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | CDSCO registration requirements in India filter uncertified competitors from hospital procurement channels. |
| Zeolite Sieve Backward Integration | Captive adsorbent testing reduces supply security risk from Chinese production concentration. |
| Modular VPSA Architecture Development | Mid-sized Southeast Asian hospitals adopt vacuum systems for throughput previously requiring cryogenic investment. |
| Aftermarket Service Unbundling | São Paulo procurement teams now separate capital acquisition from multi-year performance contracts. |
| Smart Concentrator Cybersecurity Compliance | FDA guidance for connected medical devices enables differentiated architectures and recurring revenue models. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital procurement managers, GPO contracts specialists, and aftermarket service technicians, then refined against secondary validation from FDA 510(k) filings, CDSCO medical device registration databases, EPA wastewater treatment compliance records, and industrial gas trade association reports. Bottom-up unit shipment estimates triangulated with top-down market value reconstruction across the analysis window.
Variance decomposition across technology type, end-user segment, application purity requirement, and installation mobility shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare infrastructure investment indicators. Forecast inputs incorporated PLI scheme subsidy trajectories, hospital resilience mandate adoption curves, and energy cost differentials between PSA and VPSA operating economics.
Forecasts assume regulatory continuity in FDA 21 CFR 868.5590 enforcement, CDSCO medical device registration timelines, and EPA dissolved oxygen mandates; material policy shifts would require re-modeling. Zeolite supply disruption, hospital capital cycle compression, or cybersecurity rule acceleration represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Germany Respiratory Devices Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Fracture Fixation Products Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
General Surgical Devices Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Intervertebral Implants Market