
 US Mobile Physician Practice Market | 2026-2036
US Mobile Physician Practice Market Size, Share, and Industry Trends Forecast 2026-2036
US Mobile Physician Practice Market Insights
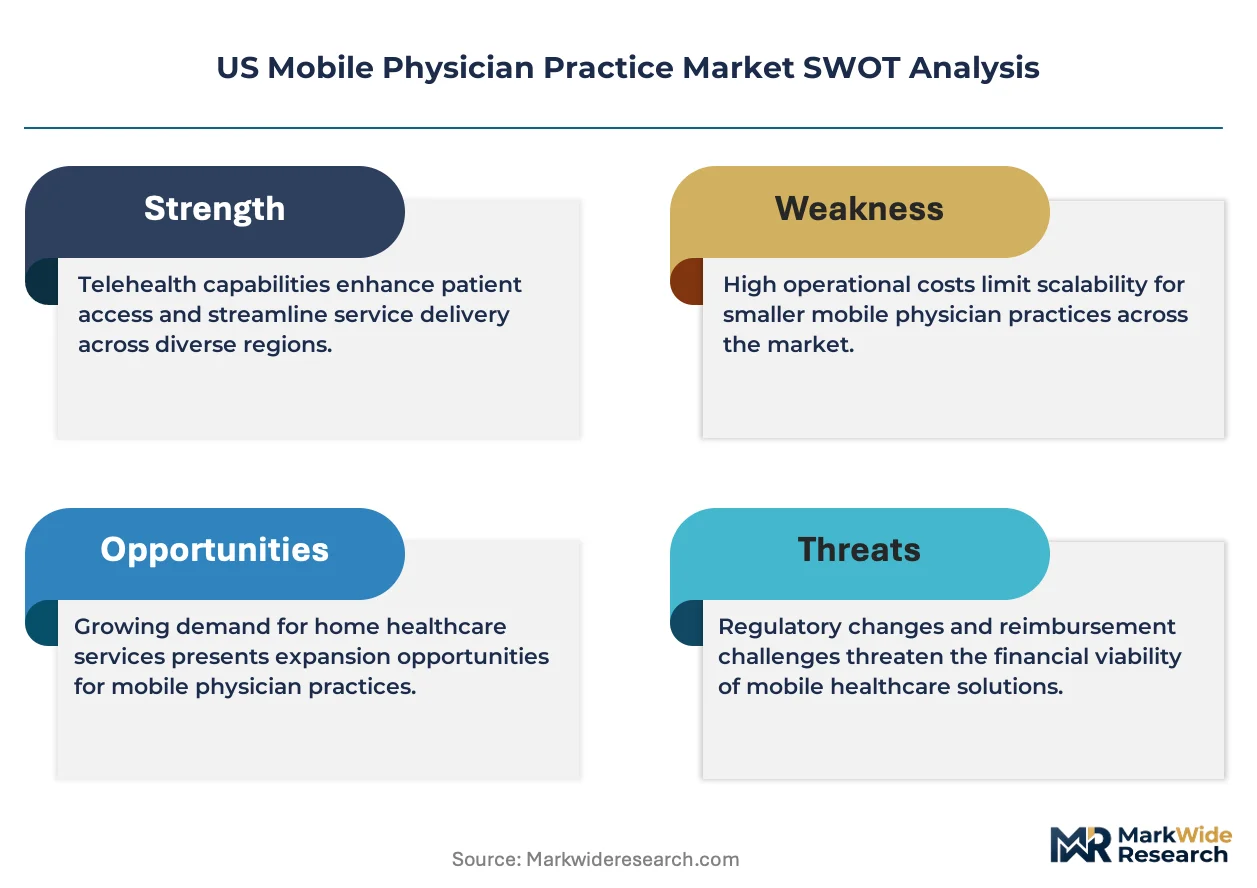
Telemedicine integration with point-of-care diagnostics is fragmenting traditional service delivery into modular, location-agnostic encounters. TeamHealth sustains geographic density through its hospital-based staffing networks while extending into mobile deployment. Doctor On Demand by Included Health, Inc. competes on virtual-first triage that anchors downstream in-person visits. Mobile Physician Services, Inc. specializes in house-call infrastructure that controls last-mile logistics in suburban markets.
A mobile physician practice delivers clinical care through transportable or remotely operated medical services, combining portable diagnostic equipment, cloud-connected electronic health records, and synchronous audiovisual links to replicate office-based encounters at patient locations. Primary Care and Specialist Consultation segments lead service volume, while Preventive Care captures expanding margin pools as Medicare Advantage plans emphasize risk-adjusted outcomes. Wearable Devices and Remote Monitoring technologies concentrate fastest growth by enabling continuous physiologic surveillance that reduces emergency utilization.
FDA governs portable diagnostic device clearances, while CMS reimbursement rules determine whether mobile encounters achieve payment parity with clinic-based services. HIPAA mandates data security protocols for patient information transmitted across cellular and Wi-Fi networks during mobile encounters. State medical boards regulate interstate licensure compacts that constrain multi-state mobile practice expansion. Stakeholders must monitor whether CMS extends pandemic-era telehealth waivers permanently or reverts to geographic and originating-site restrictions that would contract addressable demand.
Market Dynamics
CMS reimbursement parity for telehealth encounters is collapsing the geographic constraints that historically tethered physician practices to fixed clinic locations, redistributing clinical capacity toward patient homes and rural communities.
Growth Catalysts
- Medicare Advantage Risk Adjustment:Capitated payment models reward mobile practices for capturing chronic conditions through intensive diagnostic documentation in patient residences.
- Interstate Medical Licensure Compact:Streamlined credentialing enables multi-state mobile deployment without redundant board certifications.
- Wearable-Generated Physiologic Data:Continuous glucose monitors and blood pressure cuffs feed real-time alerts that trigger proactive house-call interventions.
Market Restraints
- Originating-Site Restrictions:CMS statutory language limits telehealth reimbursement to rural Health Professional Shortage Areas unless Congress extends waivers.
- Portable Device Capital Intensity:Point-of-care ultrasound and laboratory analyzers require six-figure equipment investments per mobile unit.
- Cellular Network Dead Zones:Synchronous video encounters fail in rural Texas and Arizona corridors lacking 5G or reliable LTE coverage.
Strategic Opportunities
- Home-Based Acute Care Programs:Hospital-at-home waivers allow mobile physicians to substitute inpatient admissions for pneumonia, heart failure, and cellulitis.
- Remote Patient Monitoring Integration:Cloud-connected pulse oximeters and weight scales enable daily surveillance that prevents emergency department utilization.
- Behavioral Health House Calls:Psychiatric medication management and substance use counseling delivered in patient residences address transportation barriers.
Industry Challenges
- EMR Interoperability Friction:Mobile encounters must reconcile data across fragmented hospital, payer, and ambulatory systems without standardized APIs.
- Malpractice Jurisdiction Complexity:Cross-state mobile practice triggers conflicting state tort laws and coverage gaps.
- Physician Burnout in Solo Deployment:Isolated practitioners lack peer support structures available in hospital-based practice models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Mobile Physician Practice Market |
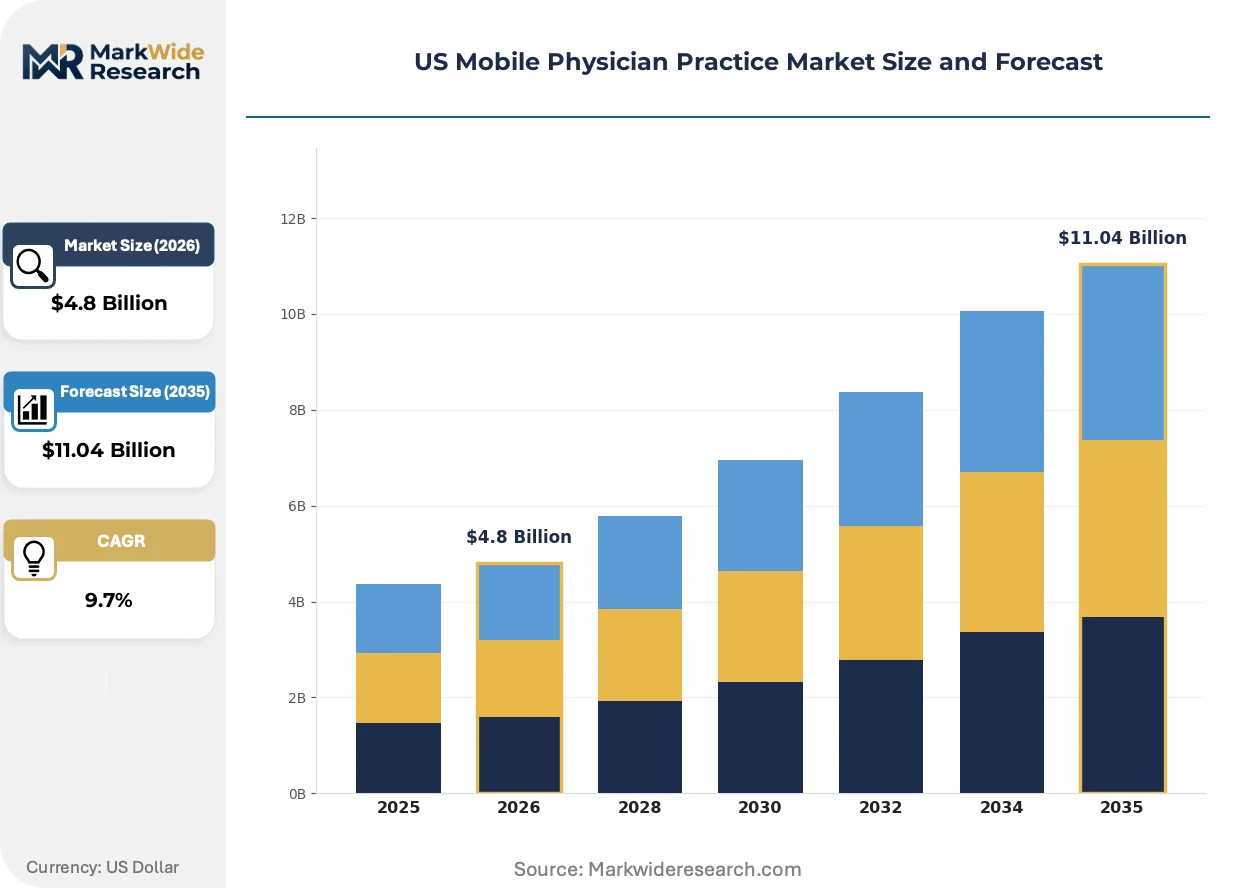
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Primary Care, Specialist Consultation, Preventive Care, Palliative Care Technology: Telemedicine, Mobile Health Apps, Wearable Devices, Remote Monitoring End User: Elderly Patients, Chronically Ill Patients, Rural Residents, Tech-Savvy Millennials Delivery Model: On-Demand Services, Scheduled Visits, Subscription-Based Care, Hybrid Services |
| Companies Covered | Mobile Physician Services, Inc., Florida Mobile Physicians, LLC, TeamHealth, Doctor On Demand by Included Health, Inc., SOS Doctor Housecall, PatientPop, Inc., PriveMD, Hill Physicians, Resurgia Health Solution LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Mobile Physician Practice Market Trends and Innovations
Clinical workflow digitization is compressing the physical infrastructure requirements for physician-patient encounters, enabling diagnostic-grade medicine outside traditional facilities.
Portable ultrasound and handheld laboratory analyzers are collapsing the equipment footprint needed for comprehensive primary care. Medicare Advantage plans in Florida and Arizona deploy these devices to complete annual wellness visits in subscriber kitchens and living rooms. The technology is collapsing the distinction between office-based and home-based diagnostic capability.
CMS telehealth waivers enacted under the Public Health Emergency are reshaping statutory reimbursement frameworks. The agency's proposed 2025 Physician Fee Schedule would make certain remote services permanently payable at parity rates. Rural health systems in Texas are restructuring staffing models to capitalize on this regulatory tailwind.
Patients with complex chronic conditions are demanding longitudinal relationships with mobile providers rather than episodic urgent care. Subscription-based membership models in suburban Phoenix and Dallas-Fort Worth replace fee-for-service billing with predictable monthly payments. This behavioral shift concentrates demand among Medicare beneficiaries who prioritize continuity over convenience.
US Mobile Physician Practice Market Segmentation
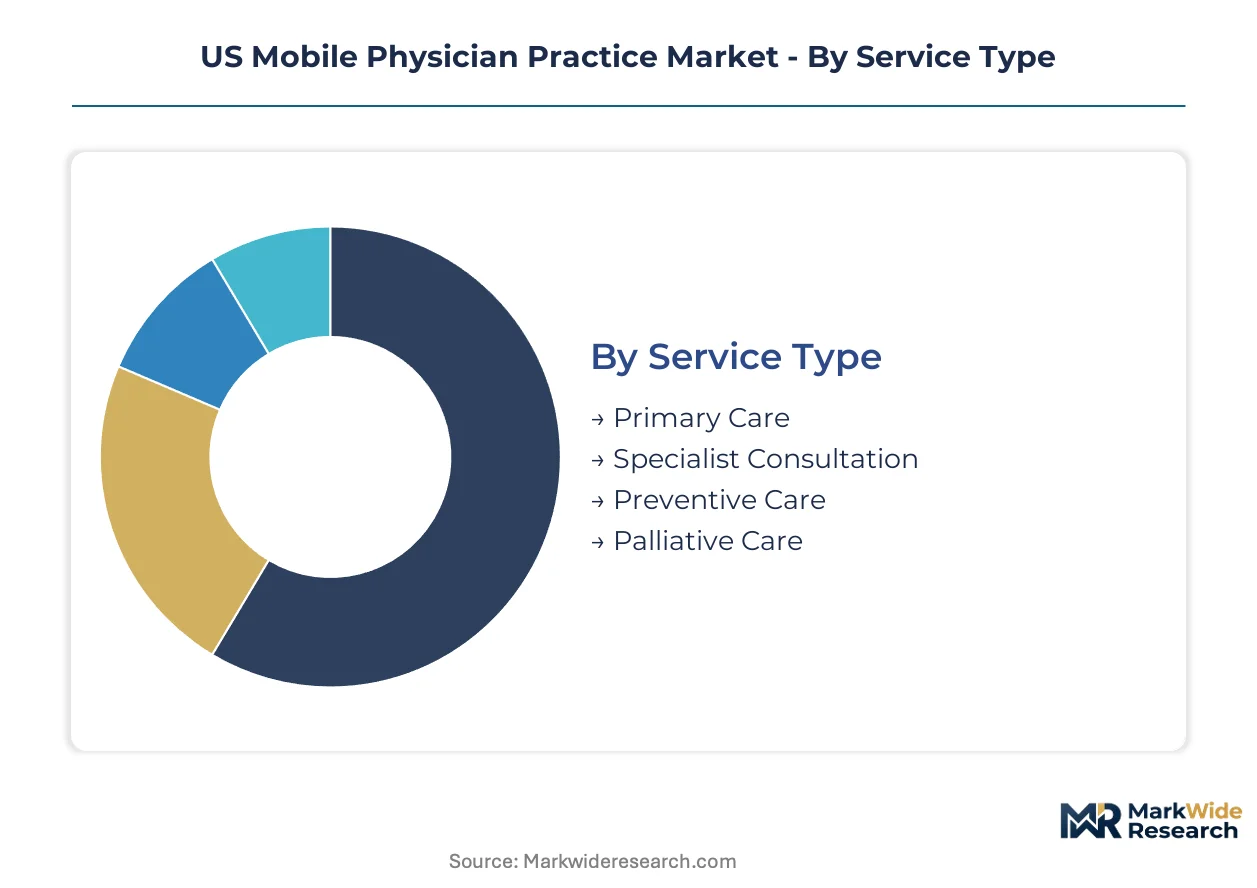
Segmentation reveals how mobile physician practices configure service architectures around patient acuity, technology integration, and payment mechanics. Each dimension exposes distinct margin structures and operational constraints that determine competitive viability across Texas, Florida, and Arizona markets.
Service Type:
Clinical intensity spans episodic intervention to longitudinal disease management, with reimbursement rates scaling according to diagnostic complexity and care continuity requirements.
- Primary Care:Comprehensive diagnostic and therapeutic services delivered at patient residences using portable examination equipment and point-of-care laboratory systems. Medicare Advantage plans in suburban Dallas-Fort Worth and Phoenix prioritize these encounters for risk-adjusted revenue capture.
- Specialist Consultation:Cardiology, pulmonology, and geriatric medicine consultations conducted via synchronous video with remote physical examination assistance. Demand concentrates among rural Texas counties where specialist physician density falls below national benchmarks.
- Preventive Care:Annual wellness visits and health screenings emphasizing early detection protocols.
- Palliative Care:Symptom management and advance care planning for advanced illness populations.
The dominant share belongs to Primary Care, while Specialist Consultation is closing the gap fastest.
Technology:
Technology infrastructure determines encounter fidelity and the scope of clinical services executable outside fixed facilities.
- Telemedicine:Real-time audiovisual consultation platforms integrated with electronic health record systems. CMS reimbursement parity in Arizona and Florida drives deployment across Medicare Advantage networks seeking to substitute virtual for in-person encounters.
- Remote Monitoring:Cloud-connected physiologic sensors transmitting continuous data streams to clinical dashboards. Rural health systems in Texas deploy these tools to reduce emergency department utilization among heart failure and diabetes populations.
- Wearable Devices:Consumer and medical-grade biosensors enabling patient-generated health data.
- Mobile Health Apps:Patient-facing software for scheduling, medication adherence, and symptom tracking.
Telemedicine commands installed base leadership, though Remote Monitoring exhibits the steepest expansion trajectory as capitated contracts reward utilization prevention.
End User:
Patient demographics dictate service design priorities from technology literacy to transportation barriers and disease burden concentration.
- Elderly Patients:Medicare beneficiaries requiring medication reconciliation, fall risk assessment, and cognitive screening in residential settings. Florida's aging population density generates concentrated demand for house-call infrastructure in Miami-Dade and Palm Beach counties.
- Chronically Ill Patients:Individuals with diabetes, congestive heart failure, and chronic obstructive pulmonary disease needing intensive monitoring. Arizona's Medicaid managed care programs fund mobile encounters to reduce hospital admission rates among this cohort.
- Rural Residents:Populations in Health Professional Shortage Areas facing geographic access constraints.
- Tech-Savvy Millennials:Younger adults preferring app-based scheduling and virtual-first triage pathways.
Elderly Patients generate the majority of encounter volume, yet Chronically Ill Patients are gaining share fastest as value-based contracts expand.
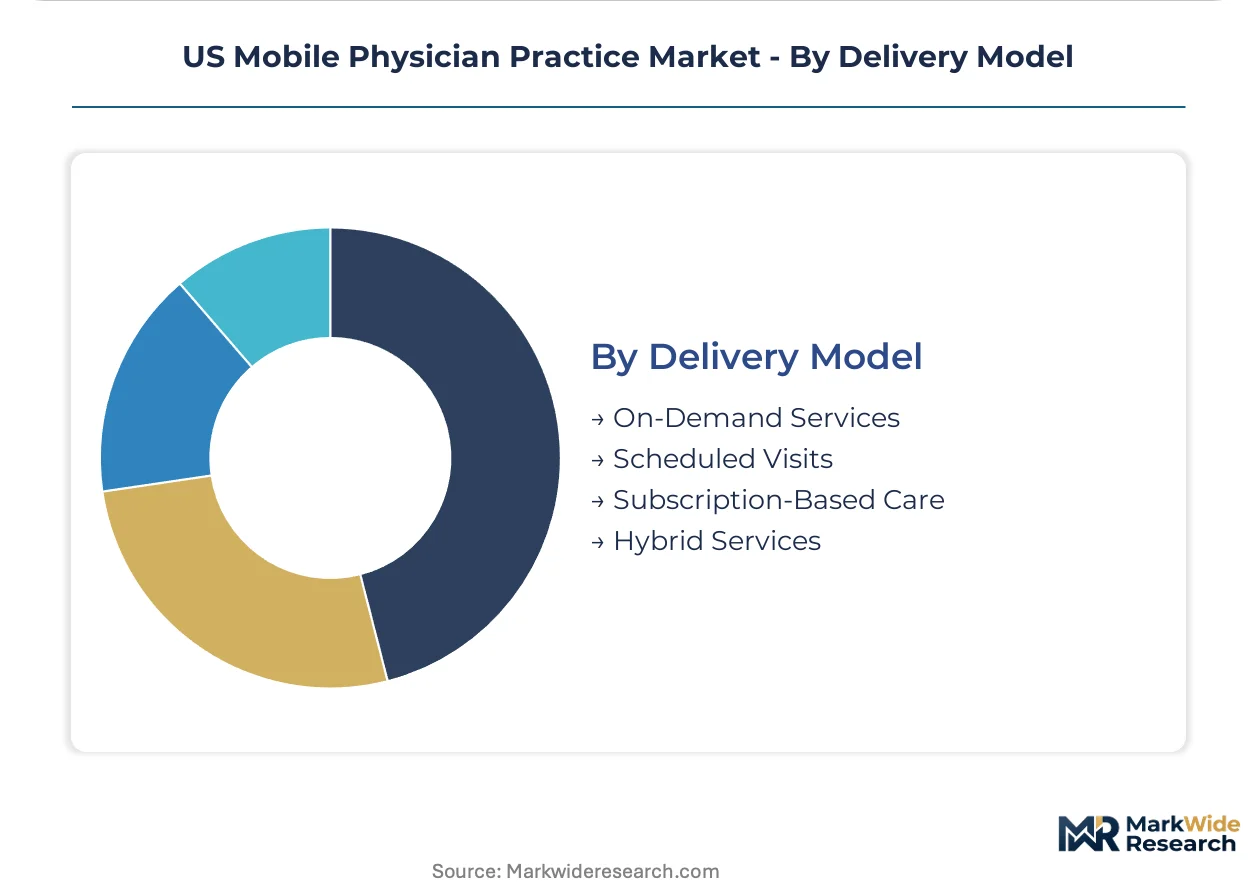
Delivery Model:
Payment architecture shapes patient relationship duration, revenue predictability, and operational scheduling intensity.
- Subscription-Based Care:Monthly membership fees covering unlimited virtual and scheduled in-person encounters. Direct primary care practices in Texas Hill Country and suburban Phoenix adopt this model to escape fee-for-service administrative burden.
- On-Demand Services:Per-encounter pricing for urgent, unscheduled clinical needs. Austin and Dallas markets show concentration among employed populations lacking established primary care relationships.
- Scheduled Visits:Appointment-based care delivery with predictable resource allocation.
- Hybrid Services:Combinations of virtual, in-person, and asynchronous care modalities.
Subscription-Based Care leads revenue stability metrics, while On-Demand Services are climbing the fastest as gig-economy expectations permeate healthcare consumption patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas health systems export mobile physician capacity to neighboring states lacking rural infrastructure, while Arizona and Florida absorb inbound service models from California telehealth operators seeking Medicare Advantage density.
Texas
Rural Health Professional Shortage Areas in the Panhandle and West Texas drive mobile deployment for primary care access. CMS telehealth waivers enacted during the Public Health Emergency allow reimbursement parity for synchronous video encounters originating in patient residences. Dallas-Fort Worth and Houston medical centers anchor hospital-at-home programs that substitute mobile physician visits for inpatient admissions.
Florida
Medicare Advantage penetration rates in Miami-Dade and Palm Beach counties concentrate demand for risk-adjusted annual wellness visits delivered in subscriber homes. State Medicaid managed care contracts mandate mobile behavioral health coverage for substance use disorders. Tampa Bay health systems deploy portable diagnostic equipment to complete HEDIS measure capture in residential settings.
Arizona
Phoenix metropolitan expansion into suburban Maricopa County creates geographic access gaps that mobile practices fill with subscription-based membership models. Arizona Health Care Cost Containment System waivers fund remote patient monitoring integration for dual-eligible populations. Flagstaff and Prescott markets demonstrate rapid adoption of wearable-generated physiologic data triggering proactive house-call interventions.
California
Silicon Valley technology firms license telehealth platforms to Texas and Florida operators seeking virtual-first triage capabilities. Department of Managed Health Care regulations enforce network adequacy standards that mobile physician practices satisfy in rural Northern California counties. Los Angeles County safety-net systems pilot home-based acute care programs for congestive heart failure under Medicaid 1115 waiver authority.
Georgia
Atlanta metropolitan sprawl into exurban counties generates demand for scheduled mobile primary care among employed populations lacking established clinic relationships. State medical board participation in the Interstate Medical Licensure Compact enables multi-state deployment from Georgia-based physician groups. Augusta and Savannah health systems integrate mobile encounters into accountable care organization contracts with Medicare Advantage plans.
US Mobile Physician Practice Market Competitive Landscape
Channel-controlling players compete with product-specialist players for patient relationship ownership and reimbursement flow capture. The market structures around three tiers: hospital-affiliated staffing networks with embedded mobile capacity, venture-backed virtual-first platforms, and regional house-call specialists with last-mile logistics control. Consolidation pressure intensifies as Medicare Advantage plans demand geographic coverage density that fragments solo practitioners cannot satisfy. Dominant competitive moves include strategic partnerships with payers for exclusive network status and technology licensing agreements that accelerate EMR interoperability.
Within the hospital-affiliated tier, TeamHealth exemplifies scale-driven deployment through its emergency medicine staffing infrastructure extended into mobile service lines. Among regional specialists, Mobile Physician Services, Inc. and Florida Mobile Physicians, LLC occupy positions anchored in suburban market logistics control and state-specific regulatory navigation. Doctor On Demand by Included Health, Inc. represents the virtual-first archetype competing on triage efficiency that funnels patients toward appropriate care modalities.
| Leading Market Players |
|---|
| Mobile Physician Services, Inc. |
| Florida Mobile Physicians, LLC |
| TeamHealth |
| Doctor On Demand by Included Health, Inc. |
| SOS Doctor Housecall |
| PatientPop, Inc. |
| PriveMD |
| Hill Physicians |
| Resurgia Health Solution LLC |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in rural Texas Panhandle mobile physician deployment creates bidding wars among Medicare Advantage plans, compressing per-encounter margins while forcing suppliers to prioritize high-utilization suburban corridors over frontier markets.
Pricing Analysis
Next-generation portable diagnostic suites command premium positioning against legacy equipment-dependent practices. Subscription-based membership models dominate revenue architecture, with price differentiation resting on CMS reimbursement tier and geographic coverage density. Pricing pressure stems from Medicare Advantage risk-adjustment compression in Florida's saturated Miami-Dade corridor. Rural health systems exhibit highest price sensitivity due to fixed Medicaid reimbursement ceilings.
Supply Chain Analysis
Tariff exposure between the United States and China dominates portable device procurement risk for point-of-care ultrasound and laboratory analyzer components. Manufacturing concentrates in China, South Korea, and domestic FDA-registered facilities. Semiconductor shortages for telemetry modules and lithium-ion battery cells for mobile power systems create single-source vulnerability. Distribution runs through GPO-affiliated medical equipment distributors and direct manufacturer relationships with multi-state practice networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Medicare Advantage plan consolidation, with four national payers now controlling network adequacy standards that determine mobile practice viability across Texas, Florida, and Arizona.
For Market Incumbents: Insulate market position by deepening EMR interoperability investments that satisfy payer data exchange requirements, and acquire suburban house-call logistics specialists before venture-backed platforms capture last-mile density. Threat substitution from virtual-first triage platforms intensifies as Doctor On Demand extends into downstream in-person anchoring. For New Entrants and Emerging Players: Rural Health Professional Shortage Areas in West Texas and Arizona's Navajo Nation represent the most penetrable entry point, with CMS telehealth waiver dependency creating temporary regulatory shelter. Behavioral health house calls in Florida's Medicaid managed care networks offer parallel white-space access. Go-to-market execution should anchor in subscription-based membership models with predictable monthly revenue. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based direct primary care practices with established patient panels exceeding five hundred lives. Long-term viability favors platforms with demonstrated CMS reimbursement parity capture and multi-state licensure compact participation. Monitor Interstate Medical Licensure Compact expansion as inflection signal for scalable addressable market growth.| Strategic Initiative | Industry Significance |
|---|---|
| CMS Reimbursement Strategy | Permanent telehealth parity capture determines Medicare Advantage network inclusion across Texas and Florida markets. |
| Hospital System Partnership | Hospital-at-home waiver participation substitutes inpatient admissions with mobile physician encounters in Dallas-Fort Worth. |
| Software Companion Development | Remote patient monitoring dashboards integrate wearable-generated alerts with proactive house-call dispatch protocols. |
| Geographic Expansion | Interstate Medical Licensure Compact participation enables multi-state deployment without redundant board certifications. |
| Platform Integration | EMR interoperability investments satisfy payer data exchange requirements and reduce administrative friction. |
Research Methodology
Cross-validation between CMS Medicare claims data and state medical board licensure records anchors the qualitative findings on physician supply distribution. Primary interviews with mobile practice operators, Medicare Advantage plan medical directors, and rural health system executives combined with secondary analysis of FDA 510(k) clearances, CMS Physician Fee Schedule rulemaking, and Interstate Medical Licensure Compact participation statistics. Bottom-up encounter volume estimates triangulate against top-down reimbursement flow projections.
Calibration against historical CMS telehealth waiver utilization patterns and Medicare Advantage risk-adjustment revenue reporting informs the analytical framework across the analysis window. Segmentation models incorporate service type, technology infrastructure, end-user demographics, and delivery model payment architecture. CAGRs derive from compound growth trajectory fitting to documented encounter expansion in Texas, Florida, and Arizona markets, with portable device adoption curves and interstate licensure velocity as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement indexing or Medicaid managed care capitation rates would shift the trajectory. Forecasts reflect documented assumptions regarding CMS waiver permanence and Interstate Medical Licensure Compact state participation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Global Thyroid Disorder Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market