
 Global Microkeratome Market | 2026-2036
Global Microkeratome Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microkeratome Market Analysis
Refractive surgery chains are bifurcating from hospital-based procurement toward dedicated ophthalmic clinics as the dominant buyer archetype. Alcon, Inc. leverages its integrated viscoelastic and microkeratome portfolio to anchor premium clinic relationships across North America. Ziemer Ophthalmic Systems AG differentiates through femtosecond-compatible mechanical platforms that sustain Swiss engineering margins in European markets. Johnson & Johnson Vision Care competes on disposable blade economics, occupying the high-volume LASIK segment with single-use safety protocols.
A microkeratome is a precision surgical instrument designed to create a hinged corneal flap of calibrated thickness, typically 110 to 180 micrometers, using an oscillating blade or pneumatic suction ring assembly; its primary purpose is to enable stromal access during laser-assisted in situ keratomileusis and related keratorefractive procedures. Automated systems with programmable cutting depth and vacuum stabilization now dominate installed bases, while disposable blade cartridges command recurring revenue streams that outpace capital equipment margins. Refractive surgery applications lead procedure volumes, though corneal surgery segments are expanding fastest as hybrid mechanical-laser platforms penetrate DALK and DSEK workflows.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation classify microkeratomes as Class II or IIb devices, requiring biocompatibility testing and post-market surveillance that elevates barriers for new entrants. Japan's PMDA enforces JIS-compliant electrical safety and blade sterilization validation, shaping product design for Asia-Pacific registrations. Stakeholders must monitor evolving reimbursement thresholds for femtosecond laser alternatives versus mechanical microkeratome cost efficiency in emerging markets.
Market Dynamics
Femtosecond laser alternatives are compressing mechanical microkeratome pricing power while automated blade systems defend volume in cost-sensitive markets. South Korean refractive surgery chains now specify hybrid mechanical-laser platforms for new clinic openings, forcing incumbent suppliers to recalibrate platform economics.
Growth Catalysts
- LASIK Volume Recovery:Refractive surgery centers in South Korea are expanding capital expenditure programs as procedure volumes rebound post-pandemic, driving replacement cycles for aging mechanical systems.
- FDA 510(k) Streamlining:The updated FDA pathway for ophthalmic surgical devices reduces pre-market notification timelines, accelerating commercialization for next-generation automated platforms.
- Hybrid Platform Development:Convergence of mechanical precision with femtosecond compatibility is opening corneal transplant workflows including DALK and DSEK procedures.
Market Restraints
- Input Cost Volatility:Surgical-grade stainless steel and diamond blade substrates face supply concentration from specialized German and Japanese metallurgical suppliers.
- Substitution Pressure:All-femtosecond LASIK platforms are capturing premium patient segments in Germany and the United States, eroding mechanical system addressable market.
- Regulatory Friction:Japan's PMDA enforces JIS-compliant electrical safety and blade sterilization validation that extends product development cycles for Asia-Pacific market entry.
Strategic Opportunities
- Underpenetrated India:Tier-2 and Tier-3 cities lack dedicated refractive surgery infrastructure, creating first-mover advantage for automated microkeratome distributors.
- Regulatory Tailwind:India's PLI scheme for medical devices offers production-linked incentives that reduce landed cost for domestic manufacturing of ophthalmic surgical equipment.
- Technology Convergence:Integration of real-time pachymetry feedback with mechanical cutting heads enables personalized flap architecture without full femtosecond cost.
Industry Challenges
- Specialized Technician Scarcity:Calibration and maintenance of oscillating blade assemblies require trained biomedical engineers that remain concentrated in metropolitan hospital clusters.
- Legacy System Integration:New automated platforms must interface with existing excimer laser footprints, creating software compatibility burdens for multi-vendor installations.
- Certification Timeline Compression:EU MDR Class IIb reclassification demands expanded clinical evidence packages that strain regulatory affairs capacity at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microkeratome Market |
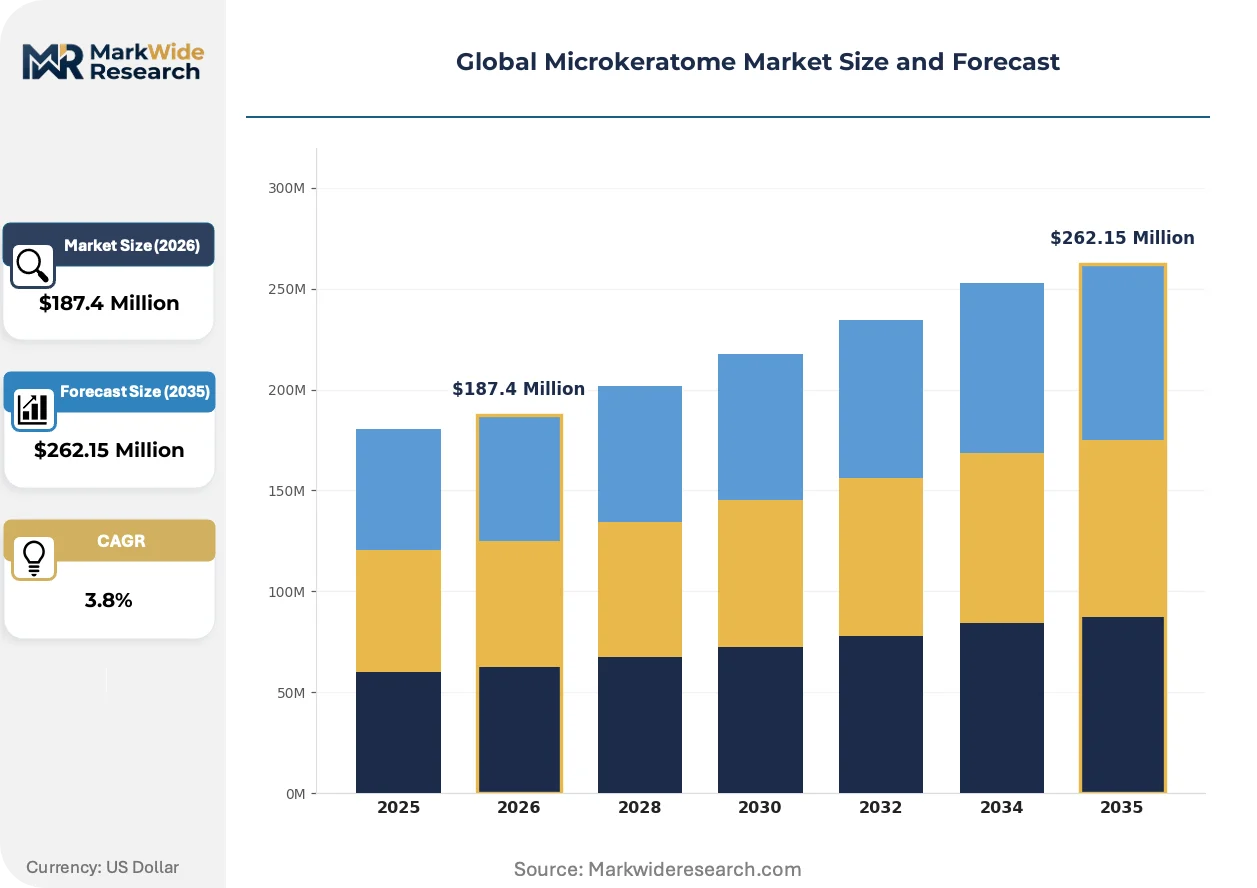
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automated, Disposable, Reusable End User: Hospitals, Ophthalmic Clinics, Research Laboratories, Eye Care Centers Technology: Mechanical, Laser, Pneumatic, Hybrid Application: Cataract Surgery, Refractive Surgery, Corneal Surgery, Others |
| Companies Covered | Bausch & Lomb Incorporated, Alcon, Inc., Johnson & Johnson Vision Care, Carl Zeiss AG, EssilorLuxottica, Moria Surgical, Ziemer Ophthalmic Systems AG, NIDEK CO., LTD, CooperVision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microkeratome Market Emerging Trajectories
Disposable blade cartridges are transforming revenue architecture away from capital equipment cycles toward recurring consumable streams. Three developments are restructuring competitive positioning and buyer relationships across the installed base.
Automated microkeratome systems with programmable cutting depth and vacuum stabilization are supplanting manual mechanical platforms in high-volume LASIK settings. Dedicated ophthalmic clinics in Germany and South Korea specify these systems for standardized flap creation protocols. The shift is compressing margins on legacy equipment while elevating service contract attach rates for precision calibration.
The EU Medical Device Regulation reclassification of microkeratomes as Class IIb devices mandates expanded post-market surveillance and biocompatibility documentation. Manufacturers serving European markets must restructure quality management systems to capture real-world performance data. German and Swiss suppliers with established MDR transition programs are capturing share from competitors with delayed technical file submissions.
Refractive surgery chains are consolidating procurement authority from individual surgeons toward centralized supply chain functions with outcome-based vendor scorecards. North American clinic networks now bundle microkeratome blade contracts with viscoelastic and diagnostic instrument agreements. The concentration of buying power is forcing suppliers to unbundle historically integrated service offerings and compete on total cost-per-procedure metrics.
Global Microkeratome Market Segmentation
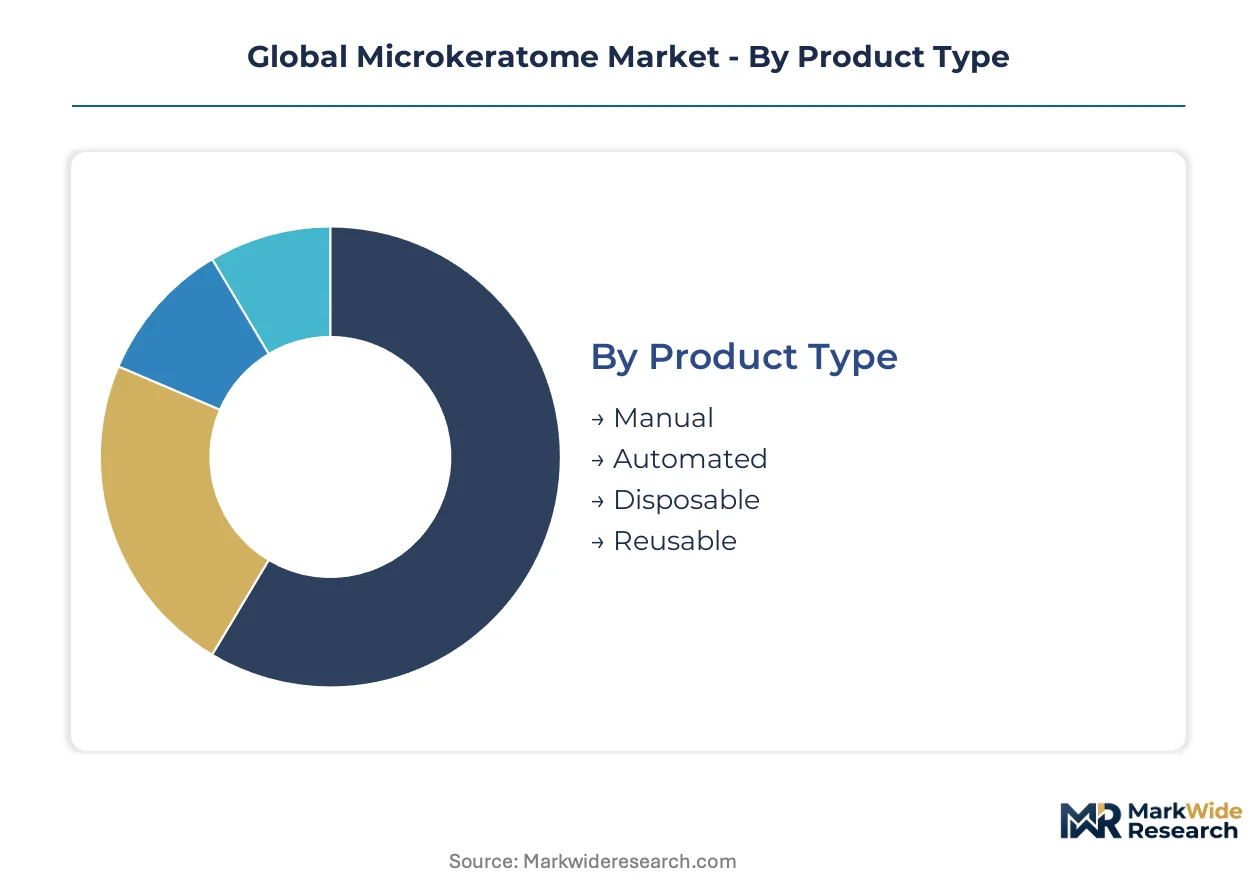
Microkeratome procurement patterns diverge sharply across product architectures and clinical settings. Automated systems with disposable cartridges now dominate high-volume refractive chains, while reusable mechanical platforms persist in cost-constrained hospital environments. Understanding these segment boundaries clarifies where pricing power concentrates versus where volume defense matters.
Product Type:
Domestic manufacturing clusters in Germany and Switzerland supply premium automated systems to European and North American buyers, while manual and reusable platforms flow primarily from Asian contract manufacturers serving price-sensitive developing markets.
- Automated:Programmable cutting depth and vacuum-stabilized suction rings enable standardized flap creation protocols. South Korean refractive surgery chains specify these systems for new clinic openings, with procurement concentrated in Seoul and Busan metropolitan clusters recovering post-pandemic LASIK volumes.
- Disposable:Single-use blade cartridges eliminate sterilization validation burdens and cross-contamination liability. North American ophthalmic clinics favor these for high-throughput settings where blade degradation risks outweigh per-procedure cost premiums.
- Manual:Surgeon-controlled oscillating blade assemblies remain prevalent in Indian tier-2 cities where capital expenditure constraints limit automated system adoption.
- Reusable:Diamond blade substrates with extended sterilization cycles serve European hospital ophthalmology departments prioritizing instrument longevity over consumable economics.
Automated systems command the established base. The steepest expansion runs through disposable cartridges.
End User:
Procurement authority is migrating from individual surgeons toward centralized supply chain functions, with volume concentration varying by facility type and reimbursement structure.
- Ophthalmic Clinics:Dedicated refractive surgery chains in Germany and the United States now bundle microkeratome contracts with viscoelastic and diagnostic instrument agreements. These buyers specify hybrid mechanical-laser platforms and enforce total cost-per-procedure vendor scorecards.
- Hospitals:Integrated health systems in Japan face PMDA-mandated JIS-compliant electrical safety validation that extends procurement cycles. Hospital-based ophthalmology departments favor reusable platforms to amortize capital costs across diverse surgical service lines.
- Eye Care Centers:India's tier-2 and tier-3 cities lack dedicated refractive infrastructure, creating first-mover openings for automated system distributors targeting emerging middle-class patient populations.
- Research Laboratories:Academic medical centers in Switzerland and the United States procure specialized platforms for corneal biomechanics studies and flap architecture validation protocols.
Ophthalmic clinics concentrate the highest procedure volumes. Eye care centers in underpenetrated Indian markets are climbing the fastest.
Technology:
Platform selection increasingly hinges on compatibility with existing excimer laser footprints and regulatory clearance pathways rather than standalone cutting performance.
- Hybrid:Convergence of mechanical precision with femtosecond compatibility opens corneal transplant workflows including DALK and DSEK procedures. German suppliers lead development, with Carl Zeiss AG and specialized clinics driving adoption across Bavaria and Baden-Württemberg.
- Mechanical:Oscillating blade assemblies with programmable depth settings defend volume in cost-sensitive markets where full femtosecond platforms remain economically inaccessible.
- Laser:All-femtosecond systems capture premium patient segments in Germany and the United States, eroding mechanical system addressable market in high-income urban centers.
- Pneumatic:Suction-based stabilization mechanisms integrate with automated cutting heads for standardized flap architecture in high-throughput LASIK settings.
Mechanical platforms retain the largest installed base. Hybrid systems are gaining share fastest as corneal surgery applications expand.
Application:
Procedure volume distribution reflects demographic myopia prevalence, reimbursement thresholds for femtosecond alternatives, and surgeon training pathway specialization.
- Refractive Surgery:LASIK and related keratorefractive procedures consume the majority of microkeratome utilization. South Korean chains are expanding capital expenditure programs as procedure volumes rebound, with replacement cycles accelerating for aging mechanical systems.
- Corneal Surgery:Deep anterior lamellar keratoplasty and Descemet's stripping endothelial keratoplasty workflows are expanding fastest as hybrid platforms penetrate transplant indications previously reserved for manual trephination.
- Cataract Surgery:Limbal relaxing incisions and astigmatic keratotomy applications utilize modified microkeratome platforms in combined phacoemulsification procedures.
- Others:Diagnostic flap creation for corneal cross-linking and research applications represents niche utilization outside standard refractive and transplant workflows.
Refractive surgery anchors current demand. Corneal surgery applications are expanding most quickly as platform capabilities broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Incheon International Airport cargo hub underwrites South Korea's role as the primary distribution node for automated microkeratome systems entering Asia-Pacific refractive surgery markets. Frankfurt Airport's pharmaceutical and medical device free trade zone anchors European supply chain consolidation for precision ophthalmic instruments.
South Korea
Seoul and Busan metropolitan clusters are expanding capital expenditure programs as LASIK procedure volumes rebound post-pandemic. The MFDS enforces stringent electrical safety and sterilization validation standards that shape product specifications for domestic market entry. Refractive surgery chains in Gangnam and Seocho districts specify hybrid mechanical-laser platforms for new clinic openings.
Germany
Carl Zeiss AG and specialized clinics across Bavaria and Baden-Württemberg drive adoption of hybrid systems for corneal transplant workflows. The EU Medical Device Regulation Class IIb reclassification mandates expanded post-market surveillance and biocompatibility documentation. Stuttgart and Munich industrial clusters concentrate precision engineering suppliers serving automated microkeratome manufacturing.
United States
The FDA's updated 510(k) pathway for ophthalmic surgical devices reduces pre-market notification timelines for next-generation platforms. North American clinic networks bundle microkeratome blade contracts with viscoelastic and diagnostic instrument agreements. California and Texas ophthalmic surgery centers concentrate procurement authority for outcome-based vendor scorecards.
India
Tier-2 and Tier-3 cities lack dedicated refractive surgery infrastructure, creating first-mover openings for automated system distributors. The PLI scheme for medical devices offers production-linked incentives that reduce landed cost for domestic manufacturing of ophthalmic surgical equipment. Maharashtra and Karnataka clusters are emerging as assembly locations for cost-optimized mechanical platforms.
Japan
Hospital-based ophthalmology departments favor reusable platforms to amortize capital costs across diverse surgical service lines. The PMDA enforces JIS-compliant electrical safety and blade sterilization validation that extends product development cycles for market entry. Tokyo and Osaka medical device procurement hubs concentrate specialized biomedical engineers for calibration and maintenance services.
Global Microkeratome Market Vendor Landscape
Concentration sits with diversified ophthalmic conglomerates that leverage integrated portfolios to anchor premium clinic relationships. The vendor base spans three tiers: Swiss and German precision engineering specialists, North American disposable economics providers, and diversified vision care conglomerates with broad surgical portfolios. Strategic moves center on hybrid platform development and consumable revenue stream expansion through disposable blade cartridge programs.
Within the diversified ophthalmic conglomerate tier, Alcon, Inc. and Johnson & Johnson Vision Care occupy positions that exemplify scale-driven consumable economics and integrated surgical workflow bundling. Carl Zeiss AG represents the precision engineering archetype originating from German industrial clusters. Ziemer Ophthalmic Systems AG and NIDEK CO., LTD sit within specialized automated platform development, with the former exemplifying Swiss engineering margins and the latter representing Japanese regulatory compliance specialization.
| Leading Market Players |
|---|
| Bausch & Lomb Incorporated |
| Alcon, Inc. |
| Johnson & Johnson Vision Care |
| Carl Zeiss AG |
| EssilorLuxottica |
| Moria Surgical |
| Ziemer Ophthalmic Systems AG |
| NIDEK CO., LTD |
| CooperVision |
| Others |
Supply Flow & Price Mechanics
Diamond blade substrates replacing surgical-grade stainless steel in premium automated systems simultaneously concentrate supply geography around German and Japanese metallurgical specialists and compress pricing economics for mid-tier mechanical platforms. This substitution dynamic reshapes procurement negotiations as refractive surgery chains weigh consumable cartridge costs against capital equipment longevity.
Pricing Analysis
Volume-discount tiering structures dominate procurement between North American ophthalmic clinic networks and disposable blade suppliers, with three-tier pricing stratification across premium femtosecond-compatible, standard automated mechanical, and economy manual platforms. Price differentiation hinges on FDA 510(k) clearance tier and after-sales calibration service bundling. Cost compression in economy manual systems is intensifying because Asian contract manufacturers compete on sterilization cycle longevity. Hospital-based buyers in Japan exhibit highest price sensitivity due to capital amortization requirements across diverse surgical service lines.
Supply Chain Analysis
Just-in-time inventory strategies prevail for disposable blade cartridges serving high-throughput LASIK chains, while strategic stockpiling of diamond substrates and surgical-grade steel persists among German and Swiss precision engineering suppliers. Manufacturing concentration sits in Germany, Switzerland, and South Korea, with raw material dependencies on Japanese metallurgical feedstock and specialized vacuum molding equipment. Single-source vulnerability runs through diamond substrate suppliers in Osaka and Nagoya industrial clusters. Distribution runs through dedicated medical device logistics channels anchored at Frankfurt Airport's pharmaceutical free trade zone and Incheon International Airport's cargo hub.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microkeratome market is cycling through post-pandemic LASIK volume recovery, with South Korean refractive surgery chains driving replacement demand for aging mechanical systems. This cyclical upswing favors incumbents with disposable cartridge revenue streams and hybrid platform development pipelines.
For Market Incumbents: Secure service contract attach rates for precision calibration by embedding biomedical engineers within metropolitan clinic clusters, defending against femtosecond laser substitution through real-time pachymetry integration. Deepen backward integration into diamond substrate supply through captive partnerships with Osaka-based metallurgical suppliers, insulating margin pressure from Japanese feedstock concentration.
For New Entrants and Emerging Players: Differentiate on regulatory pathway speed by targeting India's PLI scheme for domestic manufacturing of cost-optimized automated platforms, penetrating tier-2 and tier-3 cities lacking dedicated refractive infrastructure. White-space concentration sits with eye care centers in Maharashtra and Karnataka clusters, where first-mover distributors can establish outcome-based vendor relationships before incumbent bundling takes hold.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision engineering specialists holding MDR transition programs and established European technical file submissions. Long-term viability over a 5-10 year window depends on consumable revenue stream durability versus femtosecond platform cost curves. Watch for inflection when MFDS enforcement timelines for electrical safety validation compress product development cycles for Asia-Pacific market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Development | Convergence of mechanical precision with femtosecond compatibility opens corneal transplant workflows at Carl Zeiss AG-led German clinics. |
| Disposable Cartridge Expansion | Single-use blade programs transform revenue architecture toward recurring consumable streams outpacing capital equipment margins. |
| MDR Compliance Investment | Expanded post-market surveillance and biocompatibility documentation captures share from competitors with delayed technical file submissions. |
| India PLI Manufacturing | Production-linked incentives reduce landed cost for domestic assembly of ophthalmic surgical equipment in Maharashtra clusters. |
| Real-Time Pachymetry Integration | Feedback-enabled cutting heads enable personalized flap architecture without full femtosecond platform cost premiums. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, EU MDR technical file registries, and hospital procurement contract disclosures preceded structured interviews with refractive surgery chain procurement directors, biomedical engineering specialists, and GPO contracts managers. Primary fieldwork with ophthalmic clinic operators in Seoul, Busan, and Gangnam districts validated capital expenditure cycle timing. Secondary triangulation drew from MFDS enforcement bulletins, PMDA sterilization validation guidelines, and customs records of ophthalmic surgical instrument trade flows. Bottom-up procedure volume estimates and top-down equipment installed base calculations were reconciled across analysis approaches.
Variance decomposition across product type, end user facility, technology platform, and application segments structured the analytical framework over the projection horizon. Modeled dimensions included automated versus manual platform architectures, ophthalmic clinic versus hospital procurement authority, hybrid mechanical-laser versus pure mechanical systems, and refractive surgery versus corneal transplant procedure volumes. CAGRs were derived from segment-level growth rate blending weighted by base-year revenue contribution. Forecast inputs incorporated LASIK volume recovery trajectories in South Korea and PLI scheme uptake rates in Indian manufacturing clusters.
The analysis sits within stated boundaries; outcomes outside sustained LASIK volume recovery or accelerated femtosecond laser cost reduction would require recalibration. Forecasts reflect assumptions regarding MFDS and PMDA enforcement continuity, diamond substrate supply stability, and refractive surgery chain consolidation trajectories. Revision becomes warranted when femtosecond platform pricing crosses thresholds that erode mechanical system addressable market in Germany or United States premium segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Deflectable Catheters Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Global Ventilators Market
Medical Devices
Lactation Massager Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Global Sperm Separation Devices Market
Medical Devices
South Korea Respiratory Devices Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Neurostimulation Devices Market