
 Europe Wearable Medical Devices Market | 2026-2036
Europe Wearable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wearable Medical Devices Market Foresight
Germany is narrowing its lead as the primary hub for wearable medical device validation and reimbursement infrastructure across the continent. Abbott Laboratories leverages its FreeStyle Libre glucose monitoring platform to anchor diabetes management segments. Koninklijke Philips N.V. competes through sleep and respiratory wearable portfolios tied to hospital-at-home programs.
Europe wearable medical devices encompass body-worn instruments that capture physiological data through biosensors, accelerometers, and photoplethysmography modules for continuous health surveillance and clinical decision support. These systems transmit encrypted biometric streams via Bluetooth or NFC to cloud platforms, enabling remote patient monitoring and preventive intervention. Smartwatches dominate volume shipments as consumer-grade heart rate and blood oxygen tracking mature, while wearable patches capture expanding margin pools in ambulatory cardiac and medication adherence applications. Biosensor technology leads R&D allocation as manufacturers pursue non-invasive glucose and lactate measurement breakthroughs.
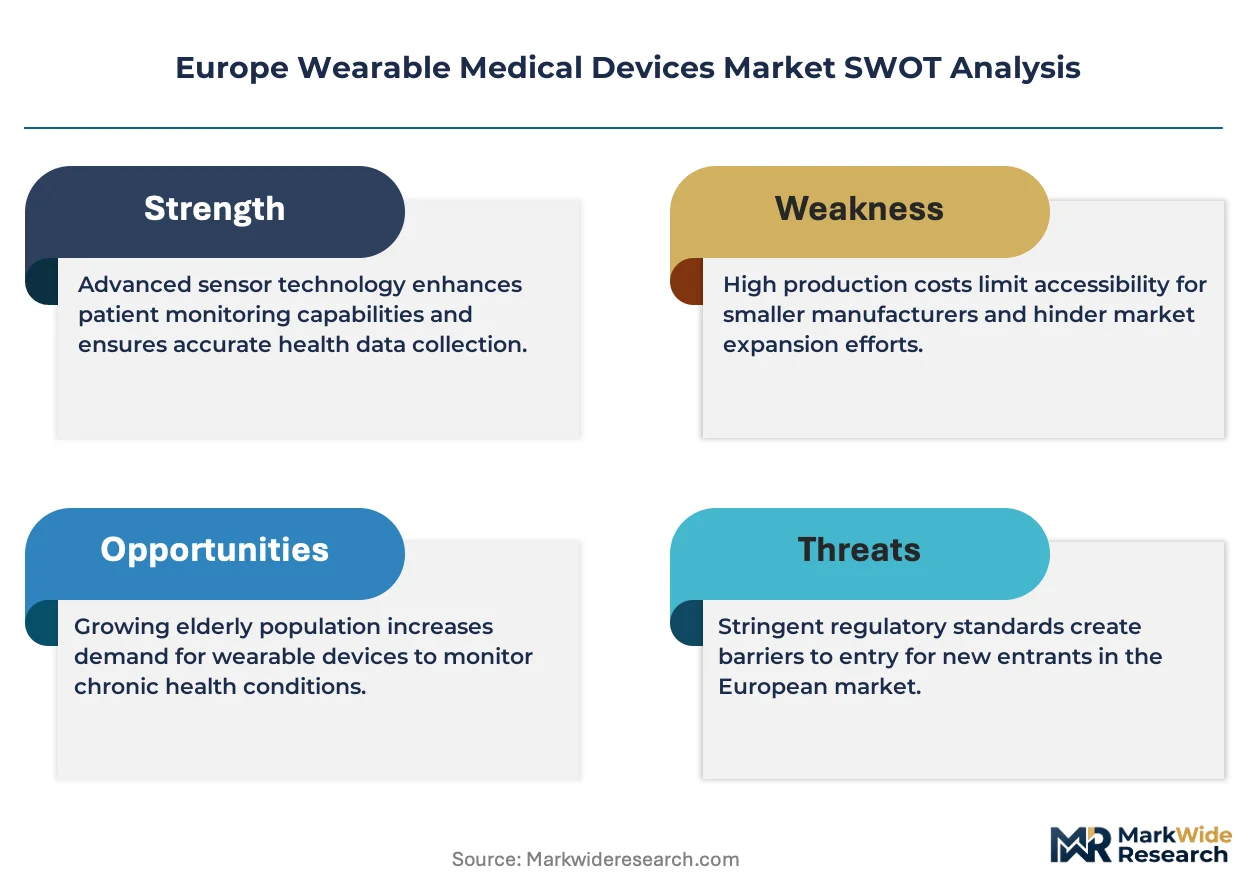
The EU Medical Device Regulation and CE marking framework enforce clinical evidence requirements that filter market entrants and elevate product liability exposure. EMA coordination with national competent authorities in France, Germany, and Italy creates fragmented but tightening conformity assessment pathways. Stakeholders must monitor forthcoming AI Act classifications that will recalibrate software-as-medical-device obligations for algorithm-driven diagnostic wearables.
Market Dynamics
The EU Medical Device Regulation is compressing commercialization timelines as manufacturers absorb heightened clinical evidence burdens and notified body capacity constraints across member states.
Growth Catalysts
- MDR Compliance Infrastructure:Specialized notified bodies in Germany and the Netherlands are expanding capacity to clear Class IIa and IIb wearables, accelerating market access for validated glucose and cardiac monitoring systems.
- Hospital-at-Home Expansion:French and Italian health systems are reimbursing remote patient monitoring through diagnosis-related group carve-outs, pulling continuous pulse oximetry and respiratory wearables into acute care substitution protocols.
- Biosensor Miniaturization:Photoplethysmography modules and flexible printed electronics are enabling multi-parameter patches that capture hydration, lactate, and core temperature through single-skin-contact platforms.
Market Restraints
- Notified Body Bottleneck:EMA-coordinated conformity assessment pathways face 12-18 month backlogs for novel wearable classifications, freezing pipeline commercialization for algorithm-driven diagnostic devices.
- Lithium-Polymer Supply Concentration:Battery cell production for ultra-thin wearables concentrates in East Asian suppliers, exposing European device assemblers to freight cost volatility and customs processing friction.
- Interoperability Fragmentation:Proprietary data protocols from competing platform vendors block seamless electronic health record integration, forcing hospitals to maintain multiple gateway systems.
Strategic Opportunities
- Eastern European Penetration:Poland and Romania exhibit sub-15% wearable adoption in chronic disease management, creating first-mover advantage for localized glucose monitoring and hypertension patch distribution.
- EU AI Act Alignment:Early certification of machine-learning diagnostic algorithms under forthcoming risk-classification frameworks will lock in preferred supplier status for cloud-connected cardiac arrhythmia detection wearables.
- Pharmacy Channel Activation:Boots Alliance and DocMorris are piloting direct-to-consumer wearable dispensing with integrated telehealth consultation, bypassing traditional hospital procurement cycles for preventive health segments.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time biosignal processing expertise for ultra-low-power microcontrollers remains concentrated in Cambridge, Eindhoven, and Munich clusters, constraining R&D scaling.
- Biocompatibility Certification Delays:ISO 10993 skin-sensitization testing for novel adhesive materials extends development cycles by 8-14 months for patch-based medication adherence monitors.
- Legacy EHR Integration Complexity:HL7 FHIR implementation gaps between wearable cloud platforms and hospital information systems force costly middleware development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wearable Medical Devices Market |
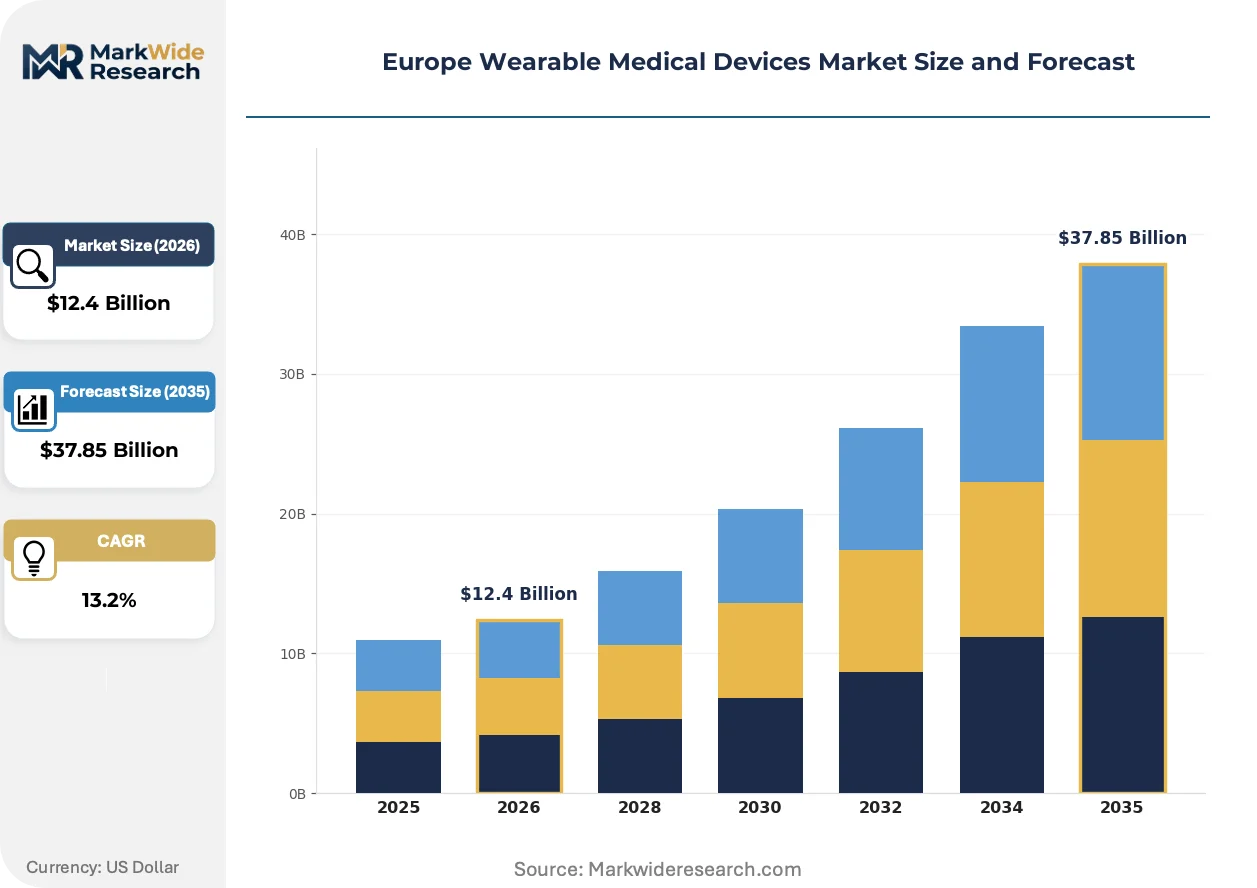
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $37.85 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartwatches, Fitness Trackers, ECG Monitors, Wearable Patch End User: Patients, Healthcare Professionals, Fitness Enthusiasts, Elderly Care Technology: Biosensors, Bluetooth, NFC, Cloud Computing Application: Heart Rate Monitoring, Sleep Tracking, Physical Activity, Medication Adherence |
| Companies Covered | Abbott Laboratories, Medtronic, Koninklijke Philips N.V., Omron Corporation, Samsung Electronics, Apple Inc., Garmin Ltd., Dexcom Inc., Withings, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wearable Medical Devices Market Shifts & Advancements
Non-invasive metabolic sensing and edge-computing diagnostics are redefining the functional boundary between consumer wellness trackers and regulated medical devices across European markets.
Photoplethysmography is hybridizing with impedance spectroscopy to enable cuffless blood pressure estimation and fluid status monitoring through wrist-worn and ring-form factors. Cardiology departments in Barcelona and Stockholm are piloting these hybrid sensors for heart failure patient triage. The convergence is compressing demand for traditional ambulatory blood pressure cuffs while elevating software validation burdens under MDR Class IIa requirements.
The EU AI Act's risk-based classification system for machine-learning medical devices is forcing algorithm documentation and post-market surveillance protocols onto wearable manufacturers before full enforcement. Sleep apnea detection algorithms and atrial fibrillation screening models face elevated conformity assessment scrutiny. French and German competent authorities are issuing early guidance that pushes developers toward notified body pre-submission meetings for AI-enabled diagnostic features.
Hospital procurement committees are unbundling device hardware from data platform subscriptions, reversing prior bundled contracting models that locked institutions into multi-year SaaS commitments. Nordic health systems are leading this disaggregation, sourcing wearable hardware through medical device tenders while negotiating analytics access separately. The shift is pressuring incumbent vendors to modularize pricing and certify standalone device performance independent of cloud service dependencies.
Europe Wearable Medical Devices Market Segmentation
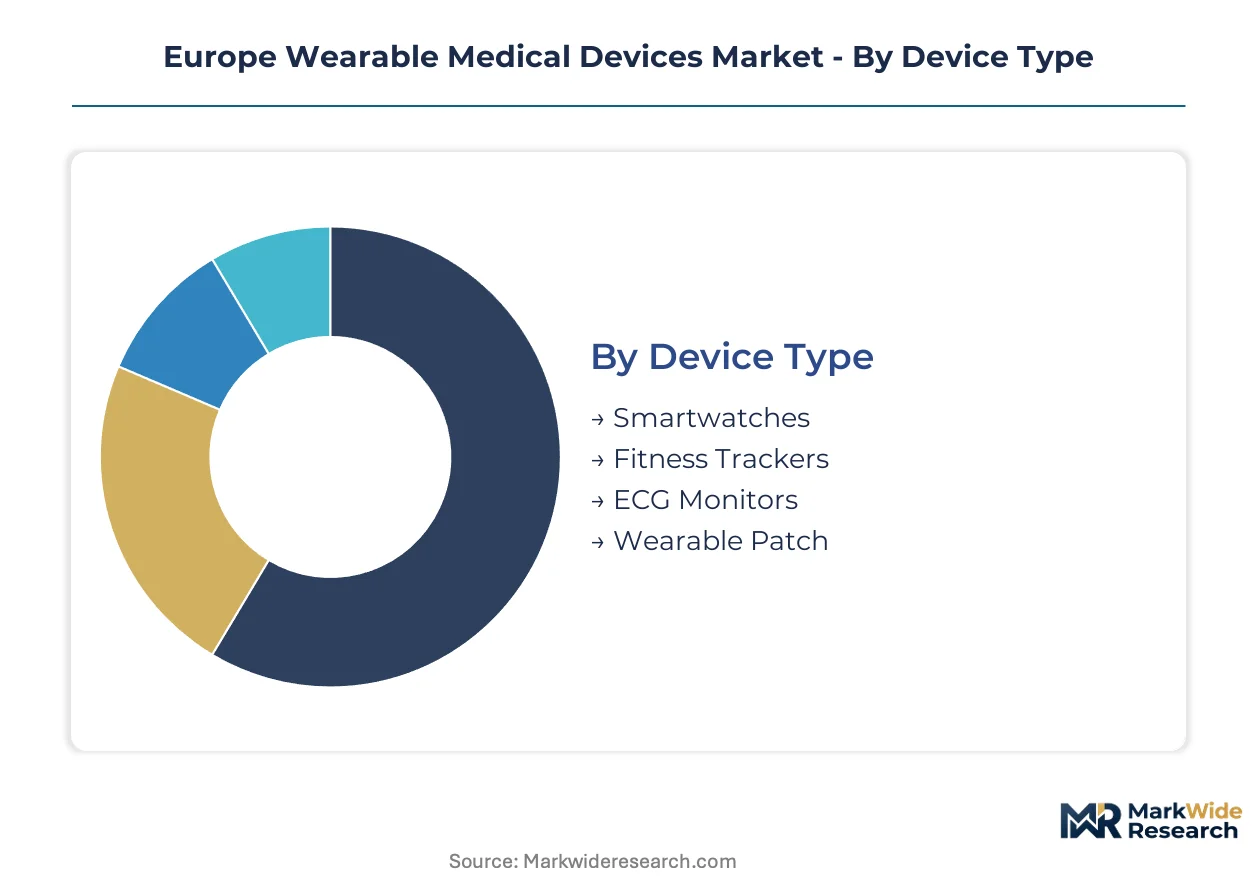
Segmentation in Europe's wearable medical devices market exposes divergent service intensity and regulatory burdens across hardware categories. Device manufacturers calibrate after-sales support networks and firmware update cadences based on whether endpoints serve chronic disease management or preventive wellness tracking.
Device Type:
After-sales service intensity varies dramatically across device architectures, with implant-adjacent patches requiring clinical liaison support while consumer wrist-worn devices rely on automated digital channels.
- Smartwatches:Multi-sensor wrist-worn platforms integrate photoplethysmography, accelerometry, and electrodermal activity through sealed ceramic housings. German and French hospital-at-home programs are standardizing on CE-marked smartwatches for post-discharge cardiac monitoring, pulling devices through procurement frameworks that mandate 24-month software support commitments.
- Wearable Patch:Flexible substrate systems embed biosensor arrays for continuous glucose, lactate, or hydration measurement through single-use adhesive interfaces. Demand concentrates in Dutch and Swedish diabetes management networks where patch-based FreeStyle Libre systems have displaced traditional fingerstick monitoring, though MDR biocompatibility testing for novel adhesives extends replacement cycles.
- ECG Monitors:Chest-worn or handheld single-lead devices capture arrhythmia signatures for remote cardiology consultation.
- Fitness Trackers:Consumer-grade accelerometry devices with basic heart rate estimation for wellness segmentation.
Smartwatches hold the largest share; momentum sits with wearable patches.
End User:
Cost tier stratification separates premium clinical-grade deployments from mass-market consumer channels, with reimbursement eligibility determining hardware specification and data platform integration depth.
- Patients:Chronic disease populations self-managing diabetes, hypertension, or heart failure through prescribed wearable systems. Italian and Spanish regional health services are expanding diagnosis-related group carve-outs to cover continuous monitoring for congestive heart failure patients, accelerating prescription volumes for validated pulse oximetry and weight-tracking wearables.
- Healthcare Professionals:Clinical staff deploying wearables for remote patient monitoring, post-operative surveillance, and emergency department triage. French hospital networks are reimbursing physician-prescribed wearable ECG monitors for atrial fibrillation screening, creating concentrated demand for MDR Class IIa-certified devices with embedded diagnostic algorithms.
- Fitness Enthusiasts:Wellness-focused consumers purchasing consumer-grade devices without clinical supervision or insurance subsidy.
- Elderly Care:Institutional and home-based aged care settings utilizing fall detection and activity monitoring for frailty management.
Patients represent the dominant revenue tier; healthcare professionals are expanding most quickly.
Technology:
Application maturity separates established connectivity protocols from emerging biosensor modalities still navigating MDR clinical evidence requirements.
- Biosensors:Electrochemical and optical transducers converting physiological signals into digital outputs through enzymatic or affinity-based recognition elements. German research clusters in Munich and Heidelberg are driving non-invasive glucose sensing breakthroughs, though EMA-coordinated notified body reviews for novel biosensor classifications currently face 14-month assessment backlogs.
- Bluetooth:Short-range wireless protocol enabling encrypted biometric transmission to paired smartphones and gateway hubs. Nordic health systems are mandating Bluetooth 5.2 with LE Audio for hearing aid integration, pushing wearable manufacturers toward dual-mode connectivity stacks.
- NFC:Near-field communication for tap-to-pair device initialization and pharmacy-based wearable dispensing.
- Cloud Computing:Distributed data infrastructure for algorithmic analysis and longitudinal health record integration.
Biosensors command premium positioning; Bluetooth maintains volume leadership.
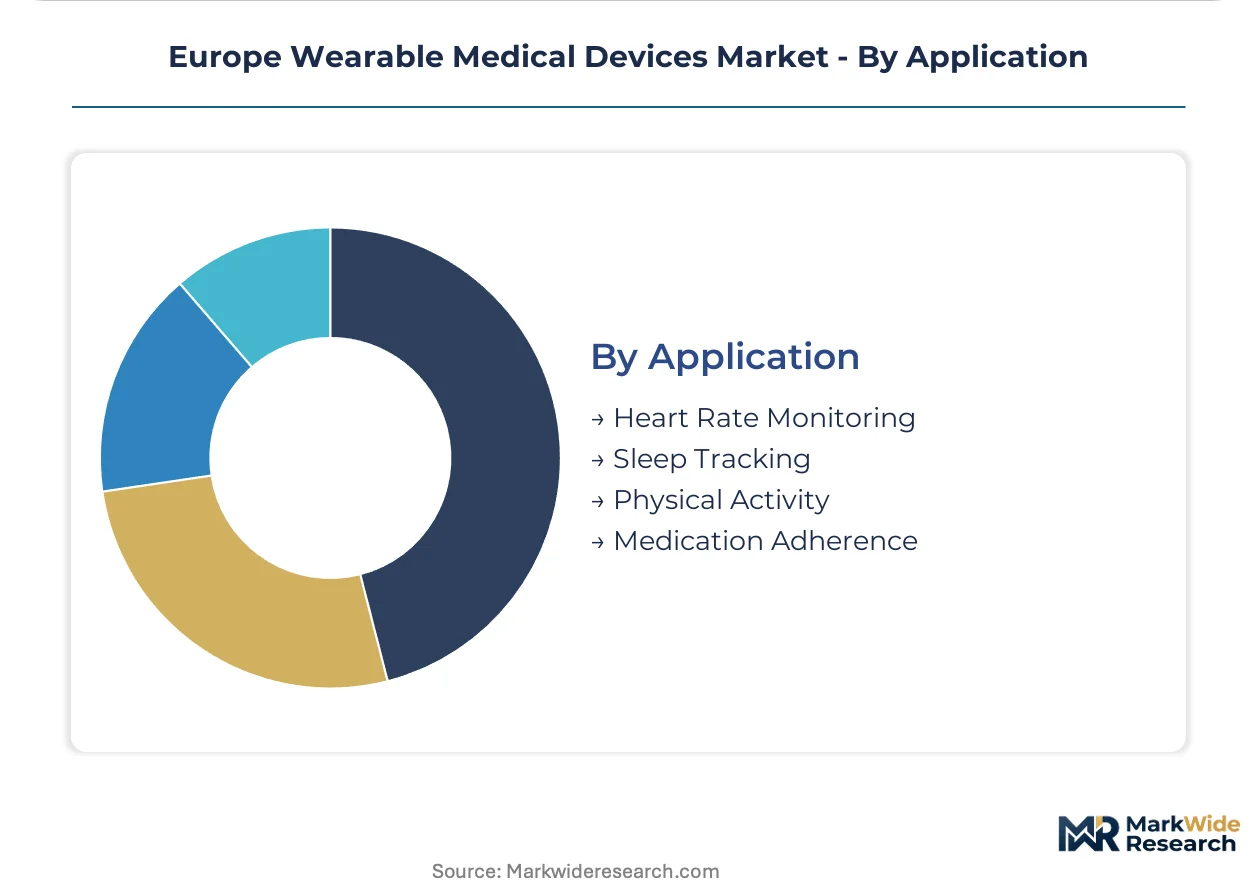
Application:
Customer type fragmentation separates acute care substitution protocols from chronic disease prevention, with reimbursement codes determining deployment scale and device sophistication.
- Heart Rate Monitoring:Continuous photoplethysmography-based pulse detection for arrhythmia screening and exercise intensity guidance. Cardiology departments in Barcelona and Stockholm are piloting hybrid PPG-impedance sensors for cuffless blood pressure estimation, compressing demand for traditional ambulatory monitoring while elevating software validation burdens under MDR Class IIa requirements.
- Sleep Tracking:Multi-parameter nocturnal surveillance combining accelerometry, blood oxygen saturation, and respiratory rate for apnea detection. The EU AI Act's risk-based classification system is forcing algorithm documentation onto sleep apnea detection models before full enforcement, with French competent authorities issuing early guidance that pushes developers toward notified body pre-submission meetings.
- Physical Activity:Step counting, calorie estimation, and movement pattern recognition for metabolic health management.
- Medication Adherence:Patch-based or ingestible sensor systems confirming pharmaceutical consumption through biochemical detection.
Heart rate monitoring dominates installed base; sleep tracking gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA coordination with German notified bodies anchors the continent's conformity assessment capacity, though fragmentation across national competent authorities creates uneven market access timelines for wearable manufacturers seeking CE marking.
Germany
Statutory health insurance funds reimburse prescribed glucose monitors and cardiac wearables through diagnosis-related group extensions, pulling devices through hospital procurement frameworks. The EU MDR designates TÜV SÜD and BSI Group Germany as priority notified bodies for Class IIb wearables, compressing assessment timelines for validated biosensor submissions. Munich and Heidelberg research clusters drive non-invasive metabolic sensing R&D, though firmware engineering talent scarcity constrains scaling.
France
Regional health agencies in Île-de-France and Provence-Alpes-Côte d'Azur pilot hospital-at-home programs reimbursing remote patient monitoring for congestive heart failure patients. ANSM issues early guidance on AI-enabled diagnostic wearables, pushing developers toward pre-submission meetings for sleep apnea detection algorithms. Paris-based contract research organizations specialize in MDR clinical evidence generation for novel adhesive patch technologies.
United Kingdom
NHS England's MedTech Funding Mandate accelerates wearable adoption for atrial fibrillation screening in primary care networks, creating concentrated demand for CE-UKCA dual-certified devices. The MHRA operates transitional recognition of EU MDR certifications while building sovereign notified body capacity. Cambridge hosts embedded firmware engineering clusters for ultra-low-power biosignal processing, though Brexit-related customs friction complicates battery supply logistics.
Netherlands
Dutch diabetes care networks achieve highest European penetration of patch-based glucose monitoring, displacing traditional fingerstick protocols through insurance-funded substitution. The Health and Youth Care Inspectorate coordinates with EMA on cross-border wearable surveillance, streamlining post-market vigilance for multi-national device deployments. Eindhoven's flexible electronics ecosystem supplies printed sensor substrates to German and French device assemblers.
Italy
Lombardy and Veneto regional health services expand diagnosis-related group carve-outs to cover continuous monitoring for post-operative cardiac patients, accelerating prescription volumes for validated pulse oximetry wearables. The Italian Medicines Agency enforces MDR transitional provisions that delay novel wearable commercialization for algorithm-driven diagnostic features. Milan-based clinical research organizations specialize in biocompatibility certification for skin-contact adhesive materials.
Europe Wearable Medical Devices Market Competitive Landscape
Capability concentration sits with specialized medical technology firms possessing notified body relationships and clinical evidence generation infrastructure; scale advantage sits with consumer electronics conglomerates leveraging manufacturing volume and retail distribution density. The market structures around three archetypes: diversified health technology conglomerates with hospital-at-home platform integration, pure-play diabetes monitoring specialists with pharmacy channel depth, and consumer wearable brands seeking MDR certification elevation. Competitive moves center on MDR notified body pre-submission investments and strategic partnerships with electronic health record vendors to resolve interoperability fragmentation.
Within the diversified health technology tier, Abbott Laboratories and Koninklijke Philips N.V. occupy positions anchored by regulatory-validated platforms and hospital procurement relationships. Among specialized glucose monitoring developers, Dexcom Inc. exemplifies the pharmacy-centric distribution archetype. Samsung Electronics represents the consumer electronics contingent pursuing MDR certification elevation for cardiac and sleep monitoring features.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Koninklijke Philips N.V. |
| Omron Corporation |
| Samsung Electronics |
| Apple Inc. |
| Garmin Ltd. |
| Dexcom Inc. |
| Withings |
| Others |
Supply & Pricing Matrix
Single-source dependency on East Asian lithium-polymer cell production determines both the premium commanded by vertically integrated European assemblers and the three-tier supply chain configuration separating validated medical-grade channels from consumer-direct distribution. MDR certification timelines and biocompatibility testing backlogs further stratify pricing power across notified body relationships.
Pricing Analysis
Geographic price spreads of 40-60% separate German hospital procurement frameworks from Eastern European pharmacy-direct channels for equivalent CE-marked glucose monitoring systems. Three-tier pricing structure across premium, standard, and economy levels reflects MDR Class IIb certification depth, after-sales clinical liaison bundling, and firmware update commitment duration. Pricing pressure stems from Nordic health systems unbundling hardware from SaaS subscriptions, forcing modularization. Hospital purchasing committees exhibit lowest price sensitivity; fitness enthusiasts through direct-to-consumer channels show highest.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Jabil, and Flex holding flexible printed electronics capacity for biosensor substrate lamination. Component sourcing draws from South Korea for display modules, Japan for precision MEMS accelerometers, and China for lithium-polymer cells. Single-source vulnerability concentrates in adhesive biocompatibility materials facing ISO 10993 certification delays. Distribution runs through hospital procurement frameworks in Germany and France, pharmacy networks in Netherlands and UK, and direct-to-consumer platforms for wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital procurement committees unbundling hardware from platform subscriptions, fragmenting vendor lock-in and compressing multi-year contract values.
For Market Incumbents: Entrench notified body relationships through pre-submission investments for AI-enabled diagnostic features under EU AI Act risk classifications. Deepen backward integration into biosensor substrate production through Eindhoven flexible electronics partnerships to offset East Asian battery dependency. Defend against Nordic disaggregation by certifying standalone device performance independent of cloud service tiers.
For New Entrants and Emerging Players: Build out pharmacy channel activation through Boots Alliance and DocMorris pilot programs, bypassing hospital procurement cycle complexity. Target Polish and Romanian chronic disease management segments where wearable adoption sits below 15% and local glucose monitoring distribution remains underdeveloped. Lead with telehealth-integrated dispensing models that bundle device fulfillment with remote consultation reimbursement.
For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors specialized medical technology firms possessing clinical evidence generation infrastructure and MDR notified body pathways. Long-term viability centers on algorithm-driven diagnostic wearable platforms with post-market surveillance capabilities already operational. Watch for AI Act enforcement timing as inflection signal for preferred supplier status lock-in.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Class IIa certification for algorithm-driven cardiac wearables compresses hospital procurement timelines in Germany. |
| Hospital System Partnership | French regional health agency pilots for congestive heart failure monitoring pull validated pulse oximetry through reimbursement carve-outs. |
| Software Companion Development | Embedded diagnostic algorithms for atrial fibrillation detection face elevated EU AI Act conformity assessment scrutiny. |
| Reimbursement Strategy | Italian diagnosis-related group extensions for post-operative cardiac monitoring accelerate prescription volumes for validated devices. |
| Regulatory Pre-Submission Investment | Early notified body engagement for sleep apnea detection algorithms locks preferred supplier positioning before full AI Act enforcement. |
Research Methodology
Desk research of EMA coordination documents, MDR transitional provisions, and hospital procurement database extracts preceded structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from CE marking registries, national competent authority guidance publications, and diagnosis-related group reimbursement schedules. Bottom-up device shipment modeling triangulated against top-down healthcare expenditure allocation estimates.
Assumptions held fixed across the projection horizon include MDR enforcement timelines, EU AI Act risk classification finalization, and existing statutory health insurance reimbursement frameworks. Segmentation dimensions modeled span device architecture, end-user cost tier, biosensor technology maturity, and acute versus chronic care application. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory chokepoint resolution. Forecast inputs incorporated notified body capacity expansion rates and Eastern European pharmacy channel development trajectories.
Stress conditions across lithium-polymer supply disruption severity, MDR notified body backlog duration, and AI Act algorithm documentation requirements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including biocompatibility certification delays and interoperability standard fragmentation. Quarterly review of notified body queue lengths and national reimbursement code expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Endoluminal Device Systems Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Medical Coatings Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Global Digital Pathology Systems Market