
 Thailand Diabetes Care Devices Market | 2026-2036
Thailand Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Diabetes Care Devices Market Analytics
Silicone-based sensor membranes is shifting toward polymer-composite substrates in continuous glucose monitor construction, reducing per-unit material costs while extending wearable durability. Medtronic leverages its integrated pump-monitor ecosystem to anchor premium positioning in Thai tertiary hospitals. Abbott Laboratories differentiates through factory-calibrated sensor technology that eliminates fingerstick requirements. Novo Nordisk sustains deep channel relationships with endocrinology clinics across Bangkok and Chiang Mai.
Thailand diabetes care devices encompass electrochemical biosensors, microneedle arrays, and algorithm-driven insulin delivery systems engineered to measure interstitial glucose, process readings through proprietary software, and administer corrective hormone doses with minimal patient intervention. Continuous glucose monitors lead the product type category due to reimbursement tailwinds and physician preference for real-time data streams over episodic blood glucose meter readings. Wireless monitoring dominates the technology dimension as Thai hospitals prioritize cloud-integrated patient dashboards and remote glycemic oversight.
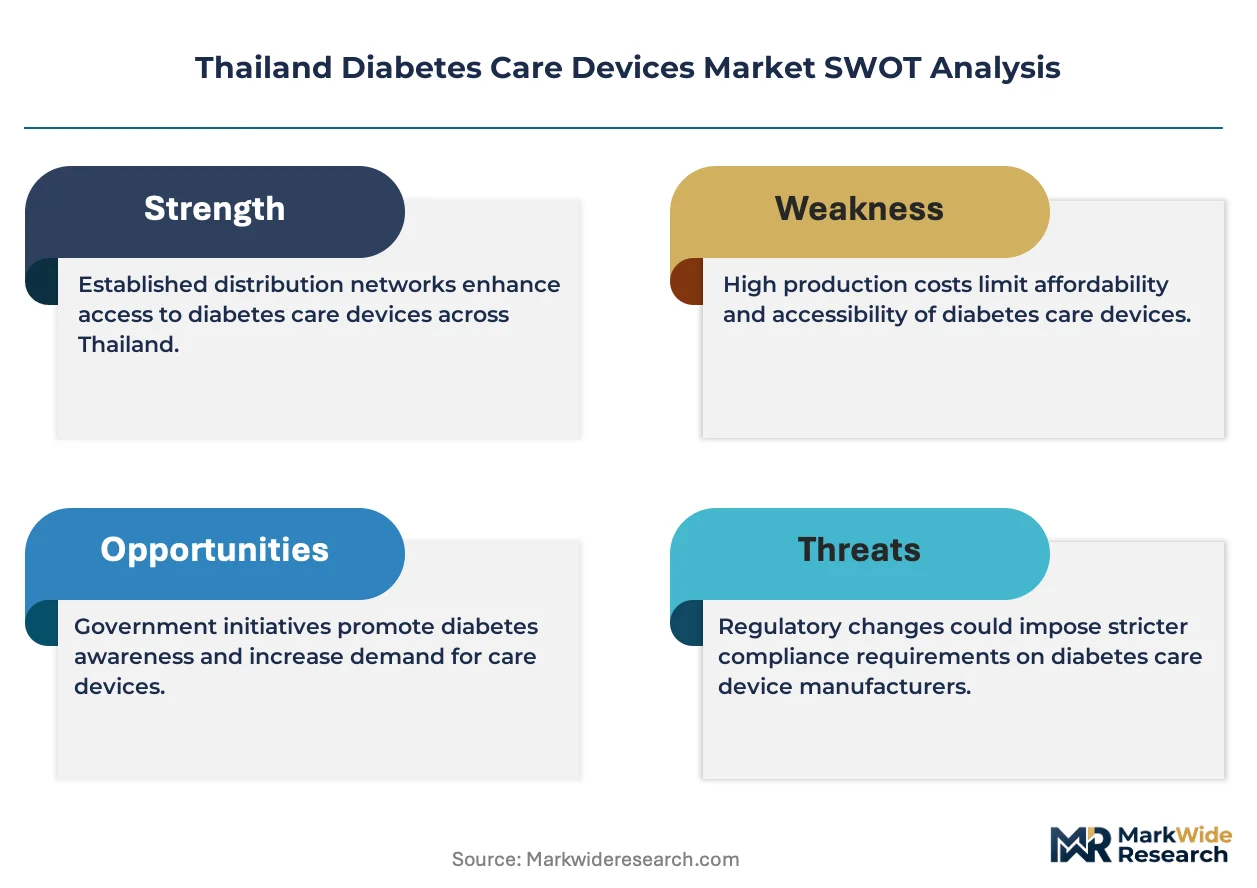
Thailand's Medical Device Control Division under the Ministry of Public Health enforces registration and post-market surveillance requirements that lengthen product approval timelines but elevate safety standards for implantable delivery systems. The Thai FDA's alignment with ASEAN Medical Device Directive harmonization is streamlining cross-border certification for multinational manufacturers. Stakeholders must monitor reimbursement list revisions and public hospital procurement centralization as these mechanisms determine volume access in Thailand's dual public-private care structure.
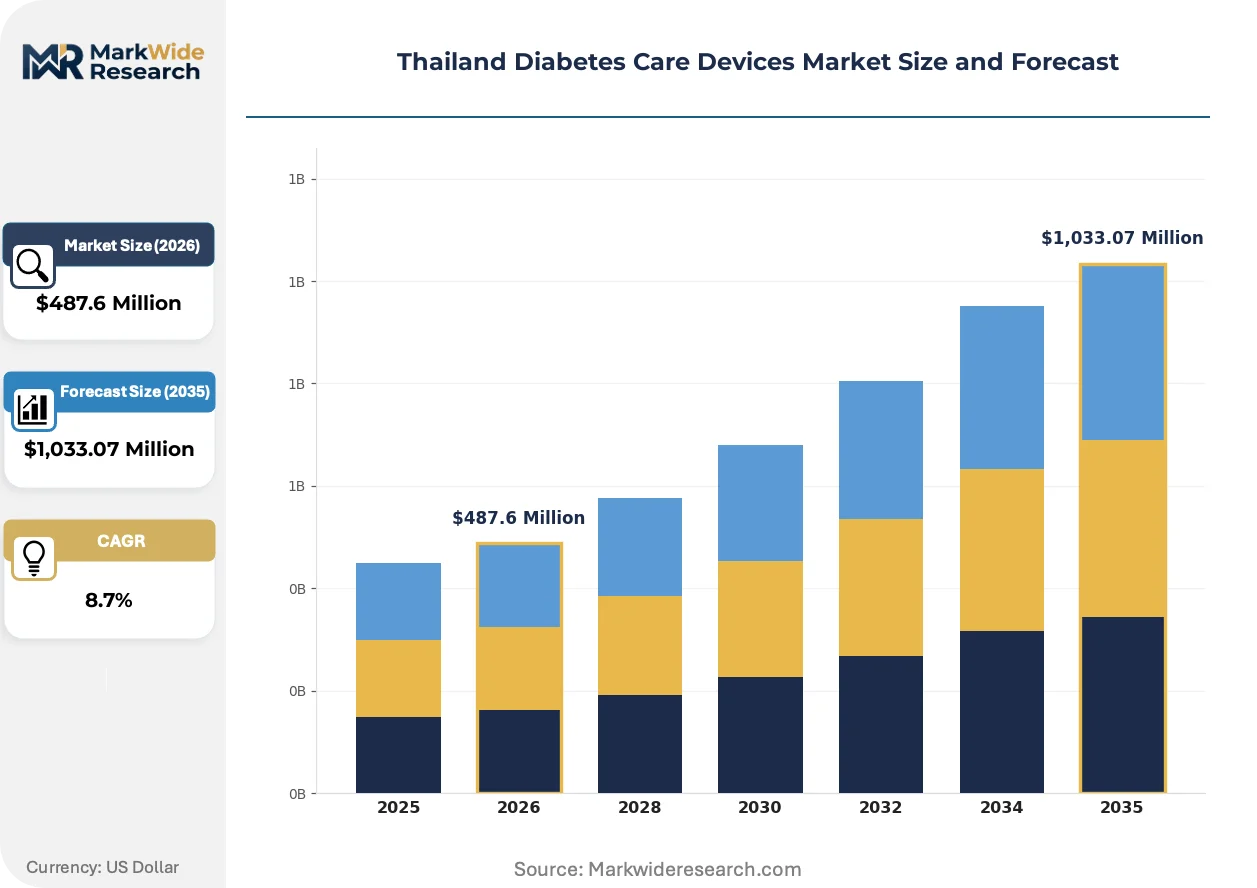
Market Dynamics
Thailand's diabetes care devices market is being reshaped by the Ministry of Public Health's centralization of public hospital procurement, which concentrates purchasing power among Bangkok's tertiary hospital networks and compresses vendor margins while demanding integrated cloud-based patient monitoring systems.
Growth Catalysts
- Thai FDA's ASEAN Medical Device Directive harmonization:The alignment with regional certification standards is shortening cross-border approval timelines for multinational manufacturers seeking entry into Thailand's dual public-private care structure.
- Continuous glucose monitoring reimbursement expansion:Thailand's universal healthcare scheme is extending coverage for real-time interstitial glucose tracking, pulling demand away from episodic blood glucose meter readings in metropolitan hospital networks.
- Wireless sensor miniaturization:Advances in polymer-composite substrate fabrication are reducing per-unit material costs while extending wearable durability for factory-calibrated sensors.
Market Restraints
- Silicone membrane supply concentration:Legacy sensor material suppliers remain concentrated in East Asian manufacturing clusters, exposing Thai device assemblers to input cost volatility and extended lead times.
- Thai Medical Device Control Division registration timelines:Post-market surveillance requirements for implantable insulin delivery systems lengthen product approval cycles, delaying revenue recognition for novel pump-monitor ecosystems.
- Interstitial fluid measurement technical limitation:Lag time between blood glucose and tissue glucose readings creates clinical hesitation among endocrinologists managing acute hypoglycemic risk.
Strategic Opportunities
- Chiang Mai specialty clinic network expansion:Northern Thailand's secondary cities present underpenetrated demand for algorithm-driven insulin delivery systems outside Bangkok's saturated metropolitan hospital corridor.
- Cloud-integrated patient dashboard convergence:Remote glycemic oversight platforms are converging with Thailand's national health information exchange, creating white space for telemedicine-integrated device vendors.
- Public hospital procurement centralization:The Ministry of Public Health's volume aggregation creates channel innovation potential for vendors offering bundled sensor-pump-service contracts with centralized maintenance.
Industry Challenges
- Biomedical algorithm validation skill gap:Thai tertiary hospitals face scarcity of clinical engineers capable of calibrating proprietary software for interstitial glucose interpretation.
- ISO 15197 certification timeline compression:Blood glucose meter accuracy standards require extensive clinical validation, stretching R&D budgets for domestic manufacturers competing against factory-calibrated imports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Diabetes Care Devices Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Continuous Glucose Monitors, Blood Glucose Meters, Lancets Technology: Wireless Monitoring, Mobile Apps, Smart Devices, IoT Solutions End User: Hospitals, Clinics, Home Care, Research Institutions Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | Medtronic, F. Hoffmann-La Roche AG, Novo Nordisk, Abbott Laboratories, Dexcom, Becton, Dickinson and Company, Insulet Corporation, Tandem Diabetes Care, Ypsomed, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Diabetes Care Devices Market Evolving Landscape
Wireless monitoring architectures are displacing conventional wired interfaces across Thailand's diabetes care landscape, with cloud-native patient dashboards and remote glycemic oversight emerging as the dominant value proposition for hospital procurement committees.
Microneedle array technology is converging with electrochemical biosensor platforms to enable minimally invasive interstitial glucose sampling. Bangkok's metropolitan hospital networks are piloting these hybrid systems in endocrinology wards, replacing fingerstick-dependent workflows. The structural consequence is converging with Thailand's push for outpatient chronic disease management, compressing inpatient monitoring revenue while expanding ambulatory device attachment rates.
Thailand's Medical Device Control Division under the Ministry of Public Health is enforcing stricter post-market surveillance protocols for implantable delivery systems. The industrial consequence elevates compliance costs for pump manufacturers while accelerating safety standard harmonization with ASEAN neighbors. Tertiary hospitals in Bangkok and Chiang Mai are responding by consolidating vendor relationships around integrated pump-monitor ecosystems with established local service infrastructure.
Procurement committees across Thailand's public hospital network are unbundling after-sales service from device acquisition contracts, shifting toward performance-based maintenance agreements with remote diagnostic capabilities. Device vendors are responding by embedding predictive analytics into cloud-integrated patient dashboards. This behavioral shift is most visible in Bangkok's university-affiliated hospitals, where glycemic data streaming to centralized command centers is becoming a mandatory tender requirement.
Thailand Diabetes Care Devices Market Segmentation
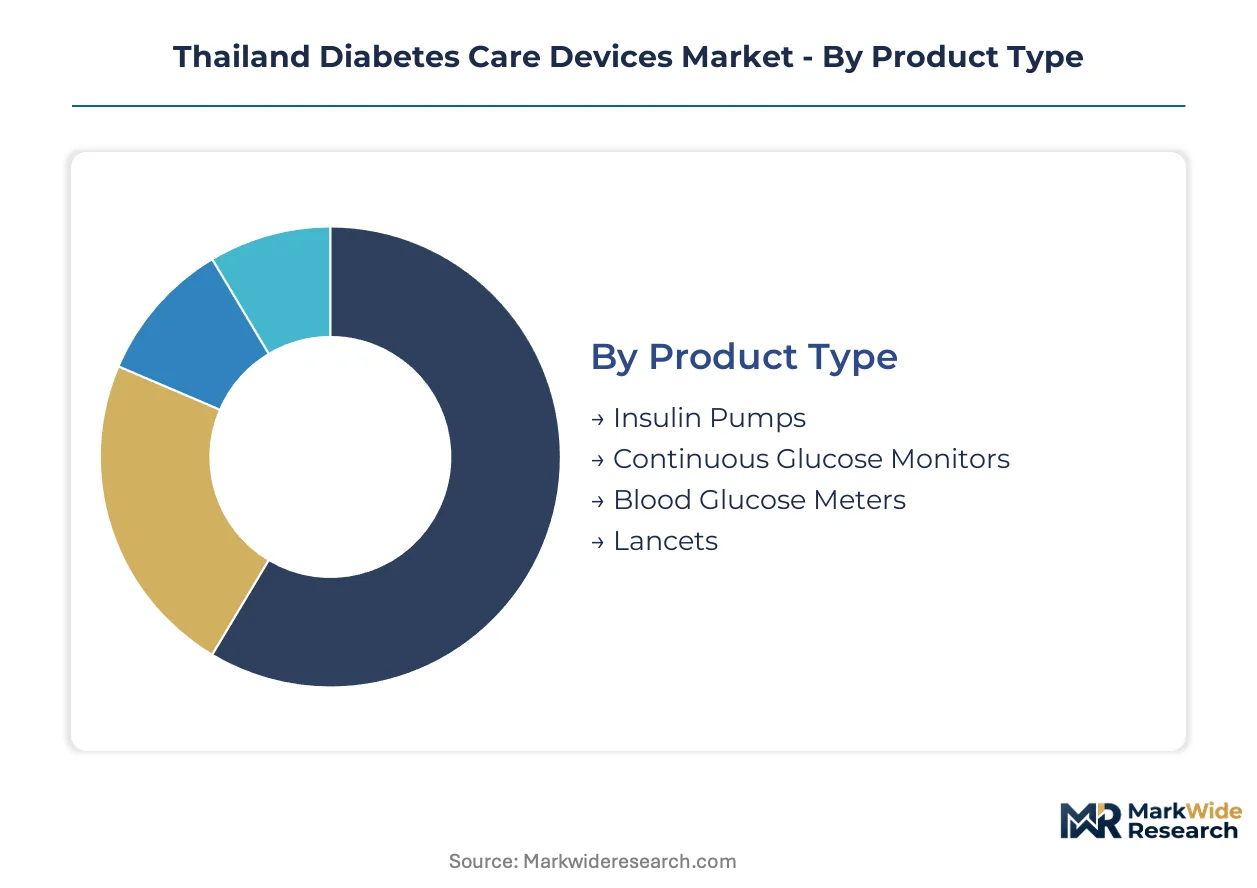
Thailand's diabetes care devices market fragments across four dimensions that determine procurement pathways and reimbursement eligibility. Product type and technology configurations dictate whether devices integrate into hospital information systems or operate as standalone patient-managed tools. Understanding these splits reveals where vendor margins concentrate versus where volume scales fastest.
Product Type:
Integration depth separates implantable delivery systems from episodic monitoring tools, with embedded pump-monitor ecosystems commanding premium positioning against disposable consumables.
- Insulin Pumps:Electromechanical delivery systems with algorithm-driven basal-bolus dosing. Bangkok's tertiary hospital networks anchor procurement volume as the Ministry of Public Health centralizes chronic disease management protocols and demands cloud-integrated patient dashboards.
- Continuous Glucose Monitors:Factory-calibrated electrochemical biosensors measuring interstitial glucose through polymer-composite substrates. Reimbursement tailwinds under Thailand's universal healthcare scheme pull demand toward real-time data streams in metropolitan hospital corridors.
- Blood Glucose Meters:Portable electrochemical devices for capillary blood sampling. ISO 15197 accuracy requirements stretch R&D budgets for domestic manufacturers competing against imported factory-calibrated alternatives.
- Lancets:Single-use microneedle consumables for fingerstick blood collection. Volume scales through pharmacy retail channels and public hospital tender contracts with standardized procurement specifications.
Volume placements concentrate in Continuous Glucose Monitors; the faster expansion belongs to Insulin Pumps.
Technology:
Cost tier stratification separates premium wireless architectures from basic mobile interfaces, with cloud-native platforms capturing hospital procurement budgets while app-only solutions serve price-sensitive home care segments.
- Wireless Monitoring:Radio-frequency or Bluetooth-enabled glucose data transmission to centralized dashboards. Thai hospitals prioritize these systems for remote glycemic oversight and cloud-integrated patient command centers.
- Mobile Apps:Smartphone-based glucose logging and insulin dose calculators. Home care adoption concentrates in Bangkok's urban corridors where smartphone penetration supports patient self-management.
- Smart Devices:Factory-integrated pump-monitor ecosystems with predictive analytics. Premium positioning in university-affiliated hospitals demands embedded service contracts with remote diagnostic capabilities.
- IoT Solutions:Sensor networks linking multiple devices through national health information exchange infrastructure. Pilot deployments in Chiang Mai specialty clinics test interoperability with Thailand's emerging telemedicine platforms.
Revenue concentrates in Wireless Monitoring; IoT Solutions are climbing the fastest as interoperability mandates take hold.
End User:
Customer type determines regulatory pathway complexity, with hospitals demanding Thai Medical Device Control Division registration while home care channels face lighter post-market surveillance obligations.
- Hospitals:Tertiary and secondary care facilities with centralized procurement committees. Bangkok's metropolitan networks drive volume through bundled sensor-pump-service contracts and mandatory glycemic data streaming requirements.
- Clinics:Endocrinology specialty practices in Bangkok and Chiang Mai. These sites favor algorithm-driven insulin delivery systems with established local service infrastructure over unbundled device purchases.
- Home Care:Patient-managed settings outside institutional oversight. Demand scales through pharmacy retail and online channels where factory-calibrated sensors eliminate fingerstick requirements.
- Research Institutions:Academic medical centers conducting clinical validation studies. Limited volume but critical influence over physician preference formation and reimbursement list recommendations.
Procurement volume concentrates in Hospitals; Clinics are gaining share fastest as specialty network expansion accelerates in northern Thailand.
Distribution Channel:
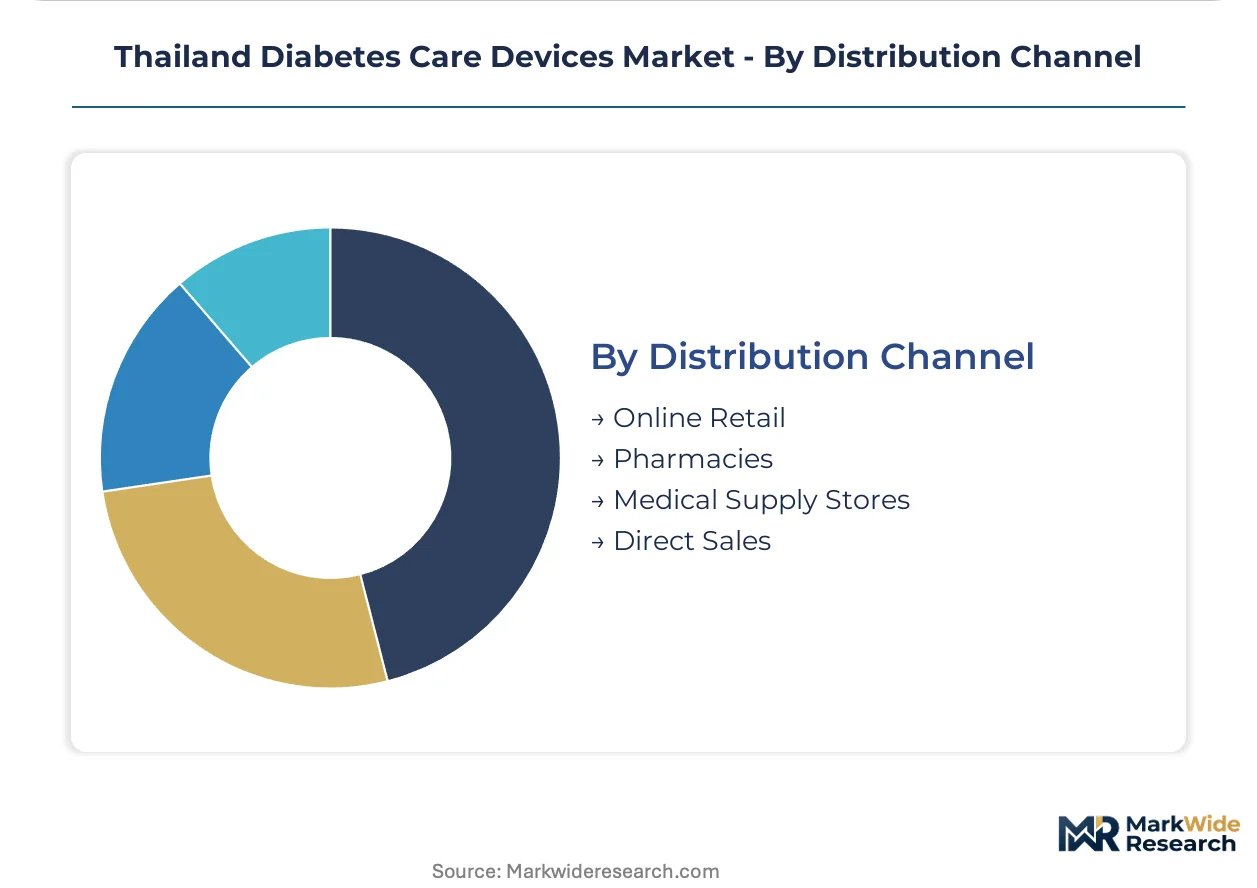
Supply concentration splits between centralized tender channels and fragmented retail, with direct sales capturing integrated ecosystem contracts while pharmacies dominate consumable replenishment.
- Online Retail:E-commerce platforms serving home care patients and price-sensitive segments. Growth tracks smartphone penetration and digital payment adoption in Bangkok's urban corridors.
- Pharmacies:Brick-and-mortar retail networks for lancets and blood glucose meter consumables. Volume scales through repeat purchase patterns and standardized universal healthcare reimbursement codes.
- Medical Supply Stores:Specialized distributors serving clinics and smaller hospitals. These intermediaries maintain inventory of pump accessories and sensor replacements with localized technical support.
- Direct Sales:Manufacturer-to-institution contracts for integrated pump-monitor ecosystems. Thai Ministry of Public Health procurement centralization favors vendors offering centralized maintenance and performance-based service agreements.
Transaction volume concentrates in Pharmacies; Direct Sales shows the steepest expansion trajectory as public hospital tender consolidation progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Economic Corridor tax-incentive zone anchors Thailand's medical device manufacturing concentration, drawing multinational assembly operations through Board of Investment privileges and duty-free import zones for polymer-composite substrates.
Bangkok Metropolitan Region
Tertiary hospital networks in Bangkok drive procurement volume for integrated pump-monitor ecosystems. The Ministry of Public Health's universal healthcare scheme extends reimbursement for continuous glucose monitors through metropolitan provider contracts. Rajavithi Hospital and Siriraj Hospital anchor clinical validation studies that shape physician preference formation nationwide.
Chiang Mai and Northern Thailand
Specialty endocrinology clinics in Chiang Mai present underpenetrated demand for algorithm-driven insulin delivery systems. The northern medical hub receives referral flows from Lao PDR and Myanmar border provinces. Maharaj Nakorn Chiang Mai Hospital pilots telemedicine-integrated glycemic oversight platforms with cloud-native patient dashboards.
Eastern Seaboard Industrial Zone
Chonburi and Rayong provinces host contract manufacturing facilities serving ASEAN medical device markets. Thai FDA's ASEAN Medical Device Directive harmonization accelerates cross-border certification for export-bound production lines. Hemaraj and Amata industrial estates concentrate polymer-composite substrate fabrication for sensor membrane assembly.
Phuket and Southern Tourism Corridor
International hospital chains in Phuket cater to medical tourism demand for premium diabetes management devices. Bangkok Hospital Phuket and Siriroj International Hospital source factory-calibrated sensors through direct manufacturer contracts. The southern region's private healthcare infrastructure operates outside public procurement centralization.
Khon Kaen and Northeastern Plateau
Srinagarind Hospital at Khon Kaen University anchors diabetes research and resident training for Isaan province networks. The northeastern region's rural healthcare system relies on blood glucose meter deployments through universal healthcare pharmacy channels. Community hospital procurement operates through provincial health office tender aggregation rather than Bangkok-centered centralization.
Thailand Diabetes Care Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pump-monitor ecosystems commanding premium positioning against disposable consumable vendors. The vendor base concentrates around three strategic archetypes: multinational medtech conglomerates with established Thai FDA registration histories, regional distributors with deep channel relationships in Bangkok's hospital networks, and emerging telemedicine-integrated platform vendors. Competitive moves center on strategic partnerships with cloud infrastructure providers and backward integration into polymer-composite substrate supply.
Among the multinational medtech tier, Medtronic, Abbott Laboratories, and Novo Nordisk occupy anchor positions. Medtronic exemplifies the integrated ecosystem archetype through its pump-monitor bundling approach. Abbott Laboratories represents factory-calibrated sensor specialization that eliminates fingerstick workflows. Novo Nordisk anchors endocrinology clinic channel relationships across Bangkok and Chiang Mai specialty networks.
| Leading Market Players |
|---|
| Medtronic |
| F. Hoffmann-La Roche AG |
| Novo Nordisk |
| Abbott Laboratories |
| Dexcom |
| Becton, Dickinson and Company |
| Insulet Corporation |
| Tandem Diabetes Care |
| Ypsomed |
| Others |
Value Network & Pricing Analysis
Polymer-composite substrate fabrication is displacing silicone-based sensor membranes across Thai device assembly lines, compressing per-unit material costs while redistributing supply leverage toward East Asian specialty chemical manufacturers. This materials transition simultaneously enables factory-calibrated sensor economics and concentrates procurement power among Bangkok's tertiary hospital networks demanding cloud-integrated patient dashboards.
Pricing Analysis
Volume concentrates in lancets and blood glucose meter consumables while margins pool in integrated pump-monitor ecosystems. Three-tier pricing structure across premium, standard, and economy levels separates factory-calibrated continuous glucose monitors from fingerstick-dependent meters and single-use disposables. Pricing pressure stems from the Ministry of Public Health's procurement centralization, which compresses vendor margins through bundled sensor-pump-service contracts. Home care patients exhibit highest price sensitivity, whereas university-affiliated hospitals prioritize predictive analytics and remote diagnostic capabilities over unit cost.
Supply Chain Analysis
Thailand's Medical Device Control Division registration requirements are reshaping sourcing patterns toward ASEAN-certified component suppliers. Polymer-composite substrates and electrochemical biosensor membranes draw from South Korea, Japan, and Taiwan manufacturing clusters. Silicone membrane supply concentration in East Asian production hubs creates single-source vulnerability for Thai device assemblers. Distribution runs through direct sales channels for integrated ecosystems, while pharmacy retail networks handle consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's diabetes care devices market is becoming a vertical-integration race, with polymer-composite substrate supply and cloud-native patient dashboard development as the decisive upstream and downstream levers.
For Market Incumbents: Extend factory-calibrated sensor production capabilities to capture reimbursement tailwinds from Thailand's universal healthcare scheme expansion. Anchor tertiary hospital relationships through embedded predictive analytics and performance-based maintenance agreements. Counter emerging telemedicine-integrated platform vendors by consolidating Chiang Mai specialty clinic networks before procurement centralization reaches northern Thailand.
For New Entrants and Emerging Players: The gap between premium integrated pump-monitor ecosystems and economy-tier blood glucose meters offers entry space for algorithm-driven insulin delivery systems with stripped-down cloud connectivity. Target Chiang Mai and Khon Kaen provincial health office tender aggregation, where Bangkok-centered centralization has not yet consolidated purchasing. Lead with telemedicine-integrated glycemic oversight platforms that interoperate with Thailand's national health information exchange pilots.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational medtech conglomerates seeking Thai FDA registration histories and established hospital procurement relationships. Five-to-ten year viability hinges on reimbursement list positioning rather than device innovation alone. Monitor Thai Medical Device Control Division post-market surveillance protocol revisions as the critical inflection signal for compliance cost escalation and vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Thai FDA Registration Pathway | Accelerates market entry through ASEAN Medical Device Directive harmonization. |
| Hospital System Partnership | Secures volume access through Ministry of Public Health procurement centralization. |
| Software Companion Development | Enables cloud-integrated patient dashboards mandatory in Bangkok university-affiliated tenders. |
| Reimbursement Strategy | Determines universal healthcare scheme coverage for continuous glucose monitors versus blood glucose meters. |
| Backward Integration into Substrates | Reduces exposure to East Asian silicone membrane supply concentration and lead time volatility. |
Research Methodology
Thai FDA registration databases, hospital procurement records, and ASEAN Medical Device Directive harmonization documents formed the secondary backbone. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and endocrinology clinic administrators combined with secondary validation. Bottom-up and top-down triangulation reconciled device shipment data against reimbursement claims and tender awards.
Bottom-up modeling tracked unit economics across product type, technology architecture, and end-user channel dimensions. Top-down validation anchored aggregate market size against Ministry of Public Health chronic disease management budget allocations and universal healthcare scheme expenditure reports. CAGRs derived from segment-specific adoption curves, reimbursement expansion timelines, and procurement centralization progress throughout the forecast period. Forecast inputs incorporated polymer-composite substrate cost trajectories and cloud infrastructure penetration rates.
Underlying measurement precision varies by segment; continuous glucose monitors and insulin pumps carry tighter precision than lancets and blood glucose meters due to concentrated procurement data availability. Forecasts reflect assumptions regarding reimbursement list revisions, public hospital tender consolidation pace, and ASEAN regulatory harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
Vietnam Insulin Infusion Pump Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market