
 Mobile Healthcare Devices Market | 2026-2036
Mobile Healthcare Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Healthcare Devices Market Foresight
EU MDR is repositioning the cost-of-entry calculus for wearable monitors and mobile diagnostic tools entering European markets. Medtronic plc leverages its vertically integrated manufacturing footprint to sustain compliance economies that smaller rivals cannot match. Philips anchors its competitive stance through deep channel control across hospital and home care networks. DexCom, Inc. specializes in continuous glucose monitoring hardware where FDA breakthrough device designation has created durable regulatory moats.
Mobile healthcare devices encompass portable, network-connected instruments and software applications that capture, transmit, or analyze physiological data outside traditional clinical settings, typically incorporating biosensors, wireless communication modules, and cloud-based analytics engines with power budgets under one watt for wearable form factors. These systems serve to decentralize care delivery, reduce acute episode frequency, and enable real-time clinical decision support at the point of living. Wearable monitors occupy the largest revenue pool today due to established consumer familiarity and expanding payer reimbursement, while telehealth platforms represent the fastest-expanding segment as health systems rebalance capacity toward virtual-first workflows. Mobile diagnostic tools command premium pricing in professional channels where ISO 13485 quality management certification gates institutional procurement.
FDA software-as-a-medical-device guidance, EU MDR technical documentation requirements, and HIPAA security rule provisions collectively shape product development roadmaps, commercialization timelines, and liability exposure for vendors operating across multiple jurisdictions. Japan's PMDA has accelerated foreign manufacturer registration pathways for AI-enabled mobile diagnostics, redirecting R&D investment toward Tokyo and Osaka clinical validation sites. Stakeholders must monitor evolving interoperability mandates from ONC and equivalent national bodies, as data portability standards will determine which platforms achieve systemic lock-in versus commoditization.
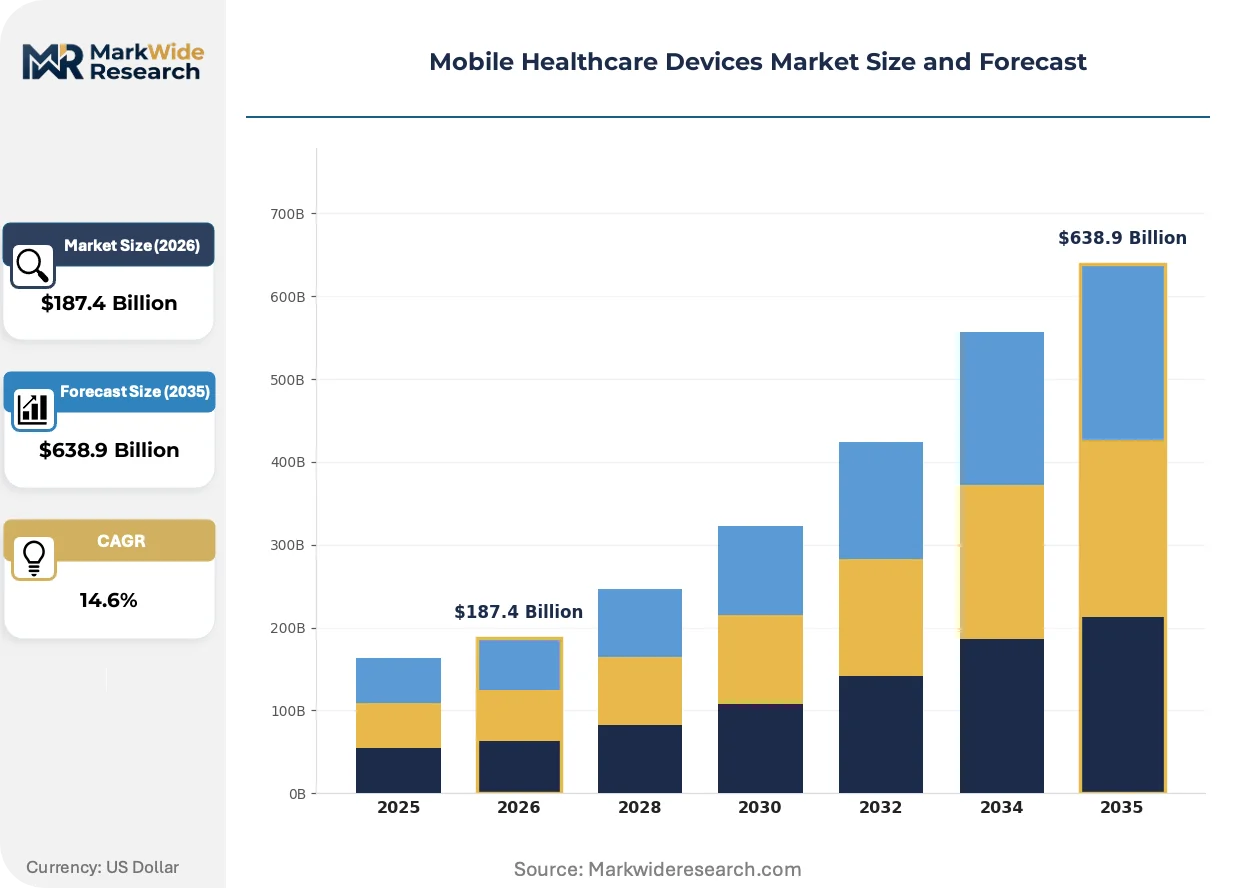
Market Dynamics
Reimbursement pathway maturation across Medicare, Germany's G-BA, and Japan's MHLW is compressing commercialization timelines and forcing vendors to front-load clinical validation spend before first revenue.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines for AI-enabled diagnostics reduce time-to-market by 12-18 months, concentrating investment in algorithmic biomarker discovery.
- Home Care Provider Consolidation:Large multi-state operators standardize on interoperable remote monitoring platforms, creating volume pull for validated device families.
- Bluetooth Low Energy 5.3:Extended range and reduced power draw enable continuous cardiac monitoring in residential settings without hub dependency.
Market Restraints
- EU MDR Technical Documentation Burden:Clinical evidence requirements for Class IIa wearables have tripled notified body review timelines to 18-24 months.
- MEMS Sensor Supply Concentration:Taiwanese foundries control 70% of high-precision accelerometer wafer supply, exposing vendors to geopolitical disruption.
- Li-Ion Cell Form Factor Constraints:Wearable power density limits constrain multi-day continuous monitoring without daily charging cycles.
Strategic Opportunities
- India's PLI Scheme for Medical Electronics:Manufacturing incentives and CDSCO fast-track pathways for essential devices redirect assembly from China to Gujarat and Tamil Nadu clusters.
- Rural Health Clinic Telemetry:Satellite-backhauled diagnostic imaging in sub-Saharan Africa and Southeast Asian archipelagos creates demand for ultra-low-bandwidth compression algorithms.
- Continuous Blood Pressure Without Cuff:Photoplethysmography plus machine learning convergence promises hypertension management in consumer form factors.
Industry Challenges
- Embedded Firmware Security Certification:UL 2900-2-1 and FDA cybersecurity guidance require specialized talent pools that command 40% salary premiums over general IoT engineering.
- Legacy EHR Integration Complexity:HL7 FHIR implementation varies across Epic, Cerner, and Meditech deployments, forcing device vendors to maintain multiple interface configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Healthcare Devices Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Mobile Diagnostic Tools, Telehealth Platforms, Health Apps End User: Patients, Healthcare Professionals, Clinics, Home Care Providers Technology: Bluetooth, Wi-Fi, Cloud Computing, NFC Application: Chronic Disease Management, Remote Patient Monitoring, Fitness Tracking, Emergency Response |
| Companies Covered | Medtronic plc, GE HealthCare, Koninklijke Philips N.V., Apple Inc., Samsung, DexCom, Inc., Fitbit Inc., OMRON Corporation, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Healthcare Devices Market Shifts & Advancements
Algorithmic biomarker extraction from photoplethysmography signals is collapsing the cost structure of continuous physiological monitoring and enabling consumer-grade hardware to approximate clinical accuracy.
Solid-state battery chemistry is electrifying wearable power architecture. Thin-film lithium metal cells from US and Korean suppliers deliver 500 Wh/L density in sub-2mm packages. Medtronic and Philips are qualifying these for next-generation cardiac patches. The technology is electrifying design freedom for multi-sensor arrays previously constrained by volumetric power budgets.
EU AI Act risk classification is restructuring software validation protocols. High-risk AI medical devices face conformity assessment blending MDR technical documentation with algorithmic impact assessments. Continuous glucose monitoring systems with predictive hypoglycemia alerts fall under this regime, forcing vendors to maintain dual regulatory dossiers for EU and US markets.
Hospital procurement departments are unbundling device hardware from data platform subscriptions. Health systems in Germany and Japan now negotiate three-year SaaS contracts separately from capital equipment purchases, compressing upfront device margins while extending customer lifetime value for analytics vendors.
Mobile Healthcare Devices Market Segmentation
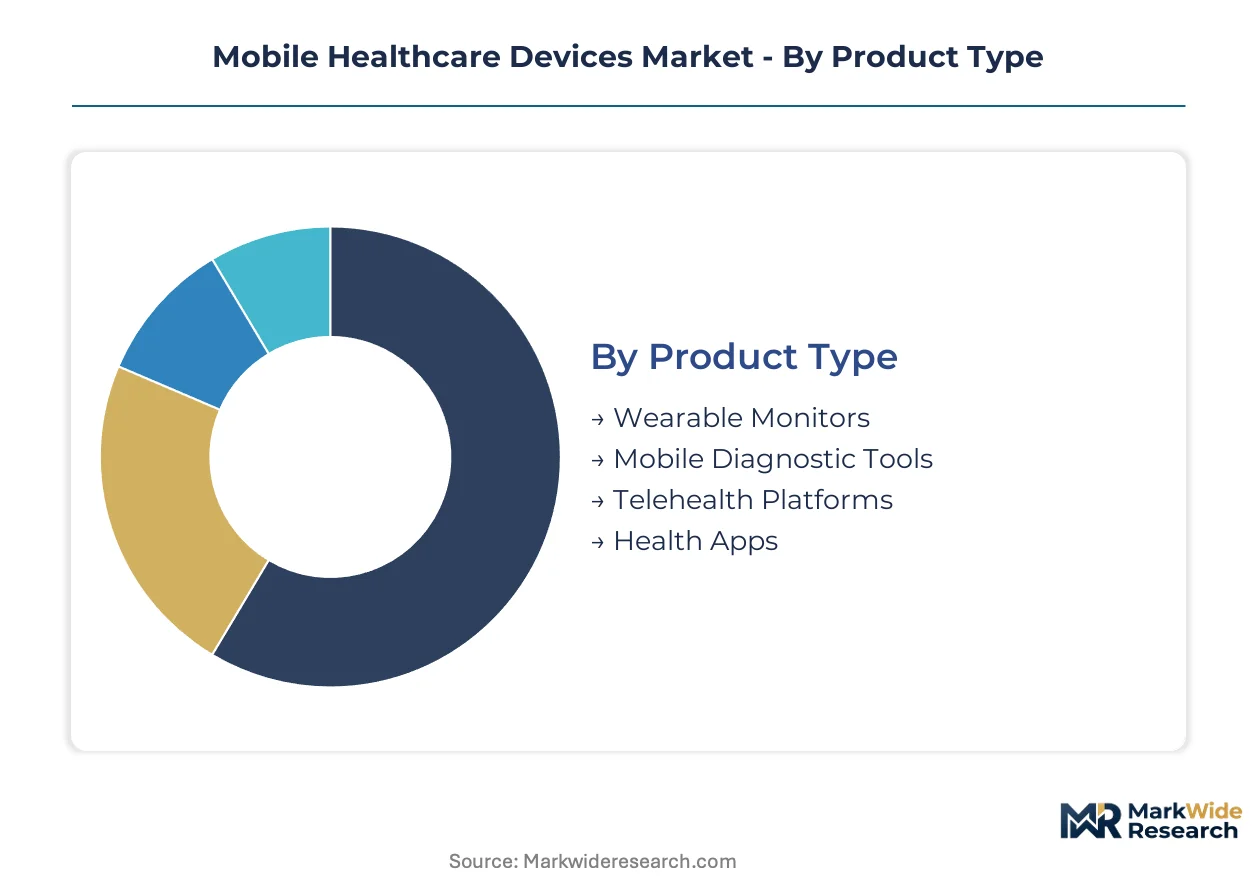
Mobile healthcare devices fragment across four distinct category axes, each governing different procurement logics and margin structures. Product type determines hardware versus software revenue recognition. End user dictates regulatory pathway complexity and reimbursement eligibility.
Product Type:
Wearable monitors anchor volume throughput while telehealth platforms capture premium recurring revenue.
- Wearable Monitors:Biosensor-embedded wristbands, patches, and clothing integrating accelerometers, photoplethysmography, and temperature sensors with sub-one-watt power budgets. Demand concentrates among home care providers in Germany and the United States where G-BA and Medicare reimbursement pathways have matured for continuous glucose and cardiac monitoring.
- Telehealth Platforms:Cloud-native software stacks enabling synchronous video consultation, asynchronous store-and-forward diagnostics, and AI triage routing. Healthcare systems in Japan and the United States rebalance capacity toward virtual-first workflows, compressing commercialization timelines for vendors with FDA breakthrough device designation or PMDA accelerated pathways.
- Mobile Diagnostic Tools:Handheld ultrasound, ECG, and pulse oximetry hardware with ISO 13485 certification gating institutional procurement.
- Health Apps:Consumer-facing software for fitness tracking, medication adherence, and wellness coaching operating below medical device thresholds in most jurisdictions.
Today's leader: Wearable Monitors. Tomorrow's challenger: Telehealth Platforms.
End User:
Institutional buyers command procurement scale while individual patients drive unit velocity through direct-to-consumer channels.
- Home Care Providers:Multi-state operators standardizing on interoperable remote monitoring platforms create volume pull for validated device families with HL7 FHIR connectivity. Large networks in the United States negotiate enterprise SaaS contracts separate from capital equipment, extending customer lifetime value for analytics vendors.
- Healthcare Professionals:Physicians and nurses utilizing point-of-care diagnostic tools in ambulatory settings where FDA premarket notification and EU MDR technical documentation requirements shape vendor selection. Premium pricing persists in professional channels where clinical validation spend front-loads regulatory clearance.
- Patients:Individual consumers purchasing wearable monitors and health apps through retail and direct-to-consumer channels, with demand sensitivity to out-of-pocket cost and charging cycle convenience.
- Clinics:Small and mid-sized outpatient facilities balancing capital constraints against reimbursement capture for remote patient monitoring CPT codes.
Home Care Providers consolidate purchasing power fastest. Patients remain the volume foundation.
Technology:
Wireless protocol selection determines range, power draw, and interoperability with legacy health IT infrastructure.
- Bluetooth:Bluetooth Low Energy 5.3 enables extended-range cardiac monitoring in residential settings without hub dependency, reducing infrastructure cost for home care deployments.
- Wi-Fi:Higher bandwidth protocol supporting diagnostic imaging transmission and telehealth video streams where residential broadband penetration permits.
- Cloud Computing:Distributed analytics engines processing algorithmic biomarker extraction from photoplethysmography signals, collapsing cost structures for continuous physiological monitoring.
- NFC:Near-field pairing and authentication for clinical workflow integration, prevalent in European hospital procurement specifications.
Bluetooth dominates wearable connectivity. Cloud Computing expands most quickly as AI-enabled diagnostics proliferate.
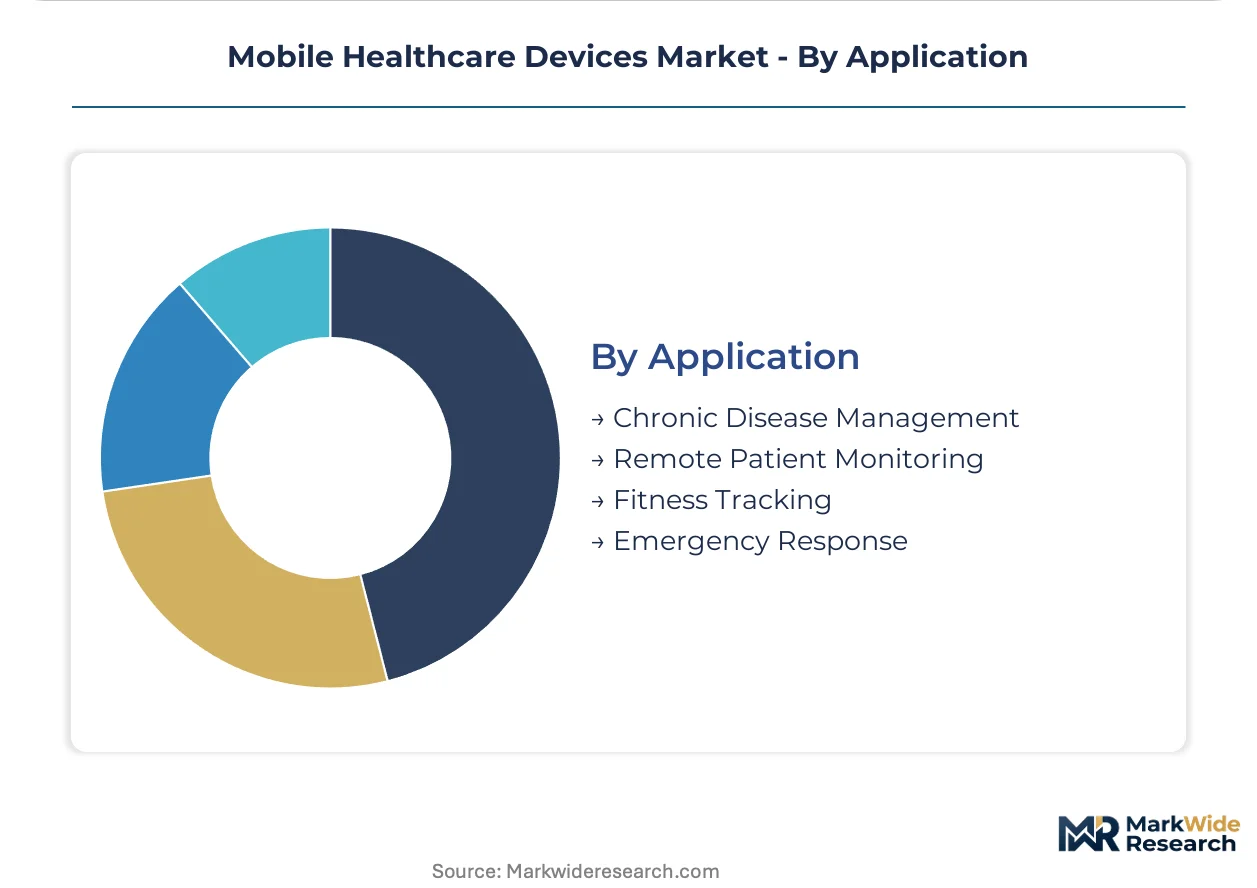
Application:
Clinical acuity tier determines regulatory classification and reimbursement intensity across use cases.
- Chronic Disease Management:Continuous glucose monitoring, hypertension tracking, and heart failure surveillance requiring FDA Class II or EU MDR Class IIa certification. DexCom and Medtronic have established durable regulatory moats through breakthrough device designations and vertically integrated manufacturing.
- Remote Patient Monitoring:Post-acute discharge surveillance and preventive monitoring programs where Medicare, Germany's G-BA, and Japan's MHLW reimbursement pathway maturation compresses vendor commercialization timelines.
- Fitness Tracking:Consumer wellness applications operating below medical device thresholds, with algorithmic biomarker extraction enabling clinical-grade accuracy from consumer hardware.
- Emergency Response:Fall detection, cardiac event alerting, and satellite-backhauled telemetry for rural and maritime settings requiring ultra-low-bandwidth compression algorithms.
Chronic Disease Management commands premium pricing. Remote Patient Monitoring gains share fastest as health systems rebalance toward decentralized care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent pools in Boston, Basel, and Osaka anchor the industry's geographic concentration. Regulatory science expertise clusters near FDA headquarters in Maryland, EMA in Amsterdam, and PMDA in Tokyo. Manufacturing scale concentrates where electronics assembly ecosystems intersect with medical device quality management capabilities.
United States
Medicare reimbursement pathways for remote patient monitoring CPT codes drive home care provider procurement at scale. FDA breakthrough device designation compresses commercialization timelines for AI-enabled diagnostics. The Minneapolis-St. Paul corridor hosts vertically integrated manufacturing operations serving cardiac and glucose monitoring segments.
Germany
G-BA reimbursement decisions for connected care devices standardize procurement across statutory health insurance funds. EU MDR technical documentation requirements triple notified body review timelines, favoring incumbents with compliance economies. The Baden-Württemberg cluster combines precision engineering heritage with ISO 13485-certified contract manufacturing.
Japan
MHLW reimbursement maturation for telehealth platforms accelerates virtual-first workflow adoption in aging prefectures. PMDA has streamlined foreign manufacturer registration for AI-enabled mobile diagnostics, redirecting clinical validation investment toward Tokyo and Osaka sites. The Kansai region concentrates wearable sensor fabrication for export markets.
India
CDSCO fast-track pathways for essential medical electronics attract assembly relocation from China. The PLI scheme for medical electronics offers manufacturing incentives redirecting production to Gujarat and Tamil Nadu clusters. Bengaluru's software engineering density supports algorithm development for low-cost diagnostic applications.
Switzerland
Swissmedic's alignment with EU MDR procedures enables simultaneous European market access from a single regulatory base. Precision manufacturing capabilities around Lake Geneva supply MEMS components for wearable form factors. The Basel pharmaceutical ecosystem creates demand for clinical trial-grade remote monitoring devices.
Mobile Healthcare Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integrated platform tiers. Medtronic plc and Koninklijke Philips N.V. leverage vertically integrated manufacturing footprints and deep hospital channel control. Pure-play specialists concentrate on single-modality excellence where regulatory moats protect pricing. Strategic moves center on M&A for data platform capabilities and geographic expansion into reimbursement-mature markets.
Among diversified health technology conglomerates, Medtronic plc and GE HealthCare exemplify scale-driven archetypes with captive supply chains and multi-modality portfolios. Koninklijke Philips N.V. occupies a position emphasizing channel depth across acute and post-acute settings. DexCom, Inc. represents the focused specialist model, concentrating regulatory investment and manufacturing precision on continuous glucose monitoring hardware where FDA breakthrough designation has created durable competitive separation.
| Leading Market Players |
|---|
| Medtronic plc |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Apple Inc. |
| Samsung |
| DexCom, Inc. |
| Fitbit Inc. |
| OMRON Corporation |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Captive manufacturing of MEMS sensors and battery cells anchors supply positioning for wearable device vendors while simultaneously determining pricing power across premium and economy tiers. Medtronic and Philips sustain margin separation through in-house fabrication of accelerometer wafers and thin-film lithium cells that smaller competitors must source at spot-market premiums.
Pricing Analysis
Bundled hardware-plus-SaaS contracts dominate institutional procurement while unbundled transactional sales persist in direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated devices from CE-marked equivalents and unregulated wellness trackers. Cost compression in the standard tier is intensifying because hospital procurement departments now negotiate analytics subscriptions separately from capital equipment. Patients purchasing through retail channels exhibit highest price sensitivity to out-of-pocket cost and charging cycle inconvenience.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from home care provider networks while distributor-mediated flows serve clinic and individual patient segments. Component supply concentrates in Taiwan for MEMS wafers, South Korea for solid-state battery cells, and China for PCB assembly and sensor packaging. Raw material dependencies include lithium metal anodes, high-purity silicon wafers, and medical-grade polymers for biocompatible housings. Single-source vulnerability in Taiwanese foundry capacity exposes vendors to geopolitical disruption. Distribution runs through ISO 13485-certified contract manufacturers serving Medtronic in Minneapolis and Philips in Eindhoven.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile healthcare device manufacturing offers geographic-arbitrage value through India's PLI scheme incentives, which undercut Chinese assembly costs while maintaining CDSCO regulatory alignment for export markets.
For Market Incumbents: Extend regulatory moat durability by accelerating FDA breakthrough submissions for AI-enabled diagnostics before EU AI Act conformity assessments proliferate. Deepen backward integration into solid-state battery chemistry to offset Taiwanese MEMS supply concentration. Fortify channel control through multi-year SaaS contracts with home care provider networks that standardize on interoperable platforms. For New Entrants and Emerging Players: Rural health clinics in sub-Saharan Africa represent an underserved buyer archetype with unmet demand for satellite-backhauled diagnostic imaging and ultra-low-bandwidth compression algorithms. Target India's domestic market for essential medical electronics where CDSCO fast-track pathways compress clearance timelines. Pursue white-label manufacturing partnerships with Gujarat-based assemblers to bypass capital-intensive facility buildout. For Investors and Strategic Acquirers: Roll-up economics work for telehealth platform specialists because hospital procurement unbundling is fragmenting analytics revenue across dozens of subscale vendors. Focus acquisition screening on firms with HL7 FHIR connectivity and Medicare reimbursement validation. Watch for FDA software-as-a-medical-device guidance tightening as the inflection signal that regulatory compliance costs will consolidate the vendor base.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review timelines compress commercialization schedules for AI-enabled diagnostics by 12-18 months. |
| EU MDR Technical Documentation Investment | Tripled notified body review timelines favor incumbents with compliance economies over emerging entrants. |
| Hospital System Partnership | Enterprise SaaS contracts with multi-state home care operators extend customer lifetime value for analytics vendors. |
| Software Companion Development | Algorithmic biomarker extraction from photoplethysmography enables consumer hardware to approximate clinical accuracy. |
| Reimbursement Strategy | Medicare CPT code capture for remote patient monitoring drives procurement at scale among institutional buyers. |
Research Methodology
Direct dialogue with hospital purchasing committees, biomedical engineers, GPO contracts managers, and home care provider procurement directors grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body registers, and hospital procurement contract disclosures. Bottom-up and top-down triangulation reconciled unit shipment estimates with revenue aggregation across product type and end user segments.
Segmented outputs across the analysis window reflect modeled projections for wearable monitors, telehealth platforms, mobile diagnostic tools, and health apps by technology protocol and application acuity tier. CAGRs were derived from regression analysis against reimbursement pathway maturation indices and regulatory clearance velocity. Forecast inputs incorporated Bluetooth Low Energy adoption curves, solid-state battery qualification timelines, and AI diagnostic algorithm validation spend patterns.
Underlying measurement precision varies by segment; telehealth platform revenue carries tighter precision than health app downloads due to disclosed SaaS contract values. Forecasts reflect assumptions about FDA guidance stability, EU MDR implementation consistency, and Medicare reimbursement expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
India Hemostats Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Global Medical Drones Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Syringeless Injector Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Global Spinal Cord Stimulation Devices Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
United States Contraceptive Devices Market