
 Global Self Care Medical Devices Market | 2026-2036
Global Self Care Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self Care Medical Devices Market Foresight
Home care users is recalibrating the addressable base for self care medical devices as post-discharge monitoring protocols expand beyond traditional clinical boundaries. Medtronic leverages its vertically integrated sensor manufacturing to dominate continuous glucose monitoring supply chains. Koninklijke Philips N.V. sustains brand authority across sleep and respiratory therapy categories through dedicated home ventilation platforms. Abbott Laboratories differentiates via factory-calibrated sensor architectures that reduce end-user calibration burdens.
Self care medical devices encompass portable, user-operated diagnostic and therapeutic instruments designed for non-clinical settings, typically incorporating biosensors, microfluidic cartridges, or pneumatic delivery systems with accuracy tolerances aligned to clinical-grade ISO 15197 and ISO 81060 standards. Blood glucose monitors occupy the largest revenue pool within product type segmentation due to recurring consumable attachment rates, while pulse oximeters retain the fastest trajectory following their integration into remote patient monitoring bundles. Diabetes management anchors application-level demand as insulin-dependent populations require daily metabolic tracking, whereas cardiovascular health applications are maturing around blood pressure monitor replacement cycles with modest feature differentiation.
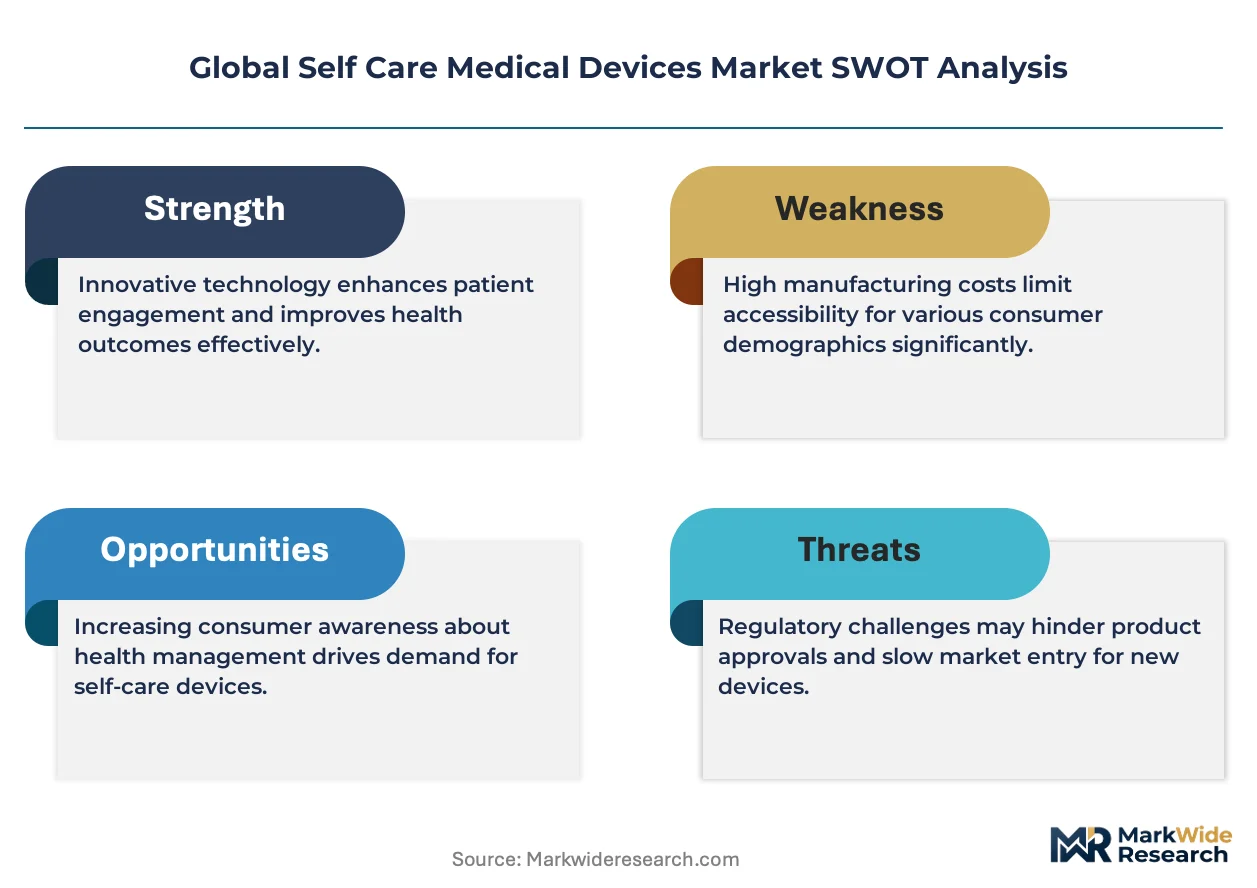
FDA premarket notification pathways and EU MDR conformity assessments are extending development timelines for novel connected devices, while ISO 14971 risk management frameworks mandate systematic hazard controls across software-enabled diagnostics. Japan's PMDA and South Korea's MFDS impose additional electromagnetic compatibility and biocompatibility testing layers that filter smaller entrants from premium market tiers. Stakeholders must weigh regulatory capital requirements against the margin compression risk of undifferentiated hardware commoditization in e-commerce channels.
Market Dynamics
Post-acute monitoring migration from hospitals to domestic environments is compressing device distribution channels and forcing manufacturers to redesign user interfaces for non-clinical operators. FDA 510(k) clearance timelines and EU MDR technical documentation requirements now consume 18-24 months for connected diagnostic platforms.
Growth Catalysts
- ISO 15197 accuracy mandates:Blood glucose monitor manufacturers in Germany and Japan are upgrading sensor architectures to meet tightened analytical performance thresholds, triggering replacement demand among insulin-dependent populations.
- Home care users:Post-discharge cardiac monitoring protocols in the United States now prescribe ambulatory blood pressure devices for 30-day observation windows, expanding the addressable patient base beyond traditional clinical boundaries.
- Continuous glucose monitoring:Factory-calibrated sensor technologies eliminate fingerstick calibration requirements, reducing user friction and accelerating penetration among Type 1 diabetes patients in reimbursement-cleared markets.
Market Restraints
- EU MDR conformity costs:Technical documentation and notified body review fees for Class IIa connected devices have tripled since 2021, filtering smaller manufacturers from premium European market tiers.
- Biocompatibility testing layers:Japan's PMDA and South Korea's MFDS impose additional electromagnetic compatibility validation requirements that extend development timelines for wireless-enabled diagnostic tools.
- Consumable attachment economics:Blood glucose test strip pricing compression in United States retail channels squeezes margin pools for monitor manufacturers dependent on recurring revenue models.
Strategic Opportunities
- Remote patient monitoring bundles:Pulse oximeter integration into Medicare-reimbursed chronic care management programs in the United States creates new channel access for multi-parameter home monitoring platforms.
- India's CDSCO fast-track pathway:Streamlined approval mechanisms for low-risk diagnostic devices enable earlier market entry for manufacturers willing to establish local manufacturing under the PLI scheme.
- AI-enabled arrhythmia detection:Machine learning algorithms embedded in blood pressure monitors and ECG wearables are expanding into cardiovascular risk stratification applications previously confined to clinical settings.
Industry Challenges
- ISO 14971 risk management documentation:Systematic hazard analysis for software-enabled diagnostics requires specialized regulatory affairs talent that concentrates among contract research organizations in Massachusetts and Basel.
- Legacy hospital procurement integration:Home care devices must interface with electronic health record systems from Epic and Cerner, demanding interoperability certifications that delay product launches by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self Care Medical Devices Market |
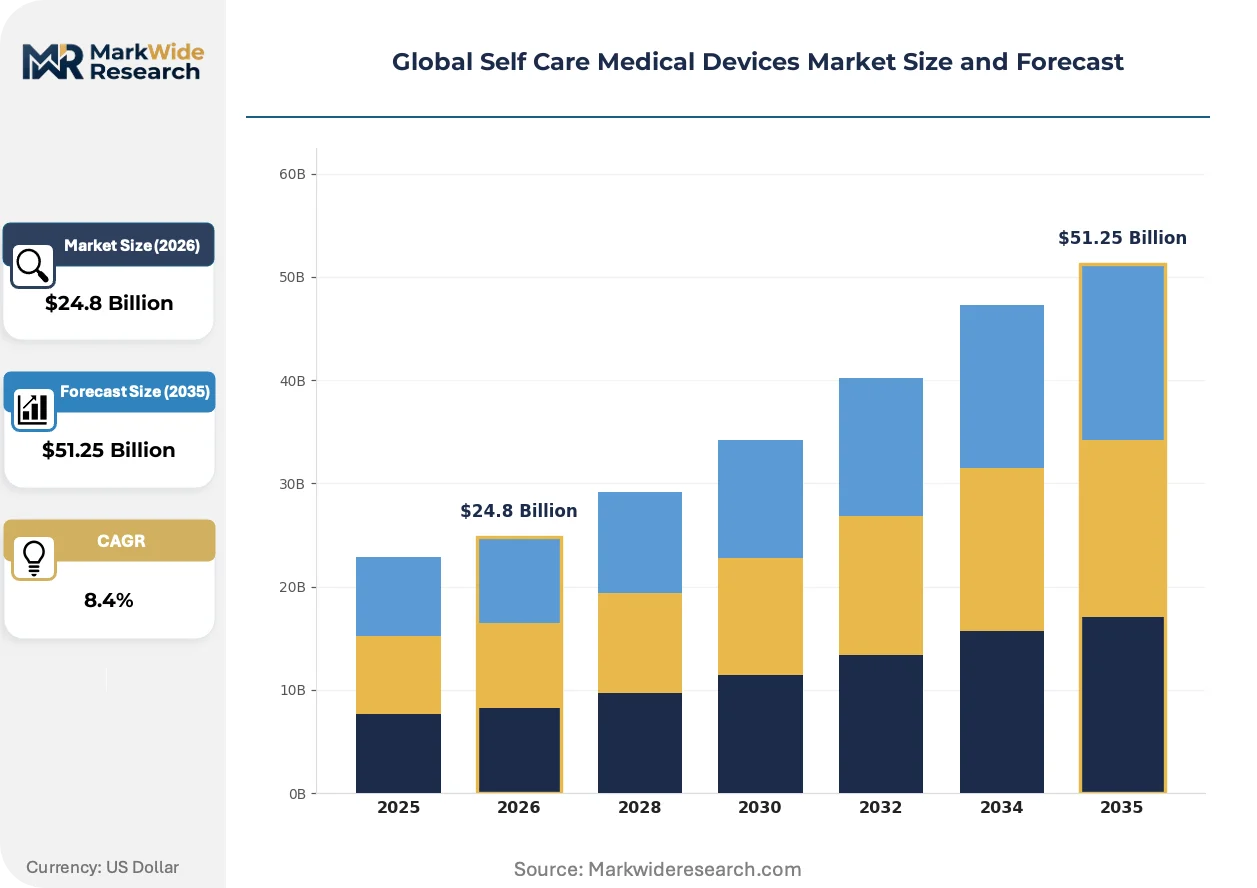
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Monitors, Blood Pressure Monitors, Thermometers, Pulse Oximeters, Nebulizers Application: Diabetes Management, Hypertension Monitoring, Respiratory Therapy, Cardiovascular Health, Fever Detection End User: Home Care Users, Elderly Individuals, Fitness Enthusiasts, Chronic Disease Patients, Caregivers Distribution Channel: Online Pharmacies, Retail Pharmacies, Medical Stores, E-commerce Platforms, Direct Sales |
| Companies Covered | Medtronic, Koninklijke Philips N.V., ResMed, Inc., Abbott Laboratories, Johnson & Johnson, GE Healthcare, OMRON Healthcare, Inc., DexCom, Inc., Roche Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self Care Medical Devices Market Shifts & Advancements
Connected diagnostic platforms are converging with consumer electronics supply chains, compressing sensor costs and accelerating firmware update cycles. Manufacturers now compete on algorithmic accuracy rather than hardware specifications alone.
Photoplethysmography sensors paired with multi-wavelength LEDs are expanding into continuous blood pressure estimation and atrial fibrillation screening functions. Sleep apnea patients and hypertensive populations in Germany and Japan are adopting these combined-function wearables at rates exceeding standalone pulse oximeter purchases. The technology is expanding into clinical validation studies required for FDA de novo classification and reimbursement eligibility.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for all Class IIa software-enabled devices, including predicate comparisons for algorithm updates. Manufacturers serving European markets must maintain post-market surveillance systems tracking real-world performance data. Blood glucose monitor vendors with legacy CE marks under the Medical Devices Directive face mandatory recertification audits that compress available notified body capacity.
Direct-to-consumer subscription models for continuous glucose monitor sensors are displacing traditional pharmacy distribution in United States metropolitan markets. Patients in Texas and Florida bypass retail channels for automated monthly deliveries tied to mobile app engagement. This channel shift concentrates customer acquisition spending on digital platforms and reduces dependence on retail pharmacy shelf space negotiations.
Global Self Care Medical Devices Market Segmentation
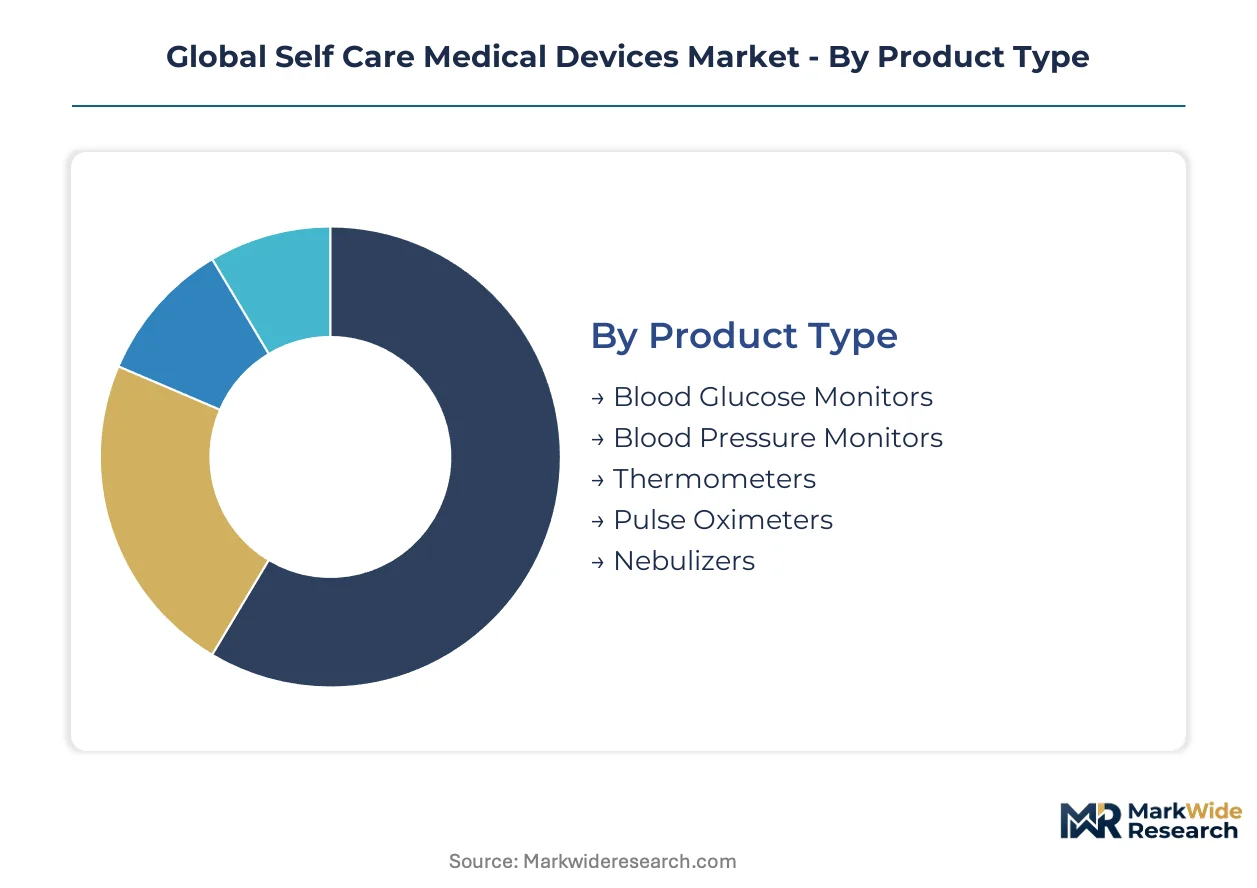
Self care medical devices fragment across four distinct taxonomies that reshape procurement patterns and margin structures. Product type determines consumable attachment economics and replacement cadence. Application segmentation governs reimbursement eligibility and clinical validation requirements across national health systems.
Product Type:
Replacement cycles and sensor upgrade trajectories define competitive positioning within each hardware category.
- Blood Glucose Monitors:Electrochemical biosensor platforms with ISO 15197-compliant analytical tolerances dominate insulin-dependent patient workflows. Germany and Japan drive upgrade demand as tightened accuracy mandates obsolete legacy sensor architectures.
- Blood Pressure Monitors:Oscillometric cuff systems with arrhythmia detection algorithms are maturing around replacement cycles in United States home care protocols. Post-discharge cardiac monitoring prescriptions expand the addressable base beyond traditional clinical boundaries.
- Thermometers:Infrared temporal artery and tympanic membrane sensors with sub-0.2°C precision tolerances serve pediatric and geriatric populations.
- Pulse Oximeters:Photoplethysmography sensors with multi-wavelength LED arrays enable continuous SpO2 tracking. Medicare-reimbursed chronic care management programs in the United States accelerate multi-parameter home monitoring adoption.
- Nebulizers:Pneumatic and mesh atomization systems deliver bronchodilator therapies for COPD and asthma management in domestic settings.
Volume placements concentrate in blood glucose monitors; the faster expansion belongs to pulse oximeters.
Application:
Cost tier stratification separates premium connected platforms from economy standalone devices within each therapeutic area.
- Diabetes Management:Continuous glucose monitoring systems with factory-calibrated sensors eliminate fingerstick calibration burdens. Type 1 diabetes populations in reimbursement-cleared markets accelerate adoption of subscription-based sensor delivery models.
- Hypertension Monitoring:Ambulatory blood pressure devices with automated nocturnal measurement protocols support 30-day observation windows prescribed in United States post-discharge protocols.
- Respiratory Therapy:Nebulizer and peak flow meter combinations manage asthma and COPD exacerbations in pediatric and elderly home care settings.
- Cardiovascular Health:ECG-enabled wearables with AI arrhythmia detection expand into risk stratification applications previously confined to clinical settings.
- Fever Detection:Non-contact infrared thermometers serve infectious disease screening protocols in household and institutional environments.
Premium connectivity features concentrate in diabetes management; steepest expansion trajectory belongs to cardiovascular health applications.
End User:
Customer type determines interface complexity, training requirements, and support infrastructure investment levels.
- Home Care Users:Non-clinical operators require simplified interfaces and automated data transmission to electronic health record systems. Post-acute monitoring migration from hospitals to domestic environments compresses distribution channels and forces user-centered design priorities.
- Elderly Individuals:Large-format displays and voice-guided operation accommodate age-related sensory and cognitive variations.
- Fitness Enthusiasts:Wearable-integrated biometric tracking supports performance optimization and recovery monitoring.
- Chronic Disease Patients:Multi-parameter monitoring platforms serve comorbid populations with coordinated care team oversight.
- Caregivers:Remote monitoring dashboards enable proxy management of device operation and data interpretation for dependent patients.
Installed base concentrates among chronic disease patients; caregiver segments are climbing the fastest as informal care networks expand.
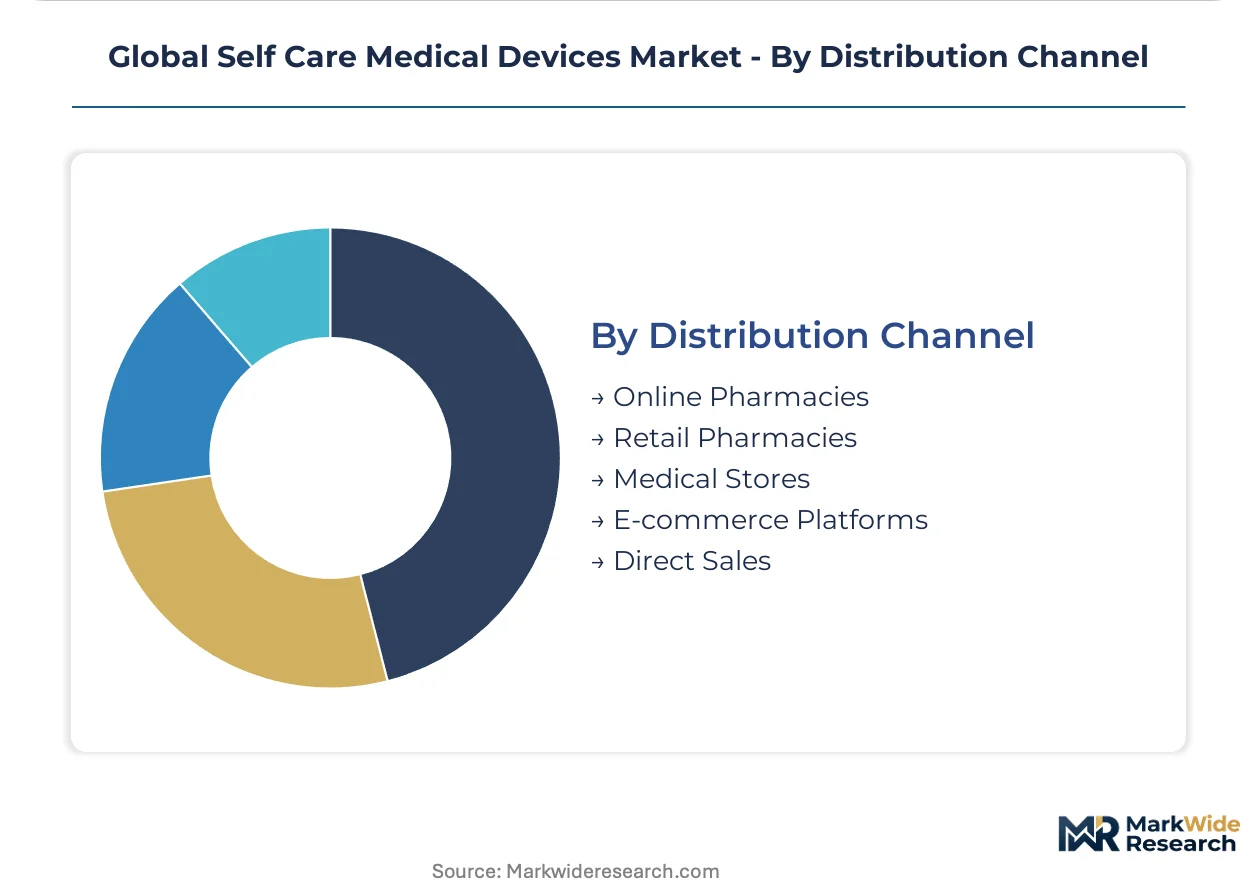
Distribution Channel:
Geographic concentration of channel infrastructure shapes manufacturer go-to-market economics and working capital requirements.
- Online Pharmacies:Prescription-integrated platforms with insurance eligibility verification serve reimbursed device categories. Direct-to-consumer subscription models for continuous glucose monitor sensors displace traditional pharmacy distribution in United States metropolitan markets.
- Retail Pharmacies:Point-of-sale counseling and immediate product availability support urgent diagnostic needs.
- Medical Stores:Durable medical equipment suppliers with technician support handle complex respiratory and mobility devices.
- E-commerce Platforms:Marketplace aggregation concentrates price comparison and review-driven purchase decisions for standardized devices.
- Direct Sales:Manufacturer-controlled channels capture recurring revenue streams and patient relationship data.
Transaction volume concentrates in retail pharmacies; digital channels are gaining share fastest as automated delivery models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate manufacturing for US-bound exports. Ireland's IDA-backed campuses attract FDA-registered production facilities. Singapore's Biopolis anchors Asia-Pacific regulatory convergence efforts.
United States
Medicare reimbursement clarity for remote patient monitoring accelerates home care device penetration among aging populations. FDA 510(k) clearance pathways for connected diagnostics now average 18-24 months, filtering smaller entrants. Minneapolis-St. Paul hosts Medtronic's vertically integrated sensor manufacturing operations serving continuous glucose monitoring supply chains.
Germany
Tightened ISO 15197 accuracy mandates for blood glucose monitors trigger replacement demand among insulin-dependent populations. EU MDR conformity assessments and notified body reviews tripled documentation costs since 2021. Tübingen and Freiburg clusters concentrate precision sensor engineering talent for next-generation diagnostic platforms.
Japan
Aging demographics and universal health coverage clarity drive premium device adoption in home care settings. PMDA imposes additional electromagnetic compatibility and biocompatibility testing layers beyond IEC baseline requirements. Tokyo-Osaka corridor hosts consolidated manufacturing for pulse oximeter exports across Asia-Pacific markets.
India
CDSCO fast-track pathways for low-risk diagnostic devices enable earlier market entry under production-linked incentive schemes. PLI scheme subsidies attract contract manufacturers establishing local glucose monitor and thermometer assembly. Gujarat and Karnataka industrial corridors concentrate medical electronics manufacturing for domestic and African export markets.
United Kingdom
NHS long-term plan commitments to hospital-at-home models expand post-discharge monitoring device prescriptions. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UKCA marking timelines. Cambridge-London corridor concentrates AI-enabled diagnostic algorithm development for cardiovascular risk stratification applications.
Global Self Care Medical Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium connected platforms consolidating around vertically integrated sensor producers while economy tiers fragment across Asian OEM assemblers. The vendor base stratifies into three tiers: multinational health technology conglomerates with regulatory affairs scale, mid-cap specialists with single-category depth, and emerging direct-to-consumer brands bypassing traditional pharmacy distribution. Dominant competitive moves include backward integration into biosensor fabrication and subscription-based sensor delivery models that capture recurring revenue streams.
Among diversified health technology conglomerates, Medtronic and Koninklijke Philips N.V. exemplify the vertically integrated archetype with captive manufacturing capabilities spanning sensor fabrication through final device assembly. Abbott Laboratories occupies a position within the factory-calibrated sensor tier, representing the shift toward reduced user calibration burdens. These three entities anchor the premium segment where regulatory clearance scale and reimbursement relationship depth create defensive positioning against direct-to-consumer entrants.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips N.V. |
| ResMed, Inc. |
| Abbott Laboratories |
| Johnson & Johnson |
| GE Healthcare |
| OMRON Healthcare, Inc. |
| DexCom, Inc. |
| Roche Pharmaceutical |
| Others |
Supply & Pricing Matrix
Biosensor electrode materials and microfluidic cartridge substrates flow from specialty chemical suppliers in Germany and Japan through contract manufacturers in Costa Rica and Puerto Rico, accumulating ISO 13485 compliance premiums at each tier before reaching FDA-cleared pricing brackets in United States distribution channels.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to continuous glucose monitor sensor orders placed outside contracted subscription windows, while spot inventory liquidation in e-commerce channels drives economy-tier pulse oximeter pricing downward. Three-tier pricing structure across premium, standard, and economy levels separates factory-calibrated CGM systems with automated data transmission from basic blood pressure monitors and non-connected thermometers. Pricing pressure stems from test strip commoditization in United States retail pharmacy chains, where private-label alternatives squeeze branded consumable margins. Home care users with chronic disease management needs show lowest price sensitivity due to reimbursement coverage, while fitness enthusiasts purchasing wearable-integrated devices demonstrate highest elasticity.
Supply Chain Analysis
ISO 13485 certification and FDA establishment registration requirements filter component suppliers to a qualified base concentrated in Germany, Japan, and the United States for precision sensor fabrication, with final assembly gravitating toward Costa Rica and Puerto Rico medical device special economic zones. Electrochemical biosensor electrodes, photoplethysmography LED arrays, and oscillometric pressure transducers constitute critical input dependencies. Single-source vulnerability concentrates in specialty polymer membranes for glucose test strips sourced from Japanese chemical conglomerates. Distribution runs through durable medical equipment suppliers for reimbursed respiratory devices, direct-to-consumer subscription platforms for CGM sensors, and retail pharmacy chains for standardized diagnostic tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-calibrated sensor architectures and AI-enabled arrhythmia detection algorithms are displacing legacy fingerstick-dependent glucose monitors and manual blood pressure cuffs across reimbursement-cleared markets, compressing upgrade cycles for incumbent hardware portfolios.
For Market Incumbents: Cement defensive positioning through backward integration into electrochemical biosensor fabrication and captive manufacturing of photoplethysmography sensor arrays, insulating margin pools from Asian OEM price competition. Prioritize ISO 14971 risk management documentation capabilities and FDA 510(k) clearance scale as barriers against direct-to-consumer entrants lacking regulatory affairs infrastructure. For New Entrants and Emerging Players: AI-enabled cardiovascular risk stratification algorithms embedded in blood pressure monitors offer a technology-first wedge into the Medicare-reimbursed remote patient monitoring channel, where interoperability requirements have filtered smaller hardware competitors. Target India's CDSCO fast-track pathway for low-risk diagnostic devices under PLI scheme manufacturing subsidies, leveraging streamlined approval timelines against entrenched European and North American competitors. Pursue hospital-at-home partnership models with United States health systems seeking post-discharge monitoring solutions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with single-category depth in continuous glucose monitoring or sleep apnea therapy platforms, particularly those with established reimbursement codes in Germany and Japan. Long-term viability hinges on algorithmic differentiation and recurring revenue attachment rates rather than hardware shipment volumes. Watch for FDA de novo classification decisions on photoplethysmography-based blood pressure estimation as inflection indicators for wearable-integrated diagnostic platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for connected diagnostics in United States reimbursement channels. |
| CE Marking Pathway | Unlocks EU MDR-compliant access to German and United Kingdom hospital-at-home procurement. |
| Hospital System Partnership | Secures Epic and Cerner EHR interoperability certifications for post-discharge monitoring protocols. |
| Software Companion Development | Enables automated data transmission to clinicians under Medicare chronic care management billing codes. |
| Reimbursement Strategy | Positions factory-calibrated CGM sensors for pharmacy benefit manager formulary inclusion. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU MDR technical documentation guidance, and ISO 15197 analytical performance standards, complemented by interviews with regulatory affairs directors at continuous glucose monitor manufacturers, biomedical engineers at United States hospital systems, GPO contracts managers, and pharmacy benefit manager formulary directors. Secondary validation drew from CMS Medicare reimbursement bulletins, PMDA electromagnetic compatibility testing protocols, and CDSCO fast-track approval guidelines. Bottom-up segment sizing triangulated against top-down macroeconomic healthcare expenditure models.
Cross-referencing historical sensor shipment patterns against clinician panel input on post-discharge monitoring protocol adoption shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user archetype, and distribution channel, with particular attention to reimbursement eligibility tier and connectivity feature bundling. CAGRs were derived from regression analysis of replacement cycle compression and consumable attachment rate trajectories, incorporating insulin-dependent population demographics and ambulatory blood pressure monitoring prescription expansion as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt FDA guidance revisions on software-as-a-medical-device classification, EU MDR notified body capacity constraints extending beyond current audit queues, and tariff disruptions affecting Costa Rica and Puerto Rico medical device export zones. Forecasts reflect assumptions regarding reimbursement code stability and ISO standard continuity. A model refresh is warranted upon material change in Medicare remote patient monitoring billing code valuations or PMDA biocompatibility testing requirement expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Cervical Fusion Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Patient Lift Slings Market