
 Global Sacral Nerve Stimulation Market | 2026-2036
Global Sacral Nerve Stimulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sacral Nerve Stimulation Market Foresight
Multi-source component procurement is decoupling from legacy single-vendor dependencies across the sacral nerve stimulation supply chain. Medtronic plc leverages its vertically integrated manufacturing footprint to sustain lead production in-house. Boston Scientific Corporation anchors its competitive stance through specialized rechargeable IPG development. Axonics Inc. differentiates via extended-interval recharge technology that reduces patient maintenance burden.
Sacral nerve stimulation employs implantable pulse generators delivering low-frequency electrical impulses to the S3 spinal nerve root via tined leads, modulating afferent pathways to restore bladder and bowel function. The system operates through closed-loop feedback between the implanted device and target neural tissue, requiring precise lead placement during fluoroscopy-guided surgical intervention. Implantable pulse generators command the dominant value share within product type segmentation, while rechargeable systems outpace conventional battery-dependent platforms in technology category growth. Urinary incontinence applications retain the largest patient addressable base, though chronic pelvic pain represents the fastest-expanding indication as diagnostic criteria standardize across specialized clinics.
FDA premarket notification pathways and EU MDR conformity assessment procedures govern device commercialization, with HIPAA and GDPR imposing parallel data governance obligations on remote monitoring ecosystems. The EU AI Act introduces emerging scrutiny for algorithm-driven stimulation optimization features. Stakeholders must monitor evolving reimbursement coding decisions by CMS and national health technology assessment bodies as procedure volume thresholds shift toward ambulatory surgery center settings.
Market Dynamics
Rechargeable implantable pulse generators are compressing replacement cycles and forcing incumbents to defend installed bases against extended-interval competitors. This technological inflection is redistributing value capture from hardware sales toward long-term service contracts and remote monitoring ecosystems.
Growth Catalysts
- FDA Breakthrough Device Pathway:Streamlined premarket review timelines accelerate commercialization for novel neuromodulation platforms targeting refractory overactive bladder.
- Japan's Aging Demographics:PMDA reimbursement approvals for sacral nerve stimulation in elderly populations expand addressable procedure volumes in Tokyo and Osaka metropolitan clusters.
- Closed-Loop Feedback Algorithms:AI-driven stimulation optimization reduces manual programming burden and improves therapeutic consistency across urology clinic networks.
Market Restraints
- Implantable Pulse Generator Cost Concentration:Single-source dependencies for lithium-ion cell supply create input cost volatility and procurement risk.
- EU MDR Conformity Assessment:Extended clinical evidence requirements and notified body capacity constraints delay CE marking timelines for rechargeable systems.
- Sacral Lead Revision Surgery Burden:Tined lead migration rates necessitate costly reintervention, limiting patient lifetime value and payer willingness to expand coverage.
Strategic Opportunities
- Chronic Pelvic Pain Indication:Diagnostic criteria standardization across German and United States specialized clinics opens new reimbursement codes for previously off-label applications.
- Ambulatory Surgery Center Migration:CMS site-of-service differential payments incentivize procedure volume shift away from hospital outpatient departments.
- Bluetooth Low Energy Integration:Wireless patient programmer connectivity enables real-time adherence monitoring and predictive maintenance revenue streams.
Industry Challenges
- Electrophysiology Specialist Shortage:Limited fellowship-trained implanters constrain procedure throughput in secondary United States markets and Japanese prefectures.
- Cross-Border Data Governance:HIPAA-GDPR divergence complicates remote monitoring platform architecture for multinational device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sacral Nerve Stimulation Market |
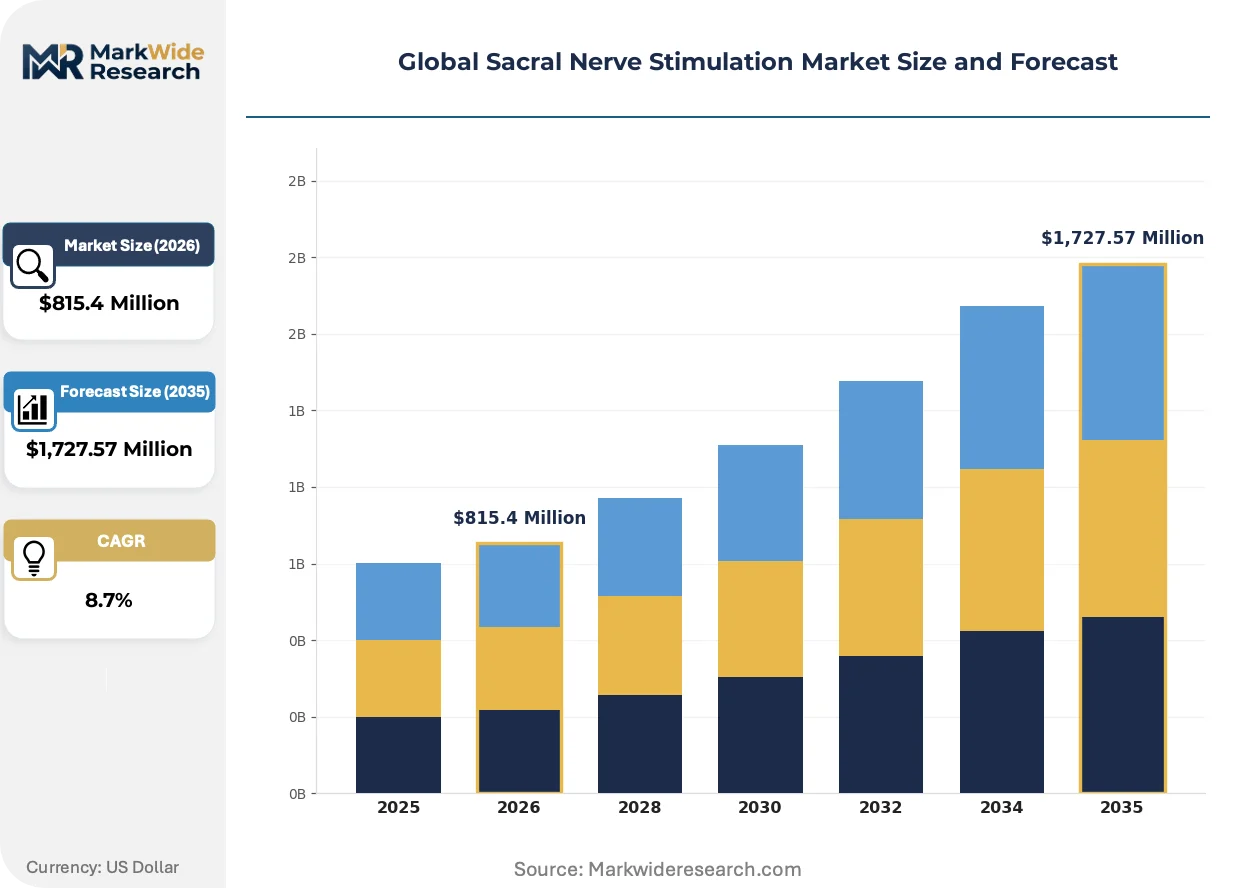
| Market Size in 2026 | $815.4 Million |
| Market Size in 2035 | $1,727.57 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Pulse Generators, Leads, Extensions, Rechargeable Devices Application: Urinary Incontinence, Fecal Incontinence, Chronic Pelvic Pain, Overactive Bladder End User: Hospitals, Ambulatory Surgery Centers, Specialized Clinics, Rehabilitation Centers Technology: InterStim, Axonics Modulation, Wireless Stimulation, Rechargeable Systems |
| Companies Covered | Nevro Corp, Laborie Medical Technologies, Medtronic plc, Abbott Laboratories, Neuspera Medical, Boston Scientific Corporation, Nuvectra Corp, StimWave Technologies Inc., Axonics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sacral Nerve Stimulation Market Shifts & Advancements
Extended battery longevity and algorithmic personalization are compressing the traditional replacement-revenue model while elevating software and service components in vendor value propositions.
Rechargeable lithium-ion cell technology is absorbing the functional burden previously assigned to primary cell systems. Urology clinics in Germany and the United States are adopting these platforms at accelerating pace as reimbursement frameworks adjust to longer replacement intervals. The technology is absorbing service contract value from hardware margins, forcing vendors to restructure revenue recognition around remote monitoring subscriptions.
EU MDR post-market surveillance requirements are intensifying clinical follow-up obligations for implantable neuromodulation devices. Manufacturers must now maintain systematic registries capturing long-term safety and performance data across diverse patient cohorts. Rechargeable system categories face disproportionate scrutiny due to their complex electronics and wireless communication modules, prompting accelerated investment in cybersecurity validation.
Patient self-management expectations are elevating demand for smartphone-integrated programming interfaces. Traditional handheld patient programmers are losing preference share among younger demographics and digitally engaged cohorts. This behavioral pivot is most pronounced in United States metropolitan markets where consumer technology familiarity intersects with higher procedure volumes.
Global Sacral Nerve Stimulation Market Segmentation
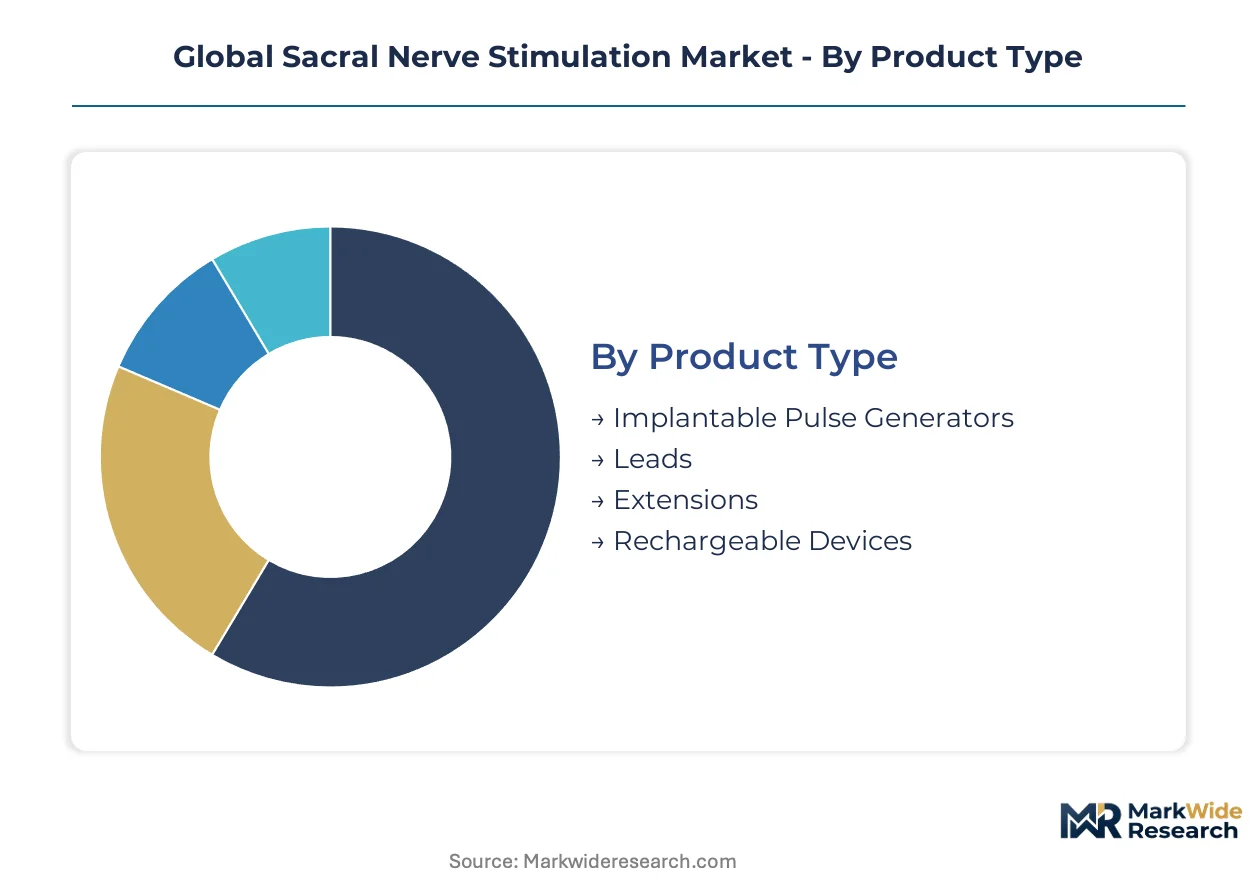
Segmentation in sacral nerve stimulation reveals distinct procurement patterns across hardware categories and care settings. Rechargeable technology diffusion and site-of-service migration are reshaping vendor-customer relationships across each dimension.
Product Type:
Procurement decisions center on lifetime cost of ownership rather than upfront capital expenditure, particularly as rechargeable platforms extend replacement intervals.
- Implantable Pulse Generators:These sealed titanium-cased units house lithium-ion cells, microprocessors, and telemetry circuits that deliver programmable electrical impulses to sacral nerve roots. Demand concentrates in United States academic medical centers where bundled payment contracts favor devices with 15-year longevity projections. Payer pressure on replacement frequency is accelerating procurement shifts toward rechargeable architectures.
- Rechargeable Devices:Systems incorporating inductive charging coils and higher-density power cells reduce surgical revision burden through extended functional lifespan. German urology clinics in Munich and Hamburg are prioritizing these platforms under DRG reimbursement frameworks that penalize reintervention costs. Patient adherence to charging protocols remains the primary adoption constraint outside metropolitan markets.
- Leads:Quadripolar tined electrodes with fluoroscopic placement markers anchor neural interface functionality.
- Extensions:Subcutaneous cable assemblies connect leads to pulse generators with strain-relief engineering.
Implantable Pulse Generators lead on scale; Rechargeable Devices lead on momentum.
Application:
Diagnostic coding specificity determines reimbursement eligibility and thus addressable patient populations across each indication.
- Urinary Incontinence:Stress and urge incontinence variants constitute the largest patient pool with established CPT coding and commercial payer coverage. Japanese prefectures with aging demographics in Kanto and Kansai regions are expanding screening programs that feed diagnostic pipelines. Outcome variability in mixed incontinence subtypes limits expansion into conservative therapy failure populations.
- Chronic Pelvic Pain:Interstitial cystitis and pudendal neuralgia applications are gaining procedure volume as diagnostic criteria standardize across specialized United States clinics in Boston and Philadelphia. Prior authorization requirements remain heterogeneous across commercial payers, constraining predictable revenue recognition for implanting physicians.
- Fecal Incontinence:Sphincter dysfunction and rectal hypersensitivity indications follow urinary applications in regulatory approval sequencing.
- Overactive Bladder:Urgency-frequency syndrome with or without incontinence represents the gateway indication for neuromodulation candidacy.
Urinary Incontinence dominates procedure volume; Chronic Pelvic Pain is climbing the fastest.
End User:
Site-of-service economics and implanting physician availability segment demand across care delivery settings.
- Ambulatory Surgery Centers:Freestanding facilities with dedicated pain management or urology service lines capture favorable CMS site-of-service differential payments. United States markets in Texas and Florida are seeing fastest volume migration as certificate-of-need restrictions ease. Capital equipment requirements and emergency backup protocols limit penetration in smaller metropolitan statistical areas.
- Specialized Clinics:Urogynecology and neurourology focused practices in Germany's university hospital networks concentrate high-complexity cases and training functions. Referral pattern consolidation around these centers is compressing procedure volume in community hospital settings.
- Hospitals:Inpatient and hospital outpatient departments retain complex revision and infection management cases.
- Rehabilitation Centers:Post-implant programming and parameter optimization services extend care continuum engagement.
Ambulatory Surgery Centers gain share fastest; Specialized Clinics retain margin premium.
Technology:
Intellectual property positioning and wireless communication capabilities differentiate competitive platforms.
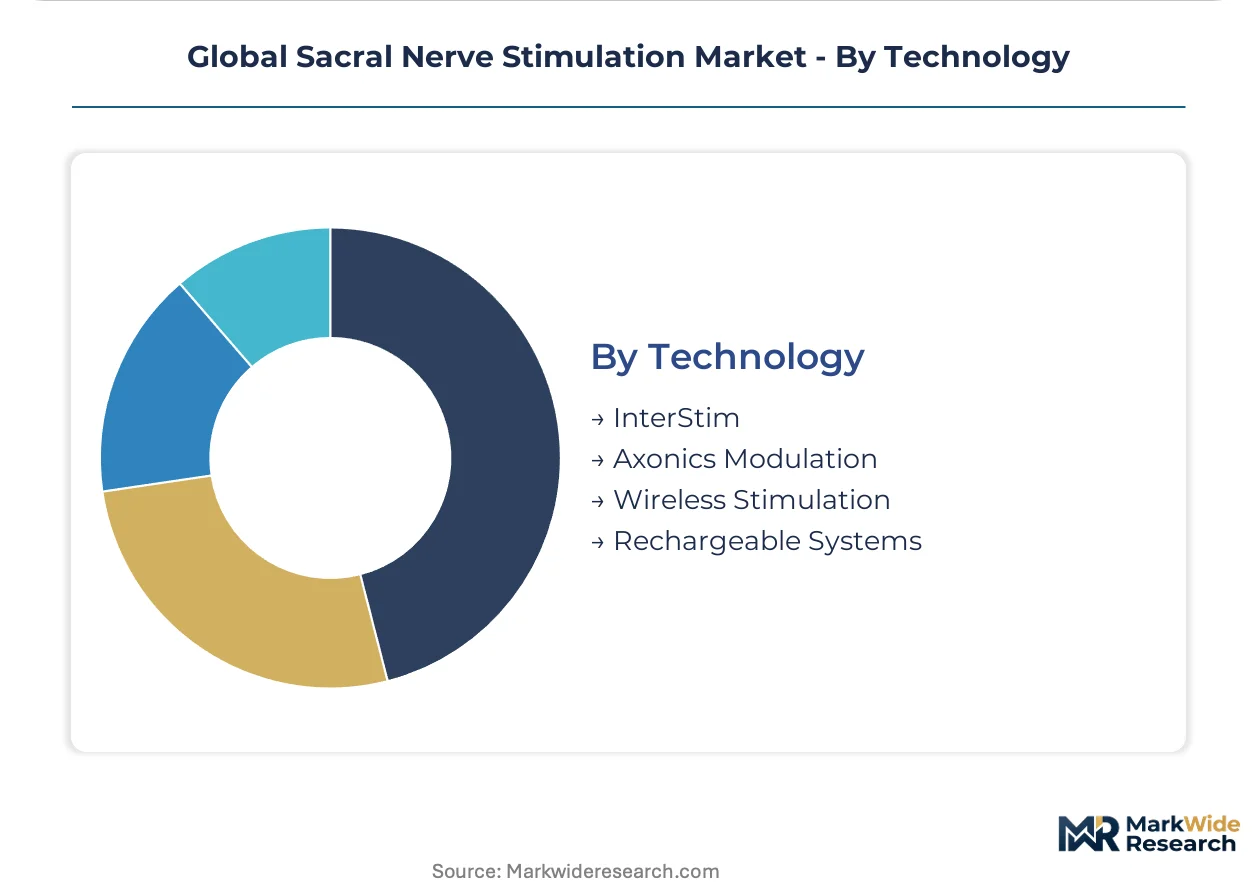
- InterStim:Medtronic's proprietary waveform algorithms and lead designs established foundational sacral neuromodulation protocols with extensive long-term safety registries. United States installed base concentration creates switching costs for competing platforms seeking market entry. Legacy primary cell dependence in historical implants creates replacement revenue exposure to rechargeable competitors.
- Axonics Modulation:Extended-interval rechargeable architecture with Bluetooth Low Energy patient programmer connectivity targets maintenance burden reduction. Japanese PMDA approval pathways are prioritizing these systems for elderly populations with transportation limitations to programming visits.
- Wireless Stimulation:Leadless or externally powered systems eliminate implantable power source requirements.
- Rechargeable Systems:Category-spanning technology platform across multiple proprietary implementations.
InterStim leads on scale; Axonics Modulation leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis metropolitan cluster anchors procedure volume concentration for sacral neuromodulation, driven by academic medical center density and bundled payment contract innovation.
United States
Aging demographics in Florida and Arizona expand screening pipelines for refractory overactive bladder. FDA breakthrough device pathways accelerate premarket review timelines for rechargeable implantable systems. Texas ambulatory surgery centers capture favorable CMS site-of-service differentials, shifting volume from hospital outpatient departments.
Germany
DRG reimbursement frameworks in Bavaria and North Rhine-Westphalia penalize reintervention costs, prioritizing extended-interval rechargeable platforms. EU MDR conformity assessment procedures impose extended clinical evidence requirements on notified bodies. Munich and Hamburg urology clinics concentrate high-complexity cases and training functions under university hospital networks.
Japan
PMDA reimbursement approvals for elderly populations expand addressable procedure volumes in Tokyo and Osaka metropolitan clusters. METI industrial policy supports domestic manufacturing capacity for implantable medical devices. Kanto region screening programs feed diagnostic pipelines for urgency-frequency syndrome with transportation-limited follow-up.
United Kingdom
NICE technology appraisal pathways determine National Health Service commissioning for sacral nerve stimulation in chronic pelvic pain applications. MHRA post-market surveillance requirements align with EU MDR transition timelines for legacy device registrations. London and Southeast England specialist centers consolidate referral patterns for interstitial cystitis and pudendal neuralgia.
Australia
TGA approval pathways for rechargeable neuromodulation systems align with FDA precedent for streamlined market entry. Medicare Benefits Schedule item numbers support procedure reimbursement in private hospital settings. New South Wales and Victoria metropolitan clusters concentrate implanter training capacity and patient programming services.
Global Sacral Nerve Stimulation Market Competitive Landscape
Global majors compete with regional champions across regulatory approval velocity and rechargeable technology development. The vendor base stratifies between vertically integrated conglomerates with in-house manufacturing footprints and specialized neuromodulation developers with focused IP portfolios. Three archetypes dominate: diversified medical technology conglomerates with broad therapy portfolios, pure-play neuromodulation specialists with waveform algorithm differentiation, and emerging wireless stimulation developers eliminating implantable power sources. Competitive moves concentrate on M&A for rechargeable IP assets and strategic partnerships for Bluetooth Low Energy ecosystem integration.
Within the diversified conglomerate tier, Medtronic plc and Abbott Laboratories occupy positions sustained by vertically integrated manufacturing and extensive long-term safety registries. Boston Scientific Corporation anchors the specialized rechargeable segment through proprietary IPG development. Among pure-play neuromodulation developers, Axonics Inc. exemplifies extended-interval architecture targeting maintenance burden reduction, while Nevro Corp represents spinal cord stimulation expertise with transferable waveform optimization capabilities.
| Leading Market Players |
|---|
| Nevro Corp |
| Laborie Medical Technologies |
| Medtronic plc |
| Abbott Laboratories |
| Neuspera Medical |
| Boston Scientific Corporation |
| Nuvectra Corp |
| StimWave Technologies Inc. |
| Axonics Inc. |
| Others |
Supply & Pricing Matrix
Rechargeable lithium-ion cell migration toward extended-interval architectures simultaneously compresses per-procedure hardware margins and concentrates procurement leverage among buyers with volume scale. This technological transition feeds back into supplier consolidation as tier-one medical device manufacturers internalize power electronics production to defend margin capture against contract manufacturers.
Pricing Analysis
Input-cost pass-through from lithium-ion cell volatility shapes contract structures across implantable pulse generator procurement. Three-tier pricing structure across premium, standard, and economy levels segments by longevity projection and wireless telemetry capability, with FDA breakthrough-designated platforms commanding brand premiums. Pricing pressure stems from ambulatory surgery center purchasing coalitions aggregating volume for standardized rechargeable systems. Community hospital outpatient departments exhibit highest price sensitivity due to constrained capital budgets; academic medical centers with bundled payment contracts demonstrate lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean lithium-ion cell suppliers feeding implantable medical device manufacturing. Raw material dependencies span cobalt hydroxide, medical-grade titanium, and biocompatible silicone elastomers. Supply chain risk centers on tariff exposure affecting cross-border component flows between Asia-Pacific production hubs and United States assembly facilities. Distribution runs through specialized medical device distributors with GPO contracting relationships, bypassing generalist healthcare supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA breakthrough device designations and PMDA reimbursement approvals compound procedure volume acceleration. EU MDR conformity assessment timelines represent the pivotal regulatory milestone compressing competitive entry windows.
For Market Incumbents: Hedge rechargeable platform exposure by accelerating in-house lithium-ion cell qualification programs to reduce single-source dependencies. Secure ambulatory surgery center GPO contracts before site-of-service migration completes, as hospital outpatient department volume erosion threatens installed base maintenance. Prioritize cybersecurity validation investments to preempt EU MDR post-market surveillance scrutiny on wireless communication modules.
For New Entrants and Emerging Players: Algorithm-driven stimulation optimization offers the most penetrable wedge against legacy waveform platforms with manual programming burdens. Chronic pelvic pain applications in German and United States specialized clinics present undercoded reimbursement white space with less entrenched incumbent relationships. Pursue hospital system partnership models with shared risk contracting to bypass capital equipment procurement barriers.
For Investors and Strategic Acquirers: Roll-up economics work for pure-play neuromodulation specialists with rechargeable IP portfolios because FDA approval velocity advantages compound against diversified conglomerates with slower platform refresh cycles. Long-term viability favors targets with Bluetooth Low Energy ecosystem integration and algorithmic personalization roadmaps. Watch CMS site-of-service differential payment recalibration as the inflection signal for ambulatory surgery center volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses time-to-revenue for rechargeable neuromodulation platforms. |
| CE Marking Pathway Under EU MDR | Extended clinical evidence requirements favor incumbents with systematic safety registries. |
| Hospital System Partnership | Bundled payment contracts with academic medical centers lock in longitudinal patient capture. |
| Software Companion Development | Smartphone-integrated programming interfaces differentiate against legacy handheld patient programmers. |
| Reimbursement Strategy | Prior authorization pathway optimization for chronic pelvic pain expands addressable patient populations. |
Research Methodology
Bottom-up urology clinic procedure modeling reconciled against top-down implantable pulse generator shipment tracking forms the analytical core. Primary interviews with sacral neuromodulation implanters, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers combine with secondary validation against FDA 510(k) filings, PMDA approval databases, CMS Medicare procedure data, and EU MDR notified body certificates. Triangulation between demand-side clinical adoption patterns and supply-side manufacturing output ensures statistical integrity.
Input-output matrix framing connects rechargeable system adoption rates to replacement cycle compression effects across product type segmentation. The analytical framework models implantable pulse generators, leads, and patient programmers by application indication, end-user setting, and proprietary technology platform across the projection horizon. CAGRs derive from logistic diffusion curves fitted to historical procedure volume trajectories, incorporating aging demographic elasticity and reimbursement policy shift scenarios. Forecast inputs include lithium-ion cell cost curves and ambulatory surgery center site-of-service migration rates.
The model holds under stable regulatory approval timelines and reimbursement code maintenance; deviation in FDA breakthrough pathway congestion or CMS site-of-service differential recalibration would shift volume trajectories. Forecasts reflect documented assumptions regarding patient adherence to rechargeable protocols and implanter training pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Capsule Endoscope and Workstations Market
Medical Devices
Respiratory Devices Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
ADA Substitute Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Global Ileostomy Market
Medical Devices
US C-Arms Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
Extremity Tissue Expanders Market
Medical Devices
Digital Intraoral Camera Market