
 Uterine Fibroid Treatment Device Market | 2026-2036
Uterine Fibroid Treatment Device Market Size, Share, and Industry Trends Forecast 2026-2036
Uterine Fibroid Treatment Device Market Intelligence
Ambulatory surgical centers are reorganizing procurement patterns for uterine fibroid treatment devices, displacing traditional hospital purchasing dominance. Insightec leverages its focused ultrasound platform to sustain technology leadership in non-invasive myoma ablation. Medtronic anchors its position through broad laparoscopic and energy-based surgical portfolios. Gynesonics specializes in transcervical radiofrequency technology, differentiating its approach from conventional hysteroscopic systems.
Uterine fibroid treatment devices encompass instruments and energy-delivery systems designed to ablate, resect, or devascularize leiomyomas while preserving uterine anatomy, typically operating at radiofrequency ranges of 460–500 kHz or high-intensity focused ultrasound frequencies above 1 MHz for thermal tissue destruction. These devices serve the primary commercial purpose of reducing heavy menstrual bleeding, pelvic pressure, and reproductive complications without hysterectomy. Radiofrequency devices capture expanding margin pools as outpatient adoption accelerates, while ultrasound devices occupy the premium segment due to capital intensity and specialized training requirements. Laparoscopic devices retain volume leadership in therapeutic intervention applications across hospital settings.
FDA 510(k) and premarket approval pathways govern device commercialization in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for thermal ablation and interventional radiology systems entering European markets. The EPA and OSHA frameworks indirectly shape manufacturing standards for device sterilization and workplace exposure controls in production facilities. Stakeholders must monitor reimbursement coding decisions for focused ultrasound procedures and evolving MDR technical documentation requirements to align portfolio investments with accessible market segments.
Market Dynamics
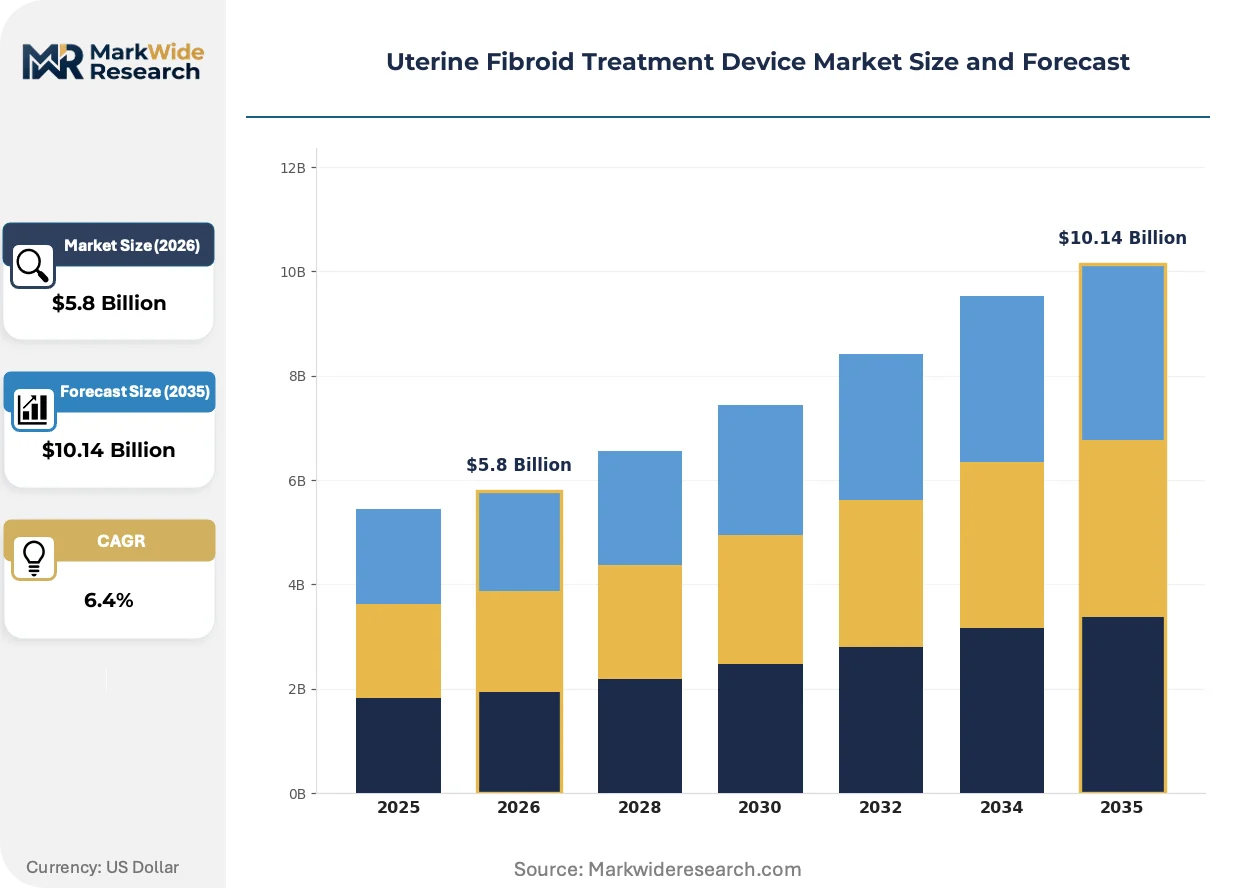
Ambulatory surgical centers are dismantling hospital procurement monopolies for uterine fibroid treatment devices, redirecting capital flows toward outpatient-compatible radiofrequency and focused ultrasound platforms that align with expanded commercial payer coverage for same-day procedures.
Growth Catalysts
- FDA 510(k) Pathway:Streamlined clearance for radiofrequency ablation devices accelerates commercialization timelines for manufacturers targeting outpatient settings.
- Ambulatory Surgical Centers:These facilities now drive device selection criteria, favoring compact, portable systems over capital-intensive installed-base equipment.
- Commercial Payer Expansion:United States insurers have broadened reimbursement for outpatient uterine fibroid procedures, reducing patient cost barriers.
Market Restraints
- Capital Intensity:High-intensity focused ultrasound systems require substantial upfront investment, limiting adoption to well-capitalized health systems.
- Specialized Training Requirements:Sonography expertise and MRI coordination create operational bottlenecks that constrain deployment velocity.
- Reimbursement Coding Lag:Delayed CPT code updates for novel ablation modalities create payment uncertainty for providers.
Strategic Opportunities
- Underpenetrated Rural Markets:United States regions with limited access to academic medical centers present demand for mobile or compact ablation technologies.
- EU MDR Alignment:Early compliance with enhanced clinical evidence requirements positions vendors for accelerated European market entry post-certification.
- Hybrid Laparoscopic-Radiofrequency Convergence:Integration of visualization and energy delivery in single platforms addresses surgeon workflow preferences.
Industry Challenges
- Interventional Radiology Talent Pipeline:Shortage of physicians trained in MRI-guided focused ultrasound limits service expansion.
- Legacy Hysteroscopic System Integration:Hospitals face capital write-down pressures when transitioning to transcervical radiofrequency platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uterine Fibroid Treatment Device Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Devices, Hysteroscopic Devices, Laparoscopic Devices, Radiofrequency Devices End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Specialty Clinics Technology: Minimally Invasive Surgery, Imaging Techniques, Thermal Ablation, Interventional Radiology Application: Symptom Management, Therapeutic Intervention, Emergency Treatment, Patient Monitoring |
| Companies Covered | Hologic, Inc., Insightec, Medtronic, CONMED Corporation, Gynesonics, Boston Scientific Corporation, CooperSurgical Inc., Johnson & Johnson (Ethicon), Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uterine Fibroid Treatment Device Market Strategic Shifts & Innovations
Device architecture is pivoting toward modularity and portability, reflecting ambulatory site demands while thermal ablation modalities compete for clinical evidence superiority in fertility preservation outcomes.
Radiofrequency ablation technology is decomposing the traditional hysterectomy referral pathway by enabling office-based myoma treatment without general anesthesia. Gynecology practices in the United States are adopting these systems at accelerating velocity. The technology is decomposing hospital-based surgical volume into distributed outpatient settings.
EU MDR technical documentation requirements for thermal ablation systems now mandate extended clinical follow-up data, extending certification timelines. Manufacturers must invest in post-market surveillance infrastructure to maintain conformity. Class III device categories face the steepest compliance burden, with smaller vendors exiting rather than absorbing regulatory costs.
Site-of-care economics now dominate capital allocation decisions, with ambulatory surgical centers negotiating direct procurement relationships that bypass hospital supply chain intermediaries. Device vendors are restructuring sales organizations to support this channel. The United States exhibits the most pronounced shift, where payer incentives align with outpatient migration.
Uterine Fibroid Treatment Device Market Segmentation
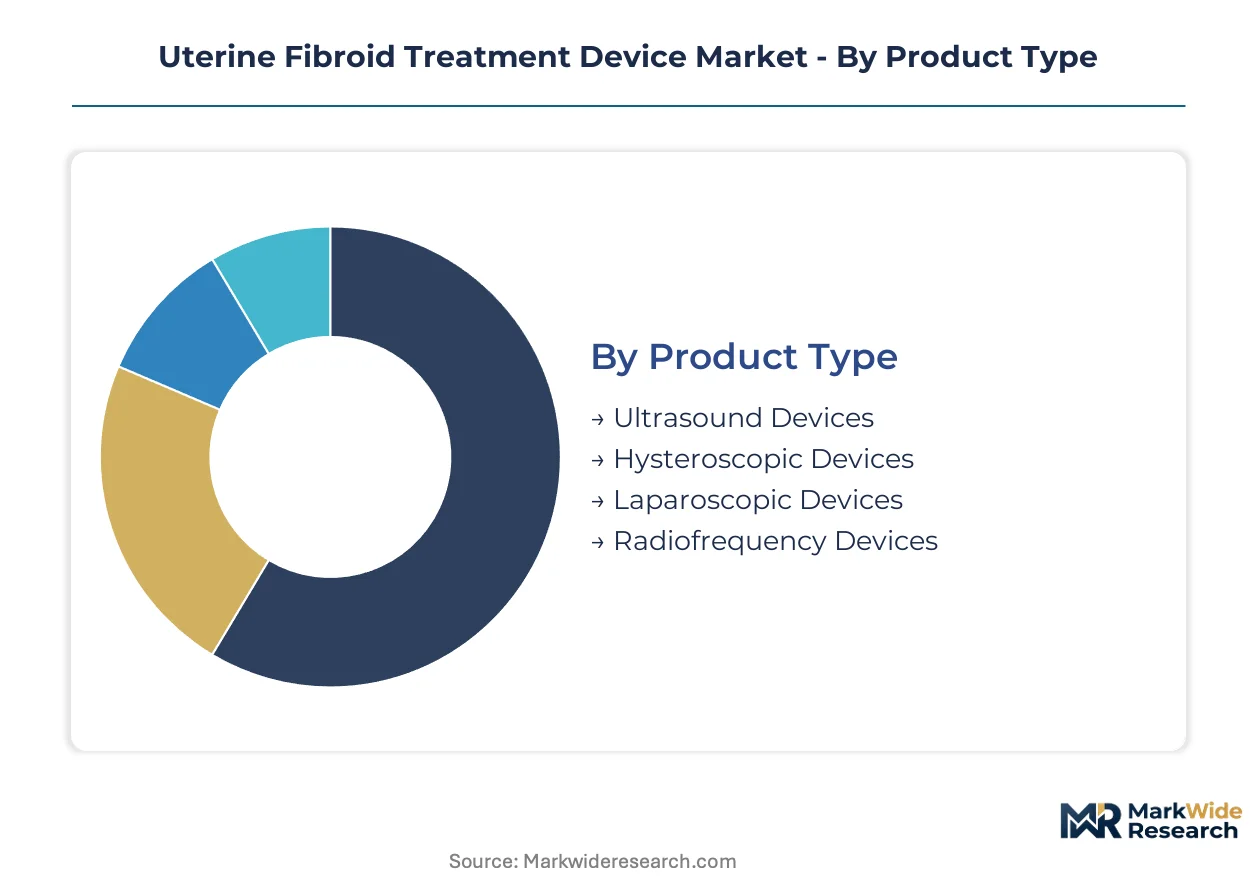
Device segmentation in uterine fibroid treatment reveals divergent margin profiles and capital requirements across product architectures. Channel economics and site-of-care migration reshape which segments command procurement priority.
Product Type:
Ultrasound devices flow through academic medical center capital budgets, while radiofrequency platforms penetrate ambulatory surgical center procurement directly.
- Ultrasound Devices:High-intensity focused ultrasound systems operate above 1 MHz for thermal tissue destruction, requiring MRI coordination and specialized sonography expertise. Demand concentrates in well-capitalized United States health systems where commercial payer coverage for outpatient procedures has expanded, though capital intensity limits deployment velocity.
- Radiofrequency Devices:Systems operating at 460–500 kHz deliver controlled thermal ablation through transcervical or laparoscopic access. Ambulatory surgical centers in the United States are driving procurement of compact, portable configurations that bypass hospital supply chain intermediaries.
- Hysteroscopic Devices:Traditional resection systems face capital write-down pressures as facilities transition to transcervical radiofrequency platforms.
- Laparoscopic Devices:Energy-based surgical portfolios retain volume leadership across hospital settings for therapeutic intervention applications.
Laparoscopic devices dominate installed base. Radiofrequency devices are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive hospital installations from margin-accretive ambulatory deployments.
- Hospitals:Traditional procurement monopolies for uterine fibroid treatment devices face displacement as capital flows redirect toward outpatient-compatible platforms.
- Ambulatory Surgical Centers:These facilities now negotiate direct procurement relationships, favoring compact systems with streamlined sterilization protocols and same-day discharge economics.
- Outpatient Clinics:Office-based myoma treatment without general anesthesia is decomposing hospital-based surgical volume into distributed settings.
- Specialty Clinics:Gynecology practices in the United States are adopting radiofrequency systems at accelerating velocity for fertility-preserving interventions.
Hospitals retain the deepest installed base. Ambulatory surgical centers are climbing the fastest.
Technology:
Application intensity varies across fertility preservation outcomes and emergency intervention requirements.
- Minimally Invasive Surgery:Laparoscopic and transcervical approaches reduce recovery time and preserve uterine anatomy. United States gynecology practices are migrating toward these modalities as standard of care for symptomatic leiomyomas.
- Thermal Ablation:Radiofrequency and focused ultrasound modalities compete for clinical evidence superiority in fertility preservation outcomes. EU MDR technical documentation requirements now mandate extended clinical follow-up data for these systems.
- Imaging Techniques:MRI guidance and real-time sonography create operational bottlenecks that constrain deployment velocity for high-intensity focused ultrasound.
- Interventional Radiology:MRI-guided procedures face talent pipeline constraints as shortage of trained physicians limits service expansion.
Minimally invasive surgery commands the broadest indication set. Thermal ablation is gaining share fastest in outpatient settings.
Application:
Volume concentration aligns with chronic condition management rather than acute intervention.
- Therapeutic Intervention:Definitive myoma ablation and resection procedures represent the core revenue pool, with radiofrequency platforms capturing expanding margin pools.
- Symptom Management:Heavy menstrual bleeding and pelvic pressure reduction drive initial patient presentation and device selection criteria.
- Patient Monitoring:Post-ablation follow-up protocols influence device design for durable treatment effect verification.
- Emergency Treatment:Acute hemorrhage or torsion events require immediate surgical intervention, typically routing through hospital emergency departments.
Therapeutic intervention anchors commercial volume. Symptom management is where patient demand initiation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in the United States, Germany, and Japan, where specialized medical technology ecosystems support precision energy-delivery system production. Commercial demand spreads across ambulatory surgical centers in North America, Western Europe, and select Asia-Pacific markets. Regulatory pathway efficiency varies sharply by jurisdiction, shaping where new ablation platforms launch first.
United States
FDA 510(k) clearance velocity attracts manufacturers seeking rapid commercialization for radiofrequency and focused ultrasound platforms. Commercial payer expansion for outpatient uterine fibroid procedures has redirected capital flows toward ambulatory surgical centers in Texas, Florida, and California. The Minneapolis-St. Paul corridor hosts energy-based surgical device engineering clusters serving both hospital and outpatient procurement channels.
Germany
EU MDR technical documentation requirements for thermal ablation systems mandate extended clinical follow-up data, extending certification timelines for manufacturers targeting European market entry. Baden-Württemberg's precision engineering base supplies components for minimally invasive surgical instruments. Stuttgart-area fabricators specialize in radiofrequency generator modules and laparoscopic instrument assemblies.
Japan
PMDA consultation pathways for novel thermal ablation devices emphasize clinical evidence standards for fertility preservation outcomes. Tokyo-Osaka medical device distribution networks prioritize compact, portable systems suitable for outpatient clinic deployment. Kanagawa Prefecture manufacturers supply high-frequency electrosurgical components to domestic and export markets.
United Kingdom
NICE technology appraisal processes for uterine fibroid interventions influence NHS procurement decisions and private payer coverage policies. London and Southeast England concentrate gynecology specialist practices adopting transcervical radiofrequency platforms. Midlands manufacturing facilities produce hysteroscopic instrument systems for European distribution.
China
NMPA innovation pathway designations for minimally invasive surgical devices accelerate review timelines for domestic manufacturers. Yangtze River Delta medical technology clusters in Shanghai and Jiangsu Province assemble laparoscopic energy systems for hospital procurement. Shenzhen-based developers focus on cost-optimized radiofrequency platforms targeting tier-two city hospital networks.
Uterine Fibroid Treatment Device Market Key Industry Players
Concentration sits with diversified medical technology conglomerates and specialized women's health device developers. The competitive structure spans three tiers: capital-intensive imaging-guided therapy platforms, mid-scale radiofrequency ablation specialists, and broad surgical portfolio providers. Strategic moves center on ambulatory site-of-care channel restructuring and EU MDR compliance infrastructure investment.
Within the specialized ablation technology tier, Insightec and Gynesonics exemplify divergent platform approaches—one anchored in non-invasive focused ultrasound architecture, the other in transcervical radiofrequency delivery. Medtronic occupies a position across multiple intervention modalities through its laparoscopic and energy-based surgical portfolios. These three entities represent distinct competitive archetypes: MRI-guided non-invasive systems, office-based transcervical platforms, and integrated surgical workflow solutions.
| Leading Market Players |
|---|
| Hologic, Inc. |
| Insightec |
| Medtronic |
| CONMED Corporation |
| Gynesonics |
| Boston Scientific Corporation |
| CooperSurgical Inc. |
| Johnson & Johnson (Ethicon) |
| Stryker |
| Others |
Cost & Logistics Intelligence
Transcervical radiofrequency platforms displacing hysteroscopic resection systems are redrawing procurement geography toward ambulatory surgical centers while compressing capital equipment pricing tiers and elevating disposable component premiums.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across device categories, with premarket approval pathways commanding premium positioning against streamlined 510(k) equivalents. Price differentiation rests on MRI compatibility certification and ambulatory portability ratings, with hospital-anchored systems facing steeper discount pressure from GPO consolidation than office-based configurations. Cost compression in the hysteroscopic segment is intensifying as facilities accelerate write-downs of legacy installed bases. Ambulatory surgical centers exhibit the highest price elasticity, while academic medical centers maintain lowest sensitivity due to research funding offsets.
Supply Chain Analysis
Strait of Malacca transit risk for Japanese-manufactured high-frequency electrosurgical components underwrites inventory buffer requirements across North American distribution networks. Component fabrication concentrates in Germany, Japan, and the United States, with radiofrequency generator modules sourcing from Baden-Württemberg precision engineering clusters and laparoscopic instrument assemblies feeding from Stuttgart-area fabricators. Supply chain vulnerability centers on single-source dependencies for MRI-compatible transducer arrays. Distribution runs through hospital supply chain intermediaries for capital equipment, while ambulatory surgical centers increasingly negotiate direct procurement relationships that bypass traditional GPO structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through ambulatory surgical center chain consolidation, with national outpatient networks extracting volume-based concessions that fragment procurement authority previously centralized in hospital systems.
For Market Incumbents: Secure reimbursement coding alignment ahead of CPT update cycles to defend margin position against transcervical platform commoditization. Prioritize backward integration into radiofrequency generator production to reduce exposure to German component pricing volatility. Channel control through direct ASC sales force deployment offers defensive leverage against distributor disintermediation. For New Entrants and Emerging Players: Differentiate on EU MDR pre-certification status to capture European market entry ahead of compliance-delayed competitors. Underpenetrated rural United States markets present the most accessible white space, with mobile ablation unit leasing models addressing capital constraints. Target fertility preservation outcome data as the go-to-market anchor for gynecology practice adoption. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed radiofrequency ablation specialists facing EU MDR compliance cost absorption. Long-term viability favors platforms with installed-base expansion potential across the 5-10 year clinical evidence accumulation horizon. Acquisition targets should demonstrate post-market surveillance infrastructure readiness. The signal to watch is NICE technology appraisal timing for transcervical platforms in NHS procurement frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined clearance timelines enable first-mover positioning in ambulatory-compatible device categories. |
| EU MDR Technical Documentation Investment | Early compliance with extended clinical follow-up mandates secures European market access ahead of certification bottlenecks. |
| Ambulatory Surgical Center Direct Partnership | Bypassing hospital supply chain intermediaries captures margin expansion in fastest-growing procurement channel. |
| Software Companion Development | Real-time MRI guidance integration addresses sonography expertise bottlenecks constraining focused ultrasound deployment. |
| Reimbursement Strategy Alignment | CPT code advocacy reduces patient cost barriers and accelerates commercial payer coverage expansion. |
Research Approach
A standing panel of gynecology practice administrators, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation repositories. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure flows.
Consistency checks against ambulatory surgical center capital expenditure surveys and commercial payer coverage policy databases validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include device architecture, site-of-care tier, technology modality, and application intensity. CAGRs derived from procedure volume elasticity to reimbursement expansion and installed-base replacement cycles.
Material uncertainties — regulatory pathway delays, reimbursement coding revisions, and interventional radiology talent pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions anchored in documented clearance timelines and coverage expansion trajectories. Practitioners should keep alternative scenarios live as EU MDR certification velocity and ASC chain consolidation dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Tissue Expanders Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Global Spinal Cord Stimulation Devices Market
Medical Devices
Posture Correction Market
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
Artificial Eye Market