
 Global Insulin Pumps Market | 2026-2036
Global Insulin Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insulin Pumps Market Foresight
Type 1 diabetes management is pivoting toward home-based automated care as patients and payers prioritize reduced hospital dependency. Medtronic leverages its vertically integrated sensor-pump ecosystem to sustain manufacturing scale across North American and European distribution channels. Insulet Corporation differentiates through its tubeless patch pump architecture, while Tandem Diabetes Care competes on algorithm-driven closed-loop interoperability with third-party continuous glucose monitors.
An insulin pump is a programmable electromechanical device that delivers rapid-acting insulin subcutaneously through a cannula or needle set at programmable basal rates and bolus doses, typically operating with precision within 0.025-unit increments to maintain euglycemia. Its primary commercial purpose is to replace or reduce multiple daily injection regimens for insulin-dependent patients across ambulatory and residential settings. Patch pumps are capturing disproportionate growth momentum as disposable, tubeless formats reduce patient training burden and expand addressable populations beyond traditional durable pump candidates. Automated insulin delivery systems command premium positioning as algorithm-integrated platforms merge continuous glucose monitoring data with predictive dosing, while tethered pumps retain mature-market share among long-term users with established infusion set workflows.
FDA premarket notification and EU MDR technical documentation requirements shape product development timelines, with both agencies intensifying cybersecurity validation for wireless-connected devices. The WHO's prequalification pathway for diabetes technologies is expanding market access corridors in lower-income health systems, though national reimbursement determinations remain fragmented. Stakeholders must monitor evolving interoperability standards between pump hardware and continuous glucose monitoring platforms as regulatory convergence around automated insulin delivery redraws competitive boundaries.
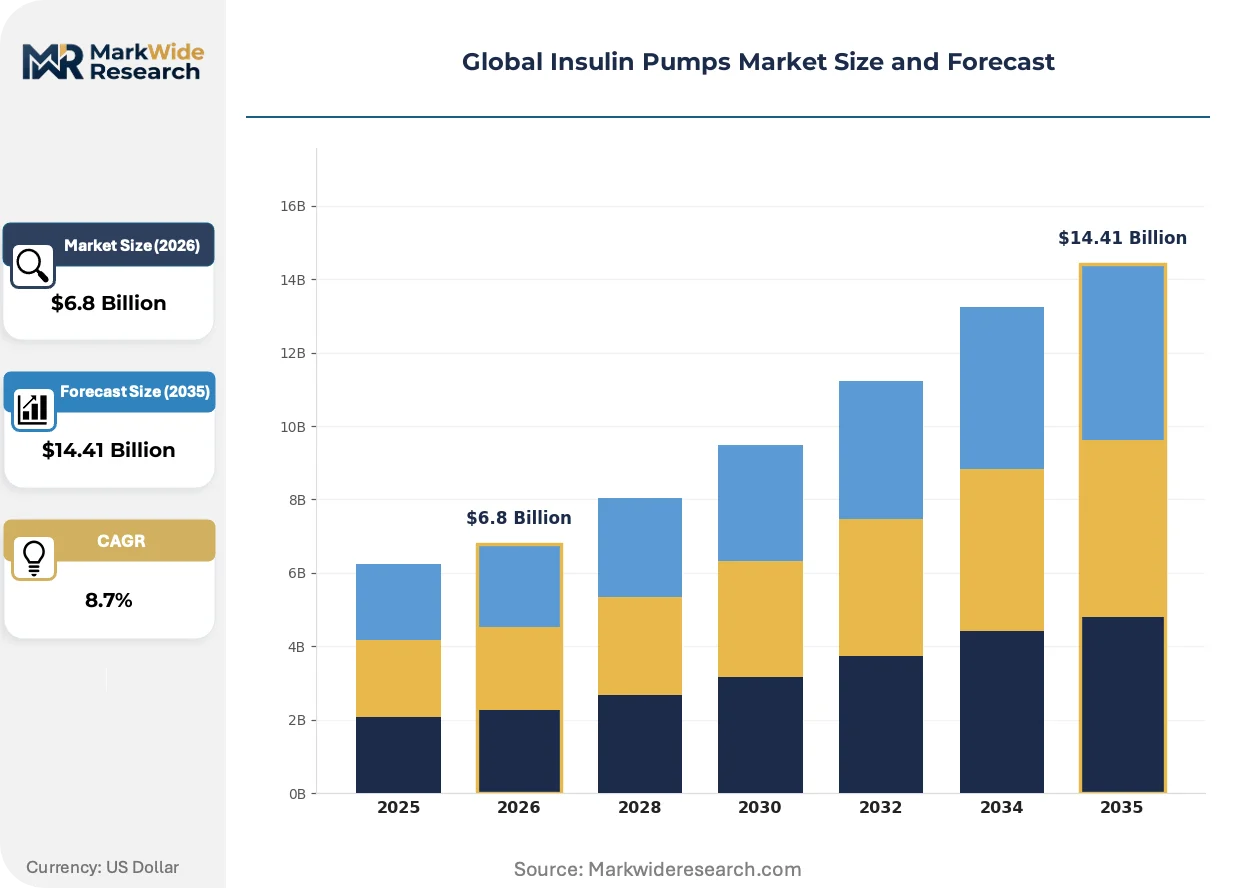
Market Dynamics
Closed-loop automated insulin delivery systems are compressing the competitive window for traditional pump manufacturers as algorithmic dosing converges with continuous glucose monitoring platforms, forcing hardware makers to secure sensor interoperability or cede premium positioning.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for hybrid closed-loop systems compress time-to-market for automated delivery platforms, rewarding manufacturers who pre-validate cybersecurity protocols.
- Home care migration:Patients managing Type 1 diabetes outside clinical settings drive demand for tubeless patch pumps that reduce training burden and enable discreet basal-bolus control during work and travel.
- Germany's DiGA framework:Digital health applications for diabetes management qualify for statutory reimbursement, creating precedent for connected pump apps across European markets.
Market Restraints
- Concentrated sensor supply:Three manufacturers control over 80 percent of continuous glucose monitor production, exposing pump makers to input bottlenecks and royalty stacking.
- EU MDR technical documentation:Extended conformity assessment timelines for class IIb active implantable devices delay product launches by 18-24 months versus prior directive schedules.
- Multiple daily injection persistence:Pen-based rapid-acting insulin analogs retain preference among newly diagnosed patients and payers prioritizing upfront cost minimization over long-term complication reduction.
Strategic Opportunities
- Japan's aging diabetes population:Adults over 65 represent the fastest-growing insulin-dependent cohort, creating demand for simplified user interfaces and caregiver-accessible remote monitoring.
- Interoperability standards convergence:IEEE 11073 and ISO 15197 harmonization enables pump-CGM data exchange across manufacturers, lowering switching costs and expanding addressable device pairings.
- Direct-to-consumer pharmacy channels:CVS and Walgreens pilot pump subscription models that bundle supplies with algorithm coaching, bypassing traditional durable medical equipment distributors.
Industry Challenges
- Cybersecurity validation complexity:FDA premarket submissions for wireless-connected pumps require penetration testing and software bill of materials documentation that extends engineering timelines.
- Infusion set manufacturing scale:Precision molding of subcutaneous cannulas demands capital-intensive cleanroom capacity that constrains production ramp for high-growth patch pump variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insulin Pumps Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Pumps, Tethered Pumps, Durable Pumps, Disposable Pumps Technology: Wireless Connectivity, Bluetooth Integration, Continuous Glucose Monitoring, Automated Insulin Delivery Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Pediatric Diabetes End User: Diabetes Clinics, Ambulatory Care Centers, Home Care, Specialty Hospitals |
| Companies Covered | Medtronic, Insulet Corporation, Tandem Diabetes Care, F. Hoffmann-La Roche, Ypsomed, SOOIL Development, EOFlow, Beta Bionics, CeQur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insulin Pumps Market Shifts & Advancements
Algorithmic decision support is migrating from advisory to autonomous dosing, compressing the gap between glucose sensing and insulin action while redrawing liability boundaries between device manufacturers and prescribing clinicians.
Dual-hormone artificial pancreas systems is absorbing developmental resources from major research consortia, combining insulin with glucagon or amylin analogs to reduce hypoglycemic exposure. Pediatric endocrinology centers in the United States and Scandinavia are piloting these platforms for nocturnal glucose control. The technology is absorbing regulatory attention as FDA and EMA draft parallel guidance for multi-analyte closed-loop validation.
EU MDR post-market surveillance requirements now mandate periodic safety update reports and trend analysis of serious incidents for all active implantable diabetes devices. Manufacturers must maintain vigilance systems that capture real-world performance data across distributed pump fleets. German notified bodies have issued the first MDR certificates for automated insulin delivery, establishing precedent for technical documentation scope that competitors must match.
Subscription-based supply bundling is displacing transactional pump purchases in United States commercial insurance segments. Patients receive quarterly shipments of infusion sets, reservoirs, and sensors with remote algorithm optimization included, flattening cash flows for manufacturers while locking in multi-year patient relationships. This model concentrates most rapidly in employer-sponsored plans seeking predictable diabetes cost management.
Global Insulin Pumps Market Segmentation
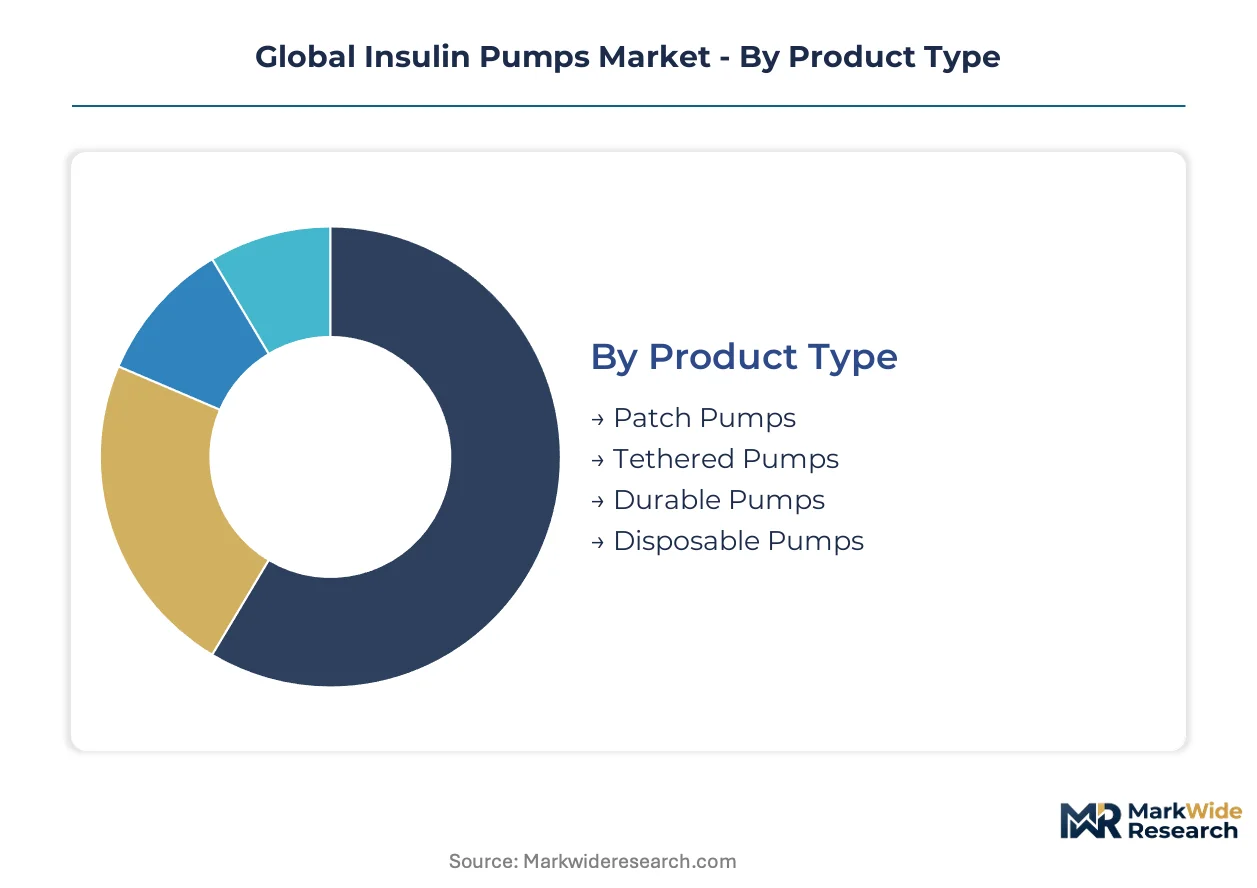
Insulin pump segmentation reflects competing priorities between hardware durability, algorithm sophistication, and care setting economics. Manufacturers must align product portfolios across these axes to capture reimbursement corridors and patient workflow preferences.
Product Type:
Patch pump architecture eliminates tubing to reduce mechanical failure modes and expand candidate populations beyond traditional durable pump users.
- Patch Pumps:Disposable tubeless devices adhere directly to skin with integrated insulin reservoirs, enabling discreet basal-bolus control during work and travel. Demand concentrates among employed adults in the United States and Germany seeking glycemic autonomy without visible medical equipment.
- Tethered Pumps:Traditional devices connect insulin reservoirs to subcutaneous infusion sets via tubing, offering larger capacity and established supply ecosystems. Long-term Type 1 diabetes patients in Japan retain preference for these systems due to familiar reservoir refill workflows and established cannula insertion routines.
- Durable Pumps:Reusable electromechanical platforms with multi-year lifespans dominate commercial reimbursement frameworks. These devices require periodic infusion set replacement rather than full device disposal.
- Disposable Pumps:Single-use fully integrated systems eliminate maintenance burden for short-term insulin-dependent populations. Gestational diabetes patients and post-surgical hyperglycemia cases drive intermittent adoption.
Patch pumps lead on momentum; tethered pumps lead on installed base scale.
Technology:
Algorithm integration intensity separates premium positioning from commodity hardware in competitive procurement.
- Automated Insulin Delivery:Closed-loop systems merge continuous glucose monitor data with predictive dosing algorithms to reduce hypoglycemic exposure. Pediatric endocrinology centers in Scandinavia and the United States pilot these platforms for nocturnal glucose control, absorbing disproportionate developmental resources from research consortia.
- Continuous Glucose Monitoring:Real-time interstitial glucose sensing enables trend alerts and retrospective pattern analysis. Integration with pump hardware varies by proprietary versus interoperable sensor pairings.
- Wireless Connectivity:Cellular and Wi-Fi transmission enables remote monitoring by caregivers and cloud-based algorithm updates. FDA cybersecurity validation requirements extend engineering timelines for these configurations.
- Bluetooth Integration:Short-range pairing with smartphone applications supports bolus dosing discretion and data visualization. This specification dominates patient-facing interface designs across all pump categories.
Automated insulin delivery leads on clinical outcome differentiation; Bluetooth integration leads on deployment ubiquity.
Application:
Disease severity and insulin dependency duration determine device complexity requirements and reimbursement eligibility.
- Type 1 Diabetes:Absolute insulin deficiency mandates continuous subcutaneous delivery for survival. Home care migration in the United States and Germany accelerates demand for automated systems that reduce hospital dependency.
- Type 2 Diabetes:Progressive beta-cell failure creates intermittent insulin requirements that challenge pump economics against pen-based alternatives. Payer cost-minimization preferences in Japan limit penetration.
- Gestational Diabetes:Temporary insulin resistance during pregnancy creates short-duration demand for simplified delivery systems. Disposable pump formats capture this episodic use case.
- Pediatric Diabetes:Caregiver oversight requirements and smaller insulin dosing increments drive demand for remote monitoring capabilities and precision delivery. FDA breakthrough device pathways prioritize pediatric indications.
Type 1 diabetes leads on device volume; pediatric applications lead on regulatory prioritization.
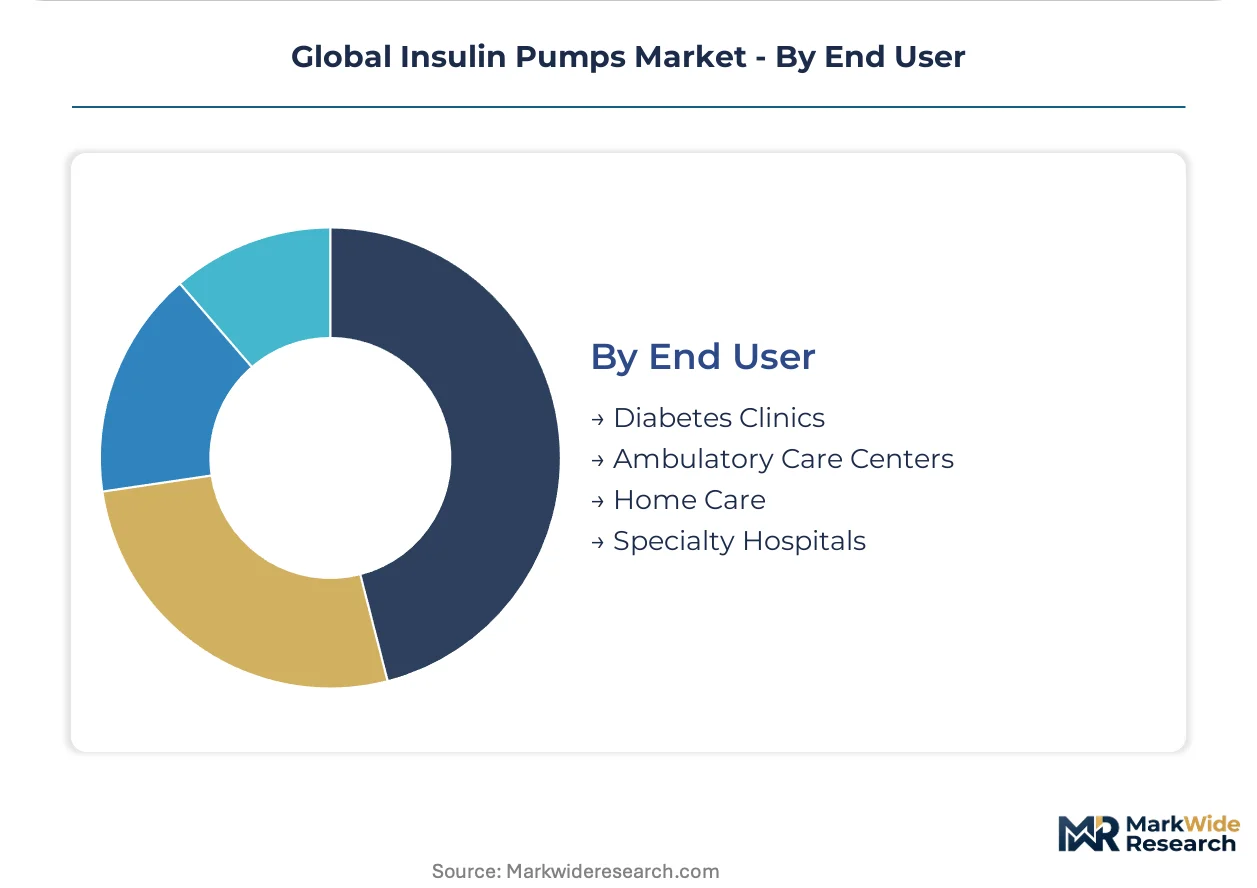
End User:
Care setting economics reshape distribution channel requirements and training burden specifications.
- Home Care:Residential self-management demands intuitive interfaces, discreet form factors, and remote troubleshooting support. Germany's DiGA framework creates precedent for connected pump app reimbursement across European markets.
- Diabetes Clinics:Specialist-led initiation and tuning of pump therapy requires durable hardware with extensive parameter adjustability. These sites concentrate in urban United States medical centers and Japanese university hospitals.
- Ambulatory Care Centers:Same-day surgical and infusion facilities utilize pumps for perioperative glycemic control. Short-term rental models dominate this channel.
- Specialty Hospitals:Inpatient endocrinology units manage pump therapy during acute illness transitions. These settings prioritize interoperability with electronic health record systems.
Home care leads on expansion trajectory; diabetes clinics lead on patient onboarding scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as manufacturers relocate production to jurisdictions with streamlined medical device approval pathways and favorable reimbursement climates. Cost-of-compliance gaps between the FDA's cybersecurity validation requirements and the EU MDR's extended conformity timelines are accelerating geographic diversification of pump assembly operations.
United States
Employer-sponsored insurance plans and Medicare Advantage expansion are driving subscription-based pump supply bundling. The FDA's Breakthrough Device Designation pathway compresses review timelines for hybrid closed-loop systems. Minneapolis-St. Paul anchors Medtronic's vertically integrated sensor-pump manufacturing ecosystem.
Germany
Statutory health insurance integration of digital health applications under the DiGA framework creates precedent for connected pump app reimbursement. The EU MDR's first automated insulin delivery certificates issued by German notified bodies establish technical documentation benchmarks. Baden-Württemberg's precision molding clusters supply subcutaneous cannula components to patch pump manufacturers.
Japan
Adults over 65 represent the fastest-growing insulin-dependent cohort, creating demand for simplified user interfaces and caregiver-accessible remote monitoring. The PMDA's streamlined approval for pediatric indications prioritizes breakthrough device pathways. Tokyo-Osaka medical device corridors concentrate diabetes clinic infrastructure for pump therapy initiation.
United Kingdom
NHS England's technology appraisal processes for continuous glucose monitor integration with pump hardware reshape procurement specifications. The MHRA's post-Brexit regulatory autonomy enables accelerated recognition of FDA-cleared automated delivery systems. Greater London's pediatric endocrinology centers pilot dual-hormone artificial pancreas platforms for nocturnal glucose control.
South Korea
National health insurance expansion for Type 1 diabetes devices reduces out-of-pocket burdens for automated insulin delivery adoption. The MFDS accelerates review timelines for wireless-connected pumps with pre-validated cybersecurity protocols. Seoul Capital Area medical centers concentrate algorithm optimization research for closed-loop interoperability.
Global Insulin Pumps Market Competitive Landscape
Strategic partnerships dominate the current landscape as hardware manufacturers secure sensor interoperability to defend premium positioning against algorithm-driven competitors. The vendor base concentrates around three distinct capability clusters: vertically integrated sensor-pump ecosystems, tubeless disposable architectures, and algorithm-specialist platforms. Two archetypes define competitive positioning: integrated device manufacturers controlling end-to-end supply chains, and modular specialists leveraging third-party continuous glucose monitor pairings. Competitive intensity manifests through M&A activity targeting algorithm assets and capacity expansion in precision cannula molding.
Within the integrated ecosystem tier, Medtronic anchors North American manufacturing scale across sensor-pump verticals. Insulet Corporation exemplifies the tubeless patch pump archetype through disposable architecture specialization. Tandem Diabetes Care occupies the algorithm-interoperability position, competing on closed-loop integration with third-party monitoring platforms. These three configurations represent the dominant strategic postures as regulatory convergence around automated insulin delivery redraws competitive boundaries.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Tandem Diabetes Care |
| F. Hoffmann-La Roche |
| Ypsomed |
| SOOIL Development |
| EOFlow |
| Beta Bionics |
| CeQur |
| Others |
Supply & Pricing Matrix
Precision molding technicians in Baden-Württemberg command wage premiums that compress margin spreads between premium automated delivery systems and standard tethered pumps, as labor-intensive cannula production constrains cost-down flexibility across pricing tiers.
Pricing Analysis
Distributor margins on insulin pump hardware compress end-user pricing power, with durable medical equipment channels capturing 15-25 point spreads before patient out-of-pocket obligations. Three-tier pricing structure across premium closed-loop, standard sensor-integrated, and economy tethered systems differentiates on algorithm sophistication and CGM interoperability certification. Pricing pressure stems from pen-based insulin analog cost minimization among commercial payers prioritizing near-term pharmacy spend over long-term complication avoidance. Newly diagnosed Type 2 patients exhibit highest price sensitivity; pediatric endocrinology centers with institutional procurement contracts demonstrate lowest.
Supply Chain Analysis
CGM sensor supply rests on concentrated manufacturing in the United States, Ireland, and South Korea, exposing pump assemblers to input bottlenecks when demand spikes for automated delivery systems. Precision-molded subcutaneous cannulas, electromechanical drive mechanisms, and rapid-acting insulin analogs constitute critical component dependencies. Single-source vulnerability in specialty polymer feedstock for patch pump adhesives threatens production continuity. Distribution runs through durable medical equipment distributors, direct-to-consumer pharmacy subscription channels, and hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Insulin Pumps Market functions as a stable compounder, with algorithm-integrated automated delivery systems driving recurrent revenue through sensor-pump subscription bundling that locks in multi-year patient relationships.
For Market Incumbents: Extend algorithm interoperability partnerships to defend premium positioning against modular competitors leveraging third-party CGM pairings. Secure backward integration into precision cannula molding capacity in Baden-Württemberg to reduce supply exposure. Invest in FDA Breakthrough Device pathway pre-validation to compress cybersecurity review timelines for wireless-connected platforms.
For New Entrants and Emerging Players: Japan's PMDA streamlined pediatric approval pathway opens a window for simplified user interface designs targeting adults over 65 with caregiver-accessible remote monitoring. Target Germany's DiGA framework for connected pump app reimbursement as the most penetrable European corridor. Pursue direct-to-consumer pharmacy channel partnerships with CVS or Walgreens to bypass entrenched durable medical equipment distribution.
For Investors and Strategic Acquirers: Medtech conglomerates with diabetes portfolio gaps are the most active acquirer in this space, seeking algorithm assets and patch pump manufacturing scale. Five-to-ten year viability hinges on automated insulin delivery regulatory convergence and interoperability standard adoption. Acquisition target archetype: algorithm-specialist platforms with validated CGM pairings and limited manufacturing footprint. Signal to watch: EU MDR certificate issuance velocity for closed-loop systems as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review compresses time-to-market for hybrid closed-loop automated delivery platforms. |
| CE Marking Pathway under EU MDR | German notified body precedent establishes technical documentation benchmarks competitors must match. |
| Hospital System Partnership | Urban United States medical centers concentrate patient onboarding scale for pump therapy initiation. |
| Software Companion Development | Germany's DiGA framework creates precedent for connected pump app reimbursement across European markets. |
| Reimbursement Strategy | Medicare Advantage expansion and employer-sponsored plans drive subscription-based supply bundling adoption. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with pediatric endocrinologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up patient volume estimates and top-down market sizing triangulate to produce segment-level outputs.
Rate-of-change decomposition across the projection horizon models insulin pump adoption by product type, technology integration level, diabetes indication, and care setting, with CAGRs derived from algorithm penetration curves and reimbursement expansion trajectories. Interoperability standard adoption velocity and closed-loop regulatory clearance timelines constitute industry-specific forecast inputs throughout the modeling period.
Revisions become necessary when FDA cybersecurity validation requirements materially extend, EU MDR conformity assessment timelines shift, or CGM sensor supply concentration disrupts pump assembly continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transradial Closure Devices Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Heart Defect Closure Devices Market
Medical Devices
Hearing Loop Market
Medical Devices
Spectacle Lens Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
Absorbable Antibacterial Envelope Market
Medical Devices
Treatment Pumps Market
Medical Devices
Elbow Fixators Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Global Surgical Drills Market