
 Lancing Devices and Lancets Market | 2026-2036
Lancing Devices and Lancets Market Size, Share, and Industry Trends Forecast 2026-2036
Lancing Devices and Lancets Market Intelligence
The bundling of lancing devices with glucose meters and test strips is consolidating buyer preference towards integrated self-monitoring kits. Roche leverages its strong position in diagnostics to offer complete diabetes care packages. BD competes on the strength of its safety-engineered lancets, which are critical for clinical and hospital settings. Abbott Laboratories differentiates through its focus on minimally invasive continuous glucose monitoring systems, which sometimes complements traditional lancing.
Lancing devices are medical instruments used to puncture skin with a small needle, or lancet, to obtain a capillary blood sample. Lancets are typically single-use, feature specific needle gauges for varying skin thicknesses, and are sterilized to prevent infection during blood sampling. The home healthcare application and home user end-use segments are expanding rapidly, driven by the management of chronic conditions like diabetes. Within product types, safety lancets represent the fastest-growing category due to their non-reusable design that minimizes needlestick injuries in clinical settings.
Regulatory frameworks from the US FDA, the EU's MDR for CE marking, and China's NMPA govern device classification, manufacturing, and post-market surveillance. These bodies mandate stringent safety and sterility standards, directly influencing product design, material choice, and market access for manufacturers. Stakeholders must now navigate the competitive pressure from emerging continuous glucose monitoring technologies that reduce the frequency of traditional finger-prick testing.
Market Dynamics
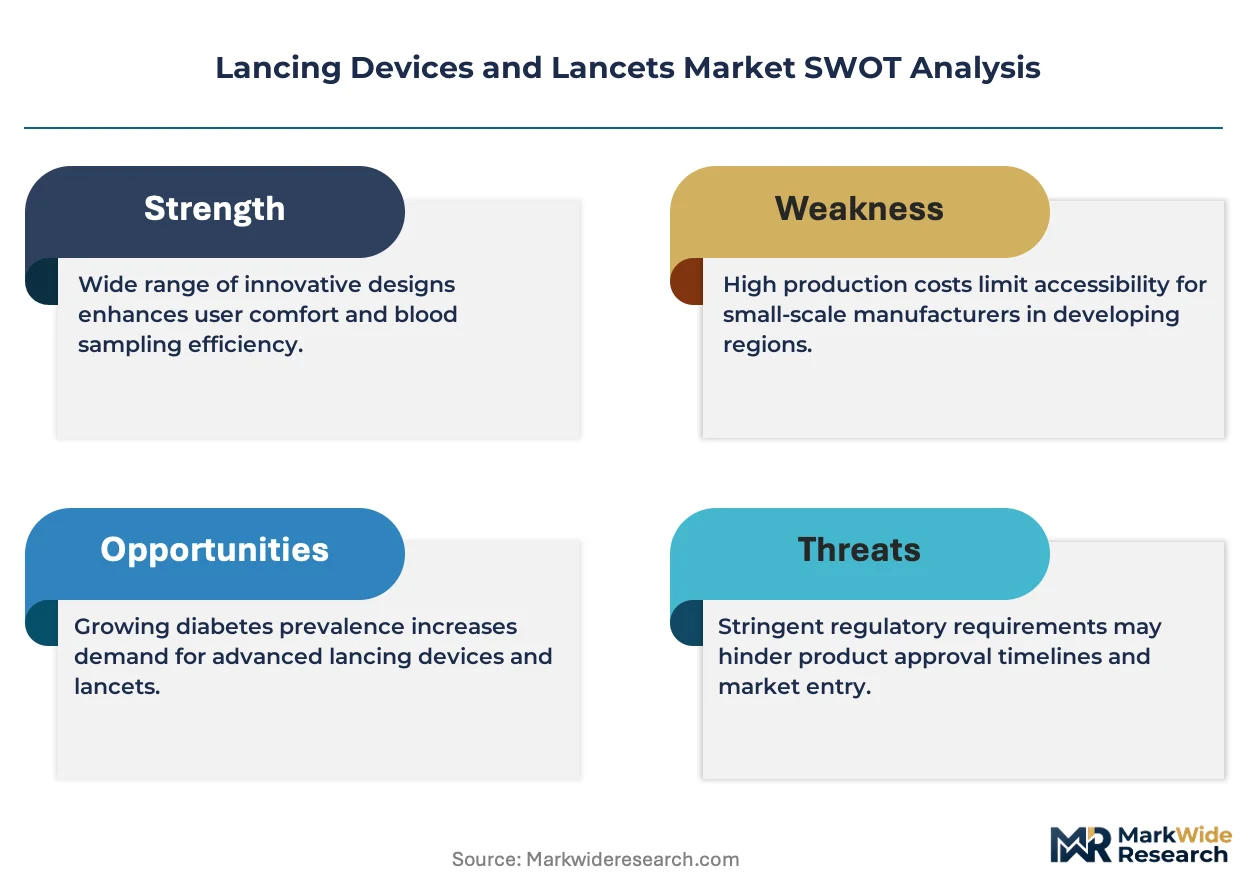
The central dynamic shaping the market is the conflict between the growing self-monitoring needs of an expanding diabetic population and the disruptive force of continuous glucose monitoring technologies that threaten to reduce the frequency of traditional finger-prick testing.
Growth Catalysts
- Expanding Home Healthcare:The rising prevalence of chronic diseases, particularly in aging populations across China and Western Europe, is expanding the home healthcare segment, which depends on user-friendly lancing devices for routine personal blood glucose monitoring.
- Stringent Safety Regulations:Europe's Medical Device Regulation (MDR) mandates stricter safety features and sterility validation. This is a catalyst for the adoption of premium, safety-engineered lancets designed to prevent needlestick injuries and cross-contamination in clinical settings.
- Point-of-Care Testing Diversification:The use of capillary blood sampling is expanding beyond diabetes management into broader point-of-care diagnostics. This includes tests for cholesterol, infectious diseases, and hemoglobin levels, creating new demand sources for lancets.
Market Restraints
- Substitution by CGM Technology:The primary restraint is the growing adoption of continuous glucose monitoring (CGM) systems. These minimally invasive technologies reduce or eliminate the need for routine finger-prick blood sampling, directly impacting lancing device and lancet volume.
- Price Commoditization:Standard, non-safety lancets face intense price pressure due to commoditization and the presence of numerous low-cost manufacturers. This erodes margins, particularly in large-volume tenders for public health systems and developing markets.
- Regulatory Compliance Costs:While promoting safety, stringent regulatory frameworks from bodies like the FDA and under the EU's MDR increase the cost and time required for product development, validation, and market approval, posing a barrier to smaller innovators.
Strategic Opportunities
- Underserved Developing Markets:Significant opportunity exists in regions like Southeast Asia and Latin America. Rising diabetes rates combined with the high cost of CGM systems make these markets prime targets for affordable, high-quality traditional lancing and monitoring kits.
- Digital Integration:There is a clear opportunity to develop "smart" lancing devices that connect via Bluetooth to smartphone applications. This integration facilitates automatic data logging, trend analysis, and seamless sharing of information with healthcare providers.
- Niche Application Development:Manufacturers can target specialized medical niches beyond diabetes. This includes creating lancets with specific gauges and penetration depths for neonatal screening, allergy testing, or micro-sampling for advanced proteomics research.
Industry Challenges
- Sterile Supply Chain Management:Ensuring the sterility and integrity of single-use lancets across complex global supply chains is a constant operational challenge. It requires rigorous quality control and adherence to standards like ISO 13485 to prevent contamination and product recalls.
- Post-Market Surveillance Burden:Complying with post-market surveillance requirements mandated by the FDA and the EU's MDR is a significant administrative and financial burden. This involves actively collecting and analyzing real-world performance and safety data throughout a device's lifecycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lancing Devices and Lancets Market |
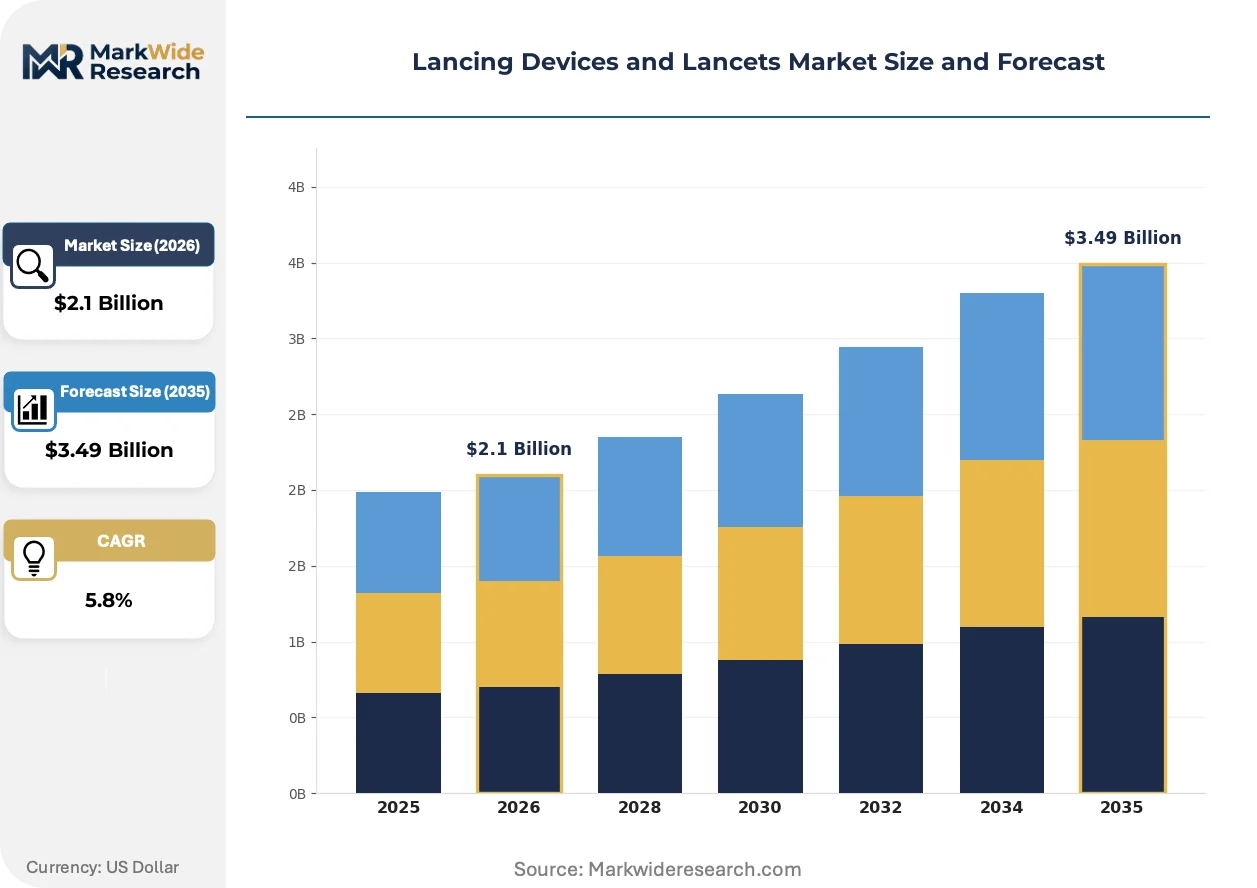
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Lancing Devices, Spring-Loaded Lancing Devices, Automatic Lancing Devices, Safety Lancets Technology: Single-Use, Multi-Use, Adjustable Depth, Sterile Coating Application: Diabetes Monitoring, Blood Sampling, Clinical Testing, Home Healthcare End User: Diagnostic Laboratories, Home Users, Research Institutes, Medical Clinics |
| Companies Covered | Roche, SARSTEDT AG & Co. KG, BD, ARKRAY, B. Braun, HTL-STREFA, Terumo, LifeScan, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lancing Devices and Lancets Market Strategic Shifts & Innovations
The dual pressures of heightened safety regulations and patient demand for less painful testing are steering innovation. This evolution is pushing the market toward devices that are not only safer for both patients and clinicians but also more integrated into digital health ecosystems.
Painless lancing technologies, utilizing lasers or micro-vibration mechanisms, are emerging to minimize the discomfort of finger-prick testing. The primary adopters are pediatric patients and premium home-users who prioritize comfort. This focus on user experience is electrifying the patient-centric segment of the market, compelling manufacturers of traditional devices to improve needle coatings and actuation mechanics.
Regulatory mandates from the US FDA regarding needlestick prevention are accelerating design changes. This has led to a decisive shift towards safety-engineered lancets with features like automatic needle retraction and single-use lockout mechanisms in clinical environments. Hospital and long-term care segments are most affected, altering their procurement criteria to prioritize devices that mitigate occupational health risks for their staff.
A significant behavioral shift involves bundling lancing devices into comprehensive diabetes management kits offered through subscription services. This model often bypasses traditional pharmacy retail channels, placing the purchasing decision with health plan providers or specialized diabetes management companies. The trend is most visible in developed healthcare systems like those in the United States and Germany, where integrated care is a strategic priority.
Lancing Devices and Lancets Market Segmentation
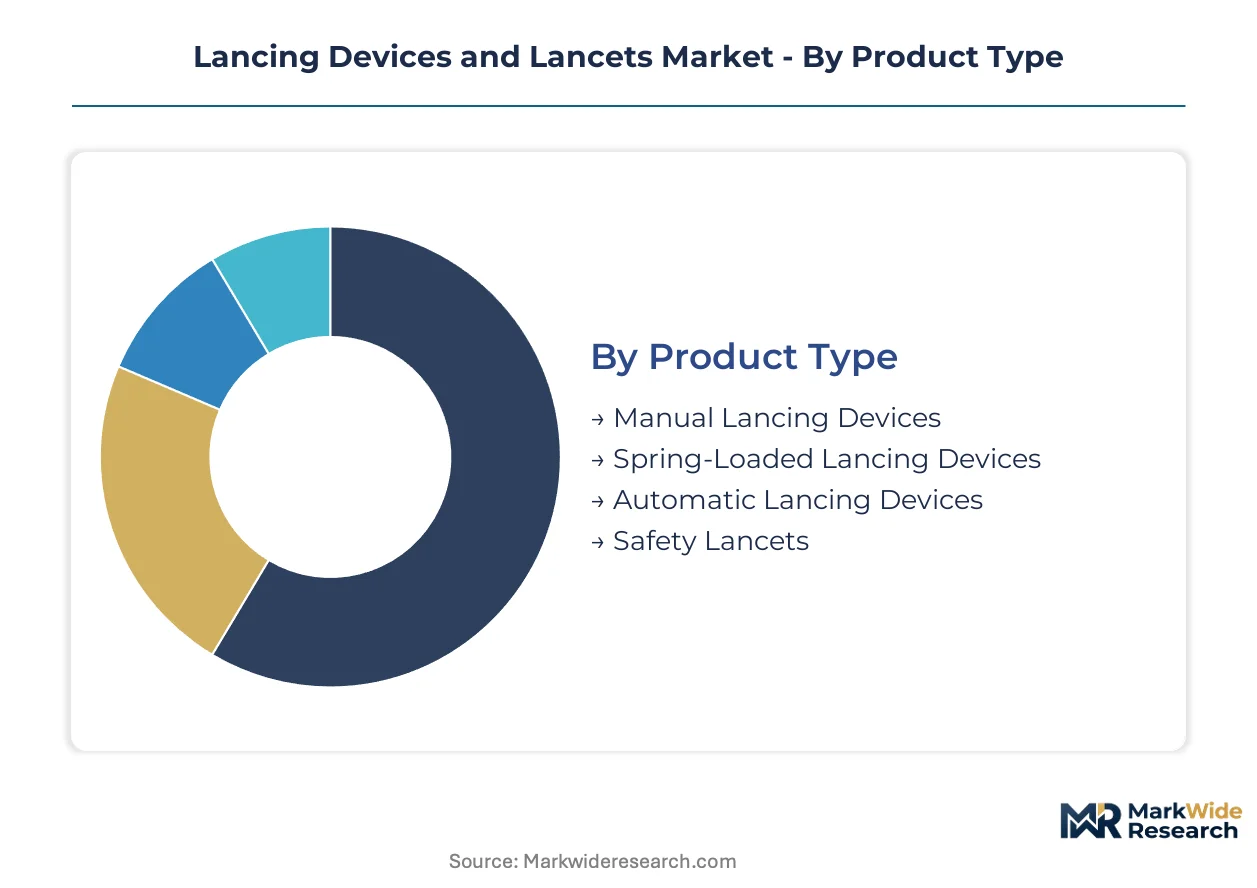
The lancing devices and lancets market demonstrates diverse segmentation reflecting varied user needs and technological advancements. Understanding these segments is crucial for manufacturers to tailor product development and market strategies. Each category reveals specific demand patterns.
Product Type:
The upgrade cycle in product types for lancing devices is driven by the continuous push for enhanced safety and user comfort. Older designs are progressively replaced by more advanced, integrated solutions in both clinical and home settings.
- Safety Lancets:These devices incorporate automatic needle retraction and single-use lockout mechanisms to prevent needlestick injuries and cross-contamination. Demand concentrates in clinical and hospital settings, driven by stringent occupational safety regulations from the EU's MDR and US FDA.
- Automatic Lancing Devices:These devices feature push-button activation for precise, consistent skin penetration, reducing user error and discomfort. Patient preference for ease of use in home healthcare, particularly for daily glucose monitoring, drives adoption.
- Manual Lancing Devices:These basic, reusable devices require manual cocking and release, representing an entry-level option for intermittent blood sampling.
- Spring-Loaded Lancing Devices:Equipped with a spring mechanism, these devices offer more consistent penetration depth than manual versions, often bundled with glucose meters.
Volume placements concentrate in Spring-Loaded Lancing Devices; the faster expansion belongs to Safety Lancets.
Technology:
Product technology differentiates based on core functional attributes, impacting operational efficiency and patient outcomes across blood sampling scenarios. These distinctions influence purchasing decisions for healthcare providers and individual users.
- Single-Use:These lancets are designed for one-time use, ensuring sterility and eliminating the risk of cross-contamination between patients. Demand accelerates in all clinical environments, driven by infection control protocols and regulatory mandates.
- Adjustable Depth:Devices with adjustable depth settings allow users to customize penetration based on skin thickness and sample volume requirements, enhancing comfort. Home users managing diabetes prioritize these features for personalized, less painful testing.
- Multi-Use:Designed for repeated use by a single patient, these devices typically require regular lancet replacement, offering a cost-effective option for personal monitoring.
- Sterile Coating:Lancets with sterile coatings reduce friction during skin penetration, minimizing discomfort and tissue damage during blood collection.
User preference for enhanced hygiene drives demand for Single-Use technologies, while patient comfort considerations elevate Adjustable Depth solutions.
Application:
The diverse applications of lancing devices and lancets reflect the expanding utility of capillary blood sampling across various medical and diagnostic fields. Each application presents unique requirements for device precision and user accessibility.
- Home Healthcare:This segment includes personal blood glucose monitoring for diabetes management and other self-administered diagnostic tests. Convenience and user-friendliness are paramount for an aging population managing chronic conditions at home.
- Diabetes Monitoring:This core application involves routine blood glucose testing to manage diabetes, requiring frequent and reliable capillary blood samples. The large global diabetic population ensures sustained demand for compatible lancing systems.
- Blood Sampling:This broad category encompasses general collection of capillary blood for various diagnostic tests beyond diabetes, such as cholesterol or hemoglobin checks.
- Clinical Testing:Professional medical environments utilize lancing devices for in-vitro diagnostics, requiring high-volume, sterile, and often safety-engineered solutions.
The maturity of Diabetes Monitoring provides a stable demand base, yet Home Healthcare applications exhibit the steepest expansion trajectory.
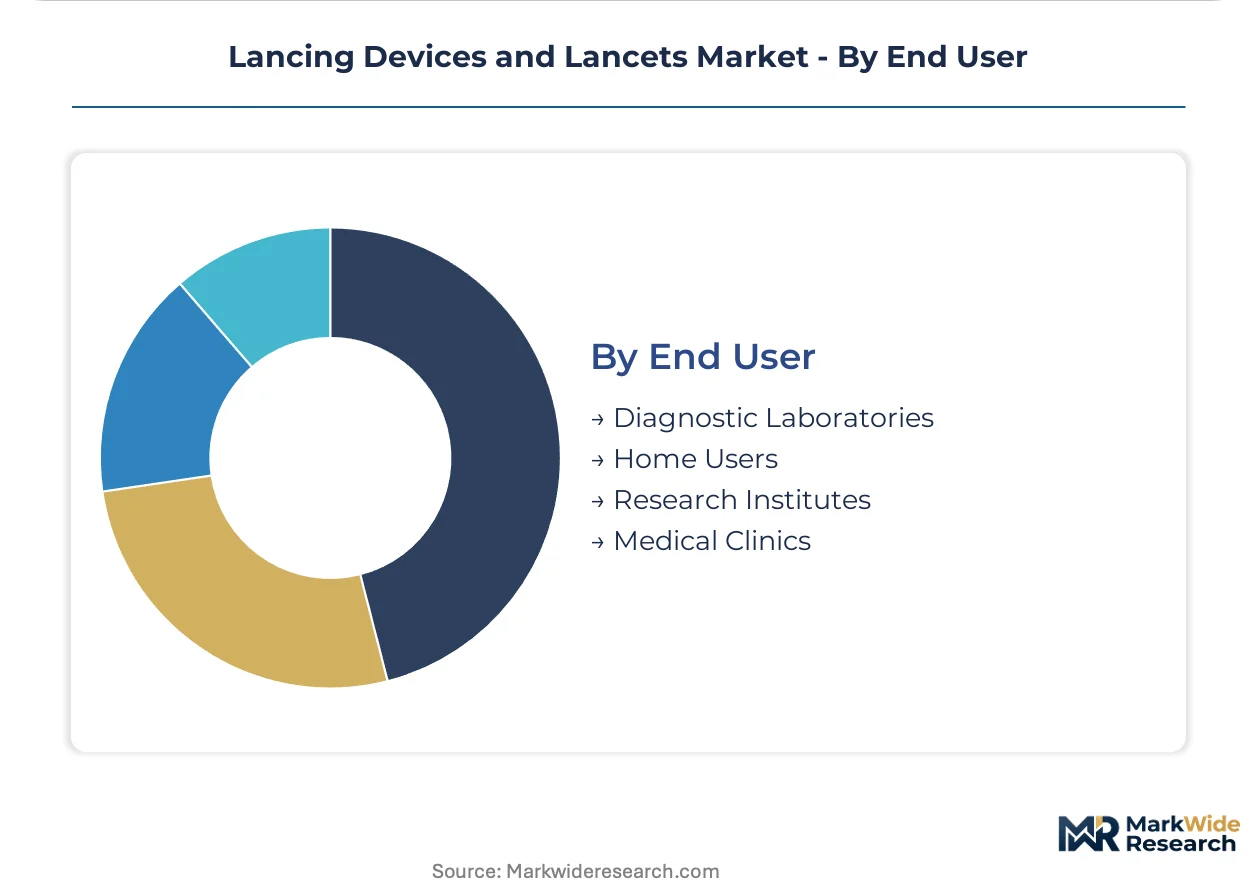
End User:
Segmentation by end-user highlights the varied operational requirements and procurement patterns across different healthcare providers and individual consumers. Each group prioritizes specific device features and cost efficiencies.
- Home Users:Individuals performing self-monitoring of blood glucose or other conditions at home constitute this segment. They prioritize ease of use, minimal pain, and cost-effectiveness for daily testing routines.
- Diagnostic Laboratories:These facilities require high-volume, reliable lancing devices for efficient processing of numerous blood samples for comprehensive diagnostic panels. Throughput and sterility are critical.
- Medical Clinics:Healthcare professionals in clinics use lancing devices for patient diagnostics, emphasizing safety features and consistent performance for diverse patient populations.
- Research Institutes:Academic and commercial research entities utilize lancing devices for studies requiring precise, reproducible micro-samples, often for specialized assays.
Regulatory compliance with safety standards significantly influences procurement in Diagnostic Laboratories, while Home Users drive innovation for comfort and ease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Greater Bay Area, a designated special economic zone, drives significant concentration in medical device manufacturing and innovation, influencing the broader lancing devices market. This region benefits from national policies promoting high-tech industries and a large, accessible patient population. The global market for lancing devices and lancets sees varied regional dynamics based on healthcare infrastructure and regulatory environments.
China
An aging population and the expanding prevalence of diabetes fuel the demand for personal glucose monitoring devices in China. The NMPA, China's national medical products regulator, mandates stringent device classification and approval processes. Shanghai, within the Yangtze River Delta, serves as a crucial hub for medical device innovation and production, attracting both domestic and international manufacturers.
United States
The United States market is characterized by a high burden of chronic diseases and a sophisticated healthcare infrastructure, driving demand for advanced lancing solutions. US FDA regulations accelerate the adoption of safety-engineered devices to minimize needlestick injuries in clinical settings. The Boston-Cambridge medical device cluster fosters significant research and development for next-generation lancing technologies.
Germany
Germany's market for lancing devices emphasizes product quality and patient comfort, supported by an established home healthcare segment. Europe's Medical Device Regulation (MDR) profoundly influences product design and material selection for market access and compliance. The Baden-Württemberg region, home to numerous precision engineering and medical technology firms, leads manufacturing excellence in this sector.
India
India presents a rapidly growing market for lancing devices due to its large and increasing diabetic population and improving access to diagnostic services. The CDSCO, India's central drug authority, regulates medical device imports and manufacturing standards to ensure product safety. Bengaluru and Hyderabad are emerging as key hubs for medical device development and distribution, catering to domestic and regional needs.
Brazil
Brazil's market experiences growth driven by expanding public health programs and a rising prevalence of chronic conditions requiring routine blood sampling. ANVISA, the National Health Surveillance Agency, establishes rigorous standards for medical device registration and quality control. São Paulo state, with its robust industrial base and extensive healthcare network, supports local production and market penetration.
Lancing Devices and Lancets Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the lancing devices and lancets market. The market structure features a mix of large, established healthcare companies and smaller, agile innovators. Strategic archetypes include comprehensive diagnostics providers, safety-focused device manufacturers, and emerging technology developers. Portfolio diversification and strategic partnerships are dominant competitive moves.
Within the comprehensive diagnostics tier, Roche and Abbott Laboratories exemplify large healthcare firms offering integrated diabetes care solutions. These companies leverage their broad market presence to provide complete monitoring packages. BD represents manufacturers specializing in safety-engineered medical devices, particularly for clinical use, emphasizing needlestick prevention and infection control.
| Leading Market Players |
|---|
| Roche |
| SARSTEDT AG & Co. KG |
| BD |
| ARKRAY |
| B. Braun |
| HTL-STREFA |
| Terumo |
| LifeScan |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Medical-grade plastic resins and stainless steel for lancets represent significant upstream cost components, directly influencing the manufacturing expense and subsequent pricing tiers of lancing devices and lancets downstream. These material costs are passed through various stages, from component suppliers to finished product manufacturers and ultimately to end-users.
Pricing Analysis
Price erosion across standard, non-safety lancets traces to intense commoditization and the proliferation of numerous low-cost manufacturers, particularly for high-volume tenders. The dominant pricing model remains per-unit transactional, though subscription models for bundled diabetes kits are emerging. Price differentiation stems from safety features, regulatory certifications like CE marking, and brand premium. Home users managing chronic conditions are generally more price-sensitive for basic devices, while clinical settings prioritize safety-engineered solutions, exhibiting lower price sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from major healthcare providers mandate multi-supplier qualification for critical lancing device components, ensuring supply resilience. Geographic supply concentrates in China for high-volume manufacturing, Germany for precision engineering, and the United States for advanced R&D. Raw material dependencies include medical-grade plastics for device housings and stainless steel for lancet needles. Regulatory compliance variations across regions, such as NMPA in China and EU MDR in Europe, pose a structural supply chain risk. Distribution runs through direct sales channels to hospitals, pharmacy retail, and increasingly, e-commerce platforms and subscription services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lancing devices market is undergoing a technology-transition phase, with continuous glucose monitoring (CGM) systems displacing some traditional finger-prick testing frequency.
For Market Incumbents: Acquire software development capabilities to integrate lancing devices into digital health platforms, counteracting the disruptive force of CGM technologies. Invest in advanced materials R&D to develop painless lancing technologies, addressing patient discomfort and differentiating products. Expand manufacturing capacity for safety-engineered lancets in regions with stringent occupational safety regulations, like Europe, to meet evolving clinical demand. Focus on channel control through strategic partnerships with health plan providers.
For New Entrants and Emerging Players: Capture underserved developing markets by offering affordable, high-quality traditional lancing and monitoring kits. Target regions like Southeast Asia and Latin America where diabetes prevalence is rising and CGM systems remain cost-prohibitive. Develop niche applications for specialized medical needs, such as neonatal screening or allergy testing, with tailored device designs and penetration depths. Leverage e-commerce and direct-to-consumer models for efficient market penetration.
For Investors and Strategic Acquirers: Widespread health plan reimbursement for smart lancing devices is the leading indicator that digital integration is gaining traction, signaling attractive investment opportunities. The market maintains long-term viability due to the stable demand for traditional methods alongside CGM adoption. Identify acquisition targets among innovators specializing in digital health integration or advanced painless lancing technologies. Monitor regulatory shifts in device classification and post-market surveillance requirements for potential M&A catalysts.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Health Platform Integration | Enhances user experience and data management for home users. |
| Safety Lancet Manufacturing Expansion | Addresses stringent regulatory mandates and clinical demand. |
| Emerging Market Distribution Partnerships | Expands reach in high-growth, price-sensitive regions. |
| R&D in Painless Sampling Technologies | Differentiates products in patient-centric segments. |
| CE Marking Pathway Acceleration | Secures market access and compliance in European markets. |
Research Approach
Trade association data, regulatory filings from the US FDA and EU MDR, and customs records anchored secondary inputs, providing foundational market intelligence. Primary research involved in-depth interviews with hospital procurement managers, diabetes educators, medical device engineers, and home users to gather qualitative insights. This comprehensive approach ensured a robust bottom-up and top-down triangulation of market data and trends.
Granularity-level modeling covered product type, technology, application, end-user, and regional regulatory frameworks across the analysis window. Compound annual growth rates were derived from historical trends, projected market shifts, and expert consensus. Key industry-specific forecast inputs included chronic disease prevalence rates and healthcare expenditure growth in target geographies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to technological breakthroughs like non-invasive glucose monitoring, and shifts in regulatory enforcement. Deviation in continuous glucose monitoring (CGM) adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Nitinol-Based Guide Wire Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Global Keratometers Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Digital BTE Market
Medical Devices
External Defibrillator Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Minimally Invasive Deformity Correction System Market