
 Pressure Ulcer Relief Products Market | 2026-2036
Pressure Ulcer Relief Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Ulcer Relief Products Market Insights
Sensor-integrated dynamic support surfaces is tilting manufacturing priorities toward real-time pressure mapping and automated repositioning algorithms. Stryker leverages its installed base of hospital beds to bundle intelligent mattress systems with enterprise analytics. Hill-Rom Holdings anchors its competitive stance through proprietary low-air-loss technology and deep clinical validation protocols. Arjo differentiates via comprehensive bariatric and wound prevention portfolios spanning acute and post-acute channels.
Pressure ulcer relief products encompass therapeutic surfaces, localized support devices, and advanced wound dressings engineered to redistribute tissue load, maintain microclimate equilibrium, and prevent ischemic injury in immobilized patients; foam densities typically range from 25 kg/m³ to 80 kg/m³ with viscoelastic formulations providing slow recovery characteristics essential for pressure dissipation. The technology dimension reveals hybrid constructions combining air-cell arrays with gel-infused foam layers are capturing disproportionate R&D investment as manufacturers pursue both pressure redistribution and shear reduction in single platforms. Application-level demand in long-term care facilities is outpacing hospital procurement growth as aging demographics expand skilled nursing bed counts and regulatory scrutiny of preventable injuries intensifies.
The FDA's 510(k) premarket notification framework governs powered and non-powered pressure-reducing devices, while the Centers for Medicare & Medicaid Services' Hospital-Acquired Condition Reduction Program imposes financial penalties for facility-acquired pressure injuries, directly linking product efficacy to institutional reimbursement. ISO 10993 biocompatibility standards and IEC 60601 electrical safety requirements constrain material selection and embedded electronics architecture for manufacturers targeting multiple jurisdictions. Stakeholders must monitor evolving CMS quality metrics and state-level long-term care staffing mandates, as these policy levers will determine whether capital investment in premium support surfaces yields measurable returns through penalty avoidance and litigation risk reduction.
Market Dynamics
Medicare's Hospital-Acquired Condition Reduction Program imposes direct financial penalties on US hospitals for facility-acquired pressure injuries, forcing capital reallocation toward premium pressure redistribution surfaces.
Growth Catalysts
- Aging demographics:Expanding skilled nursing bed counts in Japan and Germany are driving sustained demand for therapeutic support surfaces in post-acute settings.
- ISO 10993 biocompatibility standards:Harmonized material safety requirements are accelerating cross-border product registrations and reducing time-to-market for multi-jurisdictional launches.
- Powered pressure-reducing mattresses:The FDA's 510(k) clearance pathway provides predictable regulatory timelines that de-risk R&D investment for active surface technologies.
Market Restraints
- Specialized polymer foams:Viscoelastic and gel-infused formulations face input cost volatility tied to petrochemical feedstock pricing and regional supply disruptions.
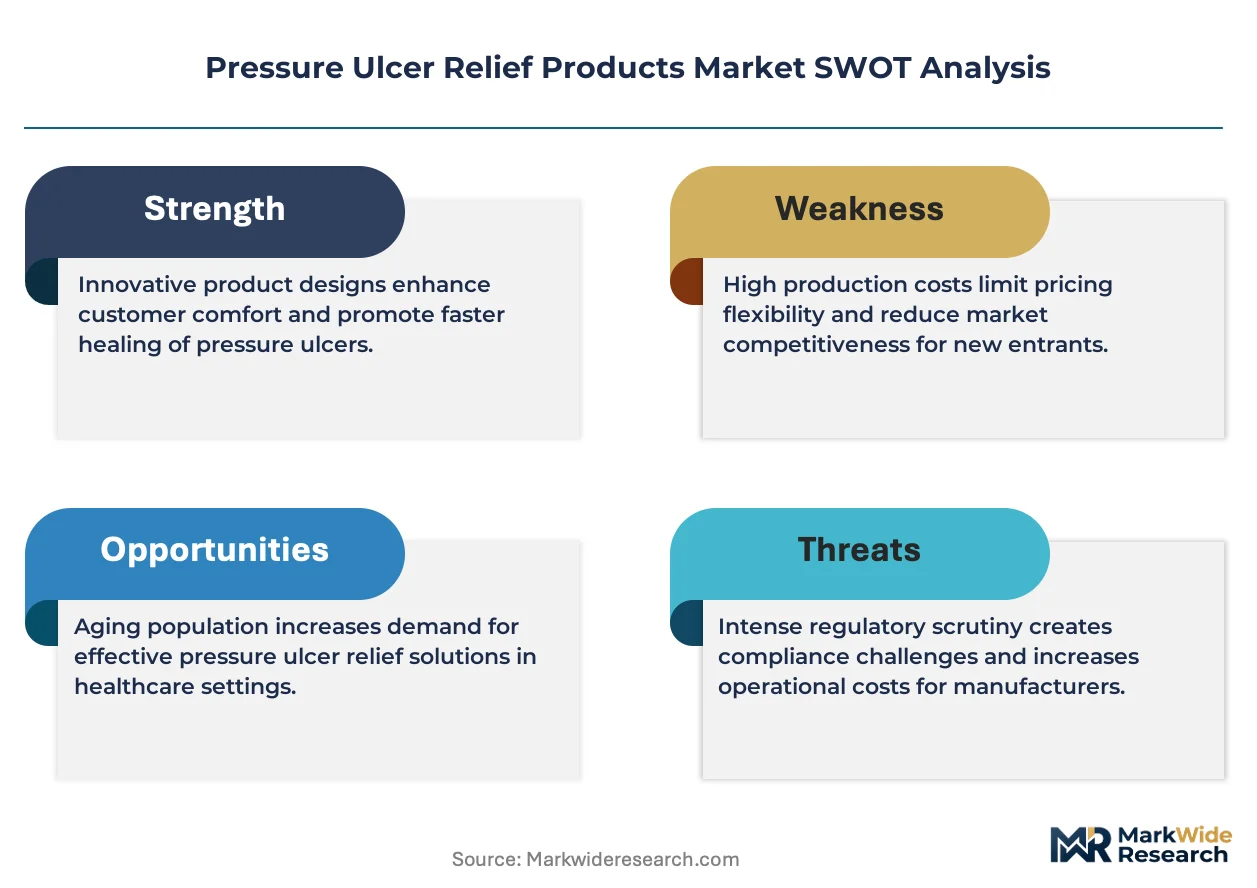
- Electronics integration:IEC 60601 electrical safety compliance adds development complexity and certification overhead for sensor-embedded dynamic surfaces.
- Static foam mattresses:Low-cost alternatives continue to capture price-sensitive procurement in emerging markets, compressing margin pools for advanced technologies.
Strategic Opportunities
- Home-based care transition:Post-acute discharge protocols in the United States are creating demand for rental and purchase models of portable pressure relief devices.
- Real-time pressure mapping:Convergence of capacitive sensor arrays with automated repositioning algorithms enables predictive intervention before tissue ischemia develops.
- EU Medical Device Regulation:MDR's enhanced clinical evidence requirements favor manufacturers with deep validation archives, creating barriers for new entrants.
Industry Challenges
- Embedded systems engineering:Shortage of firmware developers with IEC 62304 medical device software experience delays product launches for intelligent mattress platforms.
- Legacy bed integration:Retrofit compatibility with installed hospital bed frames requires mechanical adaptation that fragments engineering resources across multiple OEM form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Ulcer Relief Products Market |
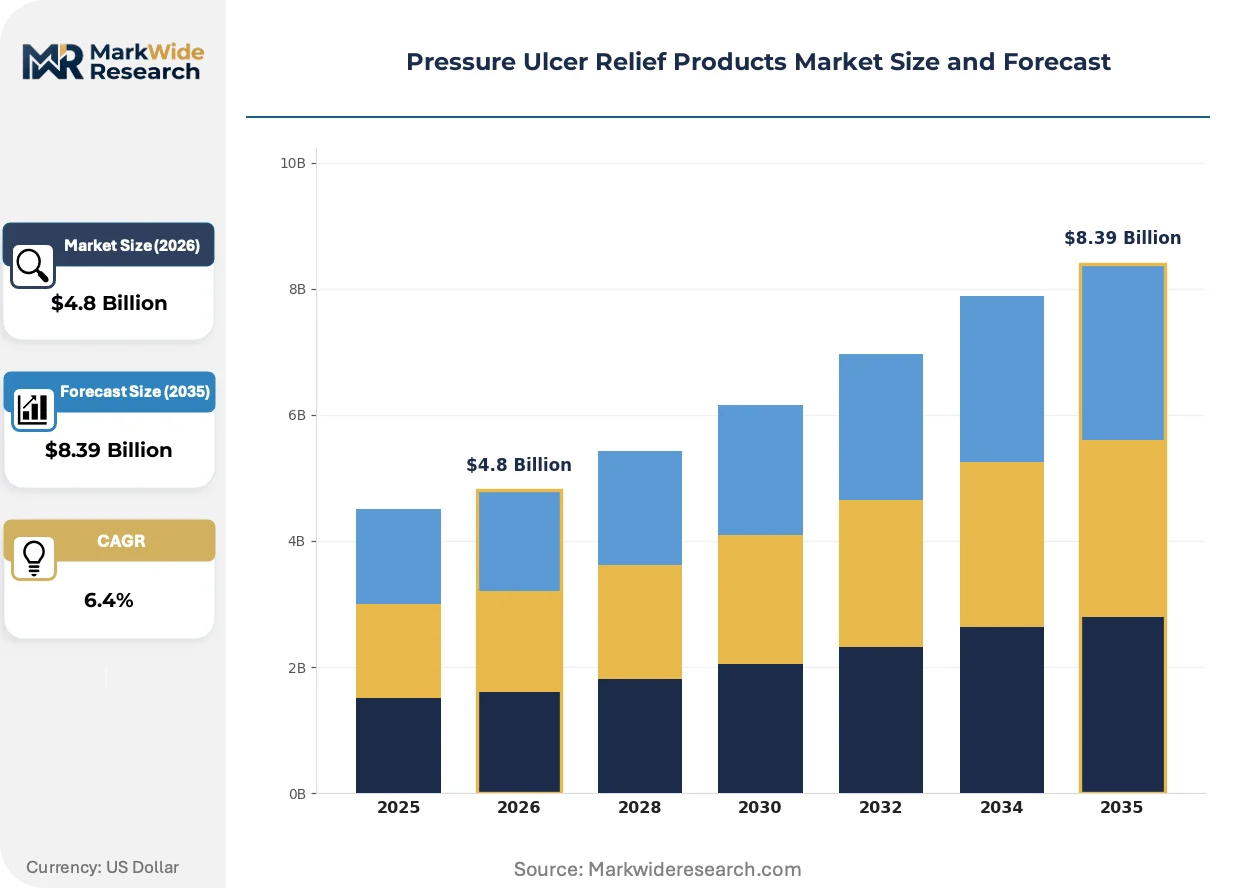
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mattresses, Cushions, Dressings, Supports Application: Home Care, Hospitals, Rehabilitation, Long-term Care End User: Clinics, Patients, Care Facilities, Health Professionals Technology: Foam, Gel, Air-filled, Hybrid |
| Companies Covered | Stryker, Hill-Rom Holdings, Arjo, Smith & Nephew, Mölnlycke Health Care, Invacare Corporation, Coloplast, Cardinal Health, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Ulcer Relief Products Market Trends and Innovations
Sensor-integrated dynamic support surfaces are compressing the traditional mattress replacement cycle while elevating clinical outcome expectations. Manufacturers are racing to embed predictive analytics that anticipate pressure injury formation before visible tissue damage occurs.
Microclimate management technology that regulates humidity and temperature at the skin-surface interface is rendering obsolete conventional low-air-loss systems that address pressure alone. Long-term care operators in the United States are piloting these hybrid platforms to reduce moisture-associated skin damage. The shift is compressing demand for standalone moisture-wicking overlays and forcing portfolio consolidation.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa and IIb pressure-reducing devices. Manufacturers must now maintain vigilance systems that track real-world performance across distributed patient populations. German and French notified bodies are enforcing this through enhanced technical documentation reviews, favoring incumbents with established quality management systems.
Acute care procurement committees are consolidating vendor relationships through enterprise analytics contracts that bundle mattress hardware with outcome monitoring software. This behavior is displacing standalone product purchasing in favor of multi-year service agreements. The pattern is most visible in United States health systems pursuing risk-based contracting with commercial payers.
Pressure Ulcer Relief Products Market Segmentation
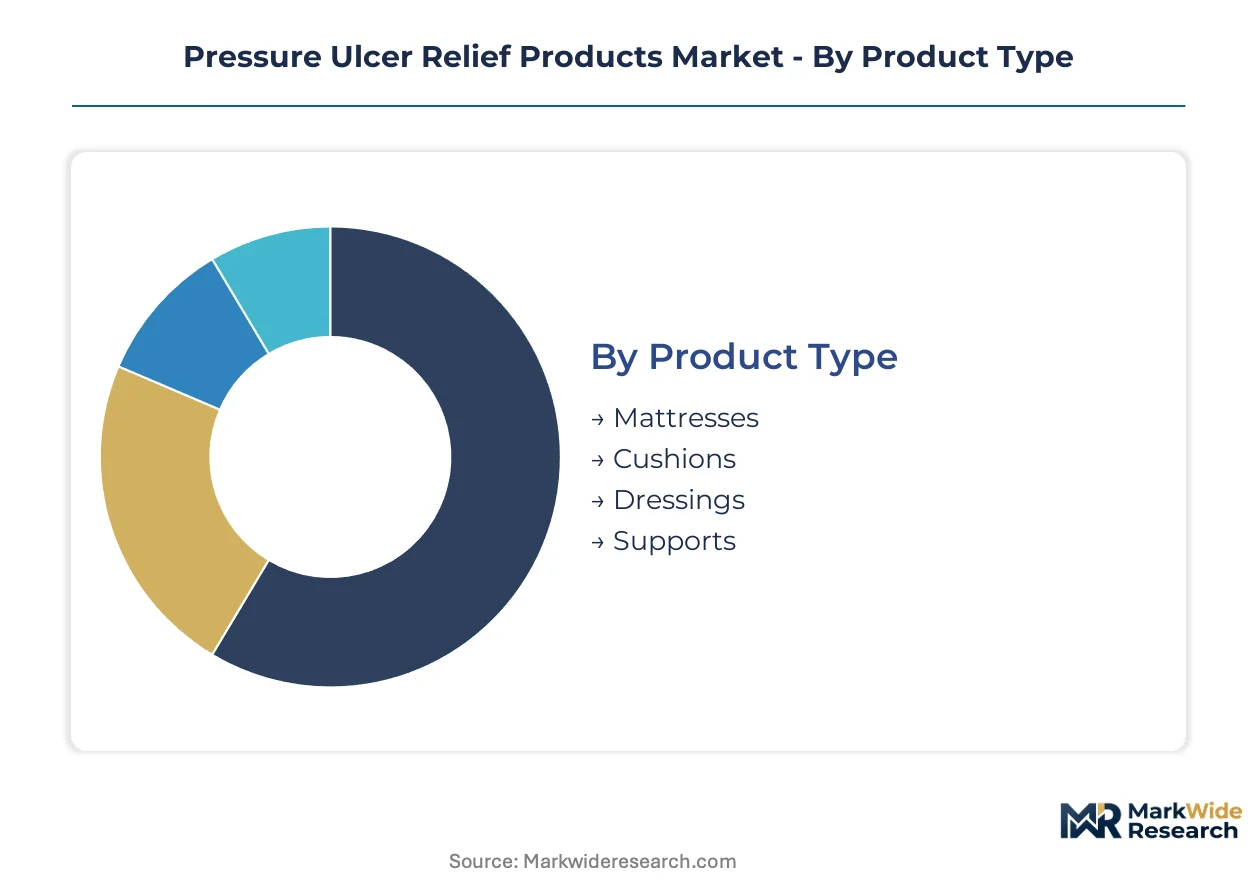
Pressure ulcer relief products fragment across four distinct taxonomies that govern procurement logic, clinical utility, and reimbursement pathways. Product type determines capital intensity and replacement cadence, while application context shapes regulatory requirements and outcome measurement protocols.
Product Type:
Mature therapeutic surfaces dominate hospital procurement budgets, yet emerging localized support devices are capturing post-acute channel expansion as care shifts toward home settings.
- Mattresses:Powered and non-powered pressure-reducing mattresses incorporate air-cell arrays, viscoelastic foam layers, or hybrid constructions to redistribute tissue load across extended contact surfaces. Demand concentrates in United States acute care facilities where Medicare's Hospital-Acquired Condition Reduction Program imposes direct financial penalties for facility-acquired pressure injuries, forcing capital reallocation toward premium redistribution surfaces.
- Cushions:Seat and heel cushions utilize gel-infused polymers, contoured foam, or dynamic air-cell configurations to isolate high-risk anatomical points from sustained pressure. Long-term care operators in Germany and Japan are expanding procurement of portable cushion systems as skilled nursing bed counts rise and regulatory scrutiny of preventable injuries intensifies.
- Dressings:Advanced wound dressings engineered for moisture management and exudate control complement mechanical pressure relief in staged injury protocols.
- Supports:Localized support devices including heel protectors and positioning wedges address anatomical pressure points through targeted offloading.
Mattresses retain volume leadership; cushions hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive institutional deployments from rental-oriented home care models, with reimbursement mechanisms determining effective purchasing power across settings.
- Hospitals:Acute care procurement committees consolidate vendor relationships through enterprise analytics contracts bundling mattress hardware with outcome monitoring software, displacing standalone product purchasing in favor of multi-year service agreements.
- Long-term Care:Skilled nursing facilities face intensified regulatory scrutiny of preventable injuries, driving sustained demand for therapeutic support surfaces as aging demographics expand bed counts.
- Home Care:Post-acute discharge protocols in the United States are creating demand for rental and purchase models of portable pressure relief devices as care transitions accelerate.
- Rehabilitation:Inpatient rehabilitation units require surfaces supporting early mobilization protocols and bariatric patient populations.
Hospitals command the highest per-unit expenditure; home care is expanding most quickly.
End User:
Customer type fragmentation reflects divergent decision authority, with institutional procurement committees operating under value-based constraints distinct from individual patient purchasing.
- Care Facilities:Long-term care and skilled nursing operators prioritize penalty avoidance and litigation risk reduction through premium support surface investment.
- Health Professionals:Wound care specialists and rehabilitation therapists influence specification decisions through clinical validation requirements and outcome documentation protocols.
- Patients:Direct purchasers in home care settings face out-of-pocket cost sensitivity that compresses margin pools for advanced technologies.
- Clinics:Outpatient wound care centers require portable devices supporting ambulatory treatment protocols.
Care facilities drive institutional volume; health professionals shape specification authority.
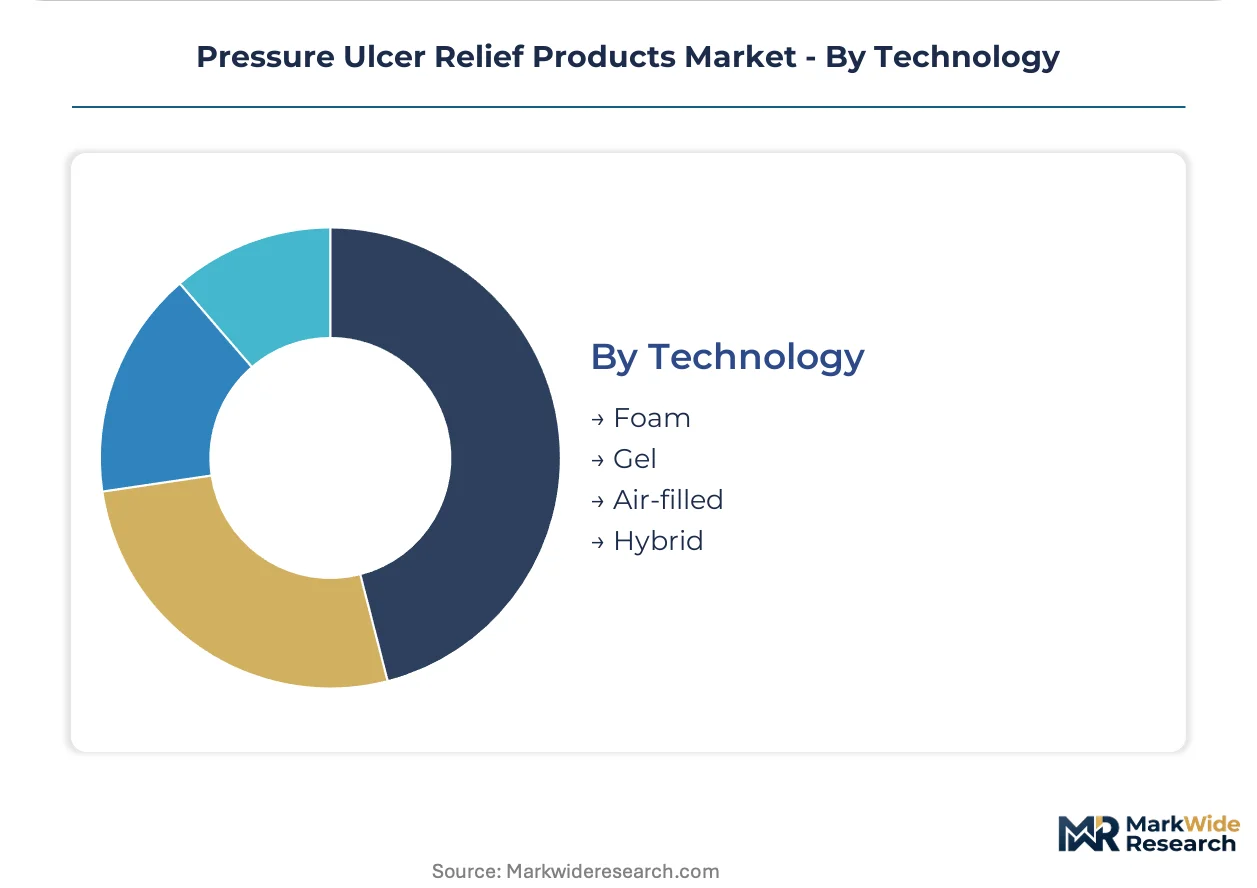
Technology:
Supply concentration in specialized polymer formulations creates input cost volatility, while electronics integration demands firmware expertise that fragments engineering resources.
- Hybrid:Convergence of air-cell arrays with gel-infused foam layers captures disproportionate R&D investment as manufacturers pursue pressure redistribution and shear reduction in single platforms.
- Air-filled:Dynamic support surfaces with automated repositioning algorithms enable predictive intervention before tissue ischemia develops, though IEC 60601 electrical safety compliance adds development complexity.
- Foam:Viscoelastic formulations with densities ranging from 25 kg/m³ to 80 kg/m³ provide slow recovery characteristics essential for pressure dissipation.
- Gel:Gel-infused polymers face input cost volatility tied to petrochemical feedstock pricing and regional supply disruptions.
Foam retains cost-accessible volume leadership; hybrid platforms hold the steepest technology premium trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export powered pressure-reducing mattresses to United States long-term care chains under FDA 510(k) clearance frameworks, establishing the dominant transatlantic trade corridor for therapeutic surface technologies.
United States
Medicare's Hospital-Acquired Condition Reduction Program imposes direct financial penalties on hospitals for facility-acquired pressure injuries, accelerating capital procurement of premium redistribution surfaces. The FDA maintains its 510(k) premarket notification pathway for powered and non-powered devices. Cleveland Clinic and Mayo Clinic health systems in the Midwest pilot sensor-integrated dynamic surfaces with automated repositioning algorithms.
Germany
Expanding skilled nursing bed counts and regulatory scrutiny of preventable injuries sustain demand for therapeutic support surfaces in post-acute settings. The EU Medical Device Regulation mandates enhanced clinical evidence requirements for Class IIa and IIb pressure-reducing devices through notified bodies in Berlin and Munich. Baden-Württemberg hosts concentrated medical device engineering clusters developing hybrid air-cell and gel-infused foam constructions.
Japan
Aging demographics and rising patient acuity drive procurement of bariatric and wound prevention portfolios across acute and post-acute channels. METI coordinates industrial standards alignment with ISO 10993 biocompatibility requirements for material safety. Osaka-based manufacturers specialize in portable cushion systems for home care transitions.
United Kingdom
NHS England's pressure ulcer reduction frameworks create institutional accountability for prevention outcomes in hospital and community settings. MHRA enforces post-market surveillance under EU MDR transitional arrangements for legacy device registrations. The Midlands manufacturing corridor supplies viscoelastic foam components to European OEMs.
China
Domestic production of static foam mattresses captures price-sensitive procurement in hospital and long-term care expansion. NMPA governs medical device registration through Class II management pathways for powered support surfaces. Yangtze River Delta clusters in Jiangsu and Zhejiang provinces scale manufacturing of gel-infused polymer formulations for regional distribution.
Pressure Ulcer Relief Products Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers with embedded analytics capabilities, displacing standalone product vendors. Three strategic archetypes dominate: diversified medical technology conglomerates bundling hardware with enterprise software, specialized wound care and support surface manufacturers with deep clinical validation archives, and contract manufacturers supplying private-label foam and air-cell components to institutional procurement channels. Competitive moves concentrate on strategic partnerships linking mattress hardware to outcome monitoring platforms, and geographic expansion through rental service models targeting post-acute discharge protocols.
Within the diversified medical technology tier, Stryker Corporation and Hill-Rom Holdings exemplify platform consolidation strategies, anchoring competitive positioning through installed base leverage and proprietary low-air-loss technology. Arjo AB occupies a specialist position spanning bariatric and wound prevention portfolios across acute and post-acute channels. These three entities represent distinct approaches to navigating reimbursement-linked procurement environments where Medicare penalty avoidance drives premium surface adoption.
| Leading Market Players |
|---|
| Stryker |
| Hill-Rom Holdings |
| Arjo |
| Smith & Nephew |
| Mölnlycke Health Care |
| Invacare Corporation |
| Coloplast |
| Cardinal Health |
| Medline Industries |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese static foam manufacturing is compressing margins for commodity-tier suppliers while simultaneously elevating pricing power for hybrid technology leaders in Germany and the United States. This utilization asymmetry forces procurement committees to navigate widening cost-performance deltas across therapeutic surface categories.
Pricing Analysis
The technology-generation pricing gap separates legacy static foam systems from sensor-embedded dynamic surfaces and emerging microclimate-managed platforms. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 10993 certification depth, and after-sales analytics bundling. Cost compression in economy foam tiers is intensifying because Yangtze River Delta manufacturers are absorbing petrochemical volatility to maintain hospital procurement contracts. Home care patients exhibit highest price sensitivity; United States health systems pursuing risk-based contracts show lowest sensitivity due to Medicare penalty avoidance calculus.
Supply Chain Analysis
Contract manufacturing concentration rests with Yangtze River Delta foam processors, Baden-Württemberg precision air-cell fabricators, and Jiangsu gel-polymer compounders. Geographic supply concentration centers on China for base foam substrates, Germany for pneumatic control systems, and Japan for capacitive sensor arrays. Raw material dependencies draw from petrochemical feedstocks, medical-grade silicone membranes, and embedded electronics components. Single-source vulnerability in specialized viscoelastic formulations creates exposure to regional supply disruptions. Distribution runs through group purchasing organizations in United States acute care, direct institutional contracts in German post-acute channels, and rental service networks for home care transitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pressure ulcer relief products market is accelerating through sensor-integrated dynamic surfaces and automated repositioning algorithms, with FDA 510(k) pathway predictability and Medicare penalty structures creating aligned incentives for premium technology adoption.
For Market Incumbents: Build installed-base moats through enterprise analytics bundling that locks hospital systems into multi-year mattress replacement cycles with outcome monitoring software. Deepen backward integration into proprietary low-air-loss technology and gel-infused foam formulations to defend margin position against commodity foam entrants. Expand capacity addition in Baden-Württemberg engineering clusters to capture EU MDR-enhanced clinical evidence requirements that favor incumbents with validation archives. For New Entrants and Emerging Players: Portable cushion systems for United States home care transitions represent the most penetrable entry point, as post-acute discharge protocols create rental-model demand with lower regulatory barriers than powered mattress platforms. Bariatric patient populations in Japanese skilled nursing facilities offer secondary white-space, with METI-coordinated standards alignment reducing certification friction. Pursue go-to-market angles through wound care specialist influence rather than hospital procurement committee direct sales. For Investors and Strategic Acquirers: Long-term, this sits as a healthcare infrastructure consolidation play because reimbursement-linked procurement environments favor platform providers with embedded analytics capabilities over standalone product vendors. Acquisition target archetype: specialized wound care manufacturers with deep clinical validation archives and established notified body relationships under EU MDR. Monitor CMS quality metric evolution and state-level long-term care staffing mandates as early signals of capital investment return realization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Predictable clearance timelines de-risk R&D investment for powered active surface technologies. |
| Hospital System Partnership | Enterprise analytics contracts bundle mattress hardware with outcome monitoring software. |
| CE Marking Pathway | EU MDR enhanced clinical evidence requirements favor manufacturers with validation archives. |
| Software Companion Development | Predictive analytics integration enables automated repositioning algorithms before tissue ischemia. |
| Reimbursement Strategy | Medicare penalty avoidance calculus directly links product efficacy to institutional purchasing power. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, CMS Medicare reimbursement policy documents, EU MDR technical documentation from Berlin and Munich notified bodies, and ISO 10993 biocompatibility standards registries. Primary interviews engaged hospital purchasing committee directors, long-term care facility operators, wound care specialist clinicians, biomedical engineers, and GPO contracts managers. Bottom-up therapeutic surface unit economics triangulate against top-down healthcare capital expenditure flows.
Forecast inputs incorporate product type segmentation across mattresses, cushions, dressings, and supports; application context spanning hospitals, long-term care, home care, and rehabilitation; technology tiers from static foam through hybrid air-cell gel constructions; and end-user decision authority fragmentation. CAGRs derive from installed base replacement cycles, regulatory penalty structure evolution, and demographic bed count expansion across the projection horizon. Industry-specific inputs include IEC 60601 electrical safety compliance timelines and skilled nursing facility staffing mandate trajectories.
Practitioners should monitor petrochemical feedstock volatility, FDA 510(k) backlog fluctuations, and CMS quality metric recalibrations for early signals of forecast revision. Cross-checking against hospital procurement database benchmarks and GPO contract award disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Hot and Cold Therapy Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market