
 Turbine Control Systems Market | 2026-2036
Turbine Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Turbine Control Systems Market Intelligence
A shift from large, state-owned electric utility companies toward a more fragmented base of independent power producers and industrial self-generators is rebalancing the customer landscape. Siemens Energy leverages its extensive portfolio in power generation to serve both traditional and renewable energy clients. General Electric sustains a strong market position through its deep integration with aviation and power turbine manufacturing. Meanwhile, Woodward specializes in control solutions for aerospace and industrial engines, differentiating on precision and reliability.
A turbine control system is an automated solution managing a turbine's rotational speed, temperature, pressure, and fuel flow. Its core function is to ensure safe, efficient operation, maximizing output while minimizing mechanical stress on components. Digital control systems, integrated with SCADA, are displacing legacy hydraulic controls due to superior precision and diagnostics. While power generation is the largest application, the renewable energy segment shows the most significant expansion.
Regulations like the US EPA's emission standards and the EU's F-Gas Regulation directly influence control system design for environmental compliance. Adherence to ISO 9001 and specific IEC safety integrity levels (SIL) is mandatory for market access and product reliability. Stakeholders must balance the push for remote monitoring and efficiency gains against the rising cybersecurity risks in connected control networks.
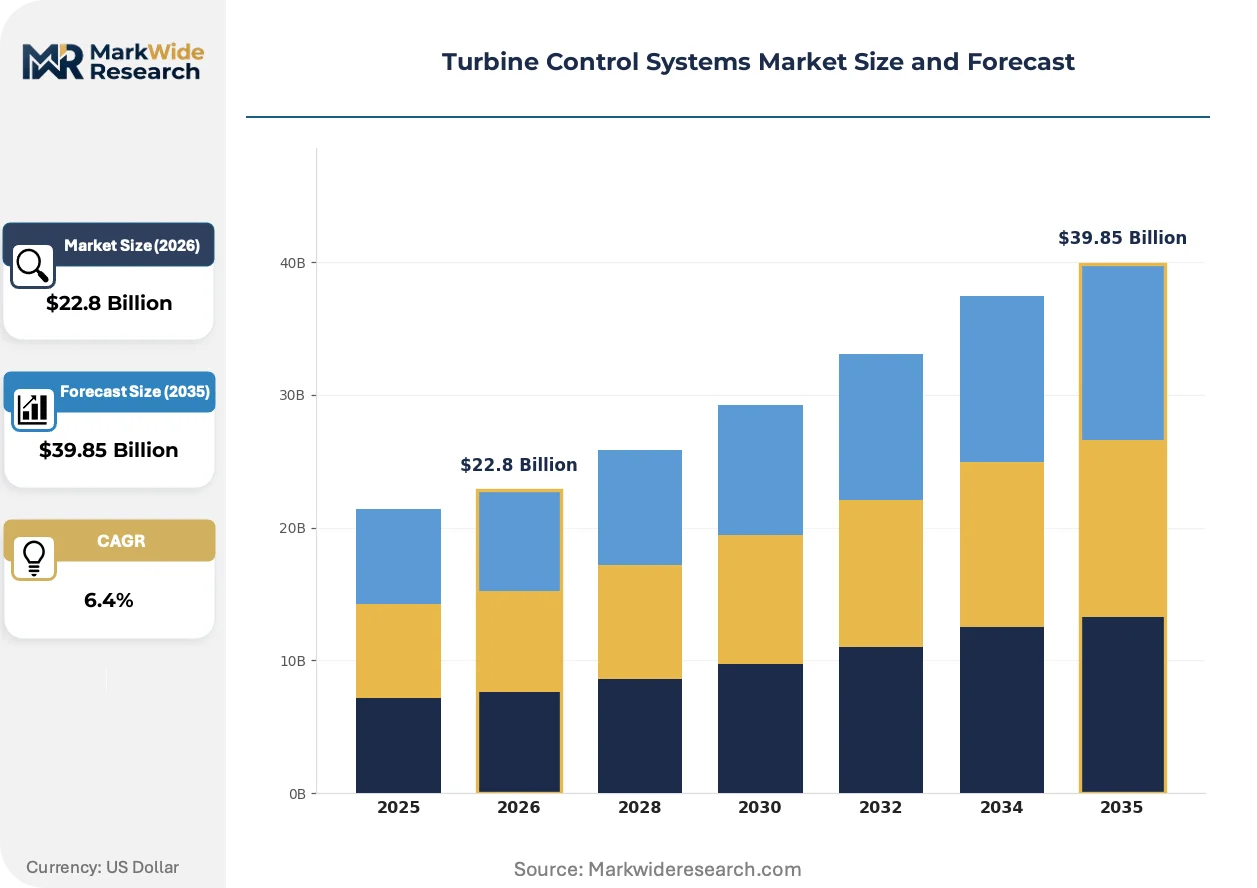
Market Dynamics
The imperative to enhance grid stability amid the rapid integration of variable renewable energy sources is the central force shaping the market. This pressure compels power generators to invest in advanced turbine control systems for faster response times and greater operational flexibility.
Growth Catalysts
- Grid Modernization:Upgrades in the power generation sector to improve grid stability and accommodate renewable energy sources drive demand for advanced digital controls, displacing legacy hydraulic systems.
- EU Green Deal:European policy emphasis on energy efficiency accelerates the modernization of existing turbine fleets with more precise and responsive control systems to reduce fuel consumption and emissions.
- Industrial Expansion:Demand concentrates in industrial hubs across China and India, where new energy infrastructure projects require state-of-the-art turbine control solutions for both power and industrial applications.
Market Restraints
- High Retrofit Costs:The significant capital investment required to replace or upgrade legacy hydraulic and analog control systems in aging power plants presents a major financial barrier for some operators.
- System Integration Complexity:Integrating new digital controls with existing plant-wide SCADA systems and older mechanical components can be technically challenging, leading to extended downtime and project delays.
- Cybersecurity Vulnerabilities:The increased connectivity of modern control systems exposes critical power generation assets to significant cybersecurity risks, demanding substantial investment in robust security protocols and expertise.
Strategic Opportunities
- Hydrogen Economy:The development of turbines designed to run on hydrogen fuel creates a new frontier for specialized control systems capable of managing the unique combustion properties and safety requirements of H2.
- Predictive Analytics:Integrating AI and machine learning into control software allows for predictive maintenance, offering operators a new value proposition beyond basic operational control and safety functions.
- Decentralized Power:The rise of independent power producers and industrial self-generators creates demand for scalable, modular control solutions that differ from the monolithic systems used by traditional state utilities.
Industry Challenges
- Talent Scarcity:A shortage of engineers and technicians skilled in both modern control software and legacy turbine mechanics creates a significant operational bottleneck for implementation and maintenance projects.
- Regulatory Compliance:Adherence to stringent safety standards like IEC 61508 for Safety Integrity Levels (SIL) requires extensive and costly validation processes for all new control system designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbine Control Systems Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
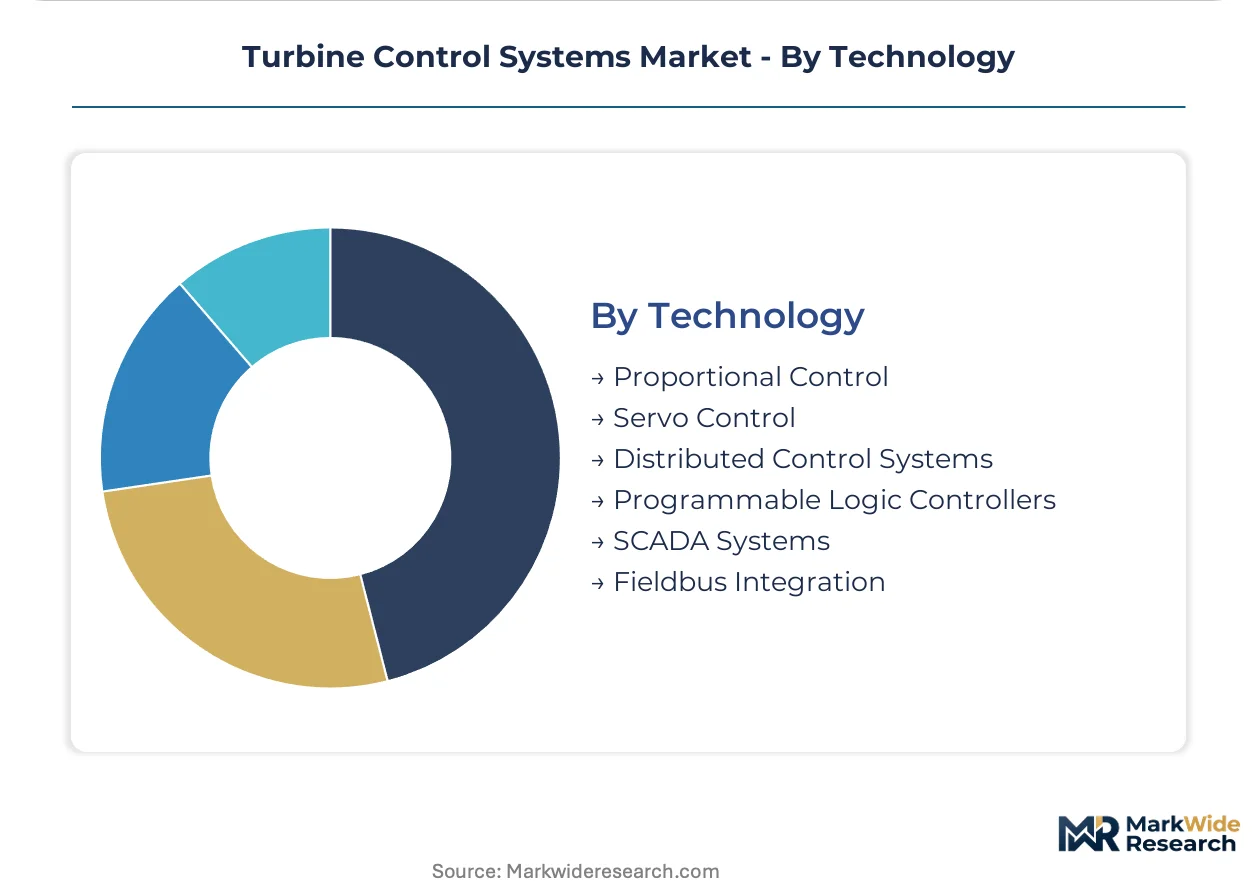
| Segmentation | Product Type: Hydraulic Control, Electronic Control, Pneumatic Control, Electro-Hydraulic Control, Digital Control Application: Power Generation, Marine Propulsion, Aviation Turbines, Oil & Gas Compression, Renewable Energy End User: Electric Utility Companies, Shipbuilding Yards, Aerospace Manufacturers, Energy Service Companies Technology: Proportional Control, Servo Control, Distributed Control Systems, Programmable Logic Controllers, SCADA Systems, Fieldbus Integration |
| Companies Covered | Emerson Electric Co., Eaton, ABB, Woodward, Schneider Electric, Siemens Energy, Honeywell International, Rockwell Automation, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbine Control Systems Market Strategic Shifts & Innovations
The market's evolution is defined by a convergence of digital technologies and stringent environmental mandates. This dynamic forces vendors to innovate beyond core operational control toward integrated performance and compliance management solutions for power generation assets.
Edge computing is being integrated directly into turbine control hardware to process high-frequency sensor data locally. Power generation asset owners, particularly in the wind and gas turbine sectors, are adopting this architecture to improve response times. The modern digital control system is absorbing many data-processing functions once reserved for centralized SCADA platforms, reducing network latency and improving autonomous decision-making.
Regulations like the EU's F-Gas Regulation are phasing out certain greenhouse gases used in industrial equipment, influencing component selection in control system hardware. This directly impacts the design of auxiliary systems and enclosures for control panels. Consequently, manufacturers serving the European market must re-engineer products and update their supply chains to ensure compliance with these environmental standards.
A clear shift is occurring from one-time hardware procurement to subscription-based models for software and analytics services. This approach disrupts the traditional transactional sales model by creating recurring revenue streams tied to performance outcomes. This trend is most visible in North American and European deregulated power markets, where operators prioritize asset lifetime value and operational expenditure over initial capital costs.
Turbine Control Systems Market Segmentation
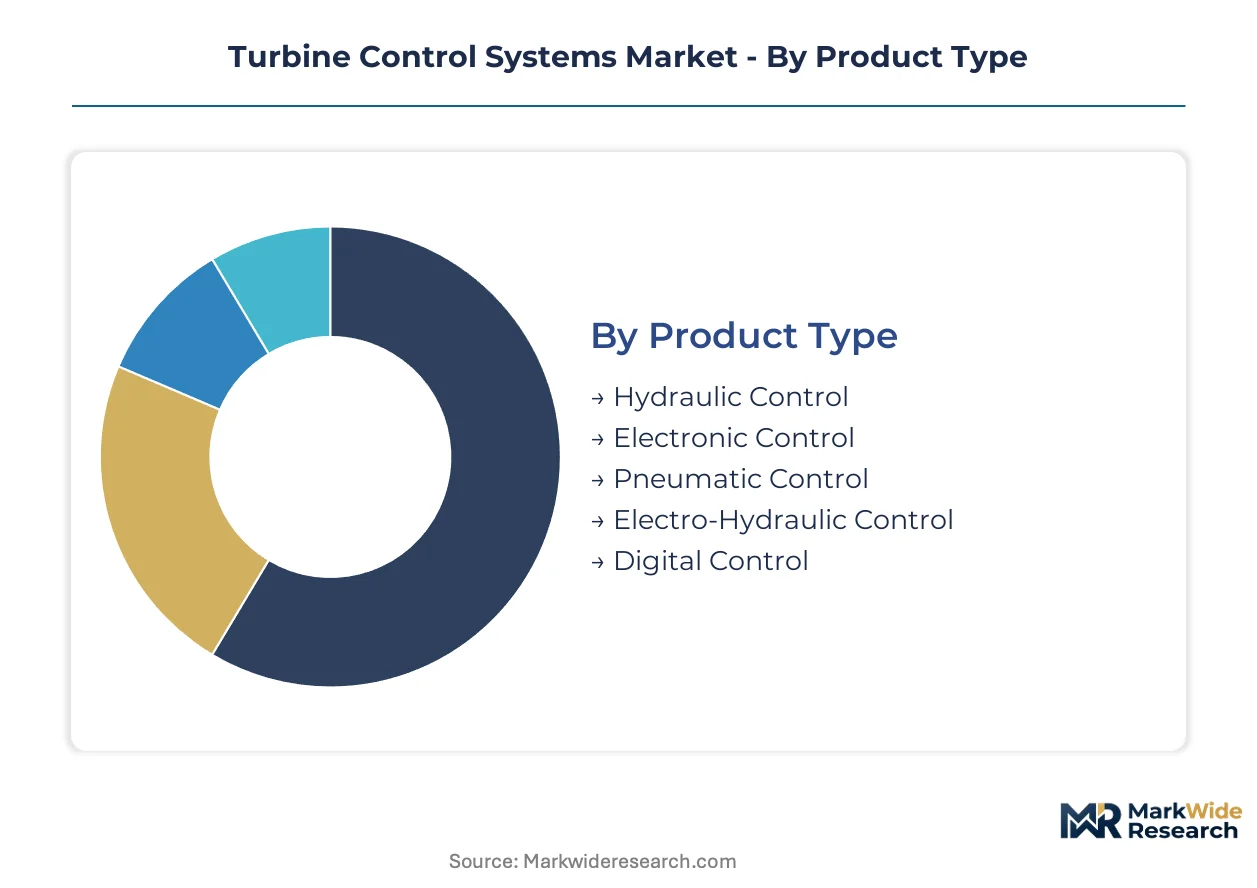
The turbine control systems market is segmented by critical operational characteristics and end-user requirements, influencing technology adoption and investment priorities. Understanding these distinctions helps stakeholders identify areas of high growth and specific technological needs across diverse applications.
Product Type:
Operators prioritize control system product types based on balancing precision, response time, and cost efficiency for their specific turbine applications.
- Digital Control:These systems integrate advanced microprocessors and software, often with SCADA, to manage turbine parameters with superior precision and offer extensive diagnostic capabilities. Demand is concentrating in power generation and renewable energy sectors, particularly in China and India, for grid stability and efficiency upgrades.
- Electro-Hydraulic Control:These hybrid systems combine the high power output of hydraulics with the precise control and responsiveness of electronics, offering robust and reliable operation. New energy infrastructure projects in industrial hubs require these systems for their balance of force and accuracy.
- Hydraulic Control:These legacy mechanical systems use fluid pressure for actuation, providing robust force but lacking the precision and diagnostic capabilities of modern digital alternatives.
- Electronic Control:Early digital systems provided improved stability and accuracy over purely mechanical controls, paving the way for fully integrated digital solutions.
- Pneumatic Control:These systems utilize compressed air for control, typically found in less demanding or specialized applications due to their inherent limitations in precision and speed.
Digital Control leads on scale in new installations; Electro-Hydraulic Control leads on momentum in modernization projects.
Application:
The choice of turbine control systems varies significantly across applications, driven by distinct operational requirements and regulatory mandates.
- Power Generation:This application involves managing industrial gas, steam, and hydro turbines to ensure stable and efficient electricity production for national grids. Upgrades in Europe, driven by the EU Green Deal, and new infrastructure in China and India compel investment in advanced controls for grid stability.
- Renewable Energy:This segment includes control systems for wind, solar thermal, and hydro turbines, optimizing performance for variable energy sources and integrating them into existing grids. This segment shows the most significant expansion due to global decarbonization efforts and the imperative to enhance grid stability.
- Marine Propulsion:Control systems in this sector manage ship engines and gas turbines, ensuring precise speed and power for vessel maneuverability and fuel efficiency.
- Aviation Turbines:These highly specialized controls are critical for aircraft jet engines, ensuring precise thrust management, safety, and compliance with strict aviation regulations.
- Oil & Gas Compression:Control systems for compressors in the oil and gas industry regulate gas flow and pressure, crucial for pipeline integrity and processing plant efficiency.
Market expansion is primarily driven by Power Generation, while Renewable Energy is the fastest-growing segment.
End User:
End-user segments dictate control system requirements based on their scale of operations and investment priorities.
- Electric Utility Companies:These traditional, often state-owned entities operate large-scale power plants and prioritize grid stability, long-term reliability, and compliance with environmental regulations like the US EPA's emission standards. They invest in upgrades for existing turbine fleets.
- Energy Service Companies:This category includes independent power producers and industrial self-generators who focus on operational flexibility, modularity, and cost-effective solutions for distributed power generation. This group is rebalancing the customer landscape.
- Shipbuilding Yards:These facilities integrate turbine control systems into marine vessels, focusing on robust, reliable solutions that meet international maritime safety standards.
- Aerospace Manufacturers:Companies in this sector design and produce turbine engines for aircraft, demanding highly precise and safety-critical control systems that meet FAA and EASA certification requirements.
Traditional demand anchors in Electric Utility Companies, with significant new opportunities emerging from Energy Service Companies.
Technology:
Control system technology adoption depends on the required level of automation, diagnostic capabilities, and integration with broader plant management systems.
- SCADA Systems:Supervisory Control and Data Acquisition systems provide centralized monitoring and control over entire plant operations, integrating data from various digital control systems. These are essential for remote monitoring and diagnostics in modern power generation facilities.
- Distributed Control Systems:These networked systems consist of multiple controllers distributed throughout a plant, offering high reliability, scalability, and redundancy for complex industrial processes. Large power plants in industrial hubs utilize these systems for robust control.
- Proportional Control:This basic feedback control mechanism adjusts output proportionally to the error between a setpoint and the measured process variable. It offers limited precision for dynamic turbine operations.
- Servo Control:These systems provide precise control over position, speed, or torque, commonly used in turbine control for accurate valve actuation and fuel flow regulation.
- Programmable Logic Controllers:PLCs are specialized industrial computers used for automating specific processes and discrete tasks within a turbine's auxiliary systems.
- Fieldbus Integration:This technology uses digital communication networks to connect control system components, reducing wiring complexity and enhancing data exchange between devices.
Advanced digital solutions like SCADA Systems and Distributed Control Systems are increasingly preferred for complex turbine operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China and India drive new energy infrastructure projects, mature markets like Germany and the United States prioritize grid stability upgrades. These distinct investment priorities shape demand for advanced turbine control systems. The global market reflects varying stages of energy transition and industrial development.
China
China's robust industrial expansion fuels demand for state-of-the-art turbine control solutions across new energy infrastructure projects. The country's dual carbon goals accelerate investment in digital controls for efficiency and emissions reduction. Manufacturing hubs in the Yangtze River Delta actively integrate advanced SCADA systems into power generation facilities.
United States
United States power generators invest in advanced controls to enhance grid stability and integrate variable renewable energy sources. The US EPA's emission standards directly influence control system design for environmental compliance in thermal power plants. Key energy regions like Texas are upgrading turbine fleets with digital solutions for faster response times.
Germany
Germany's strong emphasis on energy efficiency and renewable integration, driven by the EU Green Deal, accelerates modernization of existing turbine fleets. Compliance with the EU's F-Gas Regulation influences component selection in control system hardware for auxiliary systems. Industrial centers in Bavaria are adopting advanced digital control systems for both power generation and industrial applications.
India
India's rapid urbanization and industrial growth necessitate significant investment in new power generation capacity and grid upgrades. Government initiatives like the PLI scheme encourage domestic manufacturing of advanced components, including control systems. Major industrial corridors in Gujarat are implementing distributed control systems for robust plant management.
United Kingdom
The United Kingdom focuses on decarbonization and integrating offshore wind energy, requiring highly responsive turbine control systems. National net-zero targets compel power producers to invest in advanced digital solutions for efficient renewable energy management. The North Sea region sees significant adoption of edge computing in wind turbine controls for improved autonomous decision-making.
Turbine Control Systems Market Key Industry Players
North American producers anchor one tier, offering comprehensive solutions across various energy sectors; European specialists hold a strong position in high-precision controls and regulatory compliance. The market exhibits a tiered structure, with a few large, diversified players alongside specialized technology providers catering to niche applications. Strategic archetypes include integrated industrial conglomerates, focused control system vendors, and regional system integrators. Companies pursue portfolio diversification, strategic partnerships, and technology licensing to expand their market reach and adapt to evolving energy landscapes.
Integrated industrial conglomerates like Siemens Energy and General Electric exemplify comprehensive power generation portfolios, serving both traditional and renewable energy clients globally. These large entities leverage their broad engineering capabilities across various turbine types. Woodward, a US-based specialist, occupies a distinct position by focusing on precision control solutions for aerospace and industrial engines, differentiating on precision and reliability. These players represent the diverse strategic approaches within the turbine control systems market, from broad-spectrum offerings to highly specialized applications.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Eaton |
| ABB |
| Woodward |
| Schneider Electric |
| Siemens Energy |
| Honeywell International |
| Rockwell Automation |
| General Electric |
| Others |
Cost & Logistics Intelligence
A shortage of skilled engineers in modern control software and legacy turbine mechanics creates labor-cost differentials that influence pricing-tier spreads for specialized services and complex system integrations.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for new turbine control system installations. Project-based pricing dominates, though a shift towards subscription-based models for software and analytics services is occurring. Precision, reliability, and IEC safety integrity level (SIL) certification drive price differentiation. High system integration complexity and retrofit costs exert upward pricing pressure on comprehensive solutions. Energy Service Companies are more price-sensitive, while Electric Utility Companies prioritize long-term reliability and compliance.
Supply Chain Analysis
Refurbishment and remanufacturing flows for critical control modules are gaining traction, driven by sustainability mandates and cost efficiency. Supply concentrates in manufacturing hubs across China, Germany, and the United States for electronic and electro-hydraulic components. The supply chain relies on specialized microprocessors, high-precision sensors, and hydraulic actuation components. Regulatory restrictions, such as the EU's F-Gas Regulation, pose a structural risk to component availability and design. Distribution runs through direct sales to large utilities and specialized system integrators for complex projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Turbine Control Systems market presents a geographic-arbitrage play, capitalizing on cost differentials between new energy infrastructure projects in emerging economies and grid modernization initiatives in mature markets.
For Market Incumbents: To counter customer landscape fragmentation, incumbents must develop modular, scalable control solutions tailored for independent power producers. Strategic partnerships with renewable energy developers can expand market reach. Integrating AI and machine learning for predictive maintenance offers a new value proposition beyond basic operational control.
For New Entrants and Emerging Players: Independent power producers and industrial self-generators represent an underserved archetype requiring cost-effective, flexible control systems. Focusing on controls for the nascent hydrogen economy or specialized solutions for decentralized power offers white-space opportunities. Offering subscription-based software and analytics services can attract these operators by shifting from CapEx to OpEx models.
For Investors and Strategic Acquirers: Integrated industrial conglomerates are the most active acquirers in this space, seeking to consolidate technology and expand portfolio capabilities. The market offers long-term viability driven by global grid modernization and the imperative for renewable energy integration. Acquisition targets should include specialized control solution providers with expertise in predictive analytics or hydrogen turbine management. Practitioners should monitor the pace of hydrogen economy development for early inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| AI/ML Integration for Predictive Analytics | Enhances operational efficiency and enables predictive maintenance for power generation assets, reducing downtime. |
| Hydrogen Turbine Controls Development | Positions vendors for the emerging hydrogen economy, addressing unique combustion properties and safety requirements. |
| Expand Subscription-Based Service Models | Shifts revenue models from transactional to recurring, aligning with operator preferences for operational expenditure in North America. |
| Cybersecurity Hardening for Control Networks | Protects critical power generation infrastructure from rising cyber threats, ensuring grid stability and operational integrity. |
| Modular Solutions for Decentralized Power | Addresses the specific needs of independent power producers with scalable, cost-effective control systems for decentralized power. |
Research Approach
Coverage spans China, India, the United States, Germany, and the United Kingdom, with primary inputs from each region. Primary interviews included utility planning officers, IPP project developers, control system engineers, and OEM procurement teams. Secondary validation drew from government energy statistics, national grid operator reports, and company financial filings. This approach ensured robust bottom-up and top-down triangulation of market data.
Market volume and value were modeled at a granular level across product type, application, end user, technology, and regional adoption patterns. The analytical framework integrated historical data trends and statistical analysis across the analysis window. Compound Annual Growth Rates were derived from these detailed segment forecasts. Key inputs included variable renewable energy sources integration rates and new energy infrastructure project timelines.
Underlying measurement precision varies by segment; Power Generation and Digital Control carry tighter precision than others. Forecasts reflect assumptions regarding regulatory stability. Practitioners should monitor hydrogen economy development and grid modernization investments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
Vietnam Power EPC Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Steam Turbine Control System Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
SCR Power Controller Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Australia Power EPC Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Global Power Rental Systems Market