
 Cogeneration Equipment Market | 2026-2036
Cogeneration Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cogeneration Equipment Market Intelligence
Multi-sourced component procurement is hardening as original equipment manufacturers seek resilience against supply disruptions. General Electric leverages its in-house gas turbine casting capacity to control lead times for large-frame units. Siemens anchors its European installation base through regional service hubs that sustain aftermarket revenue. Mitsubishi Heavy Industries competes on combined-cycle efficiency ratings that dominate Asian utility tenders.
Cogeneration equipment converts a single fuel source into simultaneous electricity and useful thermal output, typically achieving total system efficiencies exceeding 80 percent through heat recovery steam generators or organic Rankine cycle configurations. The technology serves manufacturing plants, district heating networks, and institutional campuses where steady thermal loads justify capital-intensive installations. Gas turbines occupy the highest value tier due to their scalability into hundred-megawatt class plants for independent power producers. Reciprocating engines lead in sub-20 megawatt commercial and hospitality applications where modular deployment and fast ramping prove decisive. Fuel cells remain the fastest-growing technology segment despite higher capital costs, as zero-emission profiles unlock subsidies and carbon credit revenue streams for data center operators.
EPA emissions standards under the Clean Air Act and the EU F-Gas Regulation shape product design cycles by mandating nitrogen oxide limits and refrigerant phase-downs for cooling-integrated trigeneration systems. Japan's METI enforces Top Runner efficiency standards that force manufacturers to recertify equipment against progressively tighter benchmarks. China's MEE implements dual carbon goals that restrict new coal-linked cogeneration while accelerating gas-fired and biomass alternatives. Stakeholders must monitor how carbon border adjustment mechanisms reshape equipment sourcing decisions across integrated supply chains.
Market Dynamics
Industrial power reliability mandates are compressing deployment timelines for on-site thermal-electric systems as data centers and manufacturing clusters face zero-tolerance uptime requirements. This structural pressure is reshaping equipment specification priorities across procurement functions.
Growth Catalysts
- EU Green Deal carbon pricing:Industrial emitters in Germany and the Netherlands face escalating compliance costs that make high-efficiency cogeneration economically defensive against grid power alternatives.
- Data center thermal loads:Hyperscale facilities in Virginia and Frankfurt are specifying trigeneration systems to capture waste heat for cooling absorption chillers.
- Fuel cell subsidies:Japan's METI clean hydrogen incentives unlock capital cost offsets for zero-emission installations at semiconductor fabrication campuses.
Market Restraints
- Nickel superalloy supply concentration:Gas turbine casting feedstock depends on Russian and Indonesian ore processing that faces export restriction volatility.
- F-Gas refrigerant phase-down:The EU F-Gas Regulation tightens availability of working fluids for cooling-integrated systems, forcing equipment redesign cycles.
- Interconnection queue delays:Grid connection backlogs in California and Texas extend project commissioning timelines for independent power producers.
Strategic Opportunities
- India manufacturing clusters:The PLI scheme for textiles and food processing creates captive power demand in Gujarat and Tamil Nadu where thermal loads justify cogeneration scale.
- Biomass feedstock integration:Agricultural residue-to-energy systems in Brazil and Thailand unlock carbon-negative credentials for export-facing processors.
- Performance contracting channels:Energy service companies in France and Italy are assuming operational risk for municipal district heating retrofits.
Industry Challenges
- Commissioning engineer scarcity:Specialized turbine alignment and controls integration skills concentrate among aging workforces in Germany and Japan.
- Legacy SCADA integration:Brownfield industrial sites require protocol bridging to connect new cogeneration assets to existing plant control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cogeneration Equipment Market |
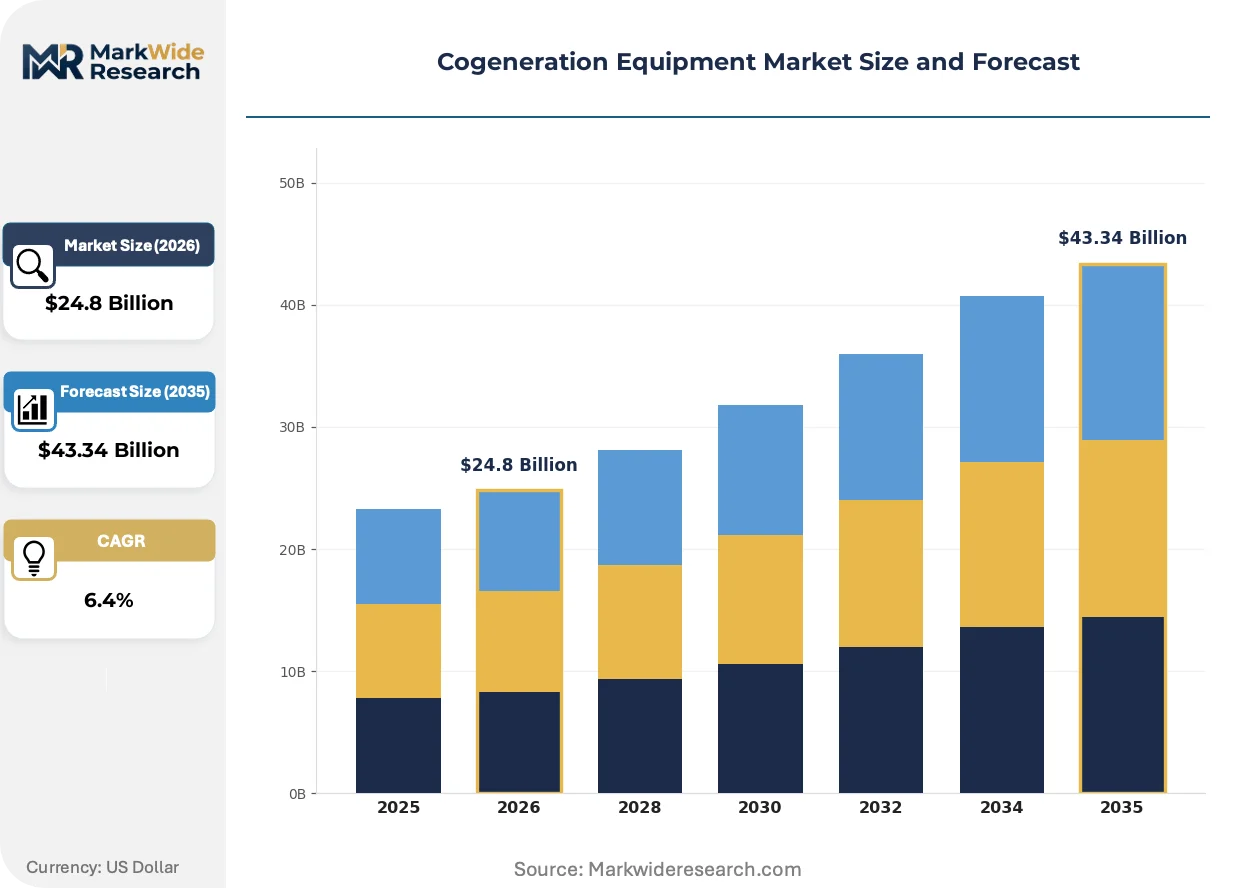
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating Engines, Gas Turbines, Steam Turbines, Microturbines, Fuel Cells Technology: Combined Cycle, Combined Heat and Power, Trigeneration, Heat Recovery Steam Generator, Organic Rankine Cycle Application: Commercial Buildings, Manufacturing Plants, Data Centers, District Heating, Hospitality Sector End User: Independent Power Producers, Public Utilities, Manufacturing Facilities, Institutional Campuses |
| Companies Covered | General Electric, Siemens, Mitsubishi Heavy Industries, ABB, Caterpillar, Rolls Royce, 2G Energy, Kawasaki Heavy Industries, Clarke Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cogeneration Equipment Market Strategic Shifts & Innovations
Modular power architectures are compressing project development cycles and enabling distributed generation at scales previously reserved for centralized utilities. Equipment suppliers are reconfiguring product platforms around standardized skids rather than field-erected systems.
Containerized organic Rankine cycle units are decentralizing waste heat recovery for sub-10 megawatt industrial applications. Food processors in Denmark and pharmaceutical manufacturers in Ireland are deploying these systems to capture exhaust energy from existing thermal oxidizers. The technology is decentralizing project finance structures by reducing upfront capital commitments and enabling equipment-as-a-service contracting.
China's MEE dual carbon enforcement is accelerating gas-fired cogeneration approvals while restricting new coal-linked installations. Provincial environmental bureaus in Jiangsu and Guangdong are fast-tracking permits for combined-cycle plants that displace standalone industrial boilers. Domestic turbine suppliers are capturing share from European competitors in these accelerated procurement windows.
After-sales service unbundling is fragmenting long-term maintenance relationships between end-users and original equipment manufacturers. Independent service providers in Texas and Alberta are winning multi-year contracts for gas turbine hot section overhauls. This shift concentrates in deregulated power markets where asset ownership separates from operational expertise.
Cogeneration Equipment Market Segmentation
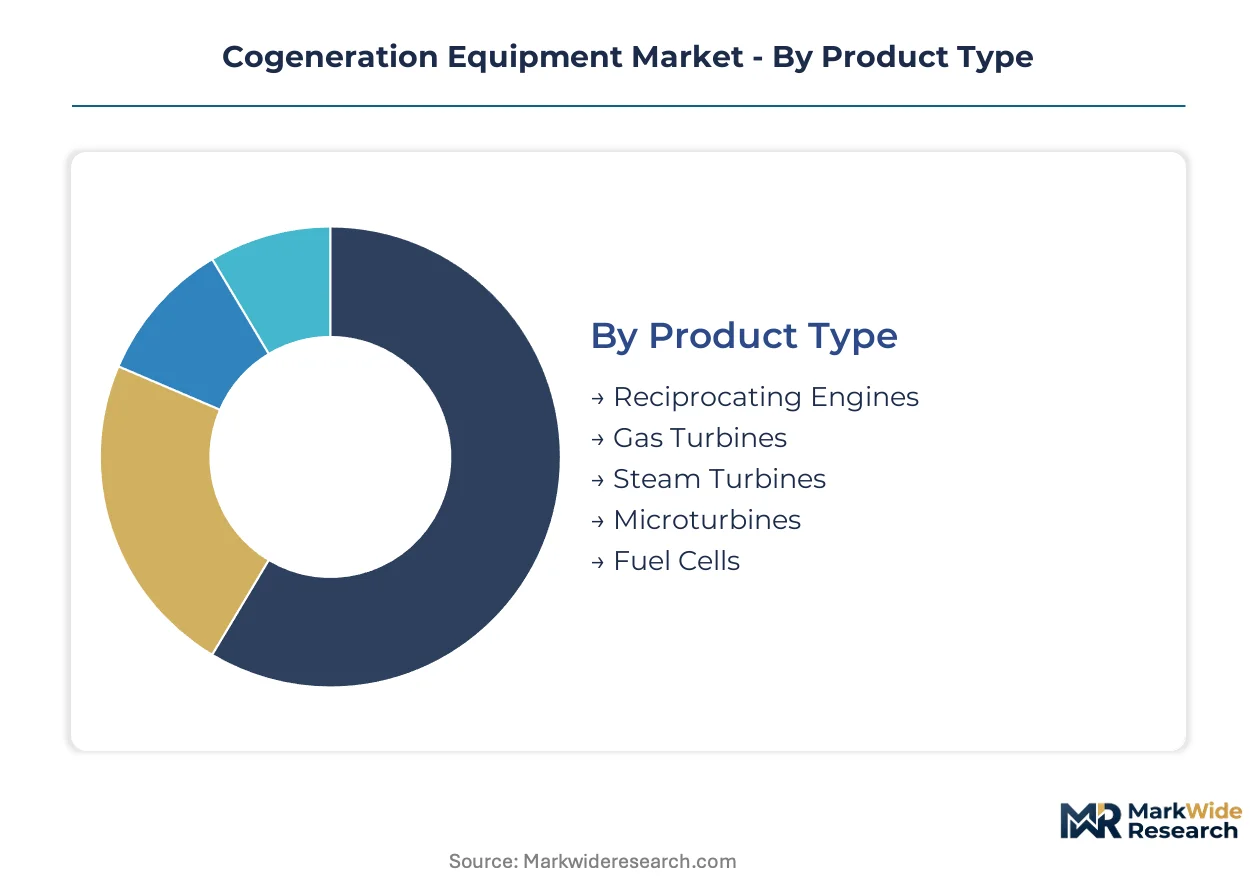
Equipment specification varies sharply across thermal load profiles and capital intensity thresholds. Procurement patterns diverge between utilities seeking hundred-megawatt scale and commercial operators prioritizing modularity.
Product Type:
Volume deployment clusters around mature reciprocating platforms, while premium positioning concentrates in fuel cell systems commanding subsidy-backed price premiums.
- Gas Turbines:Large-frame units scale into combined-cycle plants exceeding 100 megawatts for independent power producers. Demand concentrates in Germany and the United States where carbon pricing elevates efficiency premiums over simple-cycle alternatives.
- Fuel Cells:Solid oxide and proton exchange membrane configurations achieve zero-emission profiles through electrochemical conversion without combustion. Japan's METI hydrogen incentives are accelerating deployment at semiconductor fabrication campuses in Kumamoto and Hiroshima.
- Reciprocating Engines:Modular diesel and gas-fired units dominate sub-20 megawatt commercial applications with fast ramping capability.
- Steam Turbines:Industrial boiler-turbine combinations serve pulp and paper complexes with steady process steam requirements.
- Microturbines:Capstone-style units address distributed generation at remote oil and gas facilities.
Mature deployment sits with reciprocating engines. Newer deployment is concentrated in fuel cells.
Technology:
Application thermal requirements dictate selection between power-first and heat-first thermodynamic configurations.
- Combined Heat and Power:Simultaneous electricity and thermal output achieves 80-plus percent system efficiency through heat recovery integration. Manufacturing plants in the Netherlands and Denmark specify these systems to meet EU Green Deal emissions thresholds.
- Trigeneration:Cooling-integrated systems deploy absorption chillers to convert waste heat into air conditioning capacity. Data centers in Virginia and Frankfurt are specifying these configurations to manage hyperscale thermal loads.
- Combined Cycle:Gas turbine-steam turbine cascades maximize electrical efficiency for utility-scale independent power producers.
- Heat Recovery Steam Generator:Boiler-based steam production from turbine exhaust serves industrial process heat requirements.
- Organic Rankine Cycle:Low-temperature working fluids enable waste heat recovery from sub-300°C exhaust streams.
Established deployment centers on combined heat and power. Expanding deployment is concentrated in trigeneration.
Application:
End-use thermal profiles separate steady-load district heating from variable-load commercial operations.
- Data Centers:Hyperscale facilities require uninterrupted power and massive cooling capacity that trigeneration systems address through waste heat absorption chillers. Northern Virginia and Frankfurt clusters are driving specification of hundred-megawatt cogeneration plants with thermal storage integration.
- District Heating:Centralized thermal networks serve residential and commercial heating loads through piped hot water distribution. Copenhagen and Helsinki municipal operators are retrofitting with combined-cycle plants to displace coal-fired heat-only boilers.
- Manufacturing Plants:Pulp, paper, and chemical complexes with continuous process steam needs anchor industrial cogeneration deployment.
- Commercial Buildings:Office and retail complexes specify smaller reciprocating engine systems for on-site reliability.
- Hospitality Sector:Hotels and resorts deploy modular units to manage variable thermal loads across seasonal demand cycles.
Longstanding deployment sits with manufacturing plants. Accelerating deployment is concentrated in data centers.
End User:
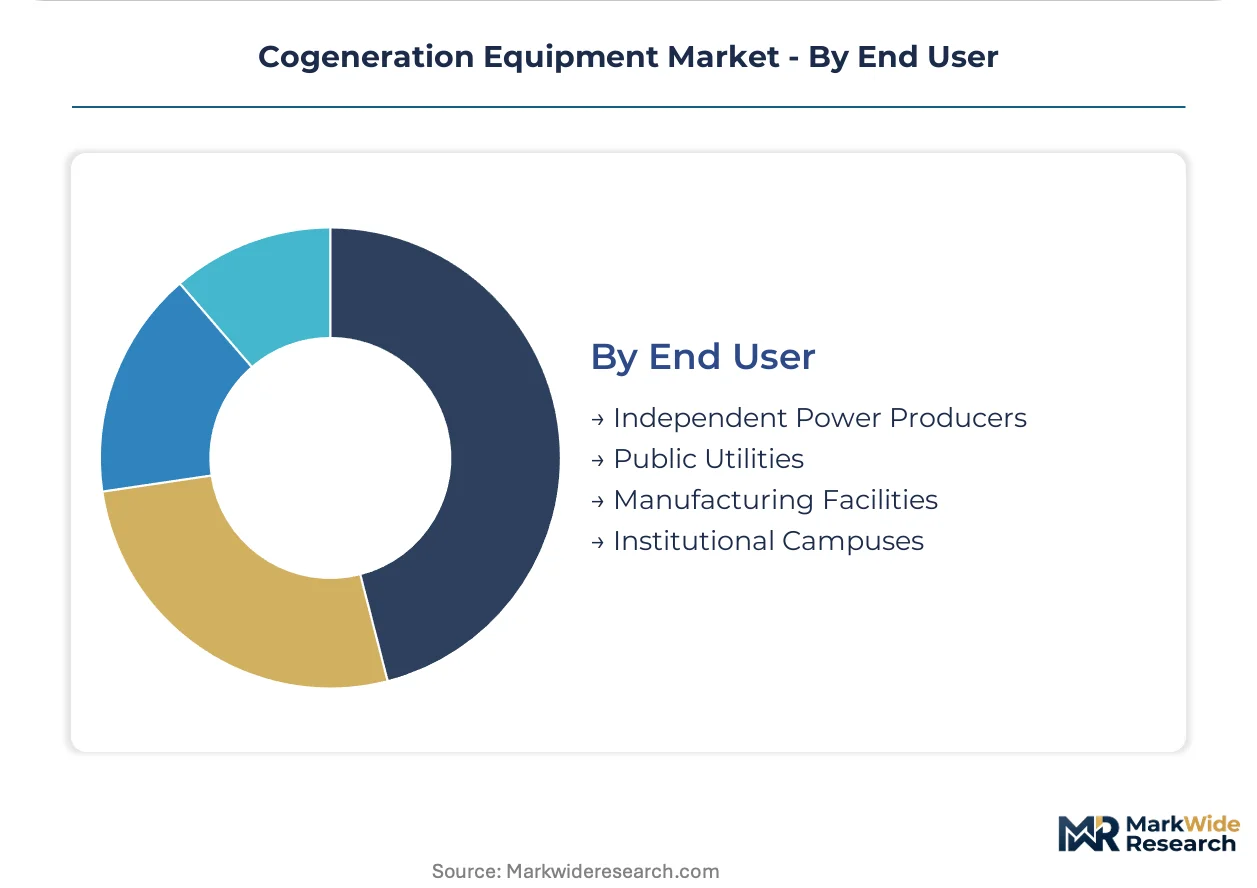
Ownership structures separate regulated utility procurement from risk-bearing independent power producers.
- Independent Power Producers:Merchant generators sell electricity into wholesale markets and thermal output to industrial offtakers under long-term contracts. Texas and California developers are navigating interconnection queue delays to commission combined-cycle plants ahead of grid reliability mandates.
- Public Utilities:Municipally owned systems prioritize rate stability and emissions compliance over merchant returns. German Stadtwerke are retrofitting district heating networks with gas-fired cogeneration to meet national carbon pricing obligations.
- Manufacturing Facilities:Captive power systems reduce exposure to grid price volatility for energy-intensive processors.
- Institutional Campuses:Universities and hospital complexes deploy on-site generation for resilience and sustainability credentials.
Traditional deployment sits with public utilities. Emerging deployment is concentrated in independent power producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian nickel ore processing underpins superalloy supply chains for gas turbine castings across multiple manufacturing geographies. Regional demand clusters around district heating networks in Northern Europe, data center corridors in North America, and industrial zones in East Asia where thermal-electric integration delivers compliance advantages.
Germany
Municipal utilities retrofit district heating infrastructure to displace coal-fired boilers under national carbon pricing obligations. The EU Green Deal emissions trading scheme tightens compliance thresholds for industrial power generators each year. Stadtwerke operators in Cologne and Hamburg commission combined-cycle plants to meet 2030 climate targets while maintaining rate stability.
United States
Hyperscale data centers in Northern Virginia specify trigeneration systems to manage uninterrupted power and cooling loads. EPA emissions standards under the Clean Air Act mandate nitrogen oxide limits that shape equipment procurement specifications. Developers in Texas navigate interconnection queue delays to commission independent power plants ahead of grid reliability mandates.
China
Provincial environmental bureaus accelerate gas-fired cogeneration permits while restricting new coal-linked installations. MEE dual carbon enforcement redirects industrial power investment toward combined-cycle configurations. Manufacturing clusters in Jiangsu and Guangdong displace standalone boilers with thermal-electric systems to meet provincial emissions budgets.
Japan
Semiconductor fabrication campuses in Kumamoto and Hiroshima deploy fuel cell systems to capture METI clean hydrogen subsidies. Top Runner efficiency standards force equipment recertification against progressively tighter benchmarks. Domestic turbine suppliers anchor aftermarket service relationships through regional technical centers.
India
Textile and food processing clusters in Gujarat and Tamil Nadu create captive power demand under PLI scheme incentives. The national power regulator prioritizes industrial self-generation permits to reduce grid load growth. Energy-intensive manufacturers in Maharashtra specify reciprocating engine systems for sub-20 megawatt reliability applications.
Cogeneration Equipment Market Key Industry Players
Capacity expansion dominates the current landscape as original equipment manufacturers harden supply chains against nickel superalloy volatility. The vendor base concentrates around three strategic tiers: diversified industrial conglomerates with in-house casting capacity, specialized turbine fabricators with regional service networks, and modular system integrators targeting distributed generation. Equipment suppliers pursue geographic anchoring through local installation partnerships. Technology licensing agreements accelerate product platform access for emerging market entrants.
Within the diversified industrial tier, General Electric, Siemens, and Mitsubishi Heavy Industries exemplify scale-driven competitive positioning. These conglomerates occupy positions defined by captive manufacturing capabilities and aftermarket service infrastructure. General Electric represents the casting-integrated archetype controlling turbine component lead times. Siemens anchors European installation density through regional technical hubs. Mitsubishi Heavy Industries sits within the efficiency-focused segment serving Asian utility procurement cycles.
| Leading Market Players |
|---|
| General Electric |
| Siemens |
| Mitsubishi Heavy Industries |
| ABB |
| Caterpillar |
| Rolls Royce |
| 2G Energy |
| Kawasaki Heavy Industries |
| Clarke Energy |
| Others |
Cost & Logistics Intelligence
Modular skid-based fabrication is compressing field installation costs while concentrating procurement leverage among original equipment manufacturers with captive component casting. This production-method transition simultaneously reshapes cost economics and supply concentration as buyers trade customization flexibility for capital deployment speed.
Pricing Analysis
Long-term service agreement bundling separates premium turbine suppliers from unbundled competitors in the cogeneration equipment market. Three-tier pricing structure across premium, standard, and economy levels reflects warranty duration, spare parts availability, and remote monitoring inclusion. Cost compression in the standard tier is intensifying because independent service providers are winning aftermarket contracts with aggressive performance guarantees. Manufacturing facilities with captive power requirements demonstrate highest price sensitivity, while data center operators prioritize uptime assurance over capital expenditure minimization.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for turbine component logistics. Nickel superalloy casting feedstock draws from Russian and Indonesian ore processing concentration. High-temperature coatings and precision-machined compressor blades represent additional critical dependencies. Single-source vulnerability around nickel superalloy supply creates exposure to export restriction volatility. Distribution runs through original equipment manufacturer service hubs that control spare parts availability and technical support access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cogeneration equipment market functions as a cost-of-compliance arena where EU F-Gas Regulation refrigerant phase-downs and EPA nitrogen oxide limits erect barrier-to-entry moats for certified equipment suppliers.
For Market Incumbents: Acquire specialized commissioning engineering capabilities to address workforce scarcity in turbine alignment and controls integration. Consolidate aftermarket service relationships through multi-year performance contracts that lock out independent providers. Fuel cell substitution threats from Japan's METI-subsidized deployments demand efficiency investment in combined-cycle platforms. For New Entrants and Emerging Players: India's PLI scheme for textiles and food processing opens a window for modular reciprocating engine systems in Gujarat and Tamil Nadu captive power applications. Target agricultural residue-to-energy integration in Brazil and Thailand where carbon-negative credentials command procurement preference. Energy service company partnerships in France and Italy offer operational risk assumption channels for municipal district heating retrofits. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified industrial conglomerates seeking regional installation density. The five-to-ten year viability window favors targets with established service hub networks and METI/EPA certification portfolios. Domestic turbine supplier capture of Chinese provincial fast-track permits signals inflection in geographic competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Superalloy Casting | General Electric's captive foundry capacity insulates turbine component lead times from Indonesian ore export volatility. |
| Regional Service Hub Expansion | Siemens anchors European installation density through Cologne and Hamburg technical centers sustaining aftermarket revenue. |
| Fuel Cell Platform Diversification | Mitsubishi Heavy Industries addresses METI hydrogen incentives through solid oxide systems for Kumamoto semiconductor campuses. |
| Modular Skid Standardization | Containerized organic Rankine cycle units reduce Danish food processor capital commitments through equipment-as-a-service contracting. |
| Performance Contracting Channel Development | French and Italian energy service companies assume operational risk for municipal district heating retrofits in Copenhagen and Helsinki. |
Research Approach
Multi-period observation of equipment efficiency certifications, interconnection queue backlogs, and carbon pricing enforcement anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads. Secondary validation drew from EIA power plant databases, IEA efficiency benchmarking reports, FERC interconnection filings, and EU ETS carbon market registries. Bottom-up project pipeline tracking triangulated against top-down manufacturing capacity assessments.
Segment-weighting across fuel source, generation capacity tier, and regional regulatory framework shaped the analytical framework over the projection horizon. CAGRs were derived from installation volume trajectories and capital expenditure patterns across the modeling period. Technology-specific inputs included fuel cell subsidy phase schedules, gas turbine efficiency improvement curves, and biomass feedstock availability projections.
The model assumes a particular technology adoption path; alternative pathways for solid oxide fuel cells would alter the outlook if hydrogen infrastructure deployment accelerates beyond base assumptions. Forecasts reflect documented assumptions regarding carbon border adjustment implementation scope and nickel supply chain normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Global Power System Simulator Market
Power Equipment
US Power EPC Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Steam Turbine Control System Market
Power Equipment
Power Analyzers Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Digital Power Conversion Market
Power Equipment
SCR Power Controller Market
Power Equipment
Air Preheater Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Process Plants Gas Turbine Market
Power Equipment
Qatar Power EPC Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Saudi Arabia Power EPC Market