
 Global Power Rental Systems Market | 2026-2036
Global Power Rental Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Rental Systems Market Intelligence
Modular containerized generator packaging is decoupling power output from permanent infrastructure commitment, letting buyers scale megawatt blocks without long-term asset ownership. Aggreko leverages its global depot network to pre-position hybrid units near active construction corridors. Caterpillar sustains manufacturing scale across its reciprocating engine lines, anchoring its rental channel with standardized power modules. Cummins Inc. competes through integrated digital telemetry that monitors fleet utilization across dispersed job sites.
Power rental systems are temporary or mobile electricity generation assets, typically diesel or gas reciprocating engines rated from 20 kW to 2,000 kW, deployed where grid connection is unavailable, unreliable, or insufficient for peak load coverage. These systems serve industrial and commercial users needing immediate, contract-based energy without capital expenditure on fixed plant. Diesel generators still dominate the installed rental base due to fuel logistics maturity and load-following flexibility, though hybrid systems are capturing the fastest growth as fuel cost volatility and emission constraints intensify. Battery storage segments are emerging as margin-rich attachments that reduce runtime hours on combustion units and lower total rental operating cost for event organizers and film studios.
EPA Tier 4 Final standards in the United States and EU Stage V emission frameworks are restricting non-road diesel engine eligibility in rental fleets, compelling capital refresh toward compliant or alternative-fuel machines. ISO 8528 performance classification and IEC electrical safety standards govern product design and interconnection protocols, shaping manufacturer R&D allocation and regional market access conditions. Stakeholders must weigh fleet composition decisions against evolving carbon border adjustments and local air quality enforcement trajectories that will redefine competitive cost structures in temporary power supply.
Market Dynamics
EPA Tier 4 Final and EU Stage V emission frameworks are forcing rental fleet operators toward compliant engine architectures, compressing the operational life of legacy diesel assets and accelerating capital redeployment into hybrid and gas-powered alternatives.
Growth Catalysts
- Grid Instability in Emerging Markets:Mining operations in Chile and construction corridors in India rely on mobile rental fleets to bridge power gaps where transmission infrastructure remains underdeveloped.
- EPA Tier 4 Final Compliance Deadlines:Rental providers in the United States are refreshing non-compliant diesel engines ahead of enforcement windows, creating replacement demand for low-emission reciprocating units.
- Hybrid System Integration:Battery storage attachments are reducing runtime hours on combustion engines at film studios and event venues, lowering total operating cost per rental contract.
Market Restraints
- Diesel Fuel Price Volatility:Fluctuations in global crude markets compress rental margin structures, particularly for operators with fixed-rate contracts and unhedged fuel exposure.
- Engine Supply Concentration:Reciprocating engine manufacturing clusters in Germany and Japan create vulnerability for rental fleet operators dependent on just-in-time delivery of Tier 4 Final and Stage V compliant power units.
- Permitting Friction:Local air quality districts in California and New York impose site-specific emission limits that exceed federal EPA standards, delaying deployment timelines for diesel-intensive projects.
Strategic Opportunities
- Modular Containerized Packaging:Standardized megawatt blocks enable mining contractors in Australia to scale temporary power without permanent infrastructure commitment or capital lock-up.
- EU Green Deal Funding Windows:National recovery plans in France and Italy are subsidizing low-emission temporary power for grid stabilization projects, creating tender opportunities for compliant rental providers.
- Digital Telemetry Convergence:Integration of IoT monitoring with predictive maintenance algorithms allows remote fleet management across dispersed job sites in the United States and Canada.
Industry Challenges
- Certification Timeline Compression:IEC 8528 and ISO electrical safety recertification cycles for hybrid systems lag product development, delaying commercial deployment of next-generation rental assets.
- Technician Skill Scarcity:Maintenance of integrated battery-combustion hybrid units requires cross-training in high-voltage electrical systems and reciprocating engine diagnostics, constraining fleet expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Rental Systems Market |
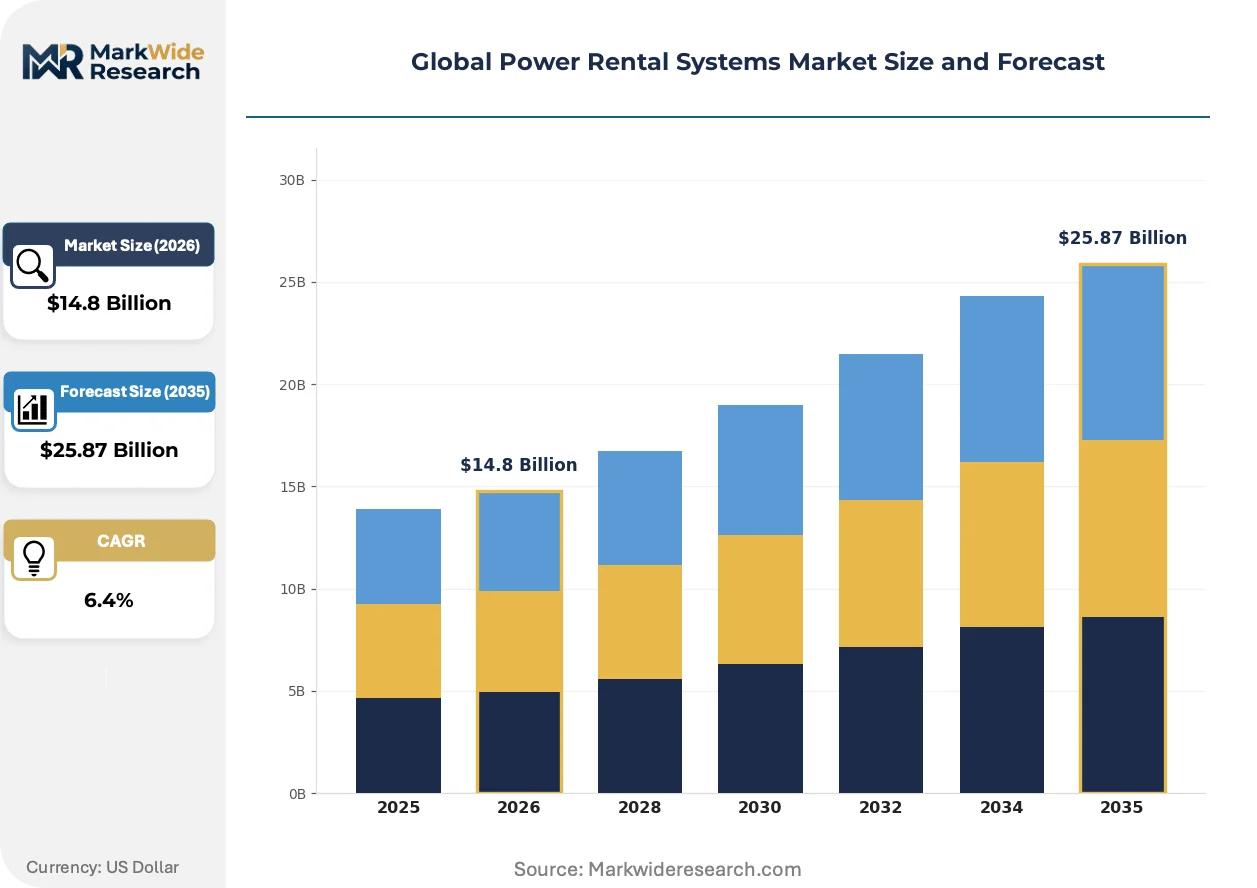
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Generators, Solar Power Units, Battery Storage, Hybrid Systems Application: Construction Sites, Events & Entertainment, Emergency Backup, Mining Operations, Film Production Customer Type: Contractors, Event Organizers, Utility Providers, Mining Companies, Film Studios Deployment: Temporary Installations, Mobile Units, Fixed Site Units, Offshore Platforms, Remote Locations |
| Companies Covered | Aggreko, United Rentals, Inc., Caterpillar, Cummins Inc., Ashtead Group plc, Atlas Copco AB, Herc Rentals Inc., APR Energy, Generac Power Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Rental Systems Market Strategic Shifts & Innovations
Containerized power packaging and digital fleet telemetry are compressing the traditional trade-off between deployment speed and operational visibility, enabling rental operators to match output blocks precisely to load duration curves without permanent asset ownership.
Hybrid diesel-battery generator sets are consolidating temporary power supply around fuel-flexible architectures that optimize runtime hours based on load profile. Mining contractors in Western Australia deploy these systems to reduce diesel consumption during low-load overnight periods. The technology is consolidating rental fleet composition decisions around total cost of ownership metrics rather than capital cost per kilowatt.
EU Stage V non-road emission standards are restricting engine eligibility in European rental fleets, compelling capital allocation toward gas-powered reciprocating units and battery-dominant hybrid configurations. Construction rental providers in Germany and the Netherlands face compressed equipment replacement cycles as 2019-vintage diesel assets age out of compliance. The regulatory pressure is accelerating manufacturer R&D allocation toward alternative-fuel engine platforms.
Power purchase agreements with embedded rental clauses are displacing traditional spot-market equipment leasing in the United States. Data center developers in Texas and Virginia now contract multi-year temporary power through integrated energy service agreements rather than transactional rental contracts. The procurement model shift is concentrating contract value with providers capable of guaranteed availability and fuel price hedging.
Global Power Rental Systems Market Segmentation
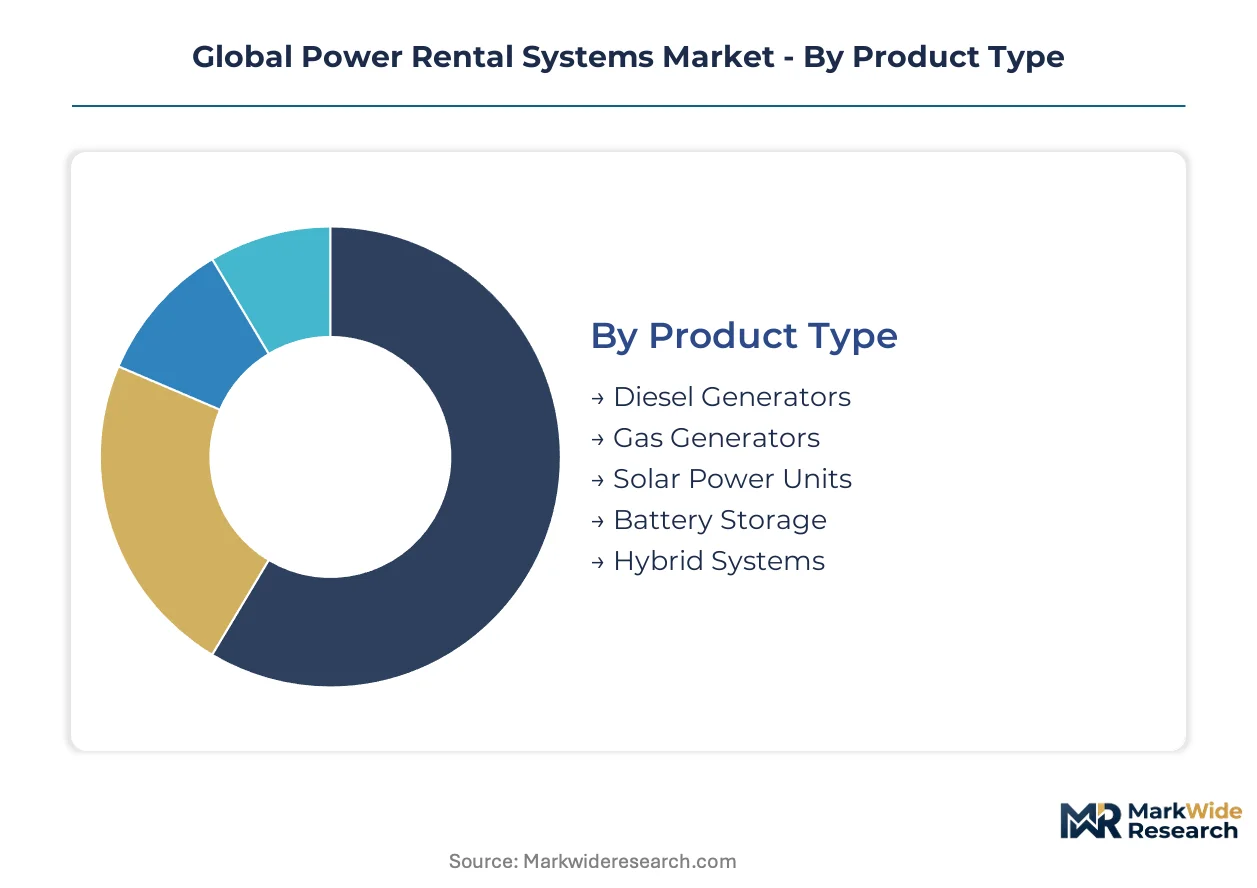
Rental fleet composition decisions hinge on matching power output characteristics to load duration curves across volatile project timelines. Segmentation reveals where capital redeploys fastest as emission thresholds tighten and fuel cost volatility reshapes contract economics.
Product Type:
Supply concentration in reciprocating engine manufacturing clusters shapes fleet refresh trajectories and regional availability of compliant units.
- Diesel Generators:Reciprocating engines rated 20 kW to 2,000 kW dominate installed rental bases through fuel logistics maturity and load-following flexibility. Mining contractors in Australia and Chile rely on these units for continuous operations where grid infrastructure remains undeveloped.
- Hybrid Systems:Integrated battery-combustion architectures reduce runtime hours on diesel engines during low-load periods. Film studios in Los Angeles and event venues in London deploy these configurations to lower total operating cost per rental contract while meeting local air quality enforcement.
- Gas Generators:Spark-ignited reciprocating units running on natural gas or LPG offer lower particulate emissions than diesel counterparts. Utilities in Texas and Oklahoma deploy these for grid stabilization contracts.
- Battery Storage:Lithium-ion containerized systems serve as margin-rich attachments that displace combustion runtime. Data center developers in Virginia integrate these for peak shaving during construction phases.
- Solar Power Units:Photovoltaic arrays with integrated inverters provide zero-emission power for remote telecommunications infrastructure. Mining exploration camps in Western Australia test these for daylight-hour operations.
Today's leader: Diesel Generators. Tomorrow's challenger: Hybrid Systems.
Application:
Cost tier differentiation separates spot-market rentals from multi-year integrated service agreements with embedded availability guarantees.
- Construction Sites:Temporary power for building corridors, road projects, and infrastructure development requires rapid deployment and scalable megawatt blocks. Contractors in India procure these through rental fleets to avoid capital lock-up in permanent generation assets.
- Mining Operations:Continuous power for extraction, processing, and camp facilities demands high-reliability units in harsh environments. Copper and lithium producers in Chile expand mobile rental fleets to bridge power gaps while avoiding transmission infrastructure investment.
- Events & Entertainment:Short-duration power for concerts, festivals, and sporting venues prioritizes rapid setup and low noise signatures. Organizers in Germany face compressed deployment timelines due to EU Stage V emission constraints on diesel-intensive projects.
- Emergency Backup:Grid-failure response for hospitals, data centers, and critical infrastructure requires guaranteed availability within hours. Utility providers in Texas contract these through power purchase agreements with embedded rental clauses.
- Film Production:Silent, emission-compliant power for on-location shooting drives demand for battery-dominant hybrid configurations. Studios in California navigate local air quality district limits that exceed federal EPA standards.
Construction Sites anchor current contract volume. Mining Operations are climbing the fastest as commodity producers defer permanent infrastructure commitments.
Customer Type:
Volume concentration among capital-intensive extractive industries creates procurement leverage that reshapes rental provider service models.
- Mining Companies:Large-scale consumers of continuous power for extraction and processing operations in remote locations. Firms in Australia and Chile favor mobile rental fleets to preserve balance sheet flexibility.
- Contractors:Diverse construction and engineering firms requiring temporary power across dispersed project portfolios. Infrastructure builders in India drive procurement of containerized generator packages.
- Event Organizers:Short-term consumers prioritizing rapid deployment and acoustic compliance over fuel efficiency. Festival operators in the Netherlands face equipment replacement cycles as pre-Stage V diesel assets age out.
- Utility Providers:Grid operators contracting temporary power for stabilization and emergency response. Regional utilities in Texas and Virginia source through multi-year energy service agreements.
- Film Studios:Production companies requiring silent, emission-compliant power for location shooting. Major studios in California integrate battery storage attachments to reduce combustion runtime.
Mining Companies dominate committed contract value. Utility Providers are gaining share fastest as grid instability intensifies.
Deployment:
Maturity gradients separate established temporary installation protocols from emerging remote location configurations requiring specialized logistics.
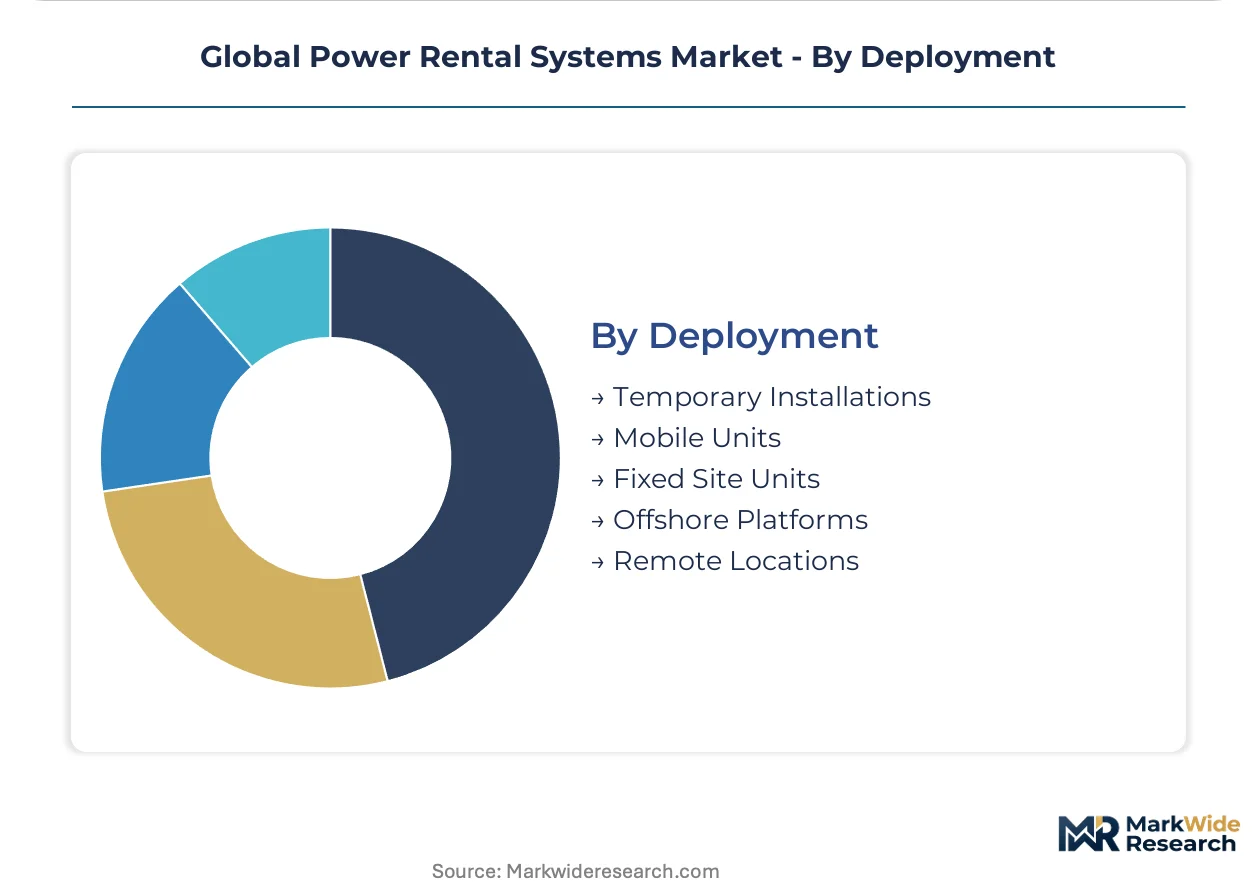
- Mobile Units:Trailer-mounted or skid-mounted generators designed for rapid relocation between job sites. Rental providers in the United States pre-position these near active construction corridors.
- Temporary Installations:Short-duration fixed deployments for construction phases or seasonal demand peaks. Contractors in India scale these megawatt blocks without permanent infrastructure commitment.
- Remote Locations:Specialized logistics for power delivery beyond established road networks or grid interconnection points. Mining exploration in Western Australia tests solar-battery configurations for daylight operations.
- Fixed Site Units:Semi-permanent installations for extended project durations with limited relocation requirements. Data center developers in Virginia deploy these through integrated energy service agreements.
- Offshore Platforms:Marine-rated generators for oil and gas production or construction support vessels. North Sea operators require specialized certification for salt-air corrosion resistance.
Mobile Units command the largest fleet allocation. Remote Locations represent the steepest expansion trajectory as extraction moves to frontier geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile power rental operations first achieved industrial scale in the United States during the 1980s oilfield services expansion, then diffused to mining frontiers in Australia and Chile. Today fleet deployment patterns track grid reliability gaps and emission enforcement intensity across five distinct national markets.
United States
Data center construction corridors in Texas and Virginia consume multi-megawatt rental blocks through power purchase agreements with embedded availability clauses. EPA Tier 4 Final enforcement windows compress replacement cycles for legacy diesel assets in California air quality districts. Rental providers pre-position hybrid units near active infrastructure build-outs in the Permian Basin and Appalachian shale plays.
Germany
Construction rental providers face accelerated equipment replacement as pre-Stage V diesel assets age out of compliance in Bavaria and North Rhine-Westphalia. EU Green Deal funding windows subsidize low-emission temporary power for grid stabilization tenders issued by transmission system operators. Industrial clusters around Stuttgart and Munich test gas-powered reciprocating units for manufacturing backup applications.
Australia
Copper and lithium producers in Western Australia expand mobile rental fleets to preserve balance sheet flexibility against volatile commodity prices. The country's national environmental regulator enforces site-specific emission limits that exceed federal baselines at Pilbara mining camps. Contractors in Queensland deploy containerized generator packages for coal seam gas field development without permanent infrastructure commitment.
India
Infrastructure builders in Maharashtra and Gujarat procure temporary power through rental channels to avoid capital lock-up in fixed generation assets. The Central Electricity Authority mandates grid code compliance for interconnected rental units serving industrial estates near Delhi-NCR. Mining contractors in Odisha and Jharkhand bridge transmission gaps with trailer-mounted diesel fleets during monsoon-disrupted grid operations.
Chile
Copper extraction operations in the Atacama Desert rely on continuous rental power where transmission infrastructure remains undeveloped across northern mining districts. The national environmental regulator enforces progressively tighter particulate limits on non-road engines at Escondida and Collahuasi mine sites. Lithium brine processors in the Salar de Atacama test hybrid diesel-battery configurations to reduce fuel logistics costs in remote locations.
Global Power Rental Systems Market Key Industry Players
Premium-margin players sit above commodity-margin players across service integration depth, with availability-guarantee contracts commanding pricing multiples over spot-market equipment leasing. The vendor base concentrates around three strategic archetypes: global depot-network operators with pre-positioned hybrid fleets, manufacturing-anchored rental channels leveraging standardized power modules, and integrated telemetry providers offering predictive maintenance across dispersed job sites. Dominant competitive moves include fleet refresh toward emission-compliant architectures and geographic pre-positioning near active construction corridors.
Within the global depot-network tier, Aggreko exemplifies pre-positioning strategy through proximity to mining and infrastructure corridors. Among manufacturing-anchored channels, Caterpillar and Cummins occupy positions leveraging reciprocating engine scale and integrated digital telemetry respectively. These three companies represent distinct competitive vectors: fleet mobility, manufacturing depth, and data-enabled service integration.
| Leading Market Players |
|---|
| Aggreko |
| United Rentals, Inc. |
| Caterpillar |
| Cummins Inc. |
| Ashtead Group plc |
| Atlas Copco AB |
| Herc Rentals Inc. |
| APR Energy |
| Generac Power Systems, Inc. |
| Others |
Cost & Logistics Intelligence
Steel and copper commodity movements cascade through generator enclosure fabrication costs into rental rate structures, with Tier 4 Final engine premiums compressing margin at the standard tier while hybrid configurations command availability guarantees from data center developers in Texas and Virginia.
Pricing Analysis
Contract-based long-term offtake with embedded fuel hedging dominates procurement for utility-scale deployments, while spot-market equipment leasing persists for construction corridors. Price differentiation rests on EPA certification tier and telemetry integration depth. Cost compression in standard diesel rentals is intensifying because unhedged fuel exposure erodes fixed-rate contract profitability. Mining companies in Australia exhibit lowest price sensitivity due to balance sheet flexibility priorities, whereas event organizers in Germany face acute budget constraints under compressed Stage V equipment replacement cycles.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese reciprocating engine manufacturing clusters for Tier 4 Final and Stage V compliant power units. Component sourcing draws from China for lithium-ion battery enclosures, India for control system electronics, and the United States for emissions after-treatment hardware. Tariff exposure on steel and aluminum generator enclosures creates margin volatility for fleet operators. Distribution runs through regional depot networks pre-positioned near active mining and infrastructure corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Power Rental Systems Market reads as a late-cycle quality story where EPA Tier 4 Final and EU Stage V compliance thresholds concentrate contract value with providers capable of guaranteed availability and integrated telemetry.
For Market Incumbents:Extend hybrid fleet pre-positioning near data center construction corridors in Texas and Virginia to capture multi-year power purchase agreement demand. Deepen backward integration into battery storage attachments to reduce third-party margin extraction and differentiate against spot-market competitors facing diesel fuel price volatility.
For New Entrants and Emerging Players:Capture remote location deployments in Western Australian mining frontiers where specialized logistics requirements deter established depot-network operators. Target film production and event venue segments in California and Germany with battery-dominant hybrid configurations that navigate local air quality limits exceeding federal baselines.
For Investors and Strategic Acquirers:Consolidation pressure builds where emission compliance investments fragment capital efficiency among mid-scale regional operators. Long-term viability favors vertically integrated providers with captive engine supply relationships and telemetry-enabled predictive maintenance capabilities. Watch EPA enforcement window timing and EU Green Deal funding disbursement velocity as inflection indicators for replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Fleet Pre-positioning | Proximity to active construction corridors in Texas and Virginia secures multi-year contract flow. |
| Backward Integration into Storage | In-house battery attachment production captures margin-rich segments in film and event applications. |
| Telemetry Platform Deployment | IoT-enabled predictive maintenance differentiates service offerings for mining contractors in Australia. |
| Emissions Certification Investment | EPA Tier 4 Final and EU Stage V compliance preserves fleet eligibility in restricted air quality districts. |
| Power Purchase Agreement Structuring | Embedded fuel hedging and availability guarantees lock in contract value with data center developers. |
Research Approach
Direct dialogue with rental fleet operations directors, mining procurement managers, construction project engineers, and utility planning officers grounded qualitative demand assessment. Secondary validation drew from EPA enforcement announcements, EU Green Deal implementation documents, FERC interconnection filings, and customs trade data for generator set imports. Bottom-up equipment deployment estimates triangulated against top-down addressable market sizing across the analysis window.
Installed base projections and revenue forecasts emerged from segment-level modeling across fuel source, power output tier, application vertical, and regional regulatory framework. CAGRs were derived from equipment replacement cycle analysis and infrastructure investment pipeline tracking. Key inputs included diesel-gas price spread trajectories, battery cost decline curves, and emission standard phase-in schedules.
Commodity price volatility, regulatory enforcement timing shifts, and grid reliability improvement trajectories are the dominant revision risks to deployment assumptions. Forecasts reflect documented assumptions about fleet refresh velocity and hybrid technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Russian Federation Power EPC Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Europe Power Rental Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Japan Power EPC Market
Power Equipment
France Power EPC Market
Power Equipment
AC Stabilized Power Supply Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
AC Power Sources Market
Power Equipment
Magnetic Bearing Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
Power Equipment Testing Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Industrial Gas Turbine Ignition System Market